
 Green Mining Market | 2026-2036
Green Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Green Mining Market Intelligence
The rise of ESG-linked project financing is reshaping competitive positioning by favoring miners with verifiable sustainability metrics. Large-scale operators like Rio Tinto leverage their extensive capital to invest in solar-powered equipment and water recycling infrastructure. Anglo American differentiates through its commitment to developing regenerative mining projects. Meanwhile, BHP sustains its market leadership by integrating advanced emission control solutions across its global operations.
Green mining encompasses a set of technologies and processes designed to minimize the environmental footprint of mineral and metal extraction. It involves methods such as bioleaching, which uses microorganisms to extract metals from ore, reducing the need for harsh chemicals. Within the technology segment, solar-powered equipment and zero-waste processing are gaining significant traction. In terms of application, tailings management and groundwater preservation represent mature, essential services, while rare earth metals extraction is the fastest-growing area.
Regulatory pressure from bodies like the US Environmental Protection Agency (EPA) and compliance with standards such as the EU's REACH directive are compelling operational changes. In parallel, China's Ministry of Ecology and Environment (MEE) enforces stringent rules on water usage and emissions, directly influencing technology adoption. For mining corporations, the critical decision lies in balancing upfront capital investment in green technologies against the long-term benefits of regulatory compliance and improved social license to operate.
Market Dynamics
The convergence of ESG-linked investment criteria and stringent government regulations on resource extraction defines the central dynamic of the green mining market. This dual pressure compels operators to adopt verifiable sustainability metrics not merely for compliance but as a core competitive differentiator.
Growth Catalysts
- Electric Vehicle Demand:The accelerating production of electric vehicle batteries creates sustained demand for sustainably sourced rare earth metals and lithium, directly spurring investment in low-impact extraction technologies.
- Regulatory Frameworks:Mandates like the EU Green Deal require end-users to verify the environmental credentials of their supply chains, creating a premium for minerals extracted through certified green processes.
- Process Innovation:The maturation of technologies such as bioleaching and advanced water recycling offers viable, lower-impact alternatives to traditional methods, improving the economic case for environmental stewardship.
Market Restraints
- High Capital Intensity:The substantial upfront investment required for green infrastructure, such as solar-powered fleets and zero-waste processing plants, presents a significant barrier for junior miners and smaller operators.
- Technological Scalability:While promising, emerging technologies like microbial leaching face challenges in scaling to the production volumes of conventional methods, sometimes limiting their application to specific ore bodies or minerals.
- Geopolitical Supply Risks:The concentration of processing for critical minerals in a few nations, notably China, creates supply chain vulnerabilities and complicates efforts by other countries to build fully-green, mine-to-market ecosystems.
Strategic Opportunities
- Regenerative Projects:Developing mining projects that include commitments to land rehabilitation and biodiversity enhancement from inception can unlock preferential financing and secure a stronger social license to operate.
- Critical Mineral Circularity:Establishing advanced facilities for recycling and recovering rare earth metals from e-waste and end-of-life batteries presents a major opportunity to create a secure, secondary supply source.
- Domestic Processing Incentives:Policies like the US Inflation Reduction Act (IRA) create powerful financial incentives for developing domestic mining and processing capabilities for critical minerals using sustainable practices.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of professionals with dual expertise in mining engineering and environmental sciences, such as hydrologists and biochemists, hinders the implementation of advanced green mining systems.
- Legacy System Integration:Retrofitting decades-old mining sites with modern green technologies is technically complex and often economically prohibitive, slowing the transition for established, large-scale operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Mining Market |
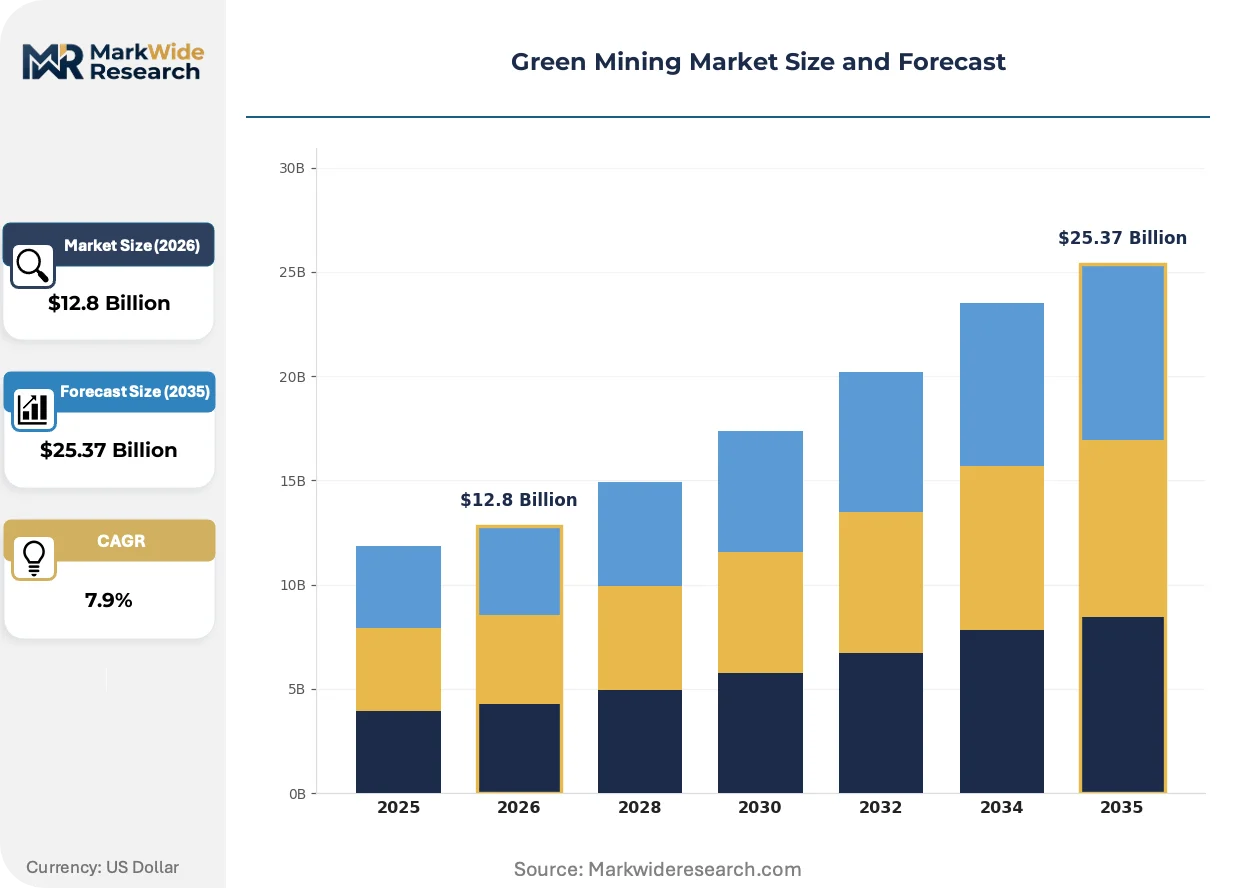
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $25.37 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
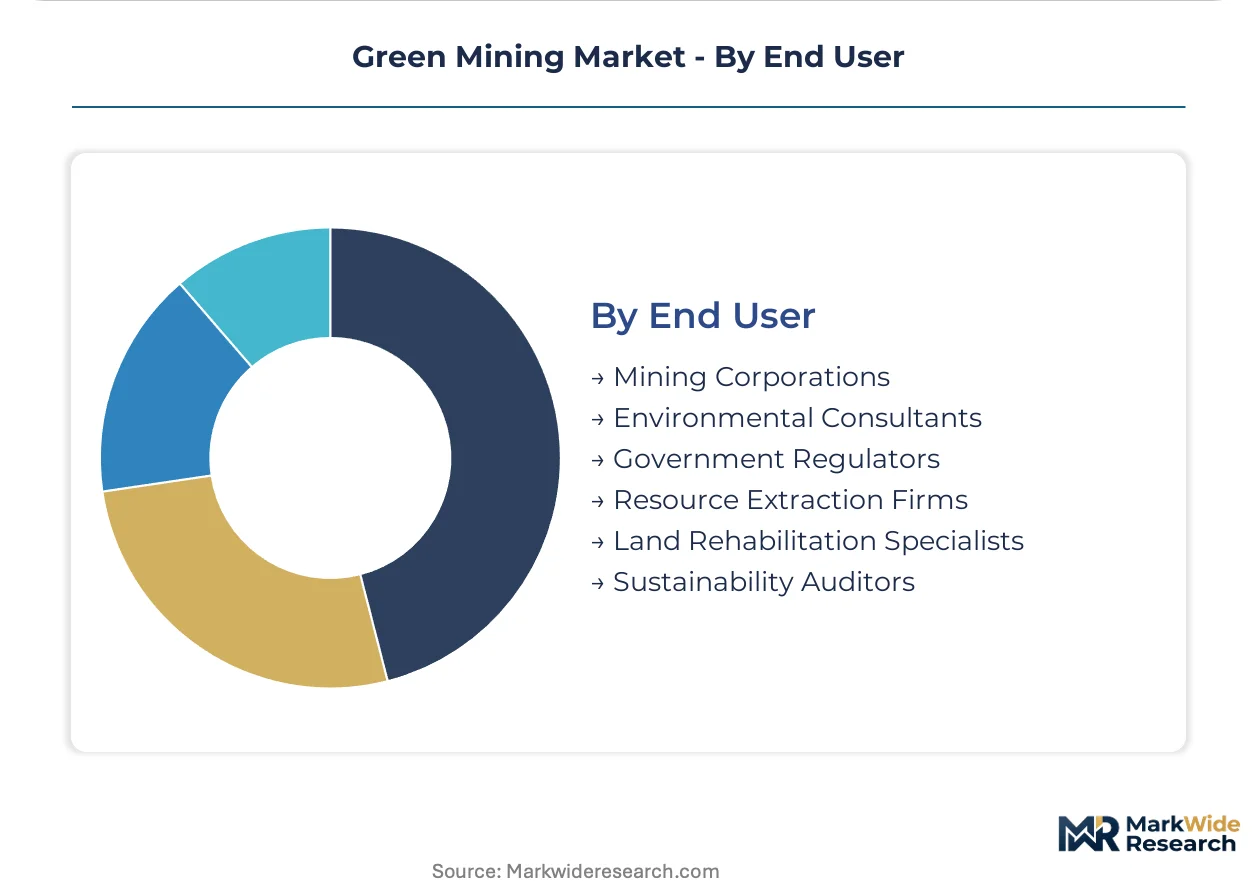
| Segmentation | Technology: Bioleaching, Phytomining, Regenerative Mining, Electrochemical Extraction, Solar-Powered Equipment, Zero-Waste Processing Application: Rare Earth Metals Extraction, Coal Rehabilitation, Metal Recovery, Ore Remediation, Groundwater Preservation, Tailings Management Product Type: Renewable Energy Systems, Eco-friendly Drilling Tools, Emission Control Solutions, Water Recycling Units, Soil Stabilization Agents, Biodegradable Lubricants End User: Mining Corporations, Environmental Consultants, Government Regulators, Resource Extraction Firms, Land Rehabilitation Specialists, Sustainability Auditors |
| Companies Covered | BHP, Rio Tinto, Anglo American, Vale S.A., Glencore, Freeport-McMoRan, Antofagasta, Codelco, Barrick Gold, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Mining Market Strategic Shifts & Innovations
A fundamental shift from conceptual environmental goals to tangible, technology-enabled execution is underway. The market's evolution is now defined by the practical application of digital tools and new regulatory disclosures to meet investor and customer demands for transparency.
Technology and Product Evolution
Digital twin technology, which creates a virtual replica of a physical mine, is gaining traction. Large-scale operators are adopting these models to simulate the environmental impact of operational changes before implementation, optimizing water and energy use. This technology is hybridizing physical extraction with data-driven simulation, enabling miners to de-risk green investments and continuously refine their environmental performance in a virtual environment.
Regulatory and Policy Shifts
The European Union's Corporate Sustainability Reporting Directive (CSRD) is forcing a major change in operational transparency. The directive requires companies operating in or selling to the EU to provide detailed, audited reports on their environmental impact, including supply chain activities. The rare earth metals segment is most affected, as miners in Australia and Canada must now implement robust tracking systems to prove compliance and maintain access to the European electric vehicle market.
Demand-Side and Behavioral Shifts
Downstream manufacturers in the automotive and electronics sectors are increasingly requiring full traceability for raw materials as part of their own ESG commitments. This is disrupting traditional commodity purchasing based solely on price, creating a clear preference for miners who can provide verifiable provenance data. This trend is most advanced in Europe and North America, where brand reputation is closely tied to supply chain ethics.
Green Mining Market Segmentation
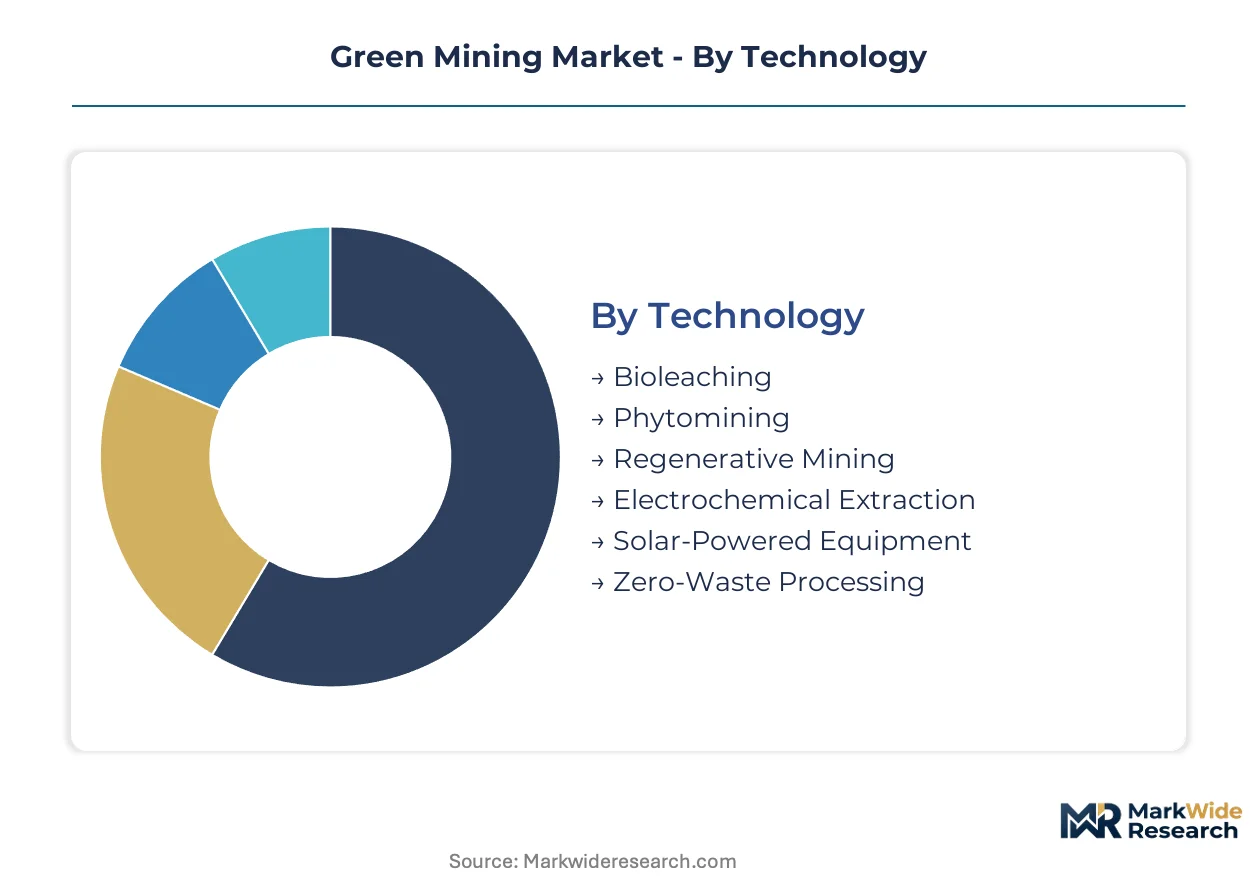
The green mining market exhibits diverse operational and technological requirements, necessitating a granular understanding of its constituent parts. This segmentation reveals how different technologies, applications, product types, and end-users contribute to the market's overall structure. Strategic investments align with these distinct segments to drive sustainable resource extraction.
Technology:
After-sales-service intensity varies across green mining technologies, influencing operational expenditure and long-term viability. Complex digital and biological systems require specialized support.
- Bioleaching:Bioleaching uses microorganisms to extract metals from ore, reducing chemical reagents. Demand concentrates in copper and gold extraction in South America.
- Solar-Powered Equipment:Solar-powered equipment integrates photovoltaic systems to power mining, cutting fossil fuels and carbon emissions. Rio Tinto invests heavily in solar fleets in Chile.
- Phytomining:Phytomining uses plants to absorb metals from contaminated soils, offering bioremediation for Australian mine sites.
- Regenerative Mining:Regenerative mining integrates ecological restoration into mining, aiming for net positive outcomes. Anglo American champions this.
- Electrochemical Extraction:Electrochemical extraction uses electrical currents to recover metals from solutions. Lithium extraction in North America explores this.
- Zero-Waste Processing:Zero-waste processing recovers all valuable materials from ore and tailings, minimizing waste. This gains traction in Canadian critical mineral facilities.
By volume, solar-powered equipment leads due to broad applicability. By growth pace, zero-waste processing is ahead, reflecting increasing regulatory pressure.
Application:
Green mining application segments define specific environmental challenges and opportunities addressed by sustainable practices.
- Rare Earth Metals Extraction:Rare Earth Metals Extraction focuses on sustainable methods for critical elements for EV batteries. Demand concentrates in Australia, driven by accelerating global EV production.
- Tailings Management:Tailings management focuses on safe disposal, storage, and reprocessing of mining waste, preventing ecological disasters. Chile's copper mines invest in dry stacking technologies.
- Coal Rehabilitation:Coal rehabilitation restores land and ecosystems after coal mining, mitigating long-term environmental damage in US Appalachia.
- Metal Recovery:Metal recovery extracts valuable metals from industrial waste and e-waste, reducing reliance on virgin material. European initiatives drive investment.
- Ore Remediation:Ore remediation addresses environmental contamination from mining waste, such as acid mine drainage. This is crucial for historical mine sites in Canada.
- Groundwater Preservation:Groundwater preservation protects underground water sources from contamination by mining activities. This is essential for operations in water-stressed South Africa.
Rare Earth Metals
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global green mining market's regional dynamics often reflect a delicate balance between a nation's mineral wealth and its technological capacity for sustainable extraction. Countries seeking critical minerals increasingly prioritize secure supply chains over purely cost-driven imports. This shift drives investment in domestic green mining capabilities.
Australia
Demand for sustainably sourced rare earth metals and lithium drives green mining investments across Australia. The Australian government supports critical mineral projects through various investment initiatives. Western Australia's mining sector focuses on advanced processing techniques for battery minerals, attracting significant capital.
Chile
Copper extraction in Chile generates substantial demand for green mining solutions like solar-powered equipment. Chile's environmental regulations mandate stringent tailings management and water recycling practices. The Atacama region sees extensive adoption of photovoltaic systems for mine operations.
Canada
Critical mineral facilities in Canada require zero-waste processing and ore remediation technologies. Health Canada regulations and provincial environmental policies compel miners to adopt advanced green practices. British Columbia's mining operations increasingly integrate bioleaching for metal recovery.
United States
Accelerating electric vehicle battery production creates demand for sustainably extracted lithium within the United States. The US Inflation Reduction Act (IRA) provides incentives for domestic green mining and processing capabilities. Appalachia's historical coal regions focus on extensive land rehabilitation projects.
China
Stringent environmental regulations from China's Ministry of Ecology and Environment (MEE) drive green mining technology adoption. Domestic demand for critical minerals also compels investment in sustainable practices. Inner Mongolia's rare earth mining operations are implementing advanced emission control solutions.
Green Mining Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, diversified mining conglomerates and a growing number of specialized technology providers. Strategic archetypes include established majors leveraging capital for green transitions and agile innovators developing niche sustainable solutions. Dominant competitive moves involve significant capital expenditure in advanced green infrastructure and strategic partnerships for technology co-development. Operators also pursue portfolio diversification into critical minerals.
Large-scale operators like BHP, Rio Tinto, and Anglo American exemplify the established major archetype, deploying extensive capital into green mining initiatives. These entities occupy a position of market leadership due to their global operational footprint and financial capacity for large-scale technology adoption. BHP sustains market leadership by integrating advanced emission control solutions across its global operations, ensuring compliance and efficiency. Rio Tinto leverages extensive capital for solar-powered equipment and water recycling infrastructure, particularly in water-stressed regions. Anglo American differentiates through its commitment to developing regenerative mining projects, aiming for net positive environmental outcomes.
| Leading Market Players |
|---|
| BHP |
| Rio Tinto |
| Anglo American |
| Vale S.A. |
| Glencore |
| Freeport-McMoRan |
| Antofagasta |
| Codelco |
| Barrick Gold |
| Others |
Cost & Logistics Intelligence
Western Australia's advanced processing capacity for battery minerals influences global rare earth metals pricing, reflecting the region's secure, sustainably-mined supply. This concentration of specialized infrastructure dictates the availability of high-grade materials for downstream industries.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for green-mined materials. Price differentiation drivers include stringent certification levels, such as EU Green Deal compliance, and the volume scale of purchases. Pricing pressure stems from the high capital intensity of green infrastructure, pushing operators to seek long-term commitments. Automotive manufacturers and electronics companies are moderately price-sensitive, balancing cost with verifiable sustainability claims.
Supply Chain Analysis
Extended payment terms for specialized green mining equipment support the capital-intensive nature of the industry. Geographic supply concentration centers on Australia for rare earth metals, Chile for copper, and Canada for critical minerals. Raw material dependencies include specialized reagents for bioleaching and high-grade silicon for solar-powered equipment. Geopolitical supply risks arise from the concentration of critical mineral processing in a few nations, notably China. Downstream distribution runs through direct contracts with large industrial consumers and specialized commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity, with specialized environmental consulting and digital twin integration services expanding faster than core green mining hardware sales.
For Market Incumbents:
Pre-empt competitive threats from junior miners by investing heavily in advanced bioleaching and zero-waste processing R&D. Consolidate market share through strategic partnerships with specialized technology providers, addressing the talent scarcity in environmental sciences. Leverage extensive capital to fund large-scale solar-powered equipment deployments, mitigating rising energy costs and enhancing ESG metrics.
For New Entrants and Emerging Players:
Localized e-waste recycling facilities represent a significant underpenetration, offering a pathway to critical mineral circularity. Target niche ore bodies or brownfield sites requiring specialized ore remediation solutions. A go-to-market angle focusing on rapid regulatory compliance and verifiable sustainability data provides a strong differentiator for smaller, agile operators. Focus on modular green technology solutions for smaller-scale projects.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized green mining technology providers with proven scalability and strong intellectual property portfolios. Long-term viability hinges on companies demonstrating verifiable net-positive environmental outcomes and strong regulatory alignment over the next decade. The signal to watch is the increasing adoption rate of zero-waste processing technologies across new project developments.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Zero-Waste Processing Facilities | Minimizes environmental impact and complies with stringent regulatory mandates from bodies like China's MEE. |
| Develop Regenerative Mining Projects | Secures preferential ESG-linked financing and enhances social license to operate for large mining corporations. |
| Form Strategic Technology Partnerships | Addresses specialized talent scarcity and accelerates the integration of advanced green mining solutions. |
| Expand Critical Mineral Recycling Capacity | Reduces reliance on virgin material extraction and diversifies supply sources for EV battery manufacturers. |
| Implement Digital Twin Technology | Optimizes operational efficiency and enables predictive environmental impact assessment for complex mine sites. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with extensive secondary validation. Primary data involved discussions with mining engineers, environmental scientists, regulatory compliance officers, and materials procurement specialists. Secondary sources included government geological surveys, environmental agency reports, corporate sustainability reports, and industry association data, all triangulated using bottom-up and top-down approaches.
The calibration approach involved cross-referencing market size estimates against production volumes and demand projections over the projection horizon. The analytical framework modeled segmentation across technology type, application area, mineral type, and regional regulatory environment. Compound annual growth rates were derived from historical trends and projected market drivers. Industry-specific forecast inputs included electric vehicle production forecasts and critical mineral demand projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized technology providers or new market entrants would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and technological progression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Global Water Quality Monitoring Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
Environmental Testing Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Indoor Air Quality Service Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Soil Remediation Technologies Market