
 Environmental Test Equipment Market | 2026-2036
Environmental Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Test Equipment Market Analysis
Copper thermal exchange systems are pivoting toward aluminum-nitride ceramic substrates in high-performance temperature chambers, cutting thermal mass and improving ramp rates. Thermo Fisher Scientific leverages captive semiconductor cleanroom expertise to dominate precision thermal cycling platforms. Agilent Technologies anchors its position through analytical instrument integration with environmental stress screening workflows. ESPEC Corp. specializes in compact benchtop chambers for Asia-based electronics contract manufacturers.
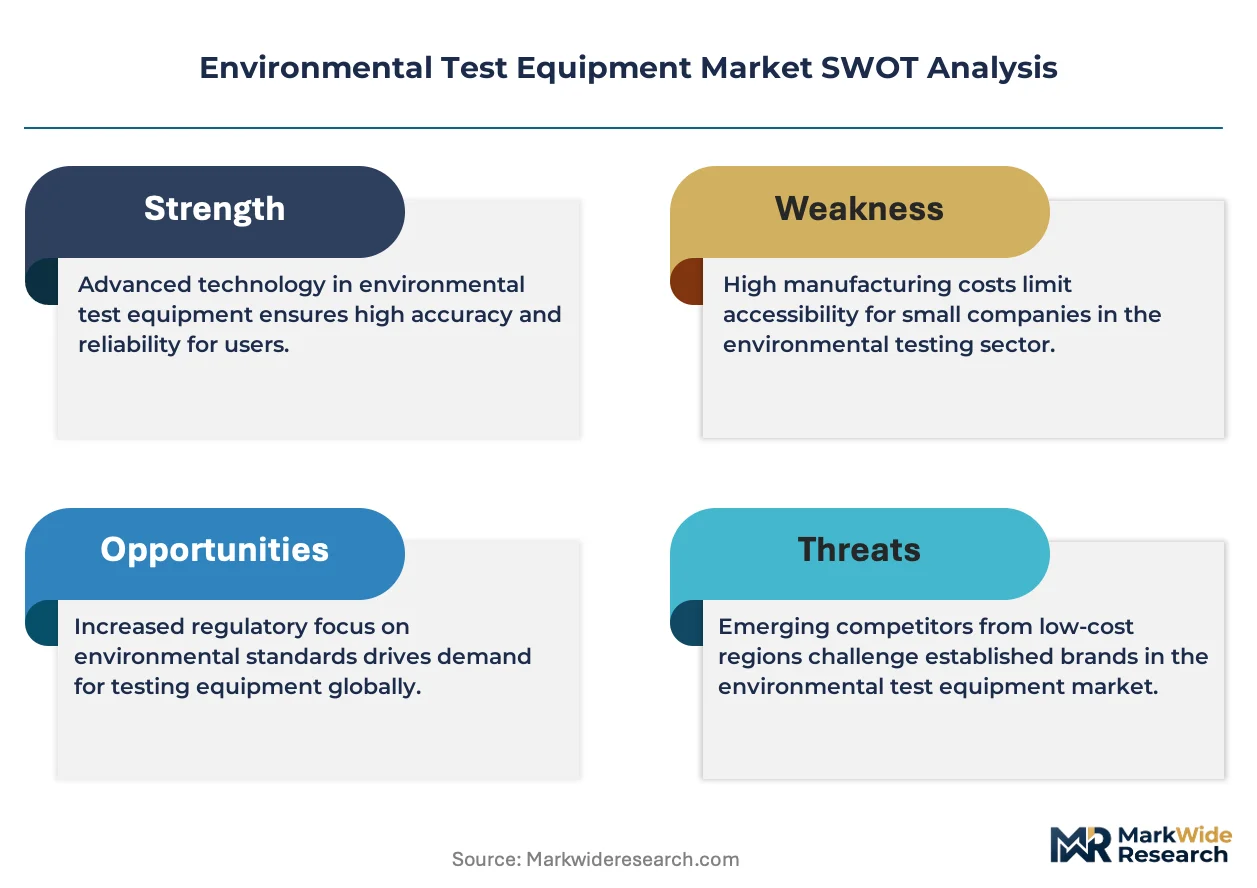
Environmental test equipment comprises controlled chambers and portable instruments that simulate temperature, humidity, vibration, altitude, and corrosive conditions to validate product durability and compliance. Modern chambers achieve thermal transition rates exceeding 15°C per minute through cascade refrigeration and liquid nitrogen boost systems, serving aerospace qualification and automotive accelerated life testing. Temperature chambers command the largest installed base but face margin compression from commoditized Asian supply, while humidity chambers generate premium pricing in pharmaceutical stability testing where ICH Q1A guidelines mandate tight tolerance control. Vibration test systems represent the fastest-expanding segment as electric vehicle battery packs require combined thermal-mechanical validation.
EPA emissions standards and OSHA workplace safety regulations in the United States mandate refrigerant containment and operator exposure limits, pushing chamber manufacturers toward closed-loop designs. ECHA REACH restrictions on hydrofluorocarbon propellants and EU F-Gas phase-down rules are reshaping refrigerant selection across European equipment portfolios. Stakeholders must monitor evolving battery safety test protocols from UN 38.3 and regional transport authorities, as lithium-ion thermal runaway simulation becomes a mandatory chamber capability across automotive and energy storage supply chains.
Market Dynamics
Cascade refrigeration systems with liquid nitrogen boost circuits are displacing conventional single-stage compressors as aerospace qualification protocols demand thermal transition rates above 15°C per minute.
Growth Catalysts
- FAA and EASA Airworthiness Mandates:Aerospace manufacturers in the US and Germany are expanding climate chamber fleets to satisfy stringent airworthiness certification protocols for next-generation aircraft programs.
- REACH Substance Restrictions:ECHA's tightening chemical regulations across Europe are forcing accelerated replacement cycles for legacy equipment containing restricted hydrofluorocarbon refrigerants.
- Semiconductor Fabrication Clusters:Demand concentrates in China's advanced manufacturing corridors around Shanghai and Shenzhen as domestic chip self-sufficiency targets expand cleanroom testing infrastructure.
Market Restraints
- Refrigerant Cost Volatility:Phase-down schedules under EU F-Gas Regulation and EPA SNAP restrictions are creating input cost uncertainty for chamber manufacturers dependent on synthetic refrigerant supply chains.
- Asian Supply Concentration:Commoditized temperature chamber production gravitates toward Chinese and South Korean contract manufacturers, compressing margins for established equipment vendors.
- Technical Limitation in Battery Testing:Current thermal runaway simulation protocols lack standardized chamber configurations capable of containing lithium-ion cascade failures at pack-level scale.
Strategic Opportunities
- Electric Vehicle Battery Validation:UN 38.3 transport safety mandates and regional battery safety codes are creating dedicated chamber demand for combined thermal-mechanical abuse testing.
- Pharmaceutical Stability Testing:ICH Q1A guideline compliance for tight-tolerance humidity control opens premium pricing pockets in contract research organization and biologics manufacturing segments.
- Aluminum-Nitride Ceramic Integration:Thermal exchange systems incorporating ceramic substrates enable faster ramp rates, creating differentiation for high-performance aerospace and defense qualification workflows.
Industry Challenges
- Cryogenic Systems Expertise Gap:Chamber manufacturers face acute shortages of technicians capable of servicing cascade refrigeration and liquid nitrogen injection subsystems.
- Multi-Standard Certification Timelines:Equipment vendors must navigate concurrent FAA, EASA, and MIL-STD-810 qualification tracks, extending product validation cycles.
- Legacy Control System Integration:Modern chambers with digital IoT architectures encounter friction when interfacing with existing facility SCADA and data acquisition infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Test Equipment Market |
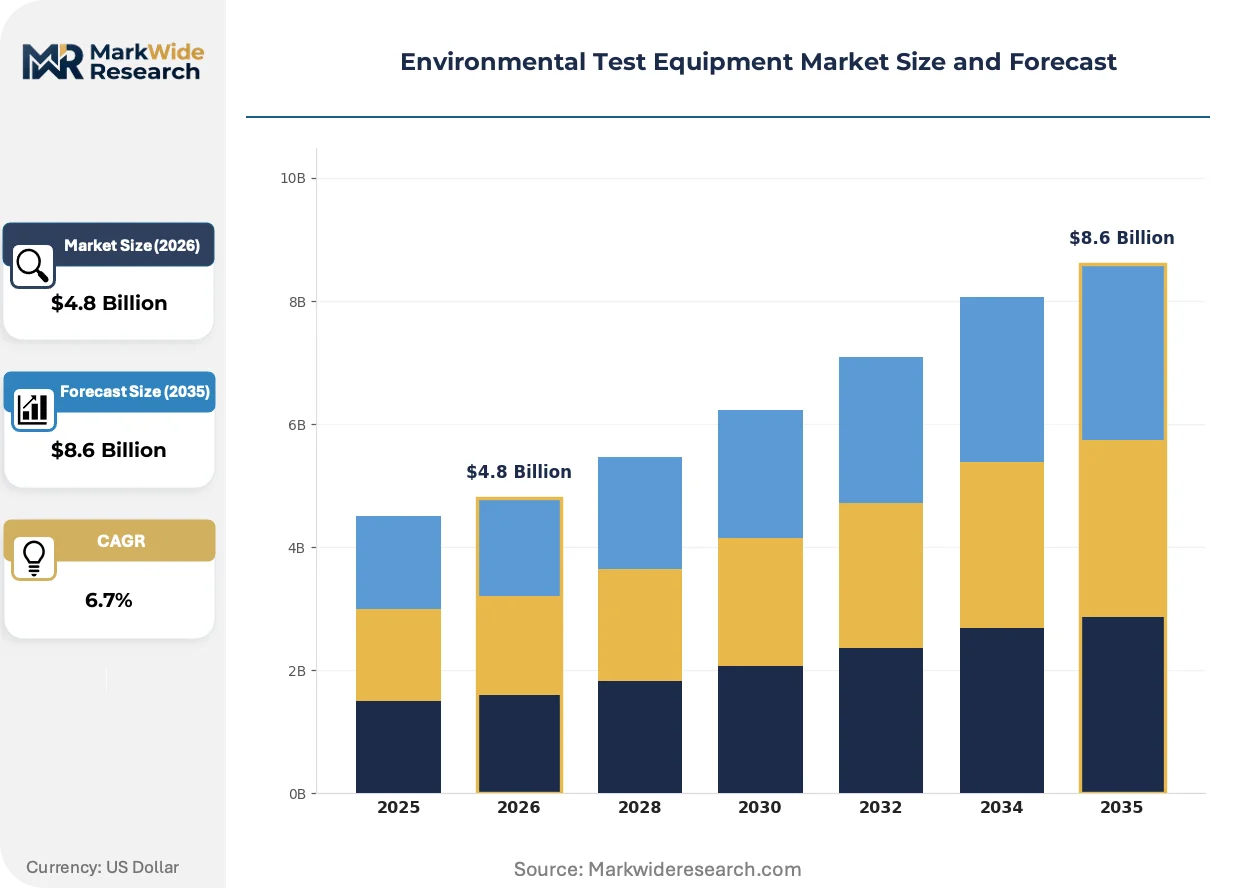
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Chambers, Humidity Chambers, Corrosion Testers, Altitude Chambers Industry Vertical: Aerospace, Automotive, Electronics, Pharmaceuticals End User: Manufacturers, R&D Labs, Quality Assurance, Environmental Agencies Testing Parameter: Temperature, Humidity, Vibration, Altitude |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., Waters Corporation, Shimadzu Corporation, PerkinElmer Inc., ESPEC Corp., Weiss Technik, Bruker Corporation, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Test Equipment Market Emerging Trajectories
Environmental test equipment architecture is pivoting from standalone chambers toward integrated validation ecosystems that combine thermal, mechanical, and electrical stress modalities in unified workflows.
Copper thermal exchange infrastructure is converging with aluminum-nitride ceramic substrates in next-generation temperature chambers. Aerospace qualification centers in Germany and the US are adopting these hybrid systems to achieve sub-10°C per minute ramp rates on large-format test articles. This materials convergence is compressing the performance gap between laboratory-grade and production-floor chamber categories, enabling contract manufacturers to bring accelerated life testing in-house.
ECHA's F-Gas Regulation phase-down schedule is forcing refrigerant portfolio restructuring across European equipment lines. Chamber OEMs are redesigning closed-loop systems around natural refrigerant alternatives to maintain CE marking compliance. Pharmaceutical and medical device segments face the steepest transition costs, as stability testing protocols demand precise humidity control that synthetic refrigerants previously delivered.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts. Asia-based electronics contract manufacturers now procure benchtop chambers through direct channels while sourcing calibration and certification from third-party metrology specialists. This disintermediation is most pronounced in Shenzhen and Suzhou, where high-volume production lines favor disposable chamber economics over capital-intensive precision platforms.
Environmental Test Equipment Market Segmentation
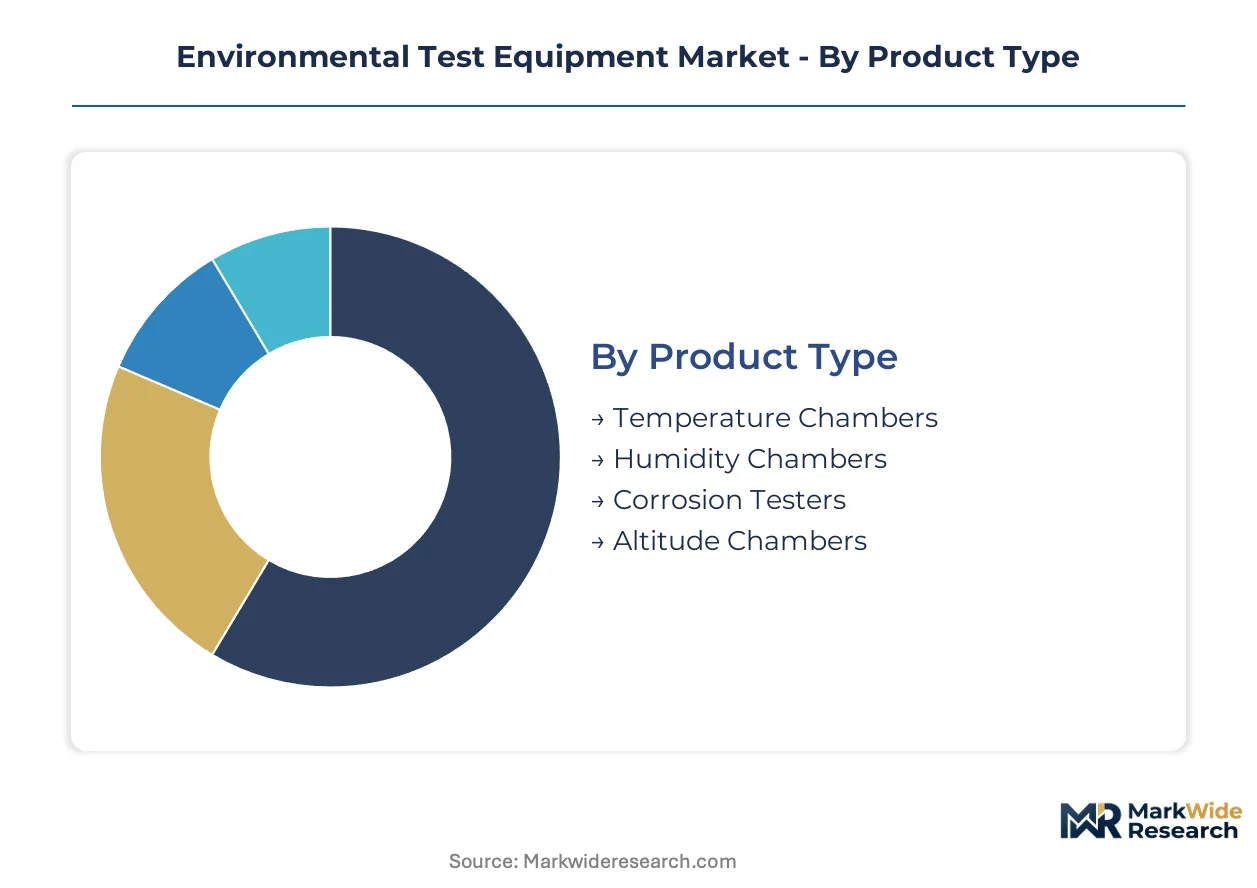
Environmental test equipment procurement decisions vary sharply by technical complexity and capital commitment. Aerospace qualification centers invest millions in multi-parameter chambers, while contract manufacturers prioritize benchtop units with rapid calibration cycles.
Product Type:
Capital intensity peaks in chambers requiring cascade refrigeration and liquid nitrogen boost circuits, where aerospace protocols demand thermal transition rates above 15°C per minute.
- Temperature Chambers:These units deploy cascade refrigeration and liquid nitrogen boost systems to achieve sub-10°C per minute ramp rates on large-format test articles. Aerospace manufacturers in the US and Germany absorb the bulk of high-end capacity as FAA and EASA airworthiness mandates tighten qualification protocols.
- Humidity Chambers:Tight-tolerance humidity control systems serve pharmaceutical stability testing where ICH Q1A guidelines mandate precise environmental control. Contract research organizations in Switzerland and Germany pay premium pricing for CE-marked units that maintain ±2% RH precision across extended test cycles.
- Corrosion Testers:Salt spray and cyclic corrosion cabinets validate automotive coating durability for OEMs in Stuttgart and Detroit.
- Altitude Chambers:Vacuum-controlled systems simulate pressure differentials for avionics and unmanned aerial vehicle battery packs.
Temperature chambers absorb the bulk of installed capacity; humidity chambers are expanding most quickly as biologics manufacturing scales.
Industry Vertical:
Application complexity determines equipment specification tiers, with combined thermal-mechanical validation requirements driving the steepest investment curves.
- Aerospace:Qualification centers operate MIL-STD-810 compliant chambers for airframe and avionics testing. German and US facilities dominate demand as next-generation aircraft programs multiply certification cycles.
- Automotive:Electric vehicle battery packs require UN 38.3 compliant thermal runaway simulation capabilities. Automotive suppliers in South Korea and Germany face acute chamber shortages for pack-level abuse testing.
- Electronics:Semiconductor fabrication corridors around Shanghai and Shenzhen concentrate demand for compact benchtop units with rapid thermal cycling.
- Pharmaceuticals:Stability testing protocols under ICH Q1A drive demand for precision humidity chambers in Swiss and German biologics manufacturing.
Electronics manufacturing concentrates the highest unit volumes; automotive battery validation shows the steepest specification escalation.
End User:
Procurement authority shifts capital allocation between centralized R&D facilities and distributed production-line testing.
- Manufacturers:In-house validation teams at automotive and electronics OEMs specify integrated thermal-mechanical chambers for production-floor deployment. German automotive suppliers lead in bringing accelerated life testing in-house.
- R&D Labs:Centralized research facilities at aerospace primes and pharmaceutical multinationals acquire multi-parameter chambers with advanced data acquisition. US and Swiss labs dominate high-end procurement.
- Quality Assurance:Third-party certification bodies operate reference-grade chambers for witness testing and audit protocols.
- Environmental Agencies:Government laboratories maintain standardized chambers for regulatory reference testing and compliance verification.
Manufacturers absorb the bulk of installed capacity; R&D labs are climbing the fastest as cleanroom testing infrastructure expands.
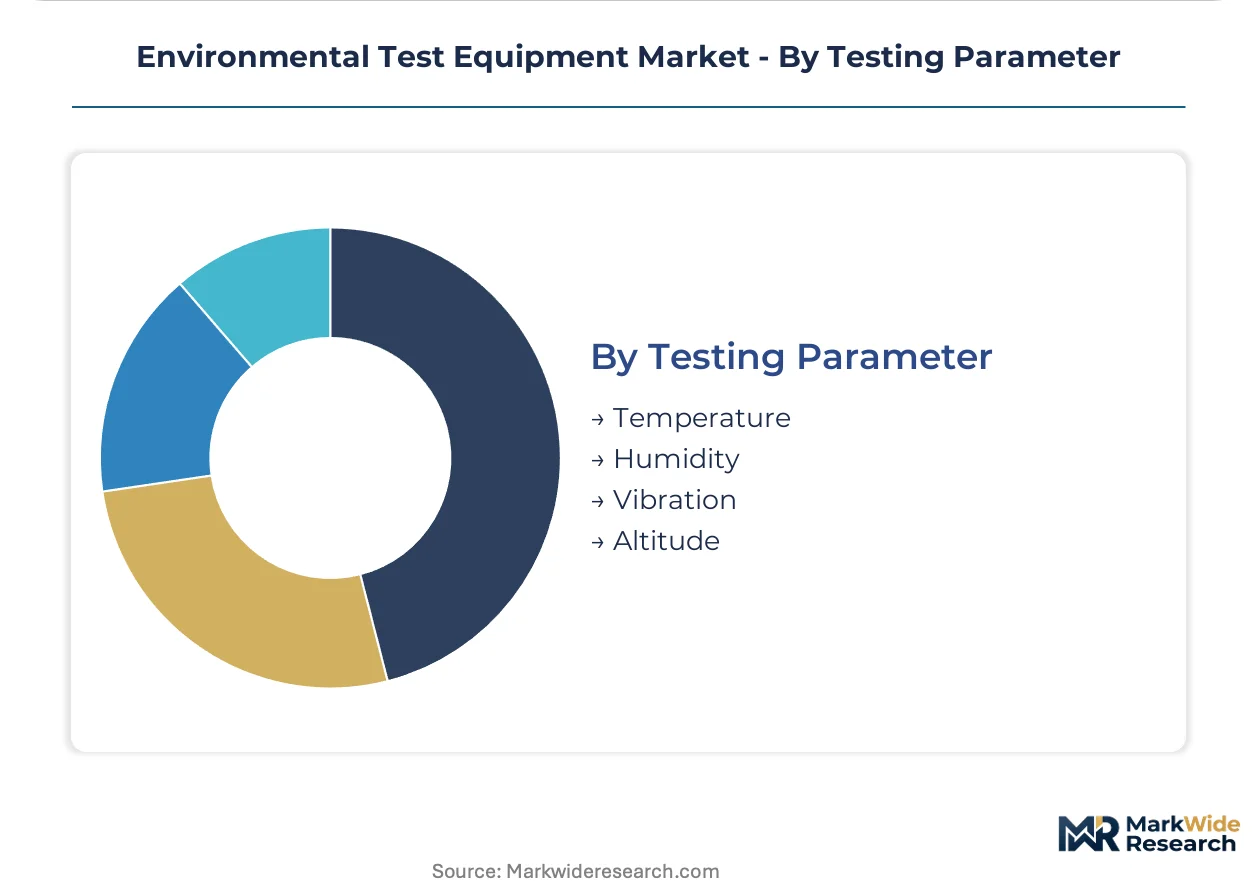
Testing Parameter:
Multi-parameter integration determines chamber architecture complexity and corresponding price positioning.
- Temperature:Thermal cycling platforms range from benchtop units to walk-in chambers with liquid nitrogen boost. Aerospace qualification centers in Germany and the US specify the most aggressive ramp rate capabilities.
- Humidity:Precision humidity control requires closed-loop refrigerant systems redesigned around natural alternatives under EU F-Gas Regulation. Pharmaceutical manufacturers in Switzerland face the steepest transition costs.
- Vibration:Electrodynamic shaker systems combine with thermal chambers for combined environment testing. Electric vehicle battery validation in South Korea and Germany drives the fastest specification escalation.
- Altitude:Pressure simulation chambers serve avionics and high-altitude drone applications with vacuum-controlled environmental envelopes.
Temperature testing absorbs the bulk of installed capacity; vibration systems are gaining share fastest as combined thermal-mechanical validation becomes mandatory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates where aerospace certification, semiconductor fabrication, and electric vehicle battery validation intersect with stringent regulatory mandates. The United States, Germany, China, Japan, and South Korea absorb the dominant share of high-performance chamber capacity.
United States
FAA airworthiness protocols and MIL-STD-810 qualification tracks drive demand from aerospace primes and defense contractors. EPA refrigerant containment rules under SNAP restrictions push chamber OEMs toward closed-loop natural refrigerant architectures. Seattle and Wichita qualification centers deploy multi-parameter chambers for next-generation aircraft programs.
Germany
EASA certification mandates and automotive battery safety codes from KBA create dual demand vectors for thermal-mechanical validation systems. ECHA REACH substance restrictions and EU F-Gas Regulation phase-down schedules force accelerated equipment replacement cycles. Stuttgart aerospace suppliers and Munich-area automotive battery labs concentrate high-end chamber procurement.
China
Domestic semiconductor self-sufficiency targets and MIIT cleanroom standards expand testing infrastructure across advanced manufacturing corridors. GB standards for environmental simulation equipment tighten technical specifications for locally produced chambers. Shanghai and Shenzhen fabrication clusters absorb compact benchtop units with rapid thermal cycling capabilities.
Japan
METI industrial standards and PMDA pharmaceutical stability guidelines sustain precision humidity chamber demand from biologics manufacturers. JIS certification requirements for test equipment create barriers for non-domestic suppliers in regulated segments. Nagoya automotive suppliers and Osaka electronics fabricators anchor regional procurement.
South Korea
MFDS pharmaceutical testing mandates and KSA battery safety standards from transport authorities drive combined thermal-mechanical chamber adoption. Electric vehicle battery pack validation requirements from domestic automotive OEMs outstrip current chamber availability. Seoul and Busan manufacturing corridors face acute shortages for pack-level abuse testing capacity.
Environmental Test Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium aerospace and pharmaceutical applications favoring established equipment vendors while electronics contract manufacturing gravitates toward commoditized Asian supply. The vendor base organizes around three strategic archetypes: diversified analytical instrument conglomerates leveraging cross-selling integration, dedicated environmental chamber specialists with captive cleanroom expertise, and regional contract manufacturers serving high-volume benchtop demand. Competitive positioning hardens through M&A consolidation of calibration and certification service networks, alongside geographic expansion of local assembly capacity to circumvent refrigerant logistics constraints.
Among diversified analytical instrument conglomerates, Thermo Fisher Scientific and Agilent Technologies occupy positions that exemplify integration-driven competitive strategy, while ESPEC Corp. represents the dedicated specialist archetype with concentrated expertise in compact chamber formats. These three entities anchor the competitive structure without exhausting its diversity, as regional fabricators across China and South Korea supply the volume tier that compresses margins at the standard-equipment level.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Waters Corporation |
| Shimadzu Corporation |
| PerkinElmer Inc. |
| ESPEC Corp. |
| Weiss Technik |
| Bruker Corporation |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
Cryogenic systems technician shortages in Germany and the US widen labor-cost differentials between high-performance aerospace qualification centers and commoditized Asian contract manufacturing, stretching pricing-tier spreads across premium certification-grade chambers and economy benchtop units.
Pricing Analysis
Volume concentrates in economy benchtop chambers while margins accrue to premium multi-parameter systems. Three-tier pricing structure across premium, standard, and economy levels separates FAA/EASA-certified aerospace units from CE-marked pharmaceutical chambers and unbranded Asian contract manufacturing supply. Cost compression in the economy tier is intensifying because Chinese and South Korean fabricators scale standardized thermal cycling platforms. Contract electronics manufacturers in Shenzhen exhibit the highest price sensitivity, while Swiss biologics manufacturers absorb premium pricing for ICH Q1A-compliant humidity precision.
Supply Chain Analysis
Certification and qualification gating restricts supply to vendors capable of concurrent FAA, EASA, and MIL-STD-810 validation tracks. Manufacturing concentrates in Germany, the United States, and China, with cascade refrigeration subsystems drawing from Japanese compressor specialists and aluminum-nitride ceramic substrates sourcing from Taiwanese materials suppliers. Single-source vulnerability in liquid nitrogen injection components creates chokepoint exposure for aerospace qualification centers. Distribution runs through direct OEM channels for high-performance chambers and electronics distributor networks for benchtop units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with captive cleanroom expertise and multi-standard certification capabilities, as REACH refrigerant restrictions and F-Gas phase-down schedules force smaller players into unsustainable replacement cost burdens.
For Market Incumbents: Cement dominance through backward integration into aluminum-nitride ceramic substrate production and captive certification service networks. Thermo Fisher Scientific's cleanroom-to-chamber workflow integration exemplifies the defensive moat against emerging Asian contract manufacturers. Prioritize MIL-STD-810 qualification track maintenance as defense contractors consolidate supplier bases. For New Entrants and Emerging Players: Battery thermal runaway simulation protocols offer a technology-first wedge into automotive validation workflows where standardized chamber configurations remain undefined. Target South Korean electric vehicle battery pack suppliers facing acute chamber shortages for pack-level abuse testing. Pursue UN 38.3 compliance partnerships with domestic automotive OEMs as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing EASA/FAA dual certification and installed base density in German aerospace corridors given accelerating replacement cycles under EU F-Gas Regulation. Long-term viability favors vendors with service revenue exceeding 40% of total mix. Watch lithium-ion thermal runaway standardization timelines at UN 38.3 working groups as the inflection signal for automotive battery validation capacity deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | Concurrent FAA, EASA, and MIL-STD-810 qualification tracks extend product validation cycles but lock out commoditized competitors from aerospace procurement. |
| Natural Refrigerant Transition | Closed-loop system redesigns around CO₂ and hydrocarbon alternatives preserve CE marking compliance under ECHA F-Gas Regulation phase-down schedules. |
| Service Network Consolidation | Calibration and certification capability acquisitions capture recurring revenue from pharmaceutical stability testing mandates under ICH Q1A guidelines. |
| Ceramic Substrate Integration | Aluminum-nitride thermal exchange systems enable sub-10°C per minute ramp rates that differentiate high-performance aerospace qualification workflows. |
| Regional Assembly Footprint | Local manufacturing capacity in China and South Korea circumvents refrigerant logistics constraints and compresses delivery timelines for electronics contract manufacturers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with aerospace qualification center directors, pharmaceutical stability testing managers, automotive battery validation engineers, and environmental chamber procurement leads at electronics contract manufacturers. Triangulation combined bottom-up equipment shipment analysis with top-down end-use demand modeling across semiconductor fabrication, biologics manufacturing, and electric vehicle battery production verticals.
Data-stream reconciliation aligned thermal cycling platform shipment volumes with cleanroom infrastructure expansion permits and EASA certification database entries across the analysis window. Segmentation dimensions modeled include product type, industry vertical, end-user category, and testing parameter complexity, with CAGRs derived from regression analysis against semiconductor capital expenditure cycles and aerospace program certification timelines. Forecast inputs incorporated REACH substance restriction implementation schedules and UN 38.3 protocol revision trajectories.
Several conditions sit outside the modeled scope, including unforeseen refrigerant supply disruptions, abrupt shifts in FAA airworthiness protocol stringency, and lithium-ion battery chemistry transitions that obsolete current thermal runaway simulation configurations. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement timelines or battery safety standard harmonization across regional transport authorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
India Cloud Seeding Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Indoor Air Quality Service Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Global Weather Forecasting Services Market
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market