
 South America Air Quality Monitoring Market | 2026-2036
South America Air Quality Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
South America Air Quality Monitoring Market Insights
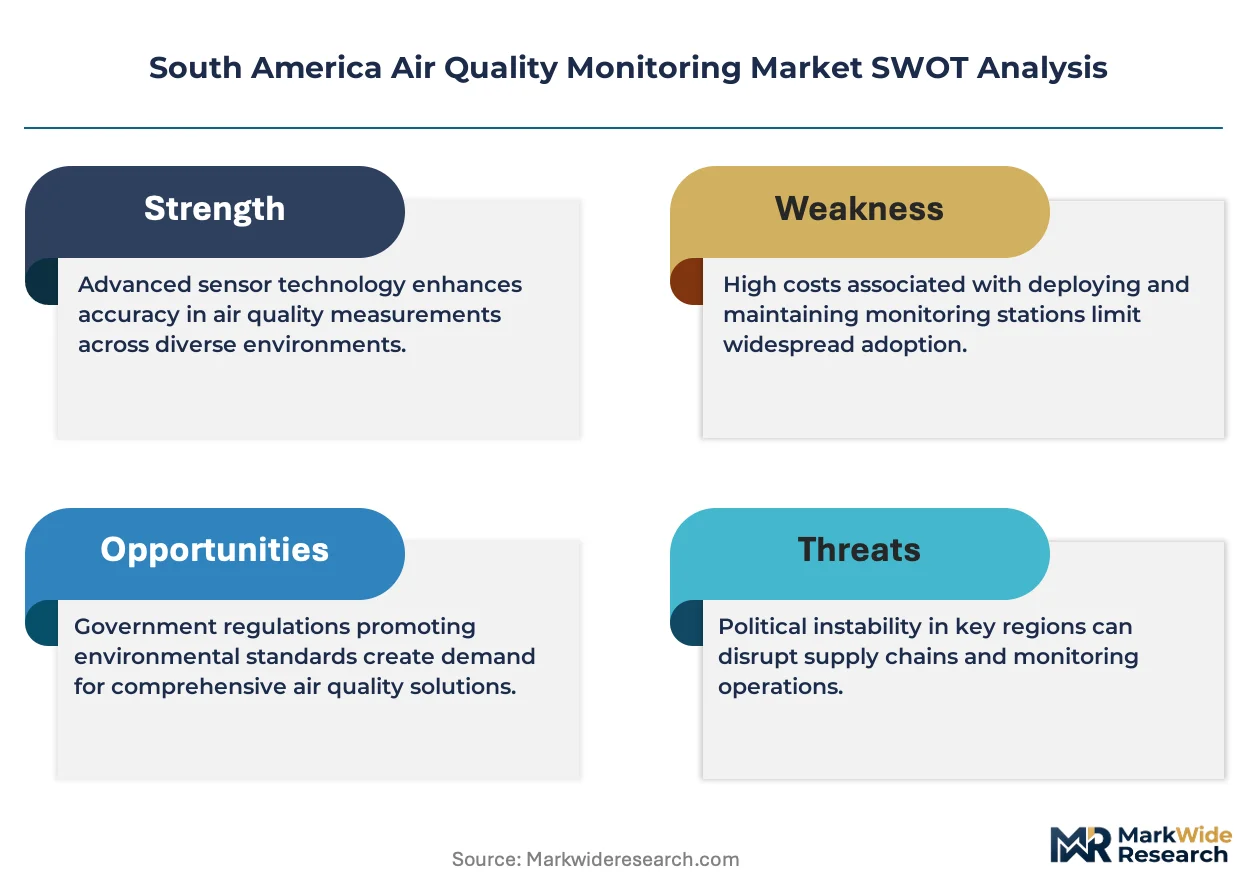
Optical sensor components are displacing electrochemical modules in premium monitor designs, which is realigning product economics toward higher-precision, lower-maintenance platforms. Thermo Fisher Scientific leverages its R&D intensity to sustain technology leadership in laser-based detection architectures. Vaisala Oyj anchors its position through meteorological integration capabilities that dominate environmental agency procurement cycles. Honeywell International Inc competes on manufacturing scale, extending its cost advantages across the portable monitor category.
Air quality monitoring encompasses the systematic measurement of atmospheric pollutants—including particulate matter, nitrogen oxides, sulfur dioxide, ozone, and volatile organic compounds—through calibrated sensor arrays, data acquisition systems, and networked reporting platforms designed to support regulatory compliance, public health alerts, and industrial process control. Fixed monitors constitute the structural backbone of national reference networks, while portable monitors represent the fastest-expanding segment as industries adopt mobile compliance verification tools. Laser sensors command premium positioning due to their detection sensitivity, whereas electrochemical sensors retain volume share in cost-sensitive municipal deployments.
CONAMA resolutions in Brazil, Chile's Ministry of Environment decontamination plans, and Peru's environmental quality standards enforcement by OEFA collectively shape product certification requirements and procurement specifications across the region. Argentina's Secretariat of Environment and Sustainable Development has accelerated reference station deployment timelines, tightening vendor qualification criteria. Stakeholders must monitor how regulatory harmonization pressures across Mercosur jurisdictions reshape equipment interoperability standards and cross-border service requirements.
Market Dynamics
Optical sensor architectures are compressing maintenance cycles and recalibrating procurement specifications across Brazilian municipal networks, forcing electrochemical suppliers to defend installed bases through price repositioning.
Growth Catalysts
- CONAMA Resolution 491:Brazil's tightening particulate matter thresholds for industrial zones are mandating denser monitoring grid deployment in São Paulo and Rio de Janeiro corridors.
- Copper smelter compliance:Chilean mining operations are retrofitting stack monitoring systems to capture sulfur dioxide emissions under Ministry of Environment decontamination timelines.
- Laser-induced breakdown spectroscopy:This detection method is penetrating reference-grade installations where sensitivity requirements exceed electrochemical module capabilities.
Market Restraints
- Import dependency:Brazil and Argentina rely on Asian-sourced optical components, exposing procurement timelines to semiconductor foundry capacity constraints.
- Calibration gas supply:Certified reference material for ozone and nitrogen dioxide span verification is concentrated among three European suppliers, creating bottleneck risk.
- Electrochemical drift:Sensor degradation in high-humidity Amazon basin conditions limits deployment lifespan below manufacturer specifications.
Strategic Opportunities
- Peruvian mining corridor:OEFA enforcement gaps in the Andean region present first-mover positioning for mobile monitoring fleet operators.
- IoT-5G convergence:Real-time data transmission architectures are enabling subscription-based air quality intelligence services for industrial estates.
- Colombian green bond financing:Bogotá's metropolitan planning department is channeling climate finance toward neighborhood-scale sensor networks.
Industry Challenges
- Metrologist scarcity:Brazil and Chile face acute shortages of technicians qualified for reference station calibration under ISO 17025 protocols.
- Multi-jurisdictional certification:Vendors must navigate divergent CONAMA, OEFA, and Chilean Ministry approval pathways, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Air Quality Monitoring Market |
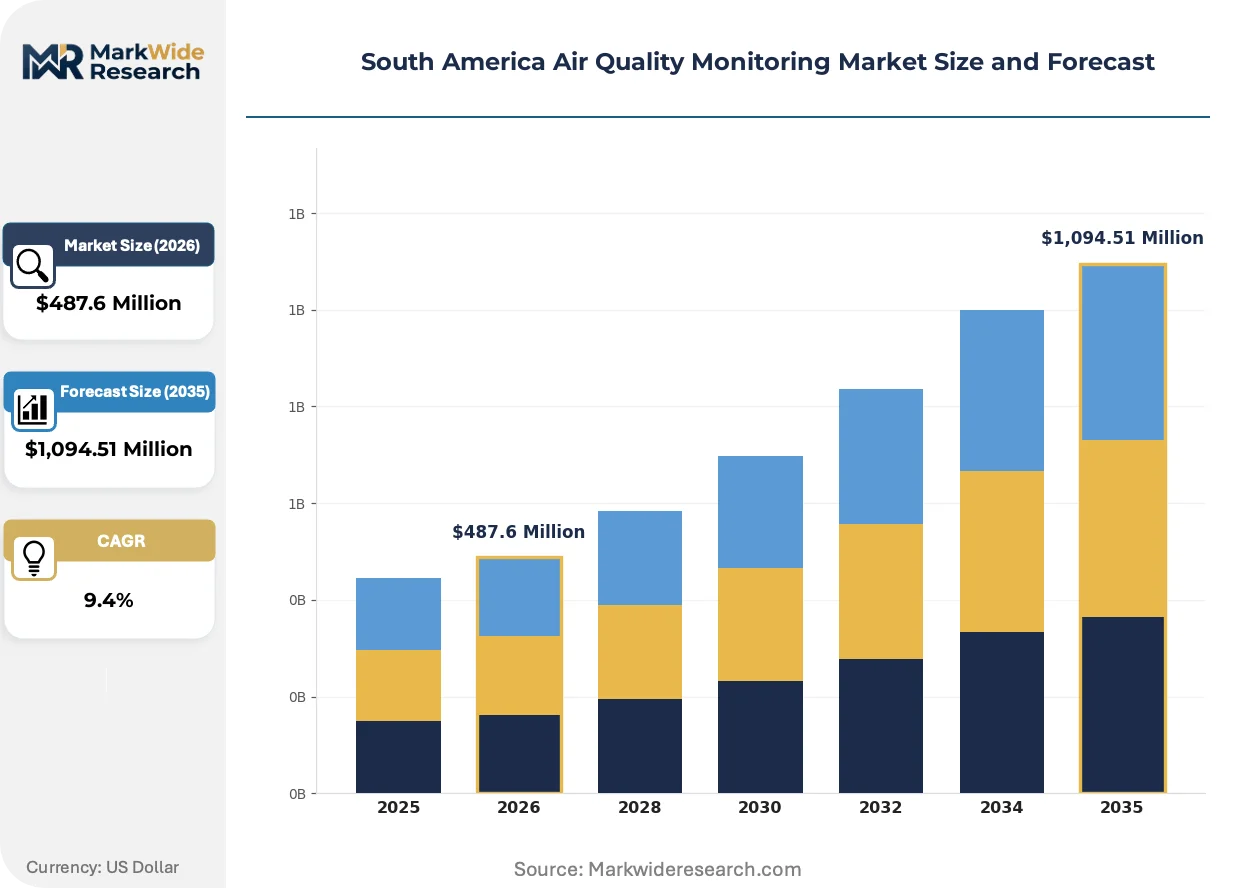
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Fixed Monitors, Stationary Systems, Indoor Air Quality Monitors Technology: Electrochemical Sensors, Infrared Sensors, Laser Sensors, Optical Sensors End User: Government Agencies, Environmental Organizations, Industries, Research Institutions Application: Outdoor Monitoring, Indoor Monitoring, Industrial Emissions, Air Quality Management |
| Companies Covered | Honeywell International Inc, Thermo Fisher Scientific, Vaisala Oyj, Ecotech, Testo SE & Co. KGaA, Aeroqual Limited, Teledyne Technologies, Horiba, Emerson Electric Co, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Air Quality Monitoring Market Trends and Innovations
Detection sensitivity thresholds are tightening across South American regulatory frameworks, compressing replacement cycles for legacy monitoring infrastructure and elevating specifications for incoming equipment.
Laser-based particulate matter sensors are integrating photon-counting architectures that achieve single-digit microgram-per-cubic-meter resolution. Brazilian environmental agencies in the São Paulo metropolitan corridor are specifying these modules for new fixed station procurements. The technology is integrating reference-grade accuracy into mid-tier price bands, collapsing the historical premium between regulatory and indicative monitoring tiers.
Chile's Ministry of Environment decontamination plans are forcing industrial emitters to upgrade from indicative to certified monitoring methodologies. Copper smelters in the Antofagasta region are deploying dual-technology stacks to satisfy both process control and regulatory reporting requirements. The policy is compressing equipment replacement cycles from seven years toward four-year refresh timelines.
Industrial buyers are unbundling hardware acquisition from data analytics services, pressuring traditional vendors to defend recurring revenue streams. Mining operations in Peru and Chile are procuring sensors through equipment lessors while contracting specialized environmental consultancies for compliance interpretation. The pattern is most pronounced in extractive sectors where capital discipline conflicts with intensifying OEFA and Ministry of Environment audit frequency.
South America Air Quality Monitoring Market Segmentation
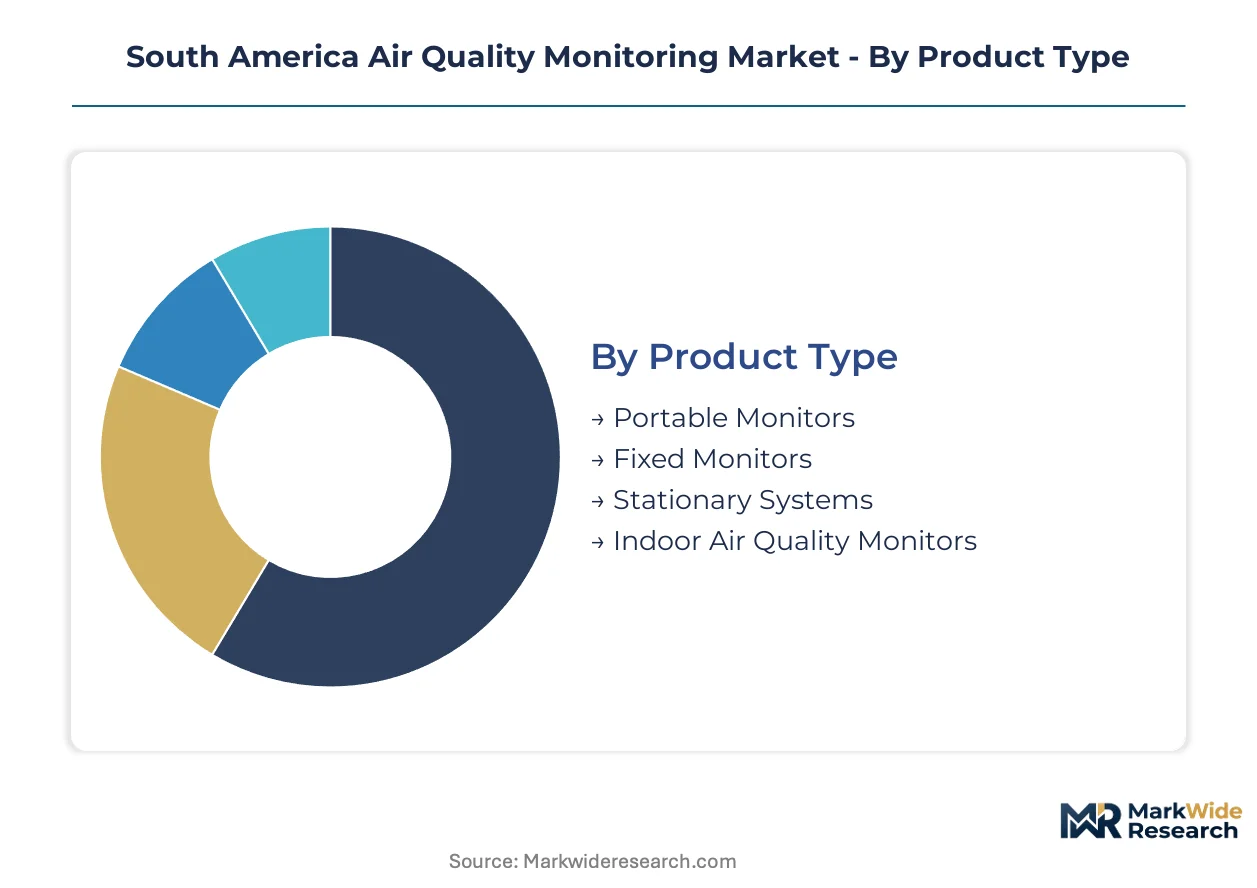
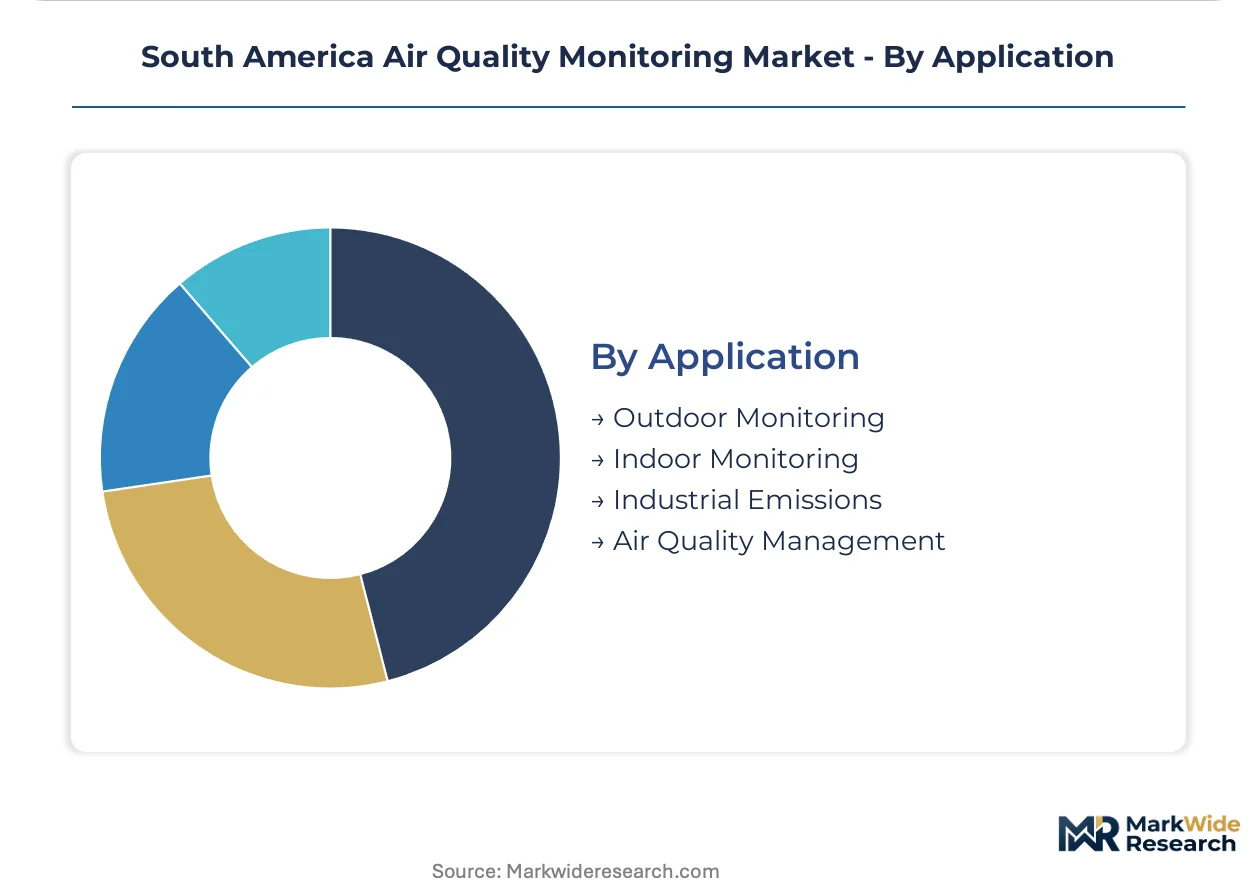
Segmentation in South American air quality monitoring reflects divergent certification burdens across regulatory jurisdictions. Equipment specifications shift dramatically between reference-grade networks and indicative deployments, with CONAMA, OEFA, and Chilean Ministry approvals creating distinct procurement tiers.
Product Type:
Certification timelines vary sharply across this category, with reference-grade fixed installations requiring ISO 17025 calibration protocols while portable units face lighter indicative-use approvals.
- Portable Monitors:Battery-powered units with electrochemical or optical sensor cores enable mobile compliance verification at mining sites and industrial perimeters. Chilean copper smelters in the Antofagasta region are deploying these for stack audit trails under Ministry of Environment decontamination mandates.
- Fixed Monitors:Permanent installations with heated inlet systems and meteorological integration constitute the backbone of national reference networks. São Paulo's municipal environmental agency specifies these for CONAMA Resolution 491 compliance in high-density industrial corridors.
- Stationary Systems:Rack-mounted multi-parameter analyzers for continuous emission monitoring at power generation and petrochemical facilities.
- Indoor Air Quality Monitors:Compact CO2 and particulate sensors for commercial building ventilation optimization in Bogotá and Santiago metropolitan areas.
Fixed monitors sit at the top of the volume ranking, with portable monitors climbing the fastest.
Technology:
Cost tiers stratify sharply here, with laser architectures commanding premium positioning against electrochemical volume plays.
- Electrochemical Sensors:Amperometric detection modules for nitrogen dioxide, sulfur dioxide, and ozone measurement dominate municipal budgets. Brazilian Amazon basin deployments suffer accelerated drift from high-humidity conditions, compressing replacement cycles below manufacturer specifications.
- Laser Sensors:Photon-counting architectures achieve single-digit microgram-per-cubic-meter particulate resolution. São Paulo's new fixed station procurements specify these modules, collapsing the historical premium between regulatory and indicative monitoring tiers.
- Infrared Sensors:Non-dispersive absorption systems for carbon monoxide and hydrocarbon detection in tunnel and traffic monitoring applications.
- Optical Sensors:Light-scattering and fluorescence-based platforms displacing electrochemical modules in premium monitor designs across the region.
Laser sensors command the premium tier, while electrochemical variants retain the broadest installed base.
End User:
Customer type determines procurement channel and service bundling preferences, with industrial buyers unbundling hardware from analytics.
- Government Agencies:Federal and state environmental authorities operating reference networks under CONAMA, OEFA, and Chilean Ministry specifications. Argentina's Secretariat of Environment has accelerated station deployment timelines, tightening vendor qualification criteria.
- Industries:Mining, smelting, power generation, and petrochemical operators facing intensifying audit frequency. Peruvian extractive sector buyers are procuring sensors through equipment lessors while contracting specialized consultancies for compliance interpretation.
- Environmental Organizations:NGOs deploying indicative monitors for community advocacy and hotspot identification in Colombian and Brazilian urban corridors.
- Research Institutions:Universities and national laboratories conducting atmospheric chemistry and health impact studies requiring research-grade instrumentation.
Industries represent the largest procurement volume, with government agencies expanding most quickly.
Application:
Geography shapes deployment patterns, with Andean mining corridors and coastal metropolitan zones presenting distinct technical requirements.
- Outdoor Monitoring:Urban reference stations and industrial perimeter networks tracking particulate matter and ozone against regulatory thresholds. CONAMA Resolution 491 mandates denser grid deployment in São Paulo and Rio de Janeiro corridors.
- Industrial Emissions:Stack and fence-line monitoring for sulfur dioxide, nitrogen oxides, and particulate capture. Chilean copper smelters are retrofitting systems under Ministry of Environment decontamination timelines.
- Indoor Monitoring:Commercial, educational, and healthcare facility ventilation management driven by green building certification requirements.
- Air Quality Management:Integrated platform deployments combining sensor networks with forecasting and alert systems for metropolitan planning departments.
Outdoor monitoring holds the largest installed base, with industrial emissions gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The São Paulo metropolitan corridor anchors procurement volume across South America, where industrial density and regulatory enforcement create concentrated demand for particulate matter and ozone monitoring infrastructure.
Brazil
Municipal governments in São Paulo and Rio de Janeiro are expanding outdoor monitoring networks under CONAMA Resolution 491. The National Environmental Council has tightened compliance timelines for industrial emitters in high-density corridors. Brazilian Amazon basin deployments suffer accelerated sensor degradation from humidity conditions, compressing replacement cycles below specifications.
Chile
Copper smelters in the Antofagasta region are retrofitting stack monitoring systems to capture sulfur dioxide emissions. The Ministry of Environment decontamination plans mandate upgrades from indicative to certified monitoring methodologies. Equipment replacement cycles are compressing from seven years toward four-year refresh timelines.
Peru
OEFA enforcement gaps in the Andean mining corridor present positioning opportunities for mobile monitoring fleet operators. Extractive sector buyers are procuring sensors through equipment lessors while contracting specialized consultancies for compliance interpretation. The pattern reflects capital discipline conflicting with intensifying audit frequency.
Argentina
The Secretariat of Environment and Sustainable Development has accelerated reference station deployment timelines. Vendor qualification criteria are tightening across federal and provincial procurement cycles. Buenos Aires metropolitan agencies are specifying heated inlet systems with meteorological integration for new fixed installations.
Colombia
Bogotá's metropolitan planning department is channeling climate finance toward neighborhood-scale sensor networks through green bond mechanisms. Indoor air quality monitors for commercial building ventilation optimization are gaining traction in the capital's green building certification pipeline. Community advocacy deployments by environmental organizations are expanding in urban corridors.
South America Air Quality Monitoring Market Competitive Landscape
Global majors compete with regional champions across technology tiers and certification pathways in South American air quality monitoring. The vendor base stratifies between premium laser-based detection platforms and cost-optimized electrochemical volume plays. Three archetypes dominate: R&D-intensive technology leaders, meteorological integration specialists, and manufacturing-scale cost competitors. Competitive moves center on portfolio diversification into subscription-based data services and geographic expansion through localized certification partnerships.
Within the technology leadership tier, Thermo Fisher Scientific exemplifies R&D-intensive positioning in laser-based detection architectures. Vaisala Oyj occupies a specialist position through meteorological integration capabilities that dominate environmental agency procurement cycles. Honeywell International Inc anchors the scale-driven end, extending manufacturing cost advantages across portable monitor categories. These three companies represent distinct competitive vectors—precision innovation, systems integration, and volume efficiency—that structure rivalry across Brazilian municipal networks and Chilean industrial compliance markets.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Thermo Fisher Scientific |
| Vaisala Oyj |
| Ecotech |
| Testo SE & Co. KGaA |
| Aeroqual Limited |
| Teledyne Technologies |
| Horiba |
| Emerson Electric Co |
| Others |
Pricing and Supply Chain Analysis
CONAMA Resolution 491 compliance mandates gate both qualified supply and premium-tier pricing access, as Brazilian municipal agencies restrict procurement to vendors with ISO 17025 calibration protocols and heated inlet meteorological integration. This regulatory filtering compresses the vendor pool while elevating price floors for reference-grade fixed installations in São Paulo and Rio de Janeiro corridors.
Pricing Analysis
Input-cost pass-through from Asian-sourced optical sensor components and European calibration gas suppliers shapes pricing dynamics across the region. Three-tier pricing structure across premium, standard, and economy levels separates laser-based photon-counting architectures from electrochemical volume plays and indicative-use portable units. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the electrochemical tier is intensifying because Brazilian Amazon basin humidity accelerates sensor drift, forcing price repositioning to defend installed bases. Municipal government agencies exhibit highest price sensitivity due to budget cyclicality, while Chilean copper smelters under Ministry of Environment mandates show lowest sensitivity for certified monitoring methodologies.
Supply Chain Analysis
Warehouse-distribution layer configuration centers on São Paulo as the regional hub, with spoke patterns radiating to Santiago, Bogotá, and Lima metropolitan corridors. Manufacturing concentrates in China, Germany, and Finland for optical components, meteorological sensors, and laser detection modules respectively. Raw material dependencies span semiconductor photodetectors, certified reference gases, and heated inlet stainless steel assemblies. Single-source vulnerability in European calibration gas supply creates bottleneck risk for ozone and nitrogen dioxide span verification. Distribution runs through authorized service partners with ISO 17025 accreditation for installation and maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in South American air quality monitoring rest on optical sensor cost curves flattening and subscription-based data analytics services capturing recurring revenue from industrial unbundling trends.
For Market Incumbents: Cement technology leadership in laser-based detection architectures through backward integration into photon-counting module production. Defend São Paulo municipal network installed bases by embedding meteorological integration capabilities that raise switching costs. Accelerate certification investment across CONAMA, OEFA, and Chilean Ministry pathways to extend product launch timeline advantages over emerging competitors. For New Entrants and Emerging Players: Enter via Peruvian Andean mining corridor enforcement gaps where mobile monitoring fleet services face limited incumbent saturation. Target Bogotá neighborhood-scale sensor networks financed through green bond mechanisms as the most penetrable government segment. Pursue equipment leasing partnerships with environmental consultancies as the dominant go-to-market angle for extractive sector buyers practicing capital discipline. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with ISO 17025 calibration capabilities because metrologist scarcity across Brazil and Chile creates captive customer relationships. Five-to-ten year viability hinges on IoT-5G convergence enabling platform subscription models. Signal to monitor: harmonization pressures across Mercosur jurisdictions reshaping equipment interoperability standards and cross-border consolidation logic.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Captures margin compression from Asian semiconductor foundry constraints affecting Brazilian procurement timelines. |
| Subscription-Based Data Analytics Services | Converts hardware transactions into recurring revenue as Chilean smelters unbundle compliance interpretation from equipment acquisition. |
| Multi-Jurisdictional Certification Investment | Extends product launch timeline advantages by pre-qualifying for CONAMA, OEFA, and Chilean Ministry approval pathways. |
| Mobile Monitoring Fleet Expansion | Exploits OEFA enforcement gaps in Peruvian mining corridors before incumbent reference network saturation. |
| Green Bond Financing Partnerships | Aligns with Bogotá metropolitan planning department climate finance channels for neighborhood-scale sensor deployment. |
Research Methodology
Multiple input streams — primary interviews with environmental agency procurement officers, industrial compliance managers, and calibration service technicians; secondary validation through CONAMA resolution texts, OEFA enforcement records, and Chilean Ministry decontamination plans; plus customs data on optical component imports — were reconciled through bottom-up equipment shipment analysis and top-down regulatory mandate scaling. Triangulation across stakeholder perspectives and documentary sources anchored volume estimates.
Historical deployment patterns were cross-referenced against panel input from municipal network operators and mining sector environmental officers to build the analytical framework. Segmentation dimensions modeled include product type, detection technology, end-user category, and application across the projection horizon. CAGRs were derived from equipment replacement cycle compression in Chile and densification mandates in Brazil, with sensitivity testing around semiconductor supply constraints and metrologist availability.
Inputs from Brazilian municipal procurement databases and Chilean copper smelter environmental disclosures were available through the study window; gaps in Peruvian OEFA mobile audit trail data introduce uncertainty bands around Andean mining corridor estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Water Quality Monitoring Systems Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Environmental Testing Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Asia-Pacific Food and Environment Manual Testing Market