
 US Environmental Testing Market | 2026-2036
US Environmental Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US Environmental Testing Market Insights
Multi-source laboratory outsourcing is expanding across industrial and municipal clients as compliance complexity outpaces in-house analytical capacity. Eurofins Scientific leverages its nationwide laboratory network to anchor federal and state contract workflows. SGS competes through specialized air toxics and stack emissions protocols. Thermo Fisher Scientific dominates analytical instrumentation supply to third-party labs and direct government purchasers.
US environmental testing encompasses chemical, biological, and physical analysis of soil, water, air, and waste matrices to detect contaminants against regulatory thresholds, employing chromatography, mass spectrometry, and immunoassay methods with detection limits reaching parts per trillion for compounds like PFAS. Water quality testing leads volume demand as EPA drinking water standards tighten, while biosensor technology represents the fastest-expanding segment through real-time contaminant screening applications. Laboratory methods still occupy the largest revenue share given certification requirements for defensible data in enforcement proceedings.
EPA, OSHA, and state-level Department of Environmental Quality frameworks collectively shape testing demand through mandated monitoring frequencies, approved analytical methods, and penalty structures for non-compliance. The Safe Drinking Water Act and Comprehensive Environmental Response, Compensation, and Liability Act create recurring compliance obligations that sustain laboratory revenue visibility. Stakeholders must monitor emerging contaminant candidate list rulings and method update frequencies to align capability investments with enforceable detection requirements.
Market Dynamics
EPA's Unregulated Contaminant Monitoring Rule is forcing municipal water utilities to expand analytical scope beyond legacy parameters, straining laboratory capacity and accelerating third-party outsourcing across the Great Lakes and California industrial corridors.
Growth Catalysts
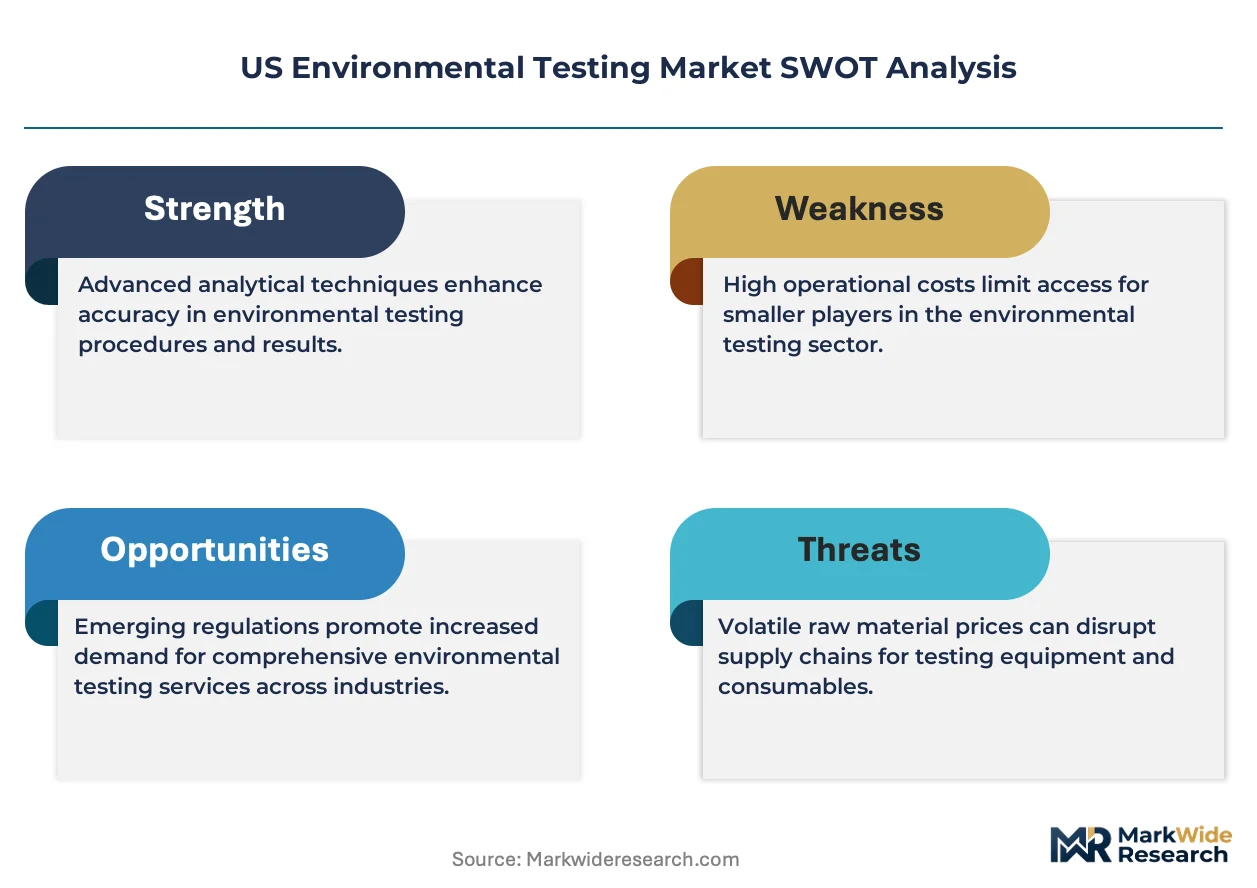
- Safe Drinking Water Act amendments:Federal mandates for PFAS detection at parts-per-trillion thresholds compel facility upgrades and recurring testing contracts across municipal water systems.
- Industrial corridor remediation:Legacy contamination in Michigan, Ohio, and Wisconsin sustains soil and groundwater monitoring demand from manufacturing and chemical processing sites.
- Biosensor miniaturization:Real-time field screening technologies reduce sample transport burdens and enable faster turnaround for emergency response protocols.
Market Restraints
- Helium supply volatility:Mass spectrometry operations depend on constrained noble gas imports, creating chromatography downtime risks and cost spikes.
- Laboratory certification bottlenecks:State-level Department of Environmental Quality accreditation timelines stretch 12-18 months, capping expansion velocity for new entrants.
- Immunoassay substitution limits:Rapid screening methods lack defensibility for enforcement proceedings, restricting their displacement of certified laboratory methods.
Strategic Opportunities
- Texas shale basin expansion:Produced water reuse regulations in the Permian Basin create demand for oilfield chemistry and salinity testing services.
- Air toxics protocol convergence:Integration of stack emissions monitoring with continuous ambient surveillance opens bundled service contracts for petrochemical clients.
- Digital chain-of-custody platforms:Blockchain-secured sample tracking reduces documentation errors and accelerates regulatory audit readiness for third-party laboratories.
Industry Challenges
- Mass spectrometry technician scarcity:Specialized instrument operation and maintenance skills command premium wages, constraining laboratory throughput scaling.
- Method update lag:EPA's slow publication of validated protocols for emerging contaminants leaves laboratories exposed to liability for non-standard analytical approaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Environmental Testing Market |
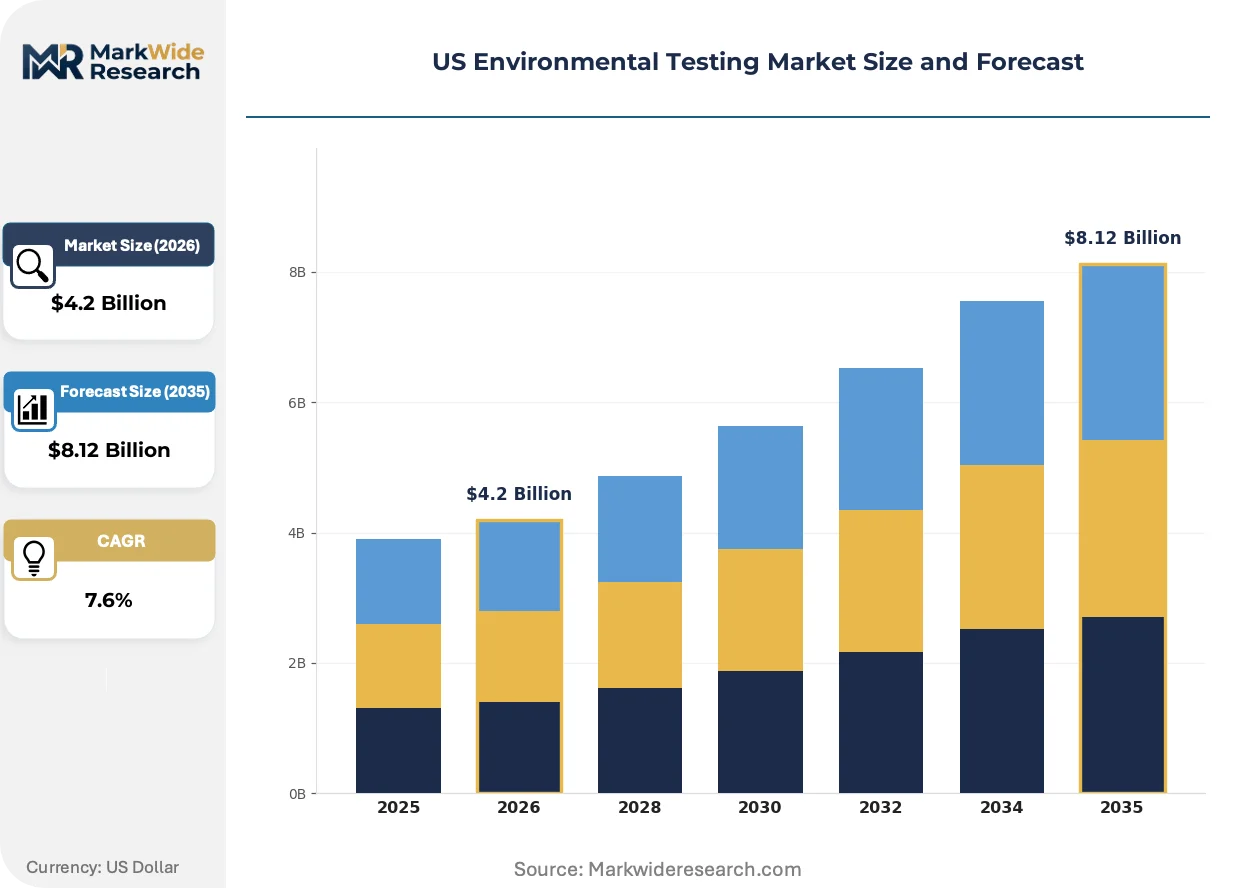
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $8.12 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Type: Soil Testing, Water Quality Testing, Air Quality Testing, Waste Testing End User: Manufacturers, Government Agencies, Environmental Consultants, Research Institutions Application: Pollution Analysis, Compliance Monitoring, Remediation Projects, Risk Assessment Technology: Laboratory Methods, Field Testing Kits, Remote Sensing, Biosensors |
| Companies Covered | Eurofins Scientific, SGS, Bureau Veritas, Intertek Group, Agilent Technologies, Thermo Fisher Scientific, Pace Analytical Services, EMSL Analytical, Microbac Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Environmental Testing Market Trends and Innovations
Digital integration and portable detection platforms are compressing the gap between field screening and laboratory-grade certainty, reshaping how environmental data is generated, transmitted, and validated across regulatory workflows.
High-resolution mass spectrometry is rewriting the detectable universe for environmental chemists. Municipal utilities in California and industrial facilities along the Gulf Coast are adopting orbitrap and time-of-flight systems to identify unknown transformation products. This capability is compressing the timeline between contaminant discovery and regulatory response, forcing laboratories to invest in non-targeted analysis workflows.
EPA's fifth Unregulated Contaminant Monitoring Rule imposes mandatory monitoring for 29 additional substances on public water systems serving over 10,000 customers. The rule's industrial consequence is a surge in sample volume concentrated among laboratories holding Safe Drinking Water Act certification. Small and medium utilities in the Midwest are responding by consolidating contracts with multi-state laboratory networks rather than maintaining in-house capacity.
Buyers are unbundling after-sales service from analytical instrument purchases, opting for third-party maintenance contracts and cloud-based remote diagnostics. Thermo Fisher and Agilent face margin pressure as independent service organizations capture calibration and repair revenue. This pattern is most visible among state Department of Environmental Quality laboratories in the Southeast, where budget constraints favor operational expenditure models over capital-intensive ownership.
US Environmental Testing Market Segmentation
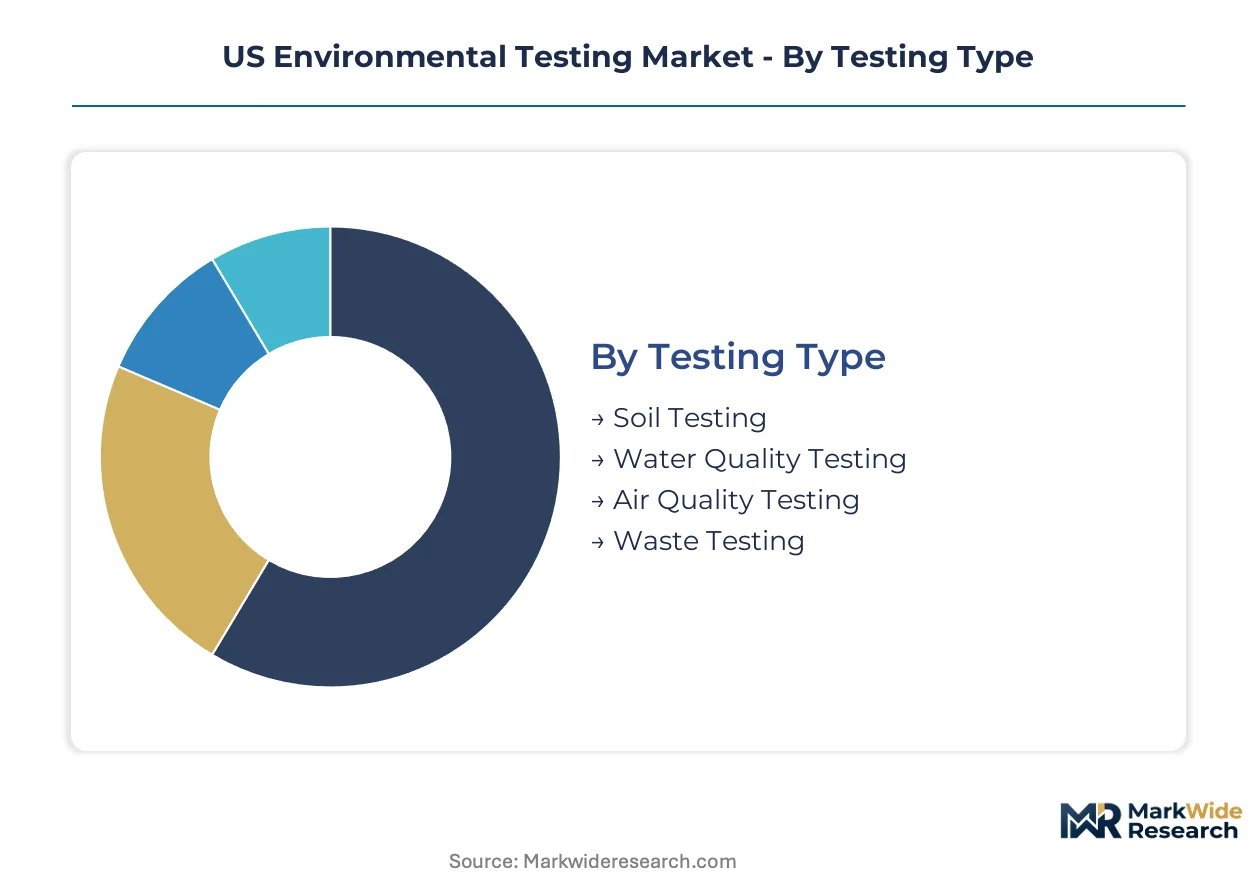
Environmental testing procurement splits across four distinct dimensions, each mapping to different capital requirements and regulatory certification burdens. Laboratories configure their service portfolios around specific technology-method combinations to capture recurring compliance contracts versus episodic remediation work.
Testing Type:
Capital intensity peaks with water quality infrastructure, where PFAS detection at parts-per-trillion demands mass spectrometry suites costing millions per installation.
- Water Quality Testing:Chromatography and mass spectrometry protocols dominate, with EPA Safe Drinking Water Act mandates driving municipal utility spending across California and the Great Lakes corridor. Helium supply constraints and 12-18 month certification timelines limit new laboratory entry.
- Soil Testing:Legacy contamination in Michigan, Ohio, and Wisconsin sustains demand from manufacturing and chemical processing sites. Sample preparation and extraction workflows require substantial bench space but lower per-sample instrument costs than water matrices.
- Air Quality Testing:Stack emissions and ambient monitoring protocols serve petrochemical clients along the Gulf Coast with continuous surveillance equipment.
- Waste Testing:Hazardous waste characterization under RCRA rules generates episodic volume from industrial generators and landfill operators.
Most installed capacity flows through Water Quality Testing. Expansion is steepest in Air Quality Testing as stack-ambient convergence creates bundled service opportunities.
End User:
Procurement authority concentrates with government agencies, whose multi-year contracts provide revenue visibility that manufacturers and consultants cannot match.
- Government Agencies:EPA, state Department of Environmental Quality laboratories, and municipal utilities anchor demand through mandated monitoring frequencies. Federal contracts favor vendors with nationwide laboratory networks and Safe Drinking Water Act certification.
- Manufacturers:Chemical, pharmaceutical, and electronics producers maintain in-house analytical capacity for process control and pre-regulatory screening. Capital constraints increasingly push mid-sized firms toward third-party outsourcing.
- Environmental Consultants:Engineering firms bundle sampling and analysis services for remediation project liability documentation. Consultant laboratories compete on turnaround speed and digital chain-of-custody capabilities.
- Research Institutions:Universities and federal research centers drive method development for emerging contaminants, though commercial volume remains limited.
Contract value concentrates with Government Agencies. Consultancy-led procurement is gaining share fastest as remediation project bundling accelerates.
Application:
Recurring revenue attaches to compliance monitoring, while remediation projects deliver higher margins through technical complexity and liability exposure.
- Compliance Monitoring:Regulatory-mandated testing under the Safe Drinking Water Act and Clean Air Act creates predictable sample volume. Municipal utilities in the Midwest are consolidating contracts with multi-state laboratory networks.
- Remediation Projects:CERCLA-driven site characterization and closure confirmation generate premium pricing for defensible data packages. Michigan and Wisconsin industrial corridors sustain the deepest project pipelines.
- Pollution Analysis:Emergency response and source identification work demands rapid turnaround, favoring laboratories with 24-hour operations.
- Risk Assessment:Pre-transaction due diligence and insurance underwriting support creates episodic demand from commercial real estate and private equity clients.
Sample volume concentrates in Compliance Monitoring. Pricing power is expanding most quickly in Remediation Projects as liability documentation standards tighten.
Technology:
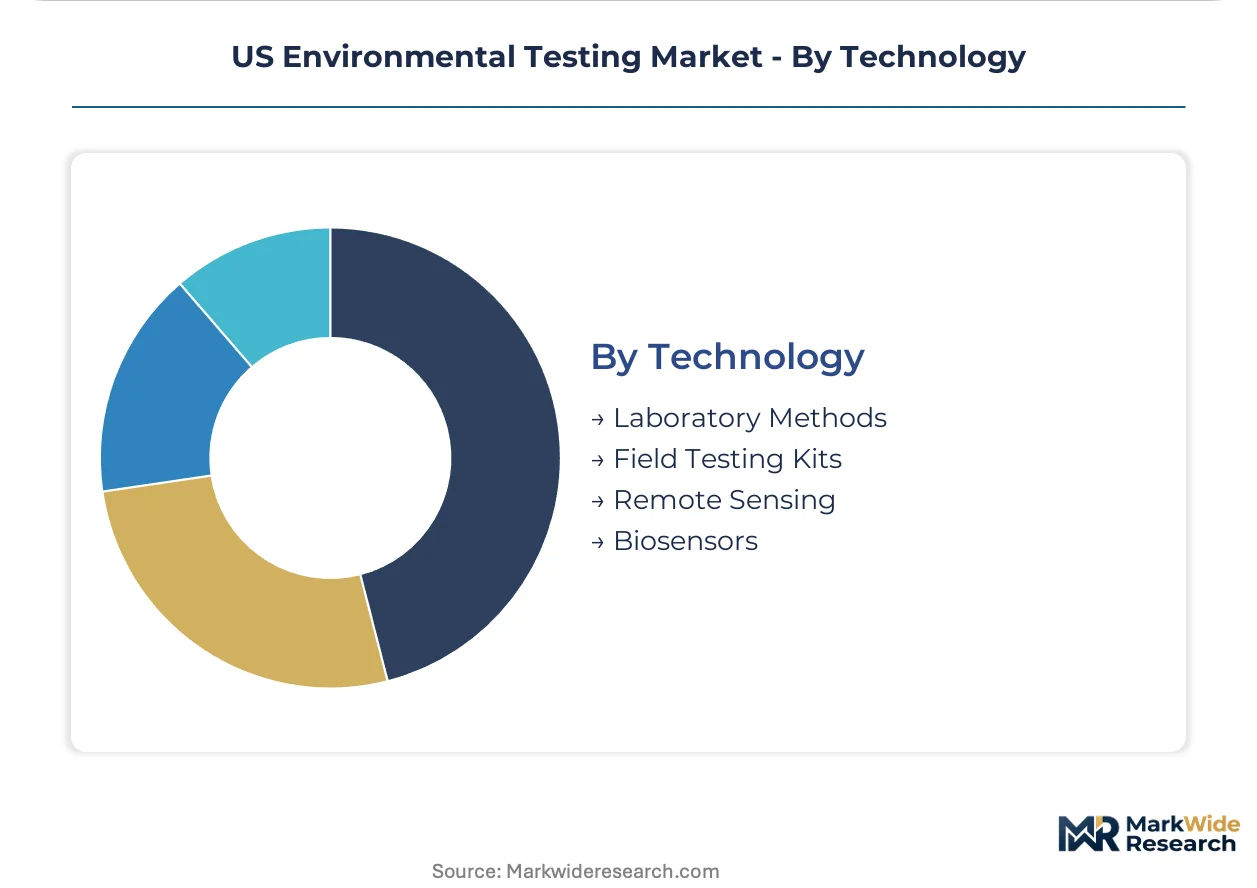
Laboratory methods command the largest revenue share given certification requirements for enforcement proceedings, though field-deployable alternatives are compressing the screening-confirmation gap.
- Laboratory Methods:Chromatography, mass spectrometry, and immunoassay techniques deliver defensible data for EPA enforcement actions. State-level accreditation requirements create sticky customer relationships and high switching costs.
- Biosensors:Real-time field screening technologies reduce sample transport burdens and enable faster emergency response. Miniaturization trends are driving adoption among municipal utilities for preliminary monitoring.
- Field Testing Kits:Immunoassay and colorimetric methods serve rapid screening needs where regulatory defensibility is not required. Cost advantages position kits for developing market entry and resource-constrained utilities.
- Remote Sensing:Satellite and aerial platforms support large-area contamination mapping and emissions monitoring, particularly for oilfield and mining applications in Texas and the Mountain West.
Certified analytical capacity concentrates in Laboratory Methods. Adoption is climbing fastest in Biosensors as real-time monitoring protocols gain regulatory acceptance for preliminary screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage shapes facility location decisions as compliance cost differentials between states drive laboratory network expansion. California and Texas command premium pricing for PFAS-certified capacity. The Great Lakes corridor sustains remediation-driven demand.
California
Stringent state-level Maximum Contaminant Levels for PFAS compounds exceed federal EPA thresholds, compelling municipal utilities to quadruple testing frequency. The State Water Resources Control Board mandates quarterly monitoring for systems serving over 10,000 customers. Los Angeles and San Diego metropolitan areas concentrate third-party laboratory contracts as in-house capacity proves inadequate for expanded analyte panels.
Texas
Produced water reuse regulations in the Permian Basin generate oilfield chemistry testing demand distinct from municipal water markets. The Texas Commission on Environmental Quality administers parallel certification tracks for commercial laboratories serving industrial versus public water system clients. Houston petrochemical corridor facilities bundle stack emissions monitoring with wastewater discharge testing under single-provider contracts.
Great Lakes Corridor
Legacy industrial contamination across Michigan, Ohio, and Wisconsin sustains soil and groundwater characterization work under CERCLA authority. EPA Region 5 maintains aggressive enforcement timelines for Remedial Investigation/Feasibility Study deliverables. Detroit, Cleveland, and Milwaukee metropolitan areas host the densest concentration of certified commercial laboratories outside California.
Southeast
State Department of Environmental Quality laboratories in Florida, Georgia, and North Carolina face procurement constraints favoring operational expenditure models over capital-intensive instrument ownership. The Southeast Coastal Plain aquifer vulnerability to saltwater intrusion drives specialized testing protocols for chloride and conductivity parameters. Atlanta and Charlotte emerging as secondary laboratory network hubs as multi-state providers establish regional satellite facilities.
Pacific Northwest
Washington and Oregon drinking water programs emphasize source water protection monitoring under state-specific Watershed Management Act frameworks. The Columbia River basin industrial discharge permitting regime requires continuous metals monitoring at pulp and paper facilities. Seattle and Portland municipal utilities lead adoption of biosensor preliminary screening technologies for distribution system monitoring.
US Environmental Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue field-deployable screening technologies and digital chain-of-custody platforms. The vendor base stratifies across three tiers: multi-national laboratory networks with federal contract vehicles, regional specialists with state-level Department of Environmental Quality accreditation, and instrument manufacturers supplying analytical platforms to both categories. Three archetypes dominate competitive positioning: certification-heavy compliance laboratories, technology-forward field screening developers, and integrated instrumentation-service hybrids. Consolidation accelerates through acquisition of state-certified facilities; vertical integration into sample collection logistics represents the second dominant vector.
Among multi-national laboratory networks, Eurofins Scientific, SGS, and Thermo Fisher Scientific exemplify distinct strategic archetypes. Eurofins Scientific anchors federal and state contract workflows through nationwide laboratory density. SGS occupies specialized positioning around air toxics and stack emissions protocols. Thermo Fisher Scientific dominates analytical instrumentation supply chains serving both third-party laboratories and direct government purchasers. Each represents a viable competitive model without implying exclusive market control.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS |
| Bureau Veritas |
| Intertek Group |
| Agilent Technologies |
| Thermo Fisher Scientific |
| Pace Analytical Services |
| EMSL Analytical |
| Microbac Laboratories |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between EPA Safe Drinking Water Act-certified laboratories and rapid-screening field operations manifests in divergent pricing architectures and procurement channel structures across the US environmental testing landscape. Premium-tier providers commanding federal contract vehicles capture multi-year municipal utility commitments at 40-60% markups over non-certified competitors, while supply chain configuration favors instrument manufacturers with captive service networks over independent distributors.
Pricing Analysis
Distributor margins on analytical instrumentation compress as direct-to-OEM channels handle hyperscale federal and state laboratory procurement. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified full-service laboratories from state-accredited regional specialists and rapid-screening field kit providers. Price differentiation hinges on certification tier—Safe Drinking Water Act approval commands substantial premiums—and after-sales service bundling. Pricing pressure stems from independent service organizations capturing calibration and repair revenue previously retained by Thermo Fisher and Agilent. State Department of Environmental Quality laboratories exhibit highest price sensitivity due to budget constraints favoring operational expenditure models.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from federal EPA contracts and state Department of Environmental Quality laboratory networks. Geographic supply concentration centers on Germany, Japan, and the United States for high-resolution mass spectrometry systems. Raw material dependencies include helium for chromatography operations, rare earth elements for magnet assemblies, and specialized optical components for detection systems. Supply chain risk rests on single-source vulnerability for helium imports constraining analytical throughput. Distribution runs through manufacturer-direct sales for large installations and specialized distributors for consumables and field equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in certified laboratory networks as PFAS detection mandates drive premium-tier demand and biosensor miniaturization creates cost-down pathways for field screening workflows.
For Market Incumbents: Hedge against helium supply volatility by securing long-term noble gas contracts and investing in hydrogen carrier gas conversion capabilities for chromatography systems. Acquire state-certified regional laboratories in Michigan, Ohio, and Wisconsin to consolidate CERCLA-driven remediation project pipelines. Certification bottlenecks represent the primary defensive moat against emerging field-screening substitutes. For New Entrants and Emerging Players: The price-point gap between premium-certified laboratories and economy field-testing kits opens white-space targets in rapid-turnaround preliminary screening for municipal utilities. Target the Texas Permian Basin oilfield chemistry segment where produced water reuse regulations outpace established laboratory capacity. Pursue digital chain-of-custody platform partnerships with environmental consultants to bypass 12-18 month state accreditation timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where state-level Department of Environmental Quality accreditation creates sticky customer relationships and high switching costs for certified facilities. Long-term viability favors multi-state laboratory networks with federal contract vehicles over single-site regional operators. Watch EPA emerging contaminant candidate list rulings as inflection indicators for capability investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of State-Certified Facilities | EPA Safe Drinking Water Act accreditation transfers defensible data capabilities and municipal utility contracts. |
| Helium Supply Diversification | Long-term noble gas contracts with Qatar and Algeria reduce chromatography downtime risks. |
| Biosensor Platform Development | Real-time field screening compresses sample transport burdens for emergency response protocols. |
| Digital Chain-of-Custody Integration | Blockchain-secured sample tracking accelerates regulatory audit readiness for third-party laboratories. |
| Permian Basin Service Expansion | Texas Commission on Environmental Quality oilfield chemistry certification captures produced water reuse demand. |
Research Methodology
Multiple input streams — primary interviews with laboratory directors and state environmental regulators, secondary validation through EPA enforcement databases and instrument manufacturer SEC filings, and trade data on helium imports and analytical equipment shipments — were reconciled through bottom-up and top-down triangulation. Stakeholder roles included municipal utility water quality managers, commercial laboratory operations directors, state Department of Environmental Quality certification officers, environmental consultant project managers, and analytical instrument service technicians. Secondary sources encompassed EPA Safe Drinking Water Act compliance databases, Unregulated Contaminant Monitoring Rule implementation reports, customs records for chromatography and mass spectrometry equipment, and state-level procurement contract disclosures.
Historical volume trends were cross-referenced against expert panel assessments of PFAS regulatory expansion timelines and biosensor technology adoption curves. Segmentation dimensions modeled across the analysis window included testing type, end user category, application purpose, and technology platform, with additional granularity on certification tier and geographic regulatory stringency. CAGRs were derived through regression analysis of historical contract value data and scenario-weighted projections of EPA rulemaking schedules. Industry-specific forecast inputs incorporated helium supply elasticity estimates and state accreditation pipeline durations.
Caveats apply where EPA method update frequencies, helium import policy shifts, or biosensor regulatory acceptance thresholds could materially shift the outlook. Forecasts reflect assumptions on sustained Safe Drinking Water Act amendment momentum and stable state-level enforcement budgets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Global Water Quality Monitoring Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market