
 Air Quality Monitoring Equipment Market | 2026-2036
Air Quality Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Air Quality Monitoring Equipment Market Analysis
China is fragmenting its air quality monitoring equipment manufacturing base across Shenzhen, Shanghai, and Chengdu industrial corridors. Thermo Fisher Scientific leverages its optical sensor R&D intensity to sustain premium positioning in laboratory-grade systems. Honeywell International anchors North American demand through deep channel control in building automation integration. Siemens AG competes on manufacturing scale across European utility and smart city deployments.
Air quality monitoring equipment comprises sensor arrays, data loggers, and telemetry systems engineered to detect particulate matter, nitrogen oxides, sulfur dioxide, ozone, and volatile organic compounds at detection thresholds reaching parts per billion. These systems serve industrial compliance, public health surveillance, and environmental research by generating continuous, auditable emissions data streams. Fixed monitors dominate capital allocation among government agencies due to networked regulatory reporting mandates, while portable monitors represent the fastest-expanding category as industrial facilities adopt spot-check protocols for fugitive emission detection. Electrochemical sensors retain cost advantages in baseline pollution monitoring, though laser sensors capture margin pools in research-grade applications requiring single-particle resolution.
The EPA enforces National Ambient Air Quality Standards that dictate minimum detection capabilities and calibration frequencies for federal reference methods. China's MEE administers GB standards for ambient air quality and emission monitoring, while the EU's F-Gas Regulation and Industrial Emissions Directive shape product specifications across European member states. Stakeholders must weigh sensor interoperability against jurisdiction-specific certification requirements when configuring multi-country deployment strategies.
Market Dynamics
Regulatory ratcheting across industrialized economies is compressing equipment replacement cycles as ambient monitoring mandates expand beyond stack emissions to fence-line and community surveillance networks. The EPA's updated National Ambient Air Quality Standards and China's MEE enforcement protocols are forcing capital redeployment toward continuous monitoring infrastructure.
Growth Catalysts
- EPA NAAQS stringency:The EPA's tightened particulate matter thresholds are compelling municipal air quality agencies to upgrade from intermittent sampling to continuous reference-grade monitoring networks.
- Industrial fugitive emission protocols:Petrochemical and refining complexes are deploying portable optical gas imaging systems to satisfy leak detection and repair mandates under evolving state-level environmental enforcement.
- China's dual carbon monitoring infrastructure:Provincial environmental bureaus are mandating real-time emissions verification systems across steel, cement, and power generation corridors to track progress toward carbon neutrality targets.
Market Restraints
- Reference method certification delays:EPA equivalency determinations for emerging sensor technologies create 18-36 month product launch timelines that freeze commercialization of lower-cost alternatives.
- Optical component supply concentration:Laser diode and photodetector fabrication concentrates in Japanese and German specialty component suppliers, exposing monitor manufacturers to allocation constraints.
- Electrochemical sensor drift limitations:Baseline pollution monitors require 6-12 month calibration intervals that elevate total cost of ownership versus solid-state alternatives in remote deployment scenarios.
Strategic Opportunities
- Smart city integration contracts:Municipal governments in India are bundling air quality nodes with traffic management and public safety infrastructure under unified data platform procurements.
- EU F-Gas Regulation compliance services:Refrigeration and semiconductor facilities require specialized perfluorocarbon monitoring systems to satisfy reporting mandates under the updated fluorinated gas phase-down schedule.
- AI-augmented predictive maintenance:Machine learning algorithms applied to sensor drift patterns are enabling condition-based calibration scheduling that reduces field service costs for distributed monitor networks.
Industry Challenges
- Multi-jurisdiction certification complexity:Equipment vendors must maintain parallel EPA, EU F-Gas, and GB standard compliance documentation that fragments engineering resources across non-harmonized test protocols.
- Field technician specialization gaps:Optical spectroscopy and laser-based detection systems require photonics expertise that conflicts with the electrochemical sensor maintenance skill base of incumbent environmental service contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Quality Monitoring Equipment Market |
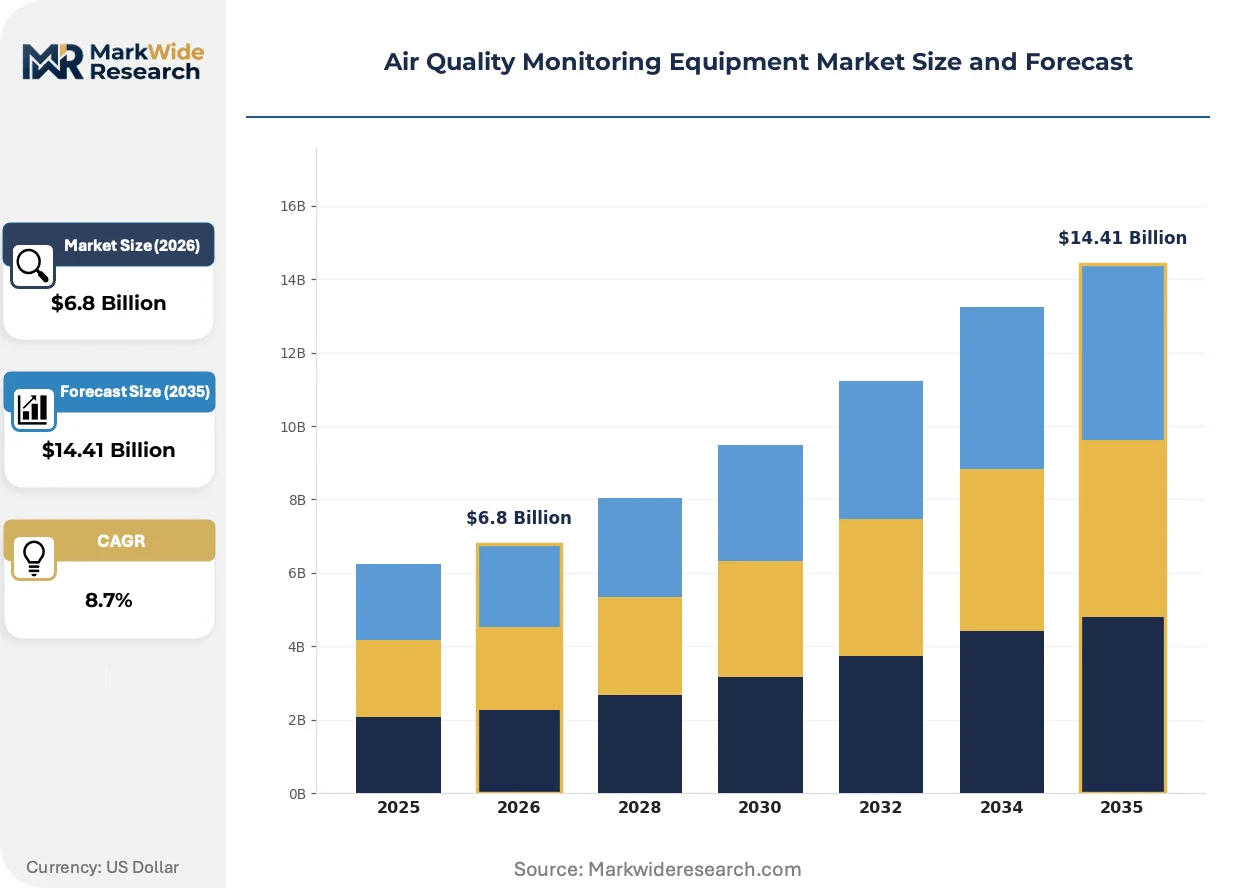
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Fixed Monitors, Indoor Systems, Outdoor Systems Technology: Electrochemical Sensors, Optical Sensors, Infrared Sensors, Laser Sensors End User: Government Agencies, Residential Users, Industrial Facilities, Environmental NGOs Application: Pollution Monitoring, Health Safety, HVAC Systems, Research Studies |
| Companies Covered | Thermo Fisher Scientific Inc., Honeywell International Inc., Siemens AG, TSI Incorporated, Aeroqual, Horiba Ltd., Emerson Electric Co., Teledyne Technologies Inc., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Quality Monitoring Equipment Market Emerging Trajectories
Sensor miniaturization and edge computing integration are collapsing the cost-performance frontier for distributed monitoring networks. These developments are enabling deployment models that bypass centralized laboratory analysis entirely.
Tunable diode laser absorption spectroscopy is achieving single-particle resolution for particulate matter characterization at one-tenth the footprint of beta attenuation reference methods. Research institutions and regulatory agencies are piloting these systems for source apportionment studies. Solid-state photonics is rendering obsolete the mechanical filter-based sampling infrastructure that has dominated federal reference monitoring for three decades.
China's MEE is accelerating GB standard harmonization with ISO 17025 calibration traceability requirements for continuous emissions monitoring systems. This regulatory convergence is pressuring domestic equipment manufacturers to abandon proprietary data protocols. The industrial stack monitoring segment is responding by consolidating supplier relationships toward vendors with dual EPA-GB certification capabilities.
Facility operators are unbundling hardware procurement from data validation services, creating standalone markets for third-party quality assurance contractors. Environmental consultancies are capturing recurring revenue streams through remote calibration management and regulatory reporting submission. This service disaggregation is most advanced in the Texas and Louisiana petrochemical corridor where specialized emissions accounting firms have displaced original equipment manufacturer service contracts.
Air Quality Monitoring Equipment Market Segmentation
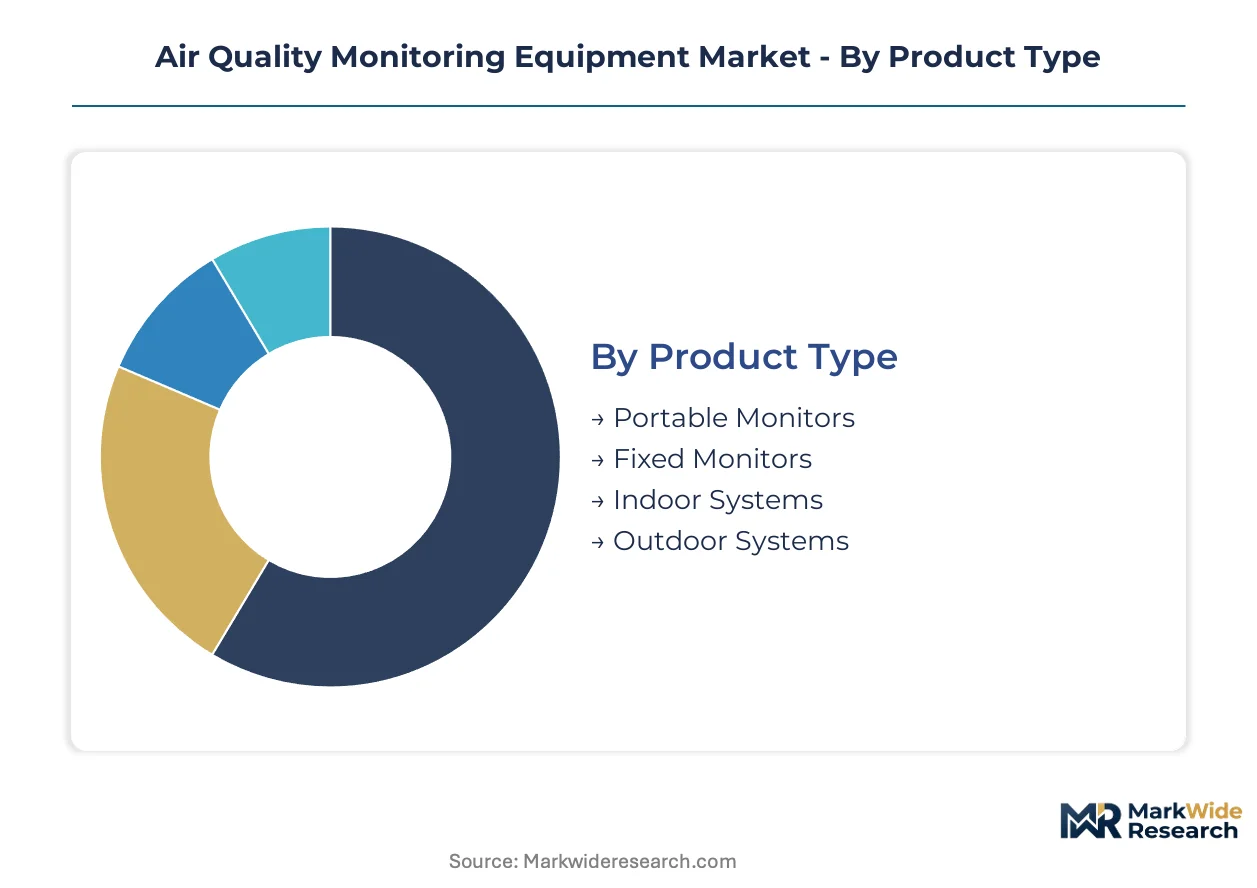
Segmentation in air quality monitoring equipment reveals divergent service intensity requirements across deployment contexts. Fixed industrial installations demand continuous calibration contracts, while portable units shift margin pools toward spot-validation services.
Product Type:
After-sales service intensity varies dramatically across installation permanence, with fixed systems locking vendors into decade-long maintenance relationships and portable units generating episodic recalibration revenue.
- Fixed Monitors:Permanent installations integrate sensor arrays, data loggers, and telemetry infrastructure for continuous regulatory reporting. Municipal agencies in China and industrial fence-line networks in the US Gulf Coast anchor replacement demand as EPA NAAQS stringency tightens detection thresholds.
- Portable Monitors:Handheld and transportable units enable spot-check protocols for fugitive emission detection and leak repair verification. Petrochemical operators in Texas and Louisiana are expanding fleet procurement to satisfy state-level LDAR mandates.
- Indoor Systems:Building-integrated sensors for commercial HVAC and residential environments prioritize low-drift solid-state technologies.
- Outdoor Systems:Weather-hardened enclosures with heated sample lines serve urban air quality networks and roadside monitoring stations.
Fixed Monitors holds the largest share; momentum sits with Portable Monitors.
Technology:
Cost tiers separate mature electrochemical platforms from research-grade photonics, with laser systems commanding premium positioning through single-particle resolution capabilities.
- Electrochemical Sensors:Gas-specific electrodes generate current proportional to target analyte concentration, dominating baseline pollution monitoring for NOx, SO2, and CO detection. Six-to-twelve month calibration intervals elevate total cost of ownership in remote deployments across Indian smart city networks.
- Laser Sensors:Tunable diode laser absorption spectroscopy achieves particulate matter characterization at one-tenth the footprint of beta attenuation methods. Research institutions in Germany and Japan are piloting these systems for source apportionment studies requiring single-particle resolution.
- Optical Sensors:Light-scattering and fluorescence-based detection serve mid-tier applications in indoor air quality and community monitoring networks.
- Infrared Sensors:Non-dispersive infrared absorption targets CO2 and hydrocarbon monitoring in industrial process control and building ventilation management.
Electrochemical Sensors retains volume leadership; Laser Sensors is climbing the fastest.
End User:
Procurement authority concentrates in government channels, though industrial self-monitoring is eroding agency dominance as liability frameworks tighten.
- Government Agencies:Federal, state, and municipal environmental authorities operate reference-grade networks for regulatory enforcement and public health surveillance. China's provincial environmental bureaus are mandating real-time emissions verification across steel, cement, and power generation corridors.
- Industrial Facilities:Petrochemical, refining, and manufacturing operators deploy monitoring infrastructure for compliance documentation and community relations management. Fence-line monitoring requirements under EPA enforcement protocols are accelerating capital redeployment in the US Gulf Coast.
- Environmental NGOs:Advocacy organizations deploy low-cost sensor networks for community science initiatives and environmental justice documentation.
- Residential Users:Consumer-grade indoor monitors serve health-conscious households and asthma management applications.
Government Agencies holds the largest share; momentum sits with Industrial Facilities.
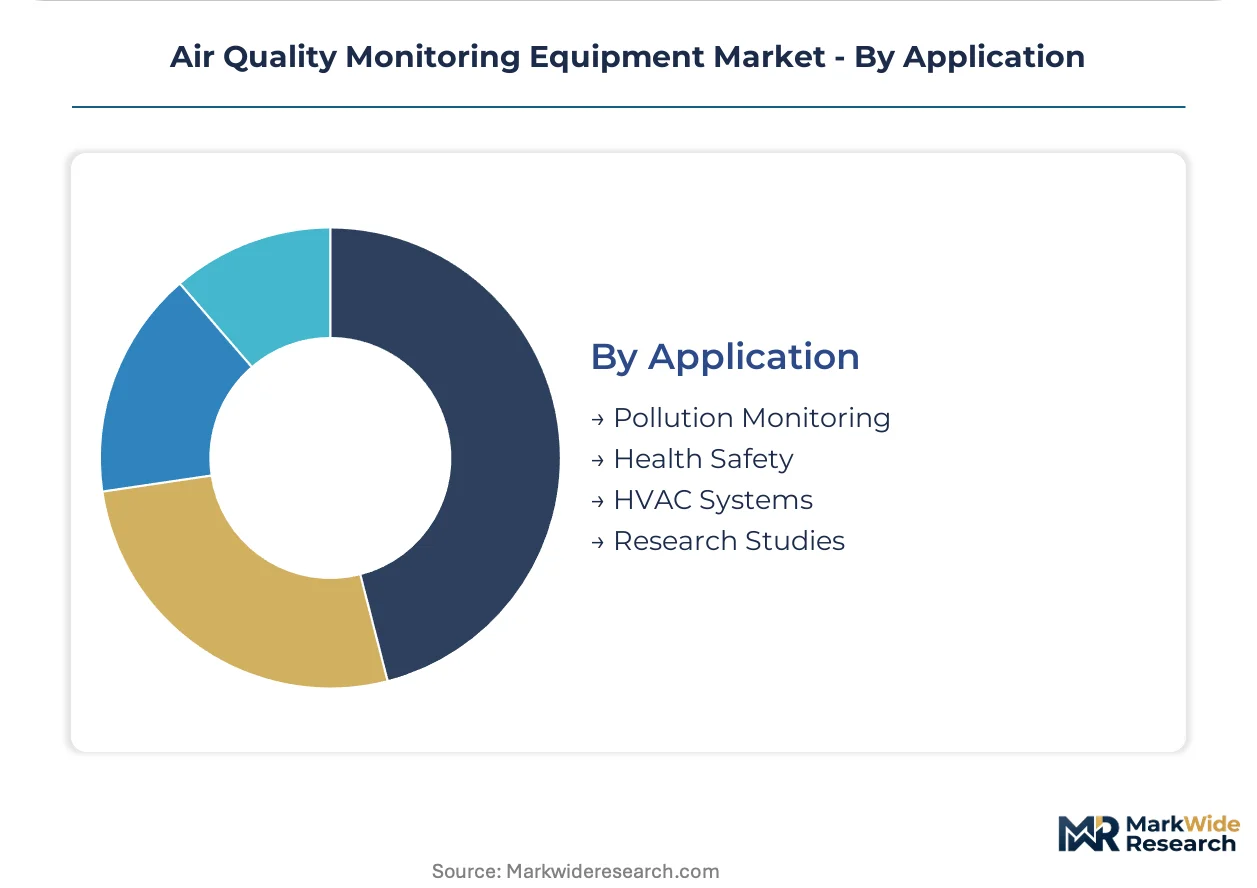
Application:
Regulatory mandate intensity separates pollution monitoring from discretionary health safety deployments, with HVAC integration emerging as a bundled procurement channel.
- Pollution Monitoring:Regulatory compliance applications require certified detection methods with traceable calibration documentation. EPA equivalency determinations and China's GB standard harmonization with ISO 17025 are consolidating supplier relationships toward dual-certified vendors.
- Health Safety:Occupational exposure monitoring and indoor air quality management serve workplace compliance and residential wellness applications.
- HVAC Systems:Building automation integration enables demand-controlled ventilation based on real-time CO2 and VOC concentrations.
- Research Studies:Academic and institutional applications require highest-tier precision for source apportionment, epidemiological linkage, and atmospheric chemistry investigations.
Pollution Monitoring holds the largest share; momentum sits with HVAC Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication for precision optical sensors concentrates in Japanese and German specialty suppliers, while system assembly and deployment scale clusters in China and the United States. This geographic split shapes procurement patterns and certification requirements across end markets.
United States
Municipal air quality agencies in California and Texas are upgrading from intermittent sampling to continuous reference-grade networks under EPA NAAQS particulate matter thresholds. The EPA's equivalency determination protocols create 18-36 month product launch timelines that freeze commercialization of lower-cost alternatives. Houston's petrochemical corridor anchors fence-line monitoring deployment as operators satisfy leak detection and repair mandates.
China
Provincial environmental bureaus across Hebei and Jiangsu provinces mandate real-time emissions verification across steel, cement, and power generation corridors to track dual carbon progress. The MEE's GB standard harmonization with ISO 17025 calibration traceability requirements pressures domestic manufacturers to abandon proprietary data protocols. Shenzhen and Shanghai industrial corridors fragment equipment manufacturing capacity.
Germany
Research institutions in Bavaria and Baden-Württemberg pilot tunable diode laser absorption spectroscopy systems for source apportionment studies requiring single-particle resolution. The EU F-Gas Regulation and Industrial Emissions Directive shape product specifications for refrigeration and semiconductor facility monitoring. Stuttgart's automotive manufacturing cluster drives demand for fence-line and community surveillance networks.
India
Municipal governments in Maharashtra and Karnataka bundle air quality nodes with traffic management infrastructure under unified data platform procurements. Six-to-twelve month calibration intervals for electrochemical sensors elevate total cost of ownership in remote smart city deployments. Mumbai and Bangalore metropolitan regions concentrate pilot programs for distributed monitoring networks.
Japan
Laser diode and photodetector fabrication concentrates in Tokyo and Osaka specialty component suppliers, exposing monitor manufacturers to allocation constraints. METI standards influence regional procurement specifications for industrial emissions verification. Nagoya's manufacturing corridor integrates monitoring systems into process control infrastructure.
Air Quality Monitoring Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in optical and electrochemical sensor supply. The market structures around three tiers: multinational conglomerates with building automation channels, mid-scale instrumentation houses with laboratory-grade positioning, and regional fabricators serving price-sensitive government procurement. Strategic moves concentrate on dual-certification capability building for EPA-GB compliance and service unbundling to capture recurring calibration revenue.
Among diversified technology conglomerates, Thermo Fisher Scientific Inc. and Honeywell International Inc. occupy positions spanning laboratory-grade systems through building automation integration. Siemens AG anchors European utility and smart city deployment scale. These three exemplify the certification-heavy, service-integrated archetype that dominates municipal and industrial procurement channels requiring multi-jurisdiction compliance documentation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Honeywell International Inc. |
| Siemens AG |
| TSI Incorporated |
| Aeroqual |
| Horiba Ltd. |
| Emerson Electric Co. |
| Teledyne Technologies Inc. |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Japanese laser diode and photodetector fabrication determines both pricing tier spreads and supply chain shape, as EPA equivalency determination timelines lock premium-grade vendors into 18-36 month certification cycles while standard-tier competitors absorb cost compression from electrochemical sensor commoditization.
Pricing Analysis
EPA NAAQS equivalency protocols dictate the pricing tier structure across the Air Quality Monitoring Equipment Market, separating reference-grade laser systems with dual EPA-GB certification from standard electrochemical platforms and economy-tier indoor sensors lacking regulatory traceability. Price differentiation hinges on calibration documentation rigor and after-sales service bundling, with municipal procurement channels least sensitive due to federal funding availability and residential segments most vulnerable to cost compression. Pricing pressure intensifies in standard-tier portable monitors as Chinese manufacturers expand export capacity, while premium laboratory-grade systems defend margins through optical sensor R&D intensity and replacement part exclusivity.
Supply Chain Analysis
Upstream photonics componentry draws from Japanese and German specialty suppliers for laser diodes and precision photodetectors, while electrochemical sensor electrodes and data logger assembly concentrate in Chinese and South Korean manufacturing corridors. Raw material dependencies span rare-earth doped glass for optical fibers, noble metal catalysts for gas-specific electrodes, and semiconductor-grade silicon for solid-state detectors. Single-source vulnerability in tunable diode laser absorption spectroscopy modules creates allocation risk during demand surges. Distribution runs through building automation integrators in North America, provincial environmental bureau tenders in China, and third-party environmental consultancies in the US Gulf Coast petrochemical corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Air Quality Monitoring Equipment Market sits in early-cycle expansion as fence-line monitoring mandates extend beyond stack emissions to community surveillance networks, creating installation base growth that outpaces replacement demand.
For Market Incumbents: Insulate service revenue streams by embedding AI-augmented predictive maintenance into long-term calibration contracts, countering the threat of third-party quality assurance contractors displacing OEM service relationships in Texas and Louisiana. Prioritize dual EPA-GB certification investment to capture consolidation in China's industrial stack monitoring segment as MEE harmonization pressures domestic manufacturers toward ISO 17025 traceability. For New Entrants and Emerging Players: India's municipal smart city bundling presents the most penetrable procurement channel, where air quality nodes integrated with traffic management infrastructure bypass reference-grade certification barriers that freeze commercialization timelines in developed markets. Target spot-validation services for portable monitor fleets as petrochemical operators unbundle hardware from data validation, using remote calibration management software as the go-to-market wedge. For Investors and Strategic Acquirers: Photonics-integrated mid-scale instrumentation houses with laboratory-grade positioning offer the strongest acquisition target archetype, as their optical sensor R&D intensity commands premium positioning while remaining digestible for conglomerate platform integration. Long-term viability across the analysis window rests on regulatory ratcheting durability rather than cyclical industrial capex. Monitor EPA equivalency determination backlog clearance rates as the inflection signal for lower-cost sensor technology commercialization windows.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Captures consolidation in China's industrial stack monitoring as MEE harmonization accelerates. |
| AI-Augmented Predictive Maintenance | Enables condition-based calibration scheduling that reduces field service costs for distributed networks. |
| Smart City Integration Partnerships | Bundles air quality nodes with traffic management infrastructure under unified data platform procurements in India. |
| Service Unbundling | Creates standalone markets for third-party quality assurance contractors in Texas and Louisiana petrochemical corridors. |
| Optical Sensor R&D Intensification | Sustains premium positioning in laboratory-grade systems through single-particle resolution capabilities. |
Methodological Framework
Desk research of EPA equivalency determination databases, China's MEE GB standard documentation, EU F-Gas Regulation filings, and ISO 17025 calibration traceability protocols preceded structured interviews with municipal air quality agency procurement officers, industrial environmental compliance managers, photonics component suppliers, and third-party environmental consultancy operators. Secondary validation drew from customs trade data for sensor component flows, SEC 10-K filings of listed instrumentation houses, and provincial environmental bureau tender announcements. Bottom-up unit deployment estimates triangulated against top-down regulatory mandate intensity scoring.
Assumptions held fixed include EPA NAAQS particulate matter threshold stringency, China's dual carbon monitoring infrastructure rollout pace, and EU F-Gas Regulation phase-down schedules, while sensor technology cost curves and certification timeline variability were modeled as scenario inputs. Segmentation dimensions spanned product permanence, detection technology, end-user procurement authority, and application regulatory mandate intensity. CAGRs were derived from regression against historical replacement cycle compression and regulatory enforcement staffing expansion. Industry-specific forecast inputs included optical component supply allocation constraints and field technician photonics specialization gaps.
Practitioners should monitor EPA equivalency determination backlog fluctuations and Chinese provincial environmental bureau budget allocation announcements for early signals of technology commercialization window shifts. Forecasts reflect these documented assumptions regarding regulatory ratcheting durability and supply concentration persistence. Cross-checking against IEA air quality investment tracking and national emissions inventory revision schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Environmental Monitoring (Surface Water) Market
Environmental Monitoring
Asia-Pacific Food and Environment Manual Testing Market
Environmental Monitoring
Water Quality Monitoring Systems Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Eco Funnel Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Global Weather Forecasting Services Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Water Quality Analyzer Market