
 Environment Testing Services Market | 2026-2036
Environment Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Environment Testing Services Market Analysis
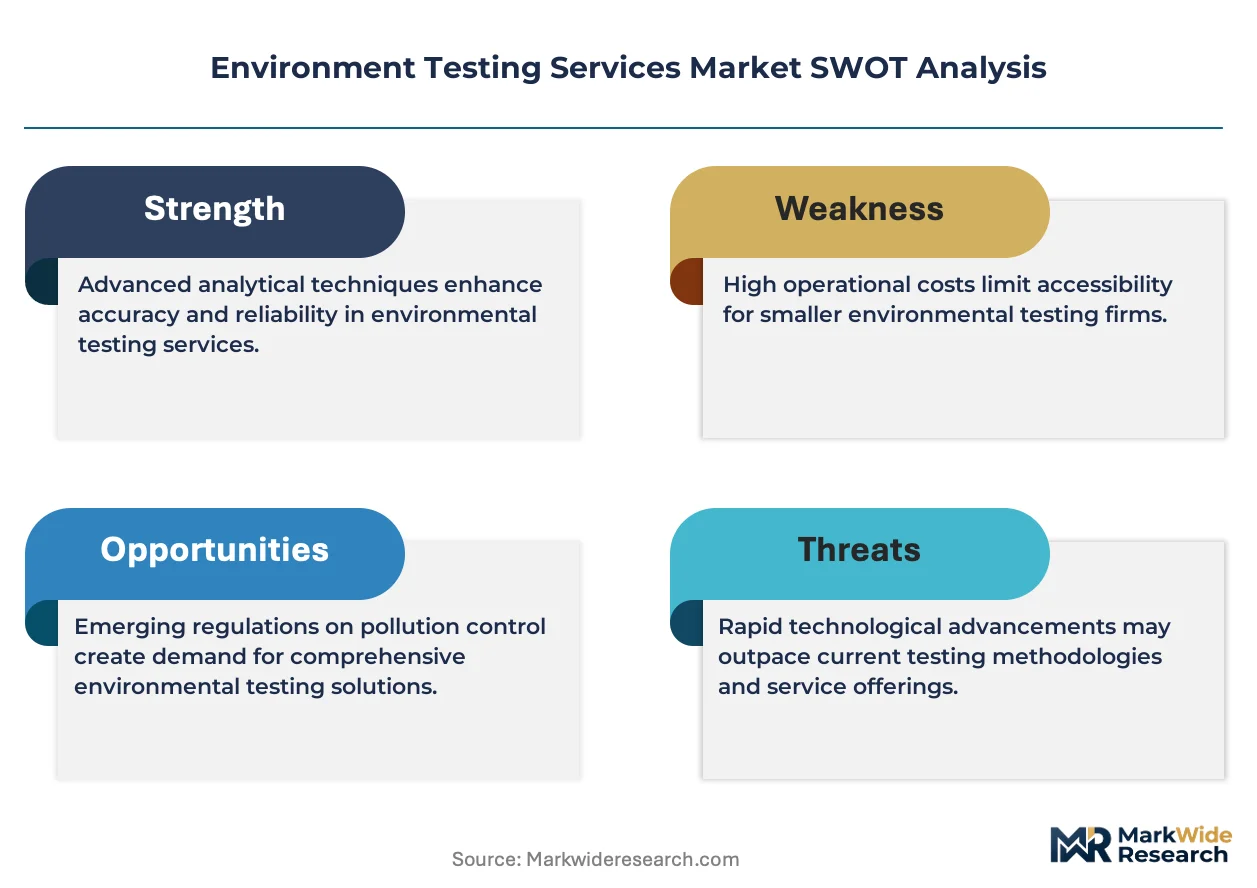
ISO 17025 accreditation is bifurcating the competitive landscape into certified laboratories and uncertified regional operators. SGS leverages its multi-country laboratory network to sustain dominance in European industrial hygiene testing. Bureau Veritas anchors its position through in-house production of specialized sampling equipment for contaminated site assessments. Eurofins Scientific differentiates via R&D intensity in PFAS analytical methods.
Environment testing services encompass the systematic collection, analysis, and interpretation of physical, chemical, and biological parameters from environmental media, typically employing gas chromatography-mass spectrometry detection limits at parts-per-trillion sensitivity to satisfy regulatory thresholds. These services enable industrial permit holders, property developers, and government agencies to verify compliance with health-based exposure limits and manage liability from legacy contamination. Water quality testing leads service revenue due to persistent infrastructure investment in municipal monitoring networks, while soil testing represents the fastest-growing category as brownfield redevelopment accelerates across former manufacturing zones. Laboratory analysis occupies the dominant technology position, though remote sensing is gaining share where drone-mounted spectrometers reduce field mobilization costs for large-area pollution surveys.
The EPA enforces Clean Water Act and Safe Drinking Water Act standards that mandate third-party verification, while REACH obliges EU manufacturers to register substance properties through accredited testing protocols. India's CPCB aligns state pollution control boards with BIS water quality norms, expanding the addressable market for cross-border certification bodies. Stakeholders must decide whether to build captive analytical capacity or outsource to platforms integrating field testing with real-time data analytics dashboards.
Market Dynamics
PFAS detection mandates are compressing laboratory turnaround times from weeks to days, forcing capital redeployment toward high-resolution mass spectrometry and automated sample prep robotics.
Growth Catalysts
- REACH substance evaluation:ECHA's 2024-2027 screening program obliges chemical manufacturers across Germany, France, and the Netherlands to commission expanded toxicity testing for legacy compounds.
- Brownfield redevelopment:Former industrial zones in the UK and Belgium now require pre-construction soil screening, pulling environmental consultancies into multi-year site monitoring contracts.
- Drone-mounted spectroscopy:Remote sensing platforms cut mobilization costs for large-area contamination surveys, expanding serviceable market segments to agricultural runoff monitoring.
Market Restraints
- Helium supply volatility:Gas chromatography-mass spectrometry operations depend on helium carrier gas, with price spikes from Qatar and US federal reserve drawdowns squeezing laboratory margins.
- Accreditation concentration:ISO 17025 certification capacity clusters in Germany, the UK, and Switzerland, creating bottlenecks for laboratories in peripheral EU markets seeking market access.
- Technical detection floors:Parts-per-quadrillion PFAS quantification remains beyond routine laboratory capability, leaving regulatory thresholds unenforceable in practice.
Strategic Opportunities
- Poland industrial corridor:Manufacturing FDI in Lower Silesia outpaces local testing infrastructure, creating first-mover advantage for accredited laboratories establishing regional hubs.
- Real-time data platforms:Integration of field sensors with cloud analytics dashboards enables subscription-based monitoring contracts, displacing transactional sample testing.
- EU Green Deal taxonomy:Corporate sustainability reporting obligations extend environmental due diligence to private equity and real estate funds previously outside regulatory scope.
Industry Challenges
- PFAS analytical chemist scarcity:Method development for novel fluorinated compounds requires specialized expertise concentrated in fewer than two dozen European laboratories.
- Legacy LIMS integration:Laboratory information management systems from the 2000s resist API connectivity with modern field data capture tools, fragmenting audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environment Testing Services Market |
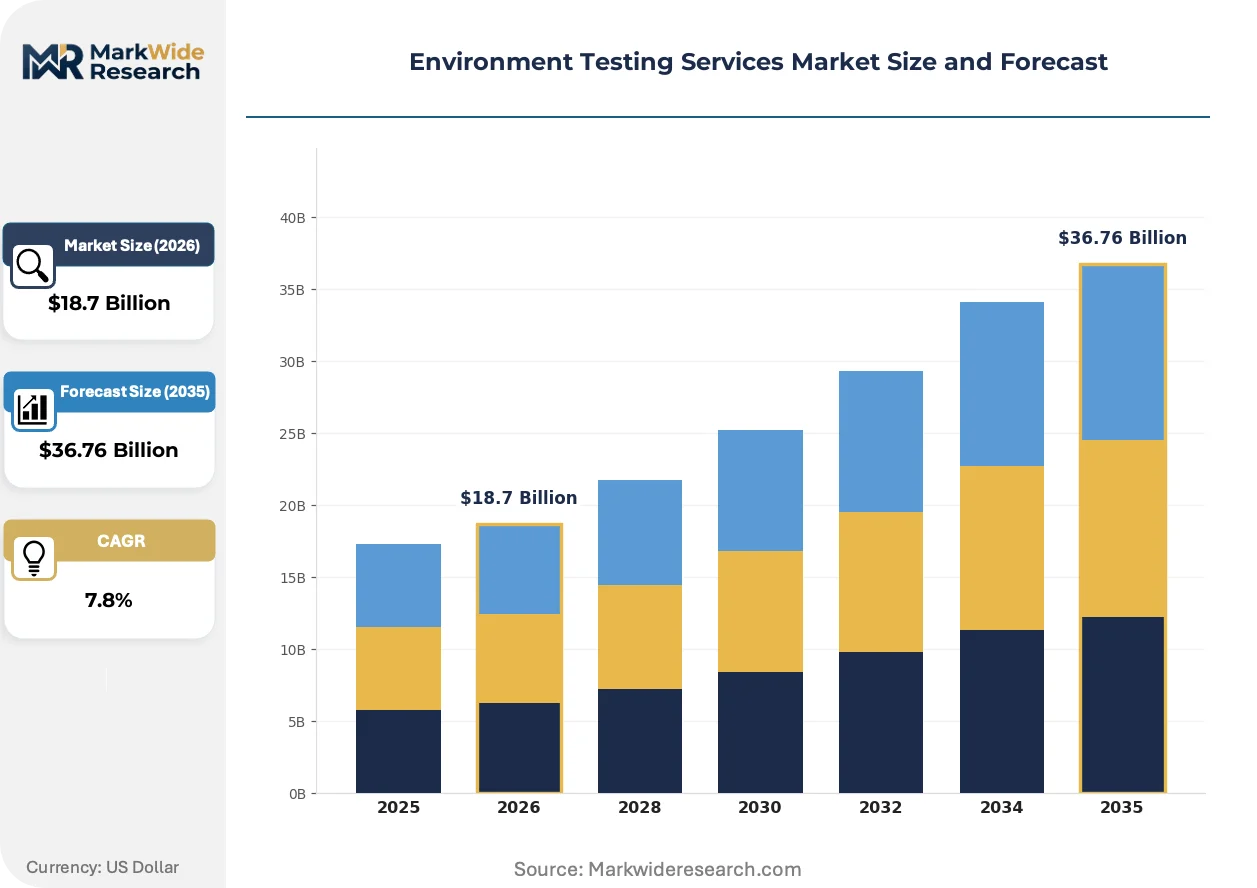
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Soil Testing, Air Quality Testing, Water Quality Testing, Industrial Hygiene End User: Manufacturing, Construction, Agriculture, Government Application: Pollution Control, Compliance Monitoring, Risk Assessment, Remediation Technology: Laboratory Analysis, Field Testing, Remote Sensing, Data Analytics |
| Companies Covered | SGS, Bureau Veritas, Eurofins Scientific, Intertek, TÜV SÜD, ALS Limited, Mérieux NutriSciences, Microbac Laboratories, Element Materials Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environment Testing Services Market Emerging Trajectories
Digital field instrumentation and automated wet chemistry are compressing the traditional laboratory value chain, unbundling sample collection from analytical interpretation and enabling new service delivery models.
Direct analysis in real time mass spectrometry (DART-MS) is supplanting solvent extraction protocols for rapid soil screening. German industrial hygiene contractors deploy portable units for same-day contamination mapping at decommissioned chemical plants. This capability collapses the decision timeline for property transactions, shifting revenue from central laboratories to field-equipped service integrators.
ECHA's restriction proposal for per- and polyfluoroalkyl substances tightens emission limits across the entire substance class. Textile and paper coating manufacturers in northern Italy and Catalonia face mandatory quarterly effluent verification. Testing volumes concentrate in laboratories with pre-validated PFAS method suites, accelerating accreditation-driven vendor consolidation.
Buyers now unbundle fixed-scope monitoring contracts into modular service components. Municipal water utilities in Denmark and Sweden procure sampling, analysis, and regulatory filing as separate line items through digital procurement platforms. This disaggregation pressures full-service laboratories to defend margin through ISO 17025 brand premium rather than bundled convenience.
Environment Testing Services Market Segmentation
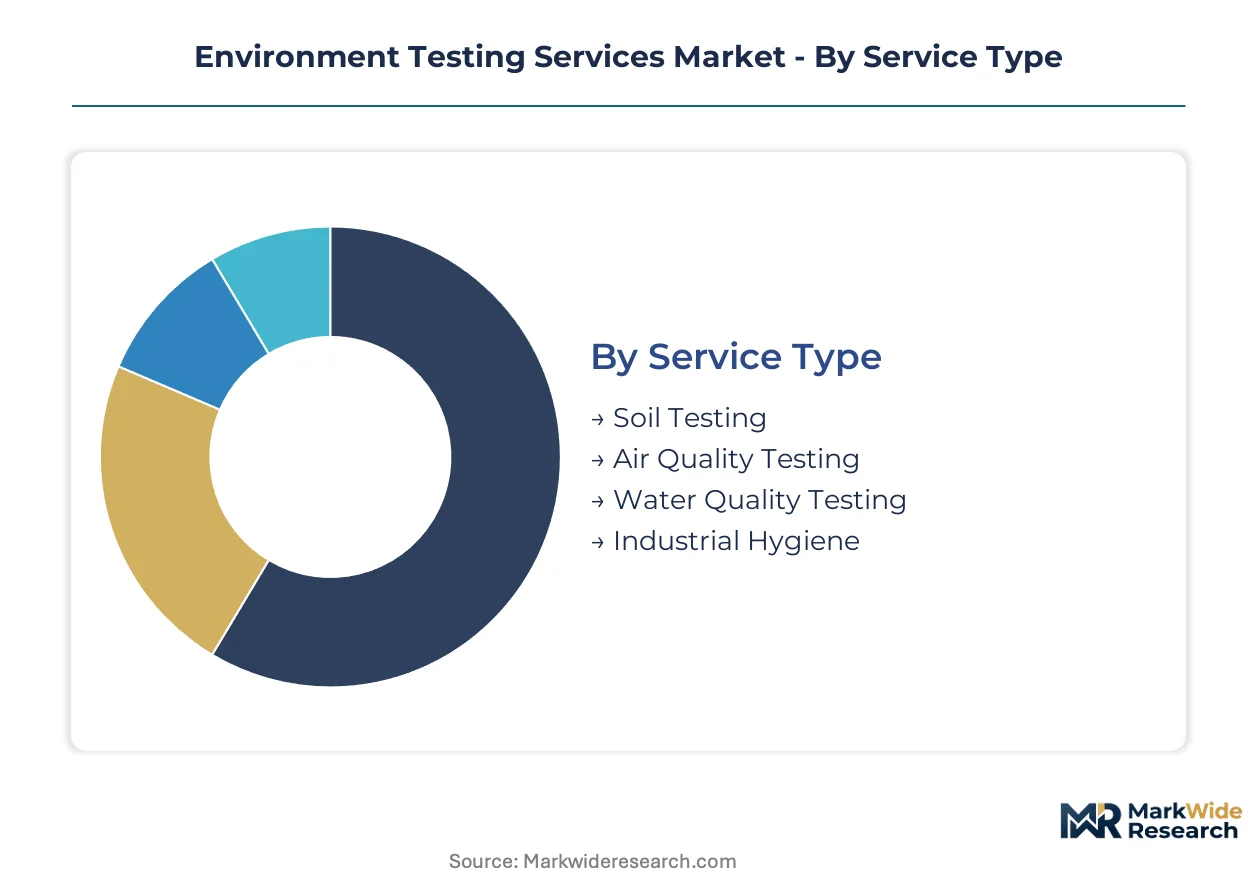
Environmental testing services fragment across service delivery models, end-use industries, and analytical technologies. Each segment carries distinct margin profiles, accreditation requirements, and geographic concentration patterns that reshape competitive positioning.
Service Type:
Domestic regulatory enforcement drives soil and air testing demand in Germany, France, and the UK, while water quality contracts increasingly cross borders through multinational laboratory networks.
- Water Quality Testing:Municipal monitoring networks deploy automated samplers at treatment plant intakes and distribution endpoints. Denmark and Sweden utilities now unbundle sampling, analysis, and regulatory filing into separate procurement lots, compressing margins for bundled service providers.
- Soil Testing:Brownfield redevelopment across former manufacturing zones in Belgium and the UK requires pre-construction screening and multi-year monitoring. DART-MS portable units enable same-day contamination mapping, collapsing decision timelines for property transactions.
- Air Quality Testing:Industrial facility permits mandate quarterly stack emission verification. German Rhine-Ruhr corridor factories drive concentrated demand for accredited stack testing contractors.
- Industrial Hygiene:Workplace exposure assessments for chemical manufacturers concentrate in ECHA-regulated substance evaluation programs across the Netherlands and northern Italy.
Water quality testing commands the established base. The steepest expansion runs through soil testing.
End User:
Cost tier differentiation separates high-frequency manufacturing contracts from episodic construction and agricultural engagements.
- Manufacturing:Chemical, textile, and paper coating producers face mandatory quarterly effluent verification under tightening PFAS emission limits. ECHA's screening program obliges expanded toxicity testing for legacy compounds.
- Construction:Property developers require pre-transaction due diligence and remediation verification. UK and Belgian brownfield projects pull environmental consultancies into extended site monitoring contracts.
- Government:Municipal utilities and pollution control boards procure compliance monitoring through framework agreements. India's CPCB alignment with BIS water quality norms expands addressable contracts for accredited bodies.
- Agriculture:Runoff monitoring and soil nutrient analysis concentrate in intensive farming regions. Drone-mounted spectroscopy reduces mobilization costs for large-area contamination surveys.
Manufacturing anchors volume concentration. Construction delivers the highest contract values per engagement.
Application:
Application maturity varies by regulatory enforcement intensity, with compliance monitoring representing the most standardized service delivery model.
- Compliance Monitoring:Permit holders verify continuous adherence to EPA Clean Water Act and Safe Drinking Water Act thresholds. Third-party verification mandates create recurring revenue streams for ISO 17025 laboratories.
- Pollution Control:Industrial operators implement source reduction and treatment optimization based on analytical feedback. Real-time sensor integration enables subscription-based monitoring contracts.
- Remediation:Contaminated site cleanup requires progress verification and closure documentation. Specialized sampling equipment production differentiates full-service contractors.
- Risk Assessment:Property transactions and corporate sustainability reporting drive due diligence testing. EU Green Deal taxonomy extends environmental obligations to private equity and real estate funds.
Compliance monitoring generates the recurring base. Pollution control is gaining share fastest through platform subscription models.
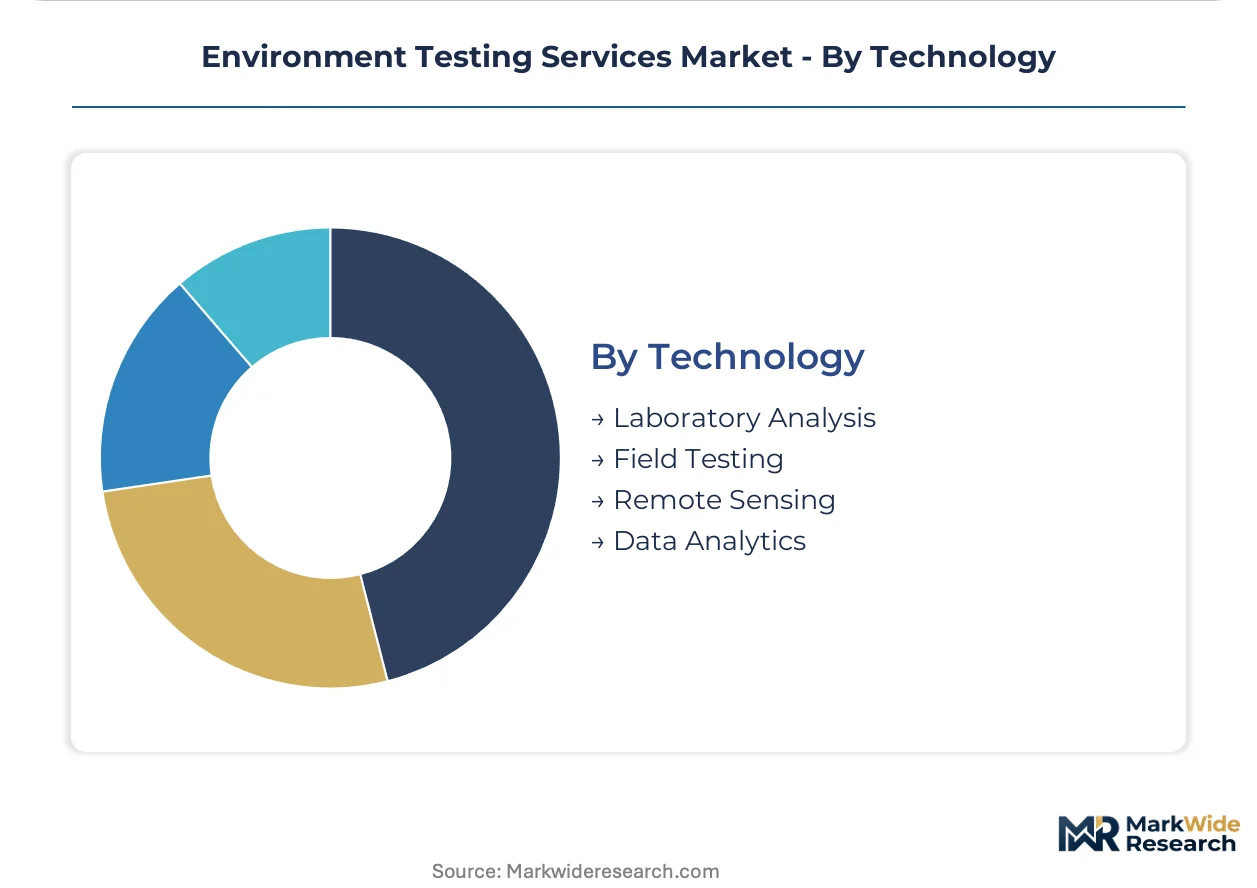
Technology:
Supply concentration clusters in automated wet chemistry and high-resolution mass spectrometry, while field testing fragments across regional equipment operators.
- Laboratory Analysis:Gas chromatography-mass spectrometry at parts-per-trillion sensitivity satisfies regulatory thresholds. Helium carrier gas dependency exposes operations to Qatar supply volatility and US federal reserve drawdowns.
- Field Testing:Portable DART-MS units and digital field instrumentation compress traditional value chains. German industrial hygiene contractors deploy rapid soil screening at decommissioned chemical plants.
- Remote Sensing:Drone-mounted spectrometers cut mobilization costs for agricultural runoff and large-area pollution surveys. Platforms expand serviceable market segments previously uneconomical for ground crews.
- Data Analytics:Cloud dashboards integrate field sensors with real-time visualization. Legacy LIMS integration challenges fragment audit trails for laboratories using 2000s-era systems.
Laboratory analysis retains the revenue base. Field testing is climbing the fastest as equipment portability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German laboratories export PFAS analytical services to northern Italian textile manufacturers facing ECHA-mandated quarterly effluent verification. This cross-border testing flow illustrates how regulatory stringency in one jurisdiction creates service demand in another.
United States
EPA enforcement of Clean Water Act and Safe Drinking Water Act thresholds drives municipal utility procurement of third-party verification. The agency's PFAS detection mandates compress laboratory turnaround times from weeks to days. Industrial clusters in Texas and Ohio anchor demand for stack emission testing contractors serving chemical manufacturing permit holders.
Germany
The Rhine-Ruhr industrial corridor generates concentrated demand for quarterly air and soil monitoring under factory compliance mandates. ECHA's 2024-2027 screening program obliges chemical manufacturers to commission expanded toxicity testing. Berlin-Brandenburg laboratories leverage ISO 17025 accreditation to capture cross-border contracts from Polish manufacturing FDI in Lower Silesia.
United Kingdom
Brownfield redevelopment across former manufacturing zones in the Midlands and North England requires pre-construction soil screening. Property developers pull environmental consultancies into multi-year site monitoring contracts. The Environment Agency's enforcement of contaminated land regulations sustains recurring revenue for accredited testing providers.
India
CPCB alignment with BIS water quality norms expands addressable contracts for cross-border certification bodies. State pollution control boards in Maharashtra and Gujarat procure compliance monitoring through framework agreements. Manufacturing FDI in these industrial states outpaces local testing infrastructure, creating openings for accredited laboratories establishing regional hubs.
Belgium
Antwerp's petrochemical complex drives demand for industrial hygiene testing under REACH substance evaluation protocols. Flemish regional authorities mandate pre-transaction due diligence for contaminated site transactions. Walloon brownfield projects in the former industrial basin around Liège require extended monitoring contracts for remediation verification.
Environment Testing Services Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded multinationals commanding premium pricing for ISO 17025-accredited capacity while regional operators compete on proximity and cost. The market structure concentrates revenue among three global testing conglomerates with multi-country laboratory networks, supported by mid-tier national specialists and fragmented local field service operators. Strategic archetypes separate into accreditation-heavy full-service laboratories, equipment-integrated site assessment contractors, and technology-focused analytical method developers. Competitive moves center on geographic hub expansion into underpenetrated industrial corridors and backward integration into specialized sampling equipment production.
Within the accreditation-dominant tier, SGS, Bureau Veritas, and Eurofins Scientific exemplify divergent strategic positioning. SGS occupies a position anchored in European industrial hygiene testing through its laboratory network density. Bureau Veritas represents the equipment-integrated archetype through in-house production capabilities for contaminated site assessments. Eurofins Scientific sits within the R&D-intensive segment, differentiating via analytical method development for emerging contaminant classes. These three listed entities collectively illustrate how certification scale, equipment control, and technical specialization create defensible positioning against price-competitive regional operators.
| Leading Market Players |
|---|
| SGS |
| Bureau Veritas |
| Eurofins Scientific |
| Intertek |
| TÜV SÜD |
| ALS Limited |
| Mérieux NutriSciences |
| Microbac Laboratories |
| Element Materials Technology |
| Others |
Supply Flow & Price Mechanics
Multi-year framework agreements with municipal utilities lock in both ISO 17025 laboratory capacity and predictable unit pricing for water quality testing across Denmark and Sweden. These structures insulate accredited providers from spot-market volatility while exposing uncertified regional operators to margin compression when helium costs spike.
Pricing Analysis
Next-generation DART-MS portable units command 40-60% premiums over legacy solvent-extraction protocols for rapid soil screening. Three-tier pricing structure across premium, standard, and economy levels separates accredited laboratories with PFAS method suites from uncertified operators and automated high-throughput facilities. Pricing pressure stems from unbundled procurement platforms that let buyers disaggregate sampling, analysis, and regulatory filing. Municipal utilities exhibit highest price sensitivity through competitive tendering, while private equity funds in EU Green Deal-mandated due diligence show lowest sensitivity.
Supply Chain Analysis
Helium inventory cycles of 6-8 weeks tether laboratory operations to Qatar supply volatility and US federal reserve drawdowns. Analytical equipment concentrates in Germany, Switzerland, and the UK, while specialized sampling consumables source from US and Japanese manufacturers. Single-source vulnerability runs through high-resolution mass spectrometry components from select German and Swiss precision engineering firms. Distribution runs through multi-country laboratory networks for cross-border certification services, with regional field operators handling last-mile sample collection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Environment testing services are recovering from a cyclical trough driven by deferred brownfield redevelopment budgets. ECHA's 2024-2027 screening program is reactivating capital deployment into accredited laboratory capacity.
For Market Incumbents: Consolidate regional ISO 17025 laboratories in Poland's Lower Silesia corridor before manufacturing FDI outpaces local testing infrastructure. Acquire specialized sampling equipment producers to defend margin against field-equipped service integrators displacing central laboratories. Prioritize backward integration into automated sample prep robotics to compress turnaround times under EPA PFAS mandates. For New Entrants and Emerging Players: Real-time data platform integration represents the most penetrable service layer where legacy LIMS resist API connectivity. Target drone-mounted spectroscopy contracts for agricultural runoff monitoring in intensive farming regions where ground crews prove uneconomical. Deploy subscription-based monitoring dashboards to displace transactional sample testing among municipal utilities in Nordic markets. For Investors and Strategic Acquirers: Capital is best deployed toward R&D-intensive analytical method developers with pre-validated PFAS suites ahead of ECHA's substance class restrictions. Five-to-ten-year viability favors laboratories bridging field instrumentation with cloud analytics rather than pure central-lab models. Watch for helium supply stabilization as the inflection signal for margin recovery in gas chromatography-dependent operations.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Hub Expansion | ISO 17025 certification in Poland's Lower Silesia captures manufacturing FDI testing demand. |
| Backward Integration into Sampling Equipment | In-house production of contaminated site assessment tools differentiates full-service contractors. |
| Real-Time Data Platform Launch | Cloud analytics dashboards enable subscription contracts displacing transactional testing. |
| PFAS Method Suite Development | Pre-validated analytical protocols capture ECHA-mandated quarterly effluent verification volumes. |
| Drone Spectroscopy Service Line | Remote sensing cuts mobilization costs for agricultural runoff and large-area pollution surveys. |
Methodological Framework
A standing panel of laboratory operations directors, municipal utility procurement managers, environmental consultancy principals, and regulatory affairs specialists at certification bodies provided ongoing calibration across the analysis window. Primary interviews combined with secondary validation from EPA enforcement records, ECHA substance evaluation databases, SEC 10-K filings of listed testing conglomerates, and BIS water quality norm circulars. Bottom-up service-line modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Consistency checks validated outputs against external benchmarks including laboratory accreditation registries and municipal procurement disclosure databases. Segmentation dimensions covered service type, end-user industry, application purpose, and technology platform across the projection horizon. CAGRs derived from regression analysis of historical contract values and regulatory mandate intensity. Forecast inputs incorporated helium price indices and brownfield redevelopment permit issuance rates.
Forecasts assume regulatory continuity in EPA Clean Water Act enforcement and ECHA REACH substance evaluation; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Water Testing Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
Emission Monitoring Systems Market