
 Carbon Monoxide Analyzers Market | 2026-2036
Carbon Monoxide Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Monoxide Analyzers Market Analysis
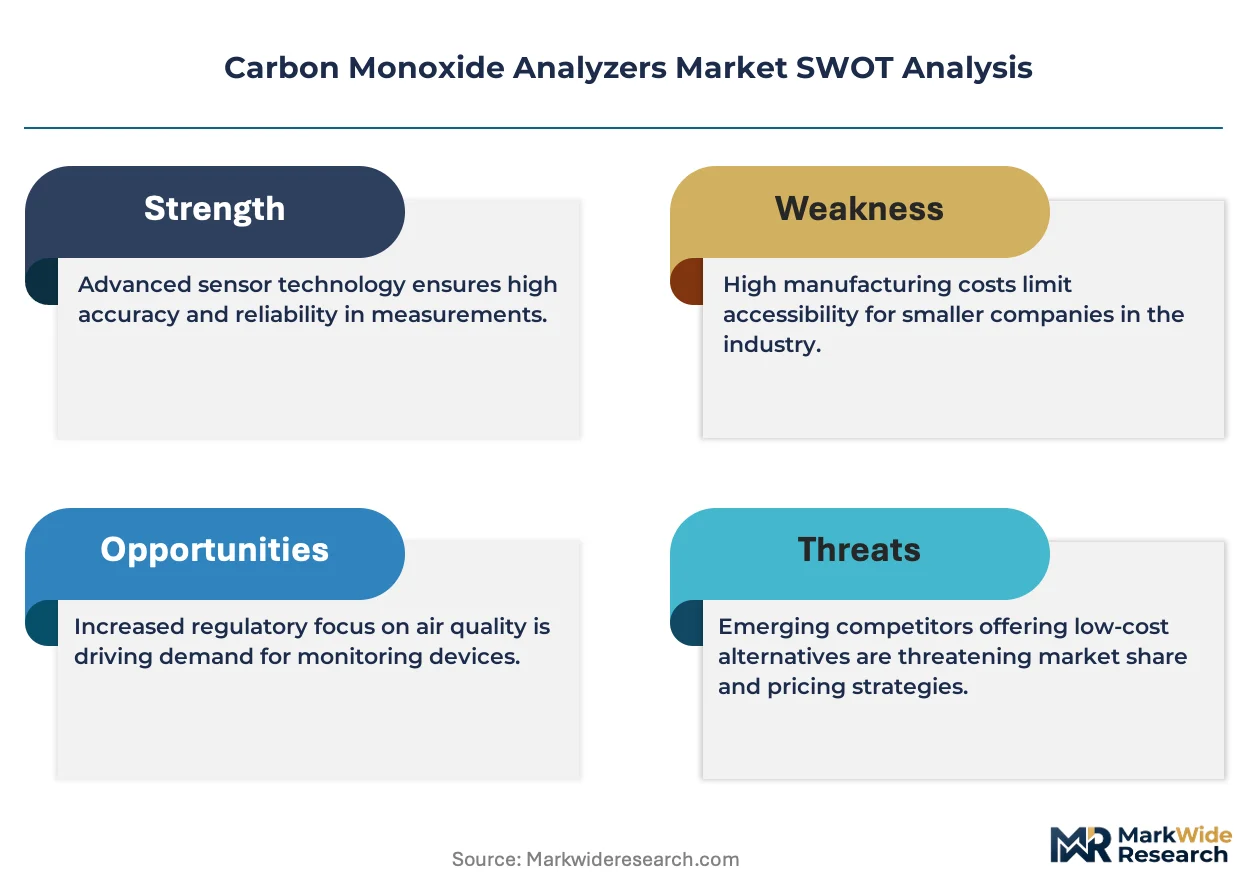
Sensor miniaturization and wireless connectivity integration is fragmenting the traditional carbon monoxide analyzer architecture into modular, distributed monitoring networks. ABB Ltd leverages its process automation heritage to anchor large-scale industrial safety deployments across petrochemical complexes. Siemens AG competes through embedded gas analytics platforms that extend building automation capabilities. Honeywell International Inc. dominates portable safety instrumentation with field-proven electrochemical designs.
Carbon monoxide analyzers are precision gas detection instruments that measure CO concentration in ambient or process streams, typically employing electrochemical cells with detection thresholds below one part per million or non-dispersive infrared spectroscopy for continuous emissions monitoring. Their primary purpose is to prevent toxic exposure in occupational settings and ensure combustion process efficiency. Fixed installations for environmental monitoring and industrial safety command the largest installed base, while handheld and portable units for automotive emissions testing represent the fastest-growing demand pool. Electrochemical technology leads unit shipments due to cost accessibility, though laser-based systems capture premium pricing in research laboratory and regulatory compliance applications.
EPA emissions standards and OSHA permissible exposure limits directly shape product certification requirements and replacement demand in the United States, while the EU Green Deal and REACH chemical safety protocols tighten analyzer accuracy mandates across European industrial facilities. The IEC 60079 explosion protection framework and ISO 17025 calibration standards further govern market access for manufacturers targeting hazardous environment deployments. Stakeholders must monitor evolving hydrogen economy infrastructure codes, as blended fuel combustion introduces new CO measurement complexities that will redefine analyzer specification priorities.
Market Dynamics
Sensor miniaturization and wireless connectivity integration is fragmenting traditional carbon monoxide analyzer architecture into modular, distributed monitoring networks, forcing established vendors to restructure hardware portfolios around software-defined detection platforms.
Growth Catalysts
- OSHA Indoor Air Mandates:Stricter permissible exposure limits in the United States are accelerating replacement cycles for aging electrochemical units across manufacturing facilities.
- Automotive Exhaust Testing:Germany's KBA certification requirements for CO measurement devices are concentrating demand for portable analyzers in vehicle inspection stations.
- Electrochemical Cost Accessibility:Mature cell manufacturing in East Asia is enabling price-competitive penetration into residential and small commercial safety applications.
Market Restraints
- Precious Metal Input Volatility:Platinum and palladium catalyst costs in electrochemical sensors create margin pressure for mid-tier analyzer manufacturers.
- Calibration Infrastructure Concentration:ISO 17025-accredited calibration laboratories cluster in Germany, Japan, and the United States, creating service access gaps in emerging industrial zones.
- Laser Spectroscopy Substitution:Tunable diode laser absorption spectroscopy is capturing premium regulatory compliance applications above ten thousand dollars per unit.
Strategic Opportunities
- Hydrogen Economy Codes:Blended hydrogen-natural gas combustion infrastructure in the Netherlands and Denmark is creating demand for CO analyzers with modified detection algorithms.
- Wireless Mesh Networks:Integration of LoRaWAN and 5G connectivity is enabling distributed analyzer deployments without hardwired power infrastructure.
- EU Green Deal Tailwinds:Industrial emissions verification requirements are mandating continuous monitoring upgrades across steel, cement, and chemical processing plants.
Industry Challenges
- Cross-Disciplinary Calibration Expertise:Analyzer maintenance requires technicians fluent in both electrochemistry and industrial networking protocols, creating recruitment bottlenecks.
- Legacy System Integration:BACnet and Modbus protocol fragmentation in building automation is complicating retrofit deployments of smart CO detection units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Monoxide Analyzers Market |
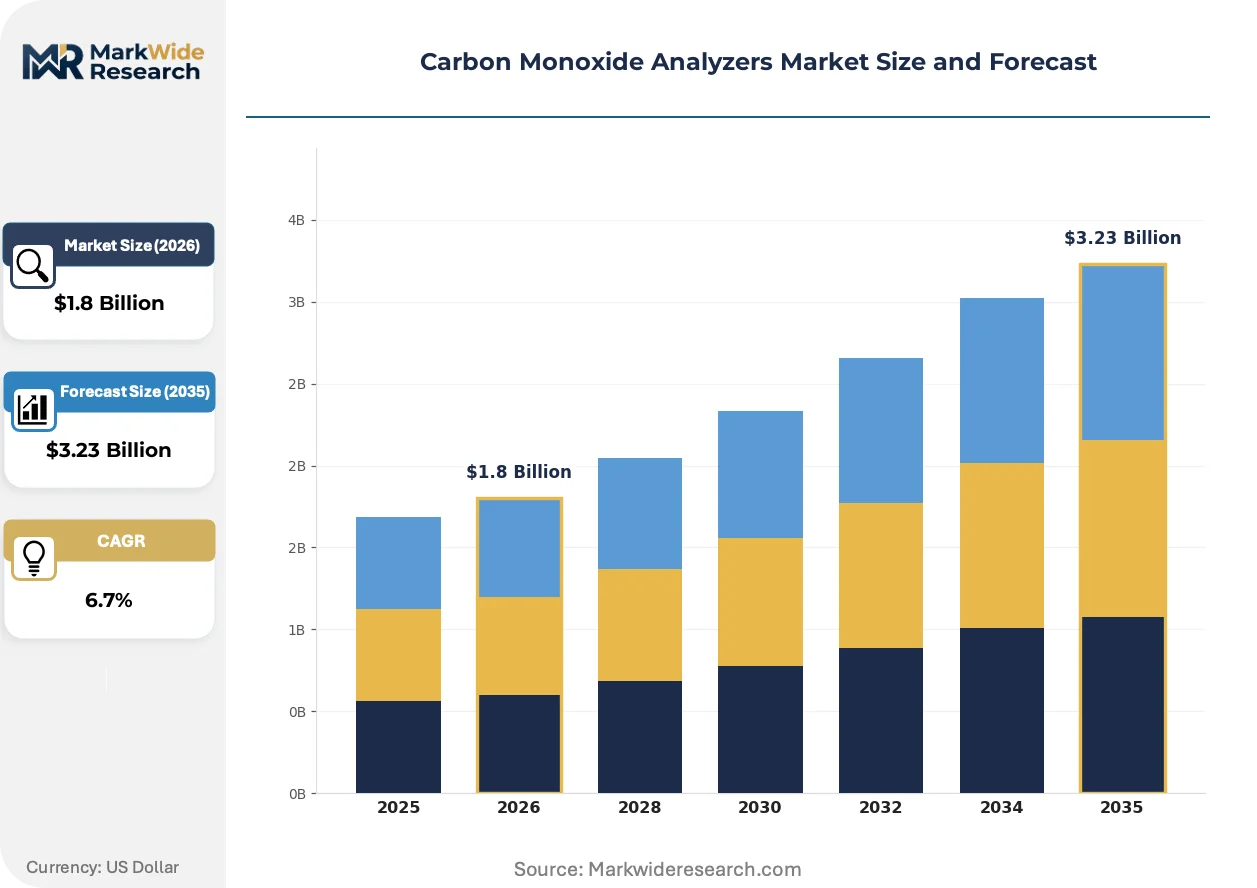
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Handheld, Bench-top End User: Environmental Monitoring, Industrial Safety, Automotive Testing, Residential Applications Technology: Infared, Electrochemical, Semiconductor, Laser-Based Application: Indoor Air Quality, Automotive Emissions, Occupational Health, Research Laboratories |
| Companies Covered | Honeywell International Inc., ABB Ltd, Siemens AG, Robert Bosch GmbH, Aeroqual Ltd, Alphasense, Yokogawa Electric Corporation, MSA Safety Incorporated, Kidde, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Monoxide Analyzers Market Emerging Trajectories
Digital detection architectures are displacing analog signal processing across the carbon monoxide analyzer value chain, compressing hardware margins while expanding software and analytics revenue pools.
Photonic integrated circuits are virtualizing the optical path in non-dispersive infrared analyzers. Petrochemical operators in Texas and Louisiana are piloting chip-scale spectrometers for perimeter monitoring. This silicon photonics platform is virtualizing the benchtop analyzer form factor into smartphone-sized modules that embed directly into process control loops.
The EPA's updated New Source Performance Standards for industrial boilers are mandating continuous emissions monitoring systems with quarterly relative accuracy test audits. Steel mills and cement kilns in the Ohio River Valley are retrofitting existing stacks with dual-beam NDIR analyzers to maintain operating permits. Equipment vendors are responding with modular analyzer designs that separate the optical bench from the electronics enclosure to simplify field servicing.
Building operators are unbundling hardware acquisition from calibration service contracts, compressing multi-year agreements into annual subscriptions with remote diagnostics. Facility management firms in Singapore and Sydney are consolidating vendor relationships around platform-agnostic service providers. This procurement restructuring is most visible in commercial real estate portfolios exceeding five hundred thousand square meters, where centralized CO monitoring dashboards override brand-specific hardware preferences.
Carbon Monoxide Analyzers Market Segmentation
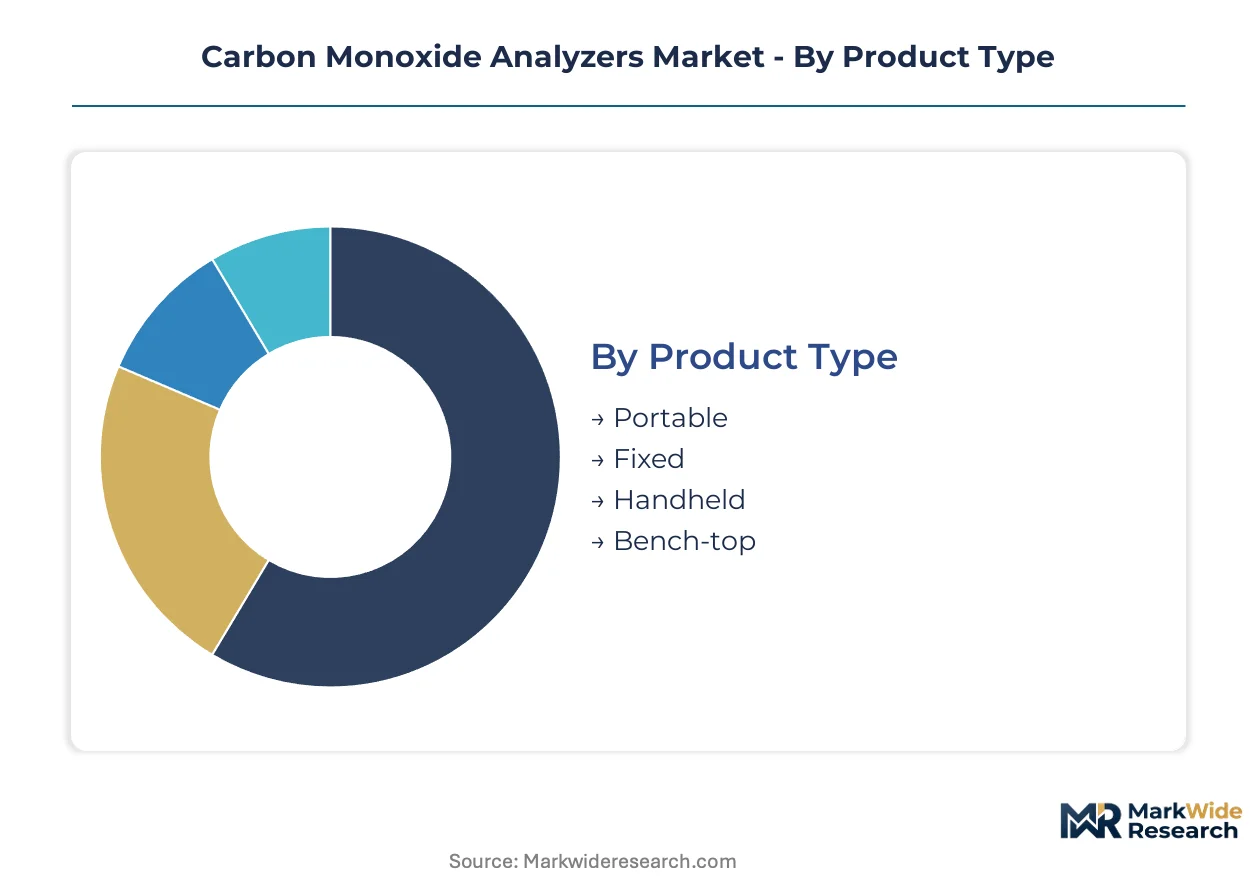
Carbon monoxide analyzer procurement splits across four distinct category systems. Product form factors, end-use environments, detection technologies, and application contexts each reshape specification priorities and vendor selection criteria for safety officers and compliance managers.
Product Type:
Portable units dominate field inspection workflows where power infrastructure is unavailable.
- Portable:Battery-powered electrochemical units with wireless data logging serve chemical plant perimeter patrols and emergency response teams. Demand concentrates in Texas and Louisiana petrochemical corridors where OSHA mandates drive quarterly equipment rotation.
- Fixed:Hardwired NDIR installations with 4-20mA outputs anchor continuous emissions monitoring at steel mills and cement kilns. German industrial facilities under EU Green Deal verification requirements represent the densest installed base.
- Handheld:Compact single-gas detectors with instant alarms support automotive technicians in German KBA-certified inspection stations.
- Bench-top:Laboratory-grade analyzers with parts-per-billion resolution serve research institutions and calibration laboratories in Japan and the United States.
The dominant share belongs to Fixed installations, while Portable units are gaining share fastest.
End User:
Cost tiers separate specification requirements from budget-constrained residential buyers to precision-demanding regulatory compliance.
- Environmental Monitoring:Continuous stack analyzers with EPA-certified protocols serve power generation and waste incineration facilities. The Ohio River Valley retrofit cycle under updated New Source Performance Standards is accelerating replacement demand.
- Industrial Safety:Distributed sensor networks with SIL-rated outputs protect worker exposure in chemical processing and oil refining. Singapore's Jurong Island petrochemical cluster deploys mesh-connected analyzers across integrated process units.
- Automotive Testing:Portable exhaust analyzers with KBA certification validate vehicle compliance in German inspection stations.
- Residential Applications:Low-cost electrochemical alarms with 10-year sealed batteries penetrate multi-family housing under municipal fire codes in California and New York.
Environmental Monitoring commands the largest contract values, though Industrial Safety is expanding most quickly through wireless infrastructure upgrades.
Technology:
Volume concentration favors mature electrochemical manufacturing, while margins cluster in optical precision.
- Infared:Non-dispersive infrared benches with dual-beam reference paths deliver drift-free continuous monitoring for stack emissions. Steel producers in the Ruhr region deploy modular NDIR units to satisfy EU Industrial Emissions Directive verification.
- Electrochemical:Three-electrode cells with polymer electrolytes dominate unit shipments through East Asian contract manufacturing. Cost accessibility enables penetration into residential safety and small commercial applications.
- Semiconductor:Metal oxide sensors with integrated temperature compensation serve cost-sensitive HVAC integration and smart building retrofits.
- Laser-Based:Tunable diode absorption spectroscopy captures premium regulatory compliance above ten thousand dollars per unit in research and metrology laboratories.
Electrochemical technology holds volume leadership, while Laser-Based systems are climbing the fastest on regulatory precision demands.
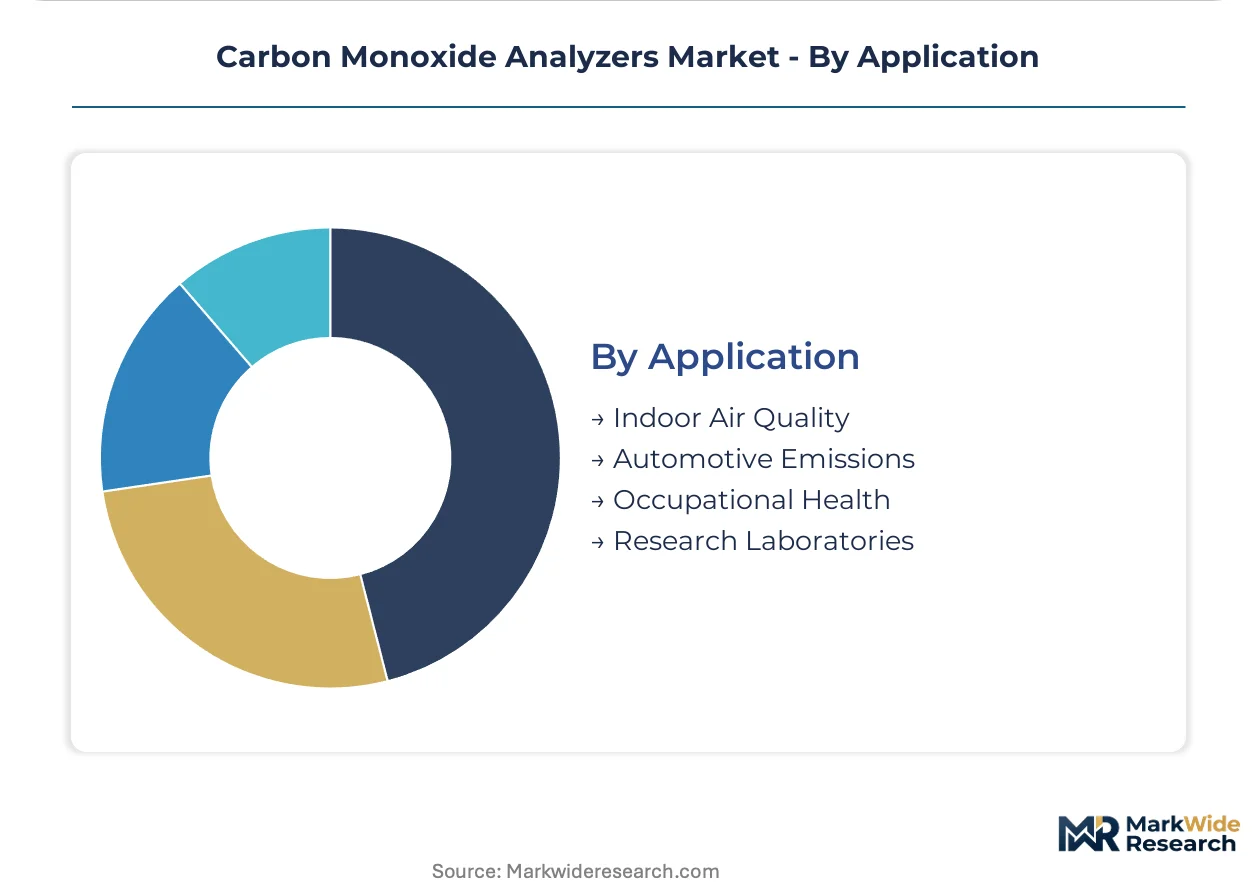
Application:
Customer type fragmentation separates one-time residential purchasers from multi-year service contract holders.
- Indoor Air Quality:Networked CO detectors with BACnet integration serve commercial real estate portfolios exceeding five hundred thousand square meters. Facility managers in Sydney and Singapore consolidate procurement around platform-agnostic service providers with remote diagnostics.
- Automotive Emissions:Certified portable analyzers with real-time printing validate exhaust compliance in vehicle inspection stations. Germany's KBA enforcement maintains the strictest certification requirements globally.
- Occupational Health:Personal exposure monitors with data logging document worker safety in confined space entry and maintenance operations.
- Research Laboratories:Parts-per-billion analyzers with gravimetric calibration traceability support atmospheric chemistry and combustion research.
Indoor Air Quality generates the highest service contract attachment rates, while Automotive Emissions is closing the gap fastest on inspection mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement managers in petrochemical, automotive testing, and building automation sectors concentrate analyzer demand across five national markets. Each geography exhibits distinct regulatory enforcement patterns and industrial cluster configurations.
United States
EPA stack emissions enforcement and OSHA permissible exposure limits drive continuous monitoring upgrades. The New Source Performance Standards for industrial boilers mandate quarterly relative accuracy test audits. Steel mills and cement kilns across the Ohio River Valley retrofit existing stacks with dual-beam NDIR analyzers.
Germany
KBA automotive exhaust certification requirements concentrate portable analyzer demand in vehicle inspection stations. EU Green Deal industrial emissions verification mandates accelerate continuous monitoring deployments. Steel producers in the Ruhr region install modular NDIR units to satisfy Industrial Emissions Directive requirements.
China
Dual carbon goals and MEE air quality enforcement expand environmental monitoring procurement. Petrochemical complexes in the Yangtze River Delta deploy distributed sensor networks. East Asian contract manufacturing of electrochemical cells enables cost-competitive residential safety penetration.
Japan
METI industrial safety protocols and JIS calibration standards anchor precision analyzer demand. Research institutions in the Kanto region procure parts-per-billion laboratory analyzers. Gravimetric calibration traceability requirements concentrate metrology-grade equipment procurement.
Singapore
Jurong Island petrochemical cluster drives mesh-connected analyzer deployments across integrated process units. Facility management firms consolidate procurement around platform-agnostic service providers. Commercial real estate portfolios exceeding five hundred thousand square meters adopt centralized CO monitoring dashboards.
Carbon Monoxide Analyzers Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Process automation conglomerates anchor large-scale industrial safety deployments through bundled instrumentation contracts. Electrochemical sensor specialists capture residential and portable safety markets through East Asian manufacturing scale. Optical precision houses serve premium regulatory compliance above ten thousand dollars per unit. Dominant competitive moves include strategic partnerships for wireless connectivity integration and portfolio diversification into hydrogen economy detection algorithms.
Within the process automation tier, ABB Ltd and Siemens AG exemplify platform-anchored competition. Honeywell International Inc. occupies a position among electrochemical portable specialists with field-proven safety instrumentation heritage. These three entities represent the dominant archetypes: automation-integrated systems, embedded gas analytics platforms, and portable safety instrumentation.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ABB Ltd |
| Siemens AG |
| Robert Bosch GmbH |
| Aeroqual Ltd |
| Alphasense |
| Yokogawa Electric Corporation |
| MSA Safety Incorporated |
| Kidde |
| Others |
Supply Flow & Price Mechanics
East Asian electrochemical cell manufacturing concentrates upstream supply, anchoring margin pools in calibration services and software-defined detection platforms downstream. Platinum and palladium catalyst costs transmit volatility through sensor pricing, while ISO 17025-accredited service providers capture recurring revenue in Germany, Japan, and the United States.
Pricing Analysis
Cost-plus contracts with precious metal indexation dominate electrochemical sensor procurement, with platinum and palladium price clauses triggering quarterly adjustments. Certification grade—EPA, KBA, or JIS tier—drives price differentiation more than brand premium, while volume scale separates residential safety economics from laboratory-grade metrology. Pricing pressure stems from laser spectroscopy substitution above ten thousand dollars per unit, compressing mid-tier NDIR margins. Residential buyers exhibit highest price sensitivity, whereas regulatory compliance purchasers accept premium positioning for traceable calibration chains.
Supply Chain Analysis
Upstream feedstock dependence on platinum group metals sourced from South Africa and Russia creates catalyst cost exposure for electrochemical cell producers. Sensor manufacturing concentrates in China, Japan, and South Korea, with polymer electrolyte membrane fabrication tethered to fluoropolymer supply from Belgian and Japanese chemical complexes. Single-source vulnerability in ISO 17025-accredited calibration gases—gravimetric standards from NIST-traceable laboratories—constrains service scaling. Distribution runs through process automation distributors for industrial accounts and fire safety wholesalers for residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against tunable diode laser absorption spectroscopy, which is displacing electrochemical and NDIR architectures in premium regulatory compliance above ten thousand dollars per unit.
For Market Incumbents: Pre-empt laser spectroscopy encroachment by embedding photonic integrated circuit roadmaps into R&D pipelines, while deepening calibration service moats through ISO 17025 laboratory geographic expansion into emerging industrial zones. Backward integration into electrochemical cell manufacturing in East Asia defends margin position against precious metal volatility. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where BACnet-integrated CO detection lacks established service provider relationships. Wireless mesh deployments without hardwired infrastructure offer a channel-agnostic go-to-market angle, bypassing incumbent automation distributor control. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed electrochemical sensor specialists carrying 2018-2022 vintage platform rollups. Long-term viability hinges on hydrogen economy detection algorithm development, with blended fuel combustion infrastructure in the Netherlands and Denmark serving as the signal to watch for technology inflection. Cross-checking against EU Green Deal industrial emissions verification mandate acceleration is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Development | Silicon photonics virtualizes optical benches into smartphone-sized modules for process control integration. |
| ISO 17025 Laboratory Geographic Expansion | Calibration service access gaps in emerging industrial zones create first-mover consolidation opportunities. |
| Hydrogen Economy Detection Algorithm Investment | Blended hydrogen-natural gas combustion in Denmark and the Netherlands demands modified CO measurement protocols. |
| Wireless Mesh Network Platform Integration | LoRaWAN and 5G connectivity enable distributed deployments without hardwired power infrastructure. |
| Backward Integration into Electrochemical Cell Manufacturing | East Asian contract manufacturing scale defends margin position against platinum group metal volatility. |
Methodological Framework
Cross-validation between primary interviews with plant safety managers, calibration laboratory technicians, and automotive emissions inspectors and secondary validation through EPA enforcement databases, KBA certification registries, and EU Industrial Emissions Directive compliance filings anchors the qualitative findings. Bottom-up triangulation across product type, end user, technology, and application segmentation layers with top-down macroeconomic calibration ensures internal consistency.
Calibration against historical replacement cycle patterns and regulatory mandate implementation timelines structures the analytical framework across the projection horizon. Segmentation dimensions modeled include product form factor, detection technology tier, end-use environment, and geographic regulatory cluster. CAGRs derive from equipment replacement velocity analysis and enforcement intensity scoring, with hydrogen economy infrastructure buildout and wireless connectivity adoption serving as scenario-weighting inputs.
Practitioners should monitor EPA New Source Performance Standards enforcement intensity and EU Green Deal verification mandate expansion for early signals of forecast revision. Cross-checking against OSHA permissible exposure limit amendment petitions and KBA certification requirement updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
Indoor Air Quality Service Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Eco Funnel Market
Environmental Monitoring
US Environmental Testing Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Radon Gas Test Kits Market
Environmental Monitoring
Environmental Testing Market