
 Laser Markable Labels Market | 2026-2036
Laser Markable Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Markable Labels Market Foresight
Medical device OEM procurement is collapsing toward laboratories and contract sterilization firms that require permanent, heat-resistant identification. Brady leverages its vertical integration into label substrates and printing systems to sustain dominance in healthcare compliance workflows. 3M Company anchors the industrial segment through its proprietary polymer formulations that withstand aggressive chemical exposure. Camcode competes on geographic reach across North American aerospace and defense maintenance depots.
Laser markable labels are synthetic or metallic substrates engineered to undergo permanent color change or material ablation when exposed to focused laser energy, typically CO2, fiber, or UV laser sources operating at precise wattages and pulse frequencies. These labels serve critical functions in asset tracking, regulatory traceability, and anti-counterfeiting across sectors where mechanical durability and chemical resistance exceed conventional printed barcode capabilities. Polymer substrates lead volume due to their adaptability across CO2 and fiber laser platforms, while metal labels command premium positioning in aerospace and heavy machinery applications where extreme thermal cycling occurs. The healthcare application segment shows the steepest trajectory as FDA UDI and EU MDR compliance deadlines force surgical instrument and implant manufacturers toward permanent marking solutions that survive autoclave sterilization.
The FDA enforces Unique Device Identification rules that mandate permanent, readable marks on medical devices through distribution and use, directly elevating laser markable label specifications for Class II and III products. The EU MDR and EMA guidance on traceability systems require economic operators to maintain device records across twenty years, creating durable-label demand that thermal transfer or inkjet methods cannot satisfy. REACH and RoHS frameworks from ECHA constrain adhesive and substrate chemistries, pushing LINTEC Corporation and tesa SE toward halogen-free and low-VOC formulation investments. Stakeholders must monitor how IEC laser safety standards evolve alongside ISO 13485 quality management requirements, as dual compliance will determine supplier qualification timelines in regulated end markets.
Market Dynamics
Healthcare traceability mandates are compressing procurement timelines for permanent marking solutions as surgical instrument manufacturers race to meet sterilization-survivable identification requirements before regulatory deadlines.
Growth Catalysts
- FDA UDI enforcement:The Unique Device Identification rule mandates permanent marks on Class II and III medical devices through distribution and use, forcing manufacturers toward laser-markable substrates that withstand repeated autoclave cycles.
- Polymer substrate versatility:Advanced polymer formulations adapt across CO2 and fiber laser platforms, enabling single-supplier consolidation for medical device OEMs managing diverse instrument portfolios.
- German precision engineering clusters:Stuttgart and Munich automotive component manufacturers drive high-volume adoption for part serialization, creating scale economies that downstream medical and aerospace buyers leverage.
Market Restraints
- Specialty polymer feedstock concentration:Fluoropolymer and high-performance thermoplastic supply concentrates among a limited German and Japanese chemical compounder base, exposing label converters to input volatility.
- Laser system capex barriers:Fiber and UV laser marking equipment requires six-figure capital outlays that contract sterilization firms and mid-sized device manufacturers struggle to justify for lower-volume SKUs.
- REACH formulation constraints:ECHA restrictions on halogenated adhesives and substrate chemistries force reformulation investments that compress margins for European-focused label producers.
Strategic Opportunities
- Indian contract manufacturing expansion:CDSCO medical device registration growth and Make in India incentives attract sterilization service providers requiring permanent instrument tracking infrastructure.
- Aerospace MRO digitization:North American and European maintenance depots are retrofitting legacy asset databases with laser-marked metal labels for component lifecycle traceability.
- RFID-laser hybrid convergence:Embedding passive RFID inlays within laser-markable polymer substrates creates dual-authentication solutions for high-value implant and pharmaceutical packaging applications.
Industry Challenges
- Laser parameter optimization expertise:Calibrating wattage, pulse frequency, and substrate interaction requires specialized technicians that label converters and end-users struggle to recruit and retain.
- Dual certification timelines:Simultaneous IEC laser safety and ISO 13485 quality management qualification extends supplier onboarding to 18-24 months, delaying healthcare market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Markable Labels Market |
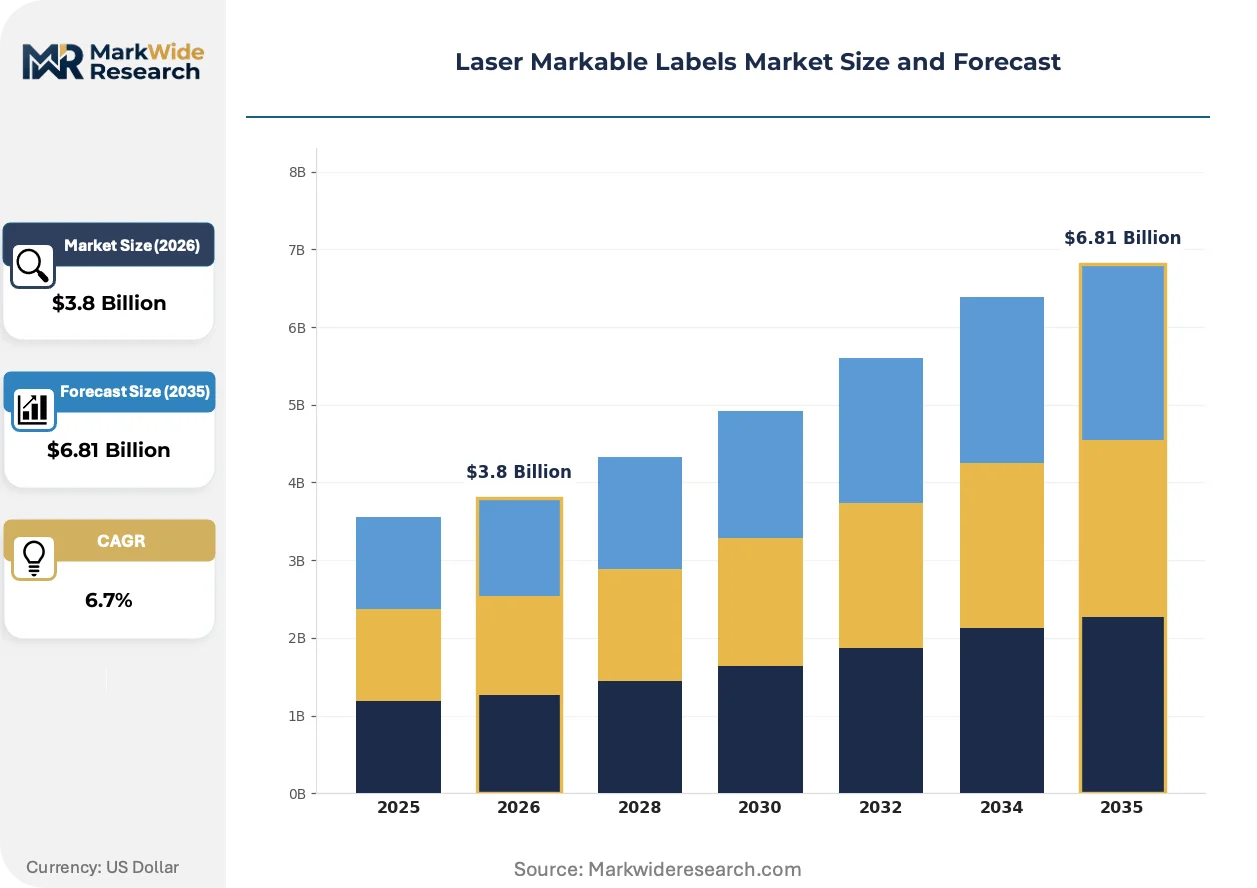
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Paper, Metal, Composite Application: Retail, Industrial, Healthcare, Logistics End User: Manufacturers, Distributors, Retailers, Laboratories Technology: Digital Printing, Offset Printing, Flexographic Printing, Direct Thermal |
| Companies Covered | 3M Company, Brady, Camcode, Horizons Inc., Keyence Corporation, LINTEC Corporation, Nortec Group, Nippon Carbide Industries (HangZhou) Co., Ltd., tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Markable Labels Market Shifts & Advancements
Permanent marking technologies are converging with digital traceability infrastructure as regulated industries abandon consumable identification methods in favor of survivable, machine-readable solutions.
UV laser marking systems is supplanting CO2 platforms in medical device applications where heat-sensitive polymers and thin-walled surgical instruments require cold ablation processes. German and Swiss instrument manufacturers are retrofitting production lines with picosecond UV sources to achieve micron-precision marks without thermal damage to delicate substrates. This platform shift is compressing equipment supplier margins as fiber laser incumbents face displacement in high-value healthcare segments.
EU MDR Article 27 traceability requirements now mandate that economic operators maintain device records across twenty years, a duration that thermal transfer and inkjet labels cannot satisfy through repeated sterilization cycles. The regulation forces surgical instrument and implant manufacturers toward laser-markable solutions as the only viable compliance pathway. German notified bodies report that label survivability documentation now constitutes a critical audit checkpoint during technical file reviews.
Hospital procurement departments are consolidating sterilization service contracts with vendors who can deliver pre-marked instrument sets rather than managing marking operations in-house. This channel shift concentrates volume among contract sterilization firms in the US Great Lakes and German Ruhr regions who have invested in high-throughput laser marking cells. The model is displacing distributed marking at individual hospital sites, favoring suppliers with regional logistics networks and regulatory documentation capabilities.
Laser Markable Labels Market Segmentation
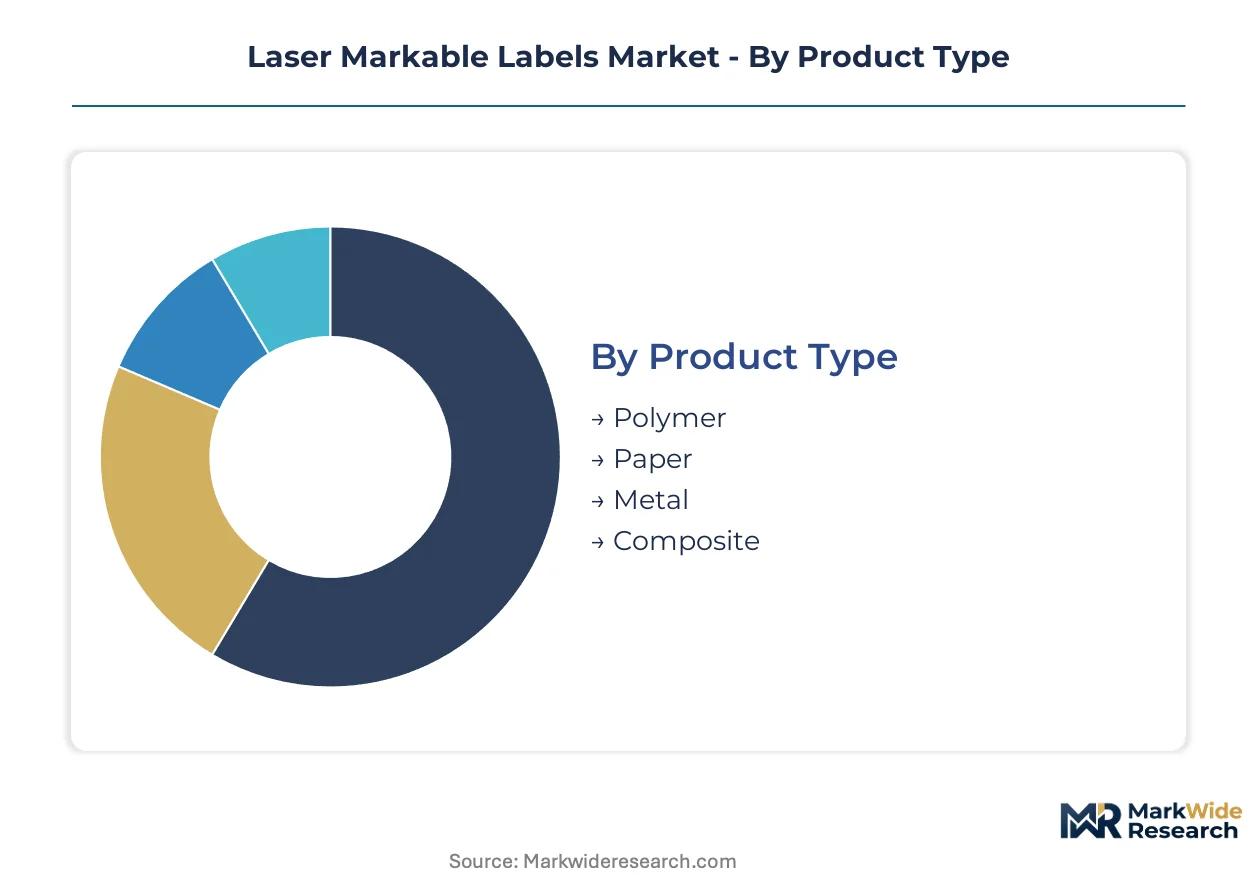
Laser markable labels fragment across material chemistry, end-use durability requirements, and printing platform compatibility. Each segmentation axis reveals distinct margin structures and procurement patterns that suppliers must navigate.
Product Type:
Margin pools concentrate in substrates engineered for extreme thermal cycling and chemical exposure, where formulation IP creates defendable pricing power.
- Polymer:Advanced thermoplastic formulations—polyimide, polyester, and fluoropolymer variants—dominate medical device applications due to autoclave survivability. German automotive OEMs and US surgical instrument manufacturers drive volume procurement for serialization workflows, with FDA UDI compliance deadlines compressing adoption timelines.
- Metal:Anodized aluminum and stainless steel substrates command premium positioning in aerospace MRO and heavy machinery asset tracking. North American maintenance depots retrofit legacy equipment databases with laser-ablated metal labels that withstand extreme thermal cycling and solvent exposure.
- Paper:Specialized coated papers serve short-lifecycle retail and logistics applications where cost minimization outweighs durability requirements. Limited heat resistance restricts deployment to ambient-temperature supply chains.
- Composite:Multi-layer laminates combine polymer flexibility with metal durability for hybrid performance tiers. Emerging adoption in pharmaceutical packaging where tamper-evidence and traceability converge.
The dominant share belongs to Polymer, while Metal is closing the gap fastest.
Application:
Regulatory intensity and sterilization requirements determine where procurement budgets concentrate across end-use verticals.
- Healthcare:Surgical instrument tracking, implant serialization, and sterilization-survivable identification dominate procurement. EU MDR Article 27 mandates twenty-year record retention, eliminating thermal transfer and inkjet alternatives from compliance pathways.
- Industrial:Automotive component serialization, chemical drum labeling, and heavy machinery asset tracking constitute core demand. Stuttgart and Munich precision engineering clusters generate scale economies that downstream buyers leverage.
- Retail:Apparel hang tags, electronics packaging, and consumer goods branding represent high-volume, low-margin deployment. Limited durability requirements favor cost-optimized substrate selection.
- Logistics:Parcel tracking, warehouse inventory management, and shipping container identification drive standardized procurement. Barcode readability specifications dominate technical requirements over environmental survivability.
Healthcare commands the steepest expansion trajectory, with Industrial maintaining volume leadership.
End User:
Procurement sophistication and regulatory documentation capabilities separate tier-one buyers from price-sensitive segments.
- Manufacturers:Medical device OEMs and automotive component producers require substrate-laser system integration and batch-level traceability documentation. Direct procurement relationships with label converters enable specification customization.
- Laboratories:Contract sterilization firms and research facilities demand pre-marked instrument sets with validated survivability data. Hospital procurement consolidation favors vendors with regional logistics networks.
- Distributors:Industrial supply intermediaries aggregate fragmented demand from mid-sized manufacturers. Limited technical specification involvement restricts margin capture.
- Retailers:Private-label apparel and electronics brands prioritize unit cost minimization over substrate performance. Short procurement cycles and high SKU turnover challenge supplier relationship depth.
Manufacturers retain the dominant procurement volume, while Laboratories are expanding fastest.
Technology:
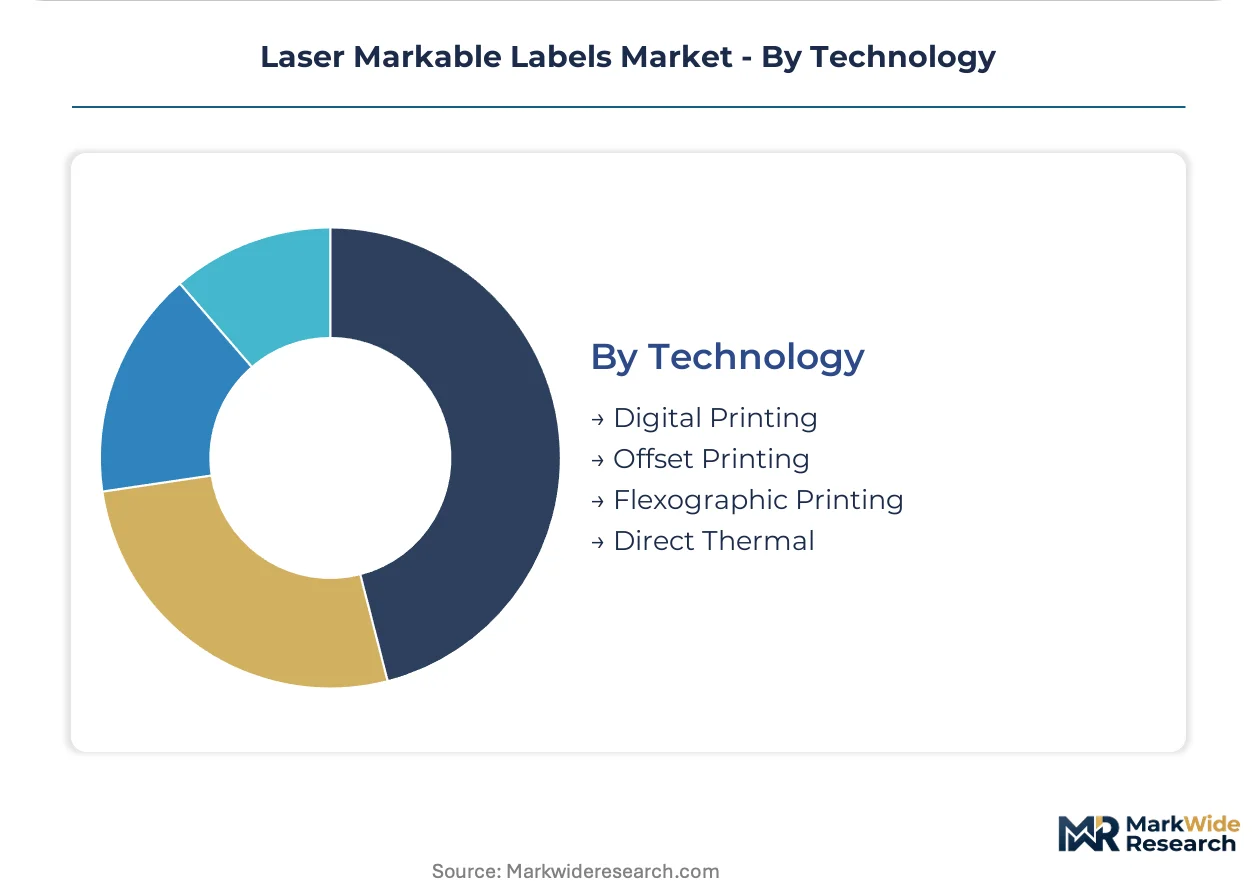
Printing platform selection determines substrate compatibility and marking permanence, with laser-compatible methods capturing regulated segment share.
- Digital Printing:Variable data capability and short-run flexibility serve medical device serialization and customized industrial labeling. UV-curable inks and laser-markable substrates converge in pharmaceutical packaging applications.
- Direct Thermal:Simplified equipment requirements and elimination of ribbon consumables attract logistics and retail deployment. Heat-sensitive chemistry limits survivability in sterilization environments.
- Offset Printing:High-volume efficiency and color consistency serve retail branding and consumer goods packaging. Limited variable data capability restricts healthcare and industrial traceability adoption.
- Flexographic Printing:Continuous-roll throughput and substrate versatility support logistics and industrial labeling at scale. Setup costs and plate preparation timelines disadvantage short-run medical device applications.
Digital Printing leads technology deployment, with Direct Thermal expanding most quickly in cost-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters export laser-markable label substrates to US medical device manufacturers and automotive OEMs across three continents, establishing the Rhine-Main corridor as the dominant trade-flow hub for permanent marking solutions.
Germany
Stuttgart automotive component manufacturers and Munich surgical instrument producers drive procurement of polymer-based labels for serialization workflows. The EU MDR Article 27 twenty-year traceability mandate eliminates thermal transfer alternatives from compliance pathways. The Baden-Württemberg precision engineering cluster generates scale economies that downstream medical and aerospace buyers leverage for high-volume contracts.
United States
FDA UDI enforcement on Class II and III medical devices compresses procurement timelines for sterilization-survivable identification. The Great Lakes contract sterilization corridor concentrates laser marking infrastructure as hospital procurement departments consolidate vendor relationships. Chicago-area sterilization service providers capture volume from distributed hospital marking operations through regional logistics networks.
Japan
Fluoropolymer compounders in Osaka and Nagoya supply high-performance thermoplastic substrates to domestic and export markets. METI industrial standards and PMDA quality management requirements shape supplier qualification protocols. The Chubu region chemical manufacturing base anchors feedstock supply for premium label formulations serving aerospace and medical end-uses.
India
CDSCO medical device registration growth and Make in India incentives attract sterilization service providers requiring permanent instrument tracking infrastructure. The Maharashtra pharmaceutical manufacturing belt and Gujarat medical device parks drive label demand for export-oriented production. Mumbai-Pune contract manufacturers expand laser marking capacity to serve European and US regulatory compliance requirements.
Switzerland
Swissmedic oversight of medical device traceability elevates specifications for implant and surgical instrument marking. Basel pharmaceutical packaging specialists and Zurich precision instrument manufacturers procure laser-markable solutions for dual-authentication applications. The Swiss-German border region concentrates UV laser system deployment for cold ablation of heat-sensitive polymers.
Laser Markable Labels Market Competitive Landscape
Player mix skews toward diversified materials conglomerates with captive polymer formulation capabilities, creating a tiered structure where substrate IP holders command pricing power over pure-play label converters. Three archetypes dominate: vertically integrated chemical-label converters, precision printing system OEMs with substrate partnerships, and regional specialty distributors with regulatory documentation capabilities. Competitive moves concentrate on backward integration into halogen-free adhesive chemistry and geographic expansion into Indian contract manufacturing corridors.
Among diversified materials conglomerates, 3M Company and LINTEC Corporation occupy positions where proprietary polymer formulations create defendable margin structures. Brady exemplifies the precision printing system archetype through its integration of substrate and equipment workflows. tesa SE anchors the European specialty adhesive tier with REACH-compliant formulation investments. These three entities represent distinct competitive vectors—materials science dominance, workflow integration, and regulatory chemistry compliance—rather than direct substitution threats.
| Leading Market Players |
|---|
| 3M Company |
| Brady |
| Camcode |
| Horizons Inc. |
| Keyence Corporation |
| LINTEC Corporation |
| Nortec Group |
| Nippon Carbide Industries (HangZhou) Co., Ltd. |
| tesa SE |
| Others |
Supply & Pricing Matrix
German precision engineering clusters generate capacity-utilization efficiencies that compress polymer substrate price floors while concentrating supply power among fluoropolymer compounders in Baden-Württemberg and Osaka. This scale asymmetry forces mid-sized label converters to accept margin compression or exit healthcare compliance segments entirely.
Pricing Analysis
CO2 laser-compatible polymer substrates trade at substantial discounts to picosecond UV-grade formulations, creating a three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from ISO 13485 certification tier and autoclave cycle survivability ratings, with FDA UDI-compliant medical grades commanding substantial premiums. Cost compression in standard-grade polymers is intensifying because Japanese feedstock suppliers are prioritizing semiconductor-grade fluoropolymer allocation. Contract sterilization firms exhibit highest price sensitivity, while implant OEMs prioritize certification documentation over unit economics.
Supply Chain Analysis
BASF Ludwigshafen polymer production and Nagoya chemical manufacturing anchor global fluoropolymer substrate supply, with limited alternative sourcing for medical-grade formulations. Raw material dependencies center on perfluoroalkoxy alkane resins, high-purity aluminum for metal labels, and halogen-free adhesive chemistries. Single-source vulnerability concentrates in German-Japanese chemical compounder relationships, where REACH reformulation timelines lag procurement deadlines. Distribution runs through regional sterilization service hubs in the US Great Lakes and German Ruhr regions, bypassing traditional industrial supply intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser parameter optimization expertise and dual-certification qualification capabilities have become the binding constraints on supplier expansion, creating acute scarcity premiums for technicians who can calibrate wattage-pulse-substrate interactions across CO2, fiber, and UV platforms.
For Market Incumbents: Consolidate backward integration into halogen-free adhesive chemistry to preempt REACH margin compression, while capturing sterilization service contracts in the US Great Lakes corridor before hospital procurement consolidation hardens vendor relationships. Dual IEC laser safety and ISO 13485 certification investments extend competitive moats against emerging Asian compounders. For New Entrants and Emerging Players: Differentiate on cold-ablation UV laser compatibility for heat-sensitive surgical polymers, where German and Swiss instrument manufacturers face equipment retrofit urgency. Indian contract sterilization expansion offers the most penetrable geography, with CDSCO registration growth outpacing qualified label supplier capacity. A go-to-market angle anchored to pre-validated autoclave survivability documentation bypasses 18-24 month supplier onboarding barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors materials-science conglomerates with captive polymer formulation IP over pure-play label converters facing feedstock volatility. Long-term viability rests on regulatory chemistry compliance capabilities rather than equipment manufacturing scale. The signal to watch is CDSCO medical device registration velocity in Maharashtra and Gujarat, which indicates sterilization infrastructure investment trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halogen-Free Adhesive Chemistry | REACH compliance investments preempt ECHA restriction-driven margin compression for European-focused producers. |
| UV Laser System Partnership Programs | Picosecond cold-ablation platform deployment captures German-Swiss surgical instrument retrofit demand. |
| Regional Sterilization Service Hub Expansion | Great Lakes and Ruhr corridor logistics networks consolidate hospital procurement relationships. |
| RFID-Laser Hybrid Substrate Development | Dual-authentication solutions address EU MDR Article 27 twenty-year traceability mandates for high-value implants. |
| Indian Contract Manufacturing Qualification | CDSCO registration growth and Make in India incentives attract sterilization infrastructure investment. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers at surgical instrument OEMs, contract sterilization operations managers, polymer formulation chemists, and hospital GPO contracts managers, and refined through secondary validation against FDA UDI guidance documents, EMA MDR technical file requirements, ECHA REACH restriction updates, and customs trade data for fluoropolymer substrate flows. Bottom-up procurement volume estimates from sterilization service providers were triangulated against top-down healthcare compliance spending projections.
Variance-decomposition across material chemistry, end-use durability requirements, printing platform compatibility, and regional regulatory cluster intensity shaped the analytical framework. CAGRs were derived from segmented adoption curves weighted by FDA UDI and EU MDR enforcement timelines. Forecast inputs incorporated autoclave cycle survivability validation rates, UV laser system deployment trajectories in German-Swiss precision engineering clusters, and CDSCO medical device registration growth patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA UDI enforcement pressure and REACH formulation constraint trajectories would require recalibration. Practitioners should keep alternative scenarios live as IEC laser safety standard evolution and ISO 13485 quality management requirement convergence reshape supplier qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Variable Data Printing Labels Market
Labels
Freezer Label Market
Labels
Integrated Labeling System Market
Labels
India Print Label Market
Labels
Global Security Labels Market
Labels
Water Dissolvable Labels Market
Labels
Pin Feed Labels Market
Labels
Die Cut Labels Market
Labels
Global Cryogenic Label Market
Labels
Sleeve Label Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Global Laminated Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Holographic Labels Market
Labels
GCC Labeling Market