
 Ripeness Indicator Labels Market | 2026-2036
Ripeness Indicator Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Ripeness Indicator Labels Market Analytics
Aftermarket data-service revenue is reshaping competitive economics in the ripeness indicator labels space. CCL Industries leverages its global converting infrastructure to anchor premium sensor-label contracts with multinational produce distributors. Insignia Technologies specializes in time-temperature indicator chemistry, sustaining R&D intensity that differentiates its portfolio from commodity sticker suppliers. Faubel competes through precision-printing capabilities calibrated for ethylene-sensitive fruit applications.
Ripeness indicator labels are adhesive or affixed visual indicators that undergo colorimetric or chromogenic changes in response to volatile organic compounds—principally ethylene—or accumulated temperature exposure, manufactured through microencapsulation of reactive dyes onto paper, plastic, or biodegradable substrates. Their primary commercial purpose is to communicate optimal consumption windows and reduce spoilage-related losses across fresh produce supply chains. Sticker and sensor formats command the dominant share of label-type revenue, while biodegradable materials represent the fastest-expanding material category as retailers face mounting packaging-waste compliance obligations. Application demand clusters heavily in fruits, where perishability premiums justify unit-cost investments that vegetable and herb segments have not yet matched.
The U.S. FDA's food-labeling integrity standards and the EU's Packaging and Packaging Waste Regulation jointly constrain adhesive migration limits and mandate recyclability disclosures, directly shaping substrate selection and regional product-line configurations. ISO 22000 food safety management certification operates as a de facto market-access threshold for supplier qualification by major European and North American retail chains. Stakeholders must monitor how evolving extended producer responsibility frameworks in France and Germany recalibrate total cost-of-ownership calculations for biodegradable versus conventional plastic label stocks.
Market Dynamics
The EU Green Deal's packaging sustainability mandates are collapsing demand for conventional plastic label substrates while accelerating biodegradable material qualification cycles across European fresh produce supply chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates recyclability disclosures and adhesive migration limits that favor compliant ripeness indicator suppliers in Germany and France.
- Precision agriculture adoption:German retailers deploy ethylene-sensitive labels to optimize inventory turnover and reduce spoilage-related losses in high-value fruit segments.
- ISO 22000 certification thresholds:Major North American retail chains require food safety management certification as a de facto supplier qualification gate.
Market Restraints
- Biodegradable substrate cost premiums:Polylactic acid and cellulose-based materials carry 40-60% unit cost disadvantages versus conventional polypropylene stocks.
- Microencapsulation chemistry concentration:Reactive dye formulation expertise clusters with three specialized European chemical converters.
- Extended producer responsibility friction:France's packaging waste fee structures create accounting complexity that slows retailer adoption decisions.
Strategic Opportunities
- Underpenetrated vegetable segments:Perishability premiums in herbs and leafy greens have not yet justified unit-cost investments that fruits command.
- Time-temperature indicator convergence:Integration of chromogenic dyes with printed electronics enables smartphone-readable freshness data.
- US FDA labeling integrity enforcement:Stricter adhesive migration surveillance creates compliance-driven replacement cycles for non-conforming label stocks.
Industry Challenges
- Food safety auditor scarcity:Qualified ISO 22000 certification bodies face backlogs that extend supplier qualification timelines by 8-14 months.
- Legacy inventory system integration:ERP platforms at mid-tier produce distributors lack API compatibility with sensor-label data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ripeness Indicator Labels Market |
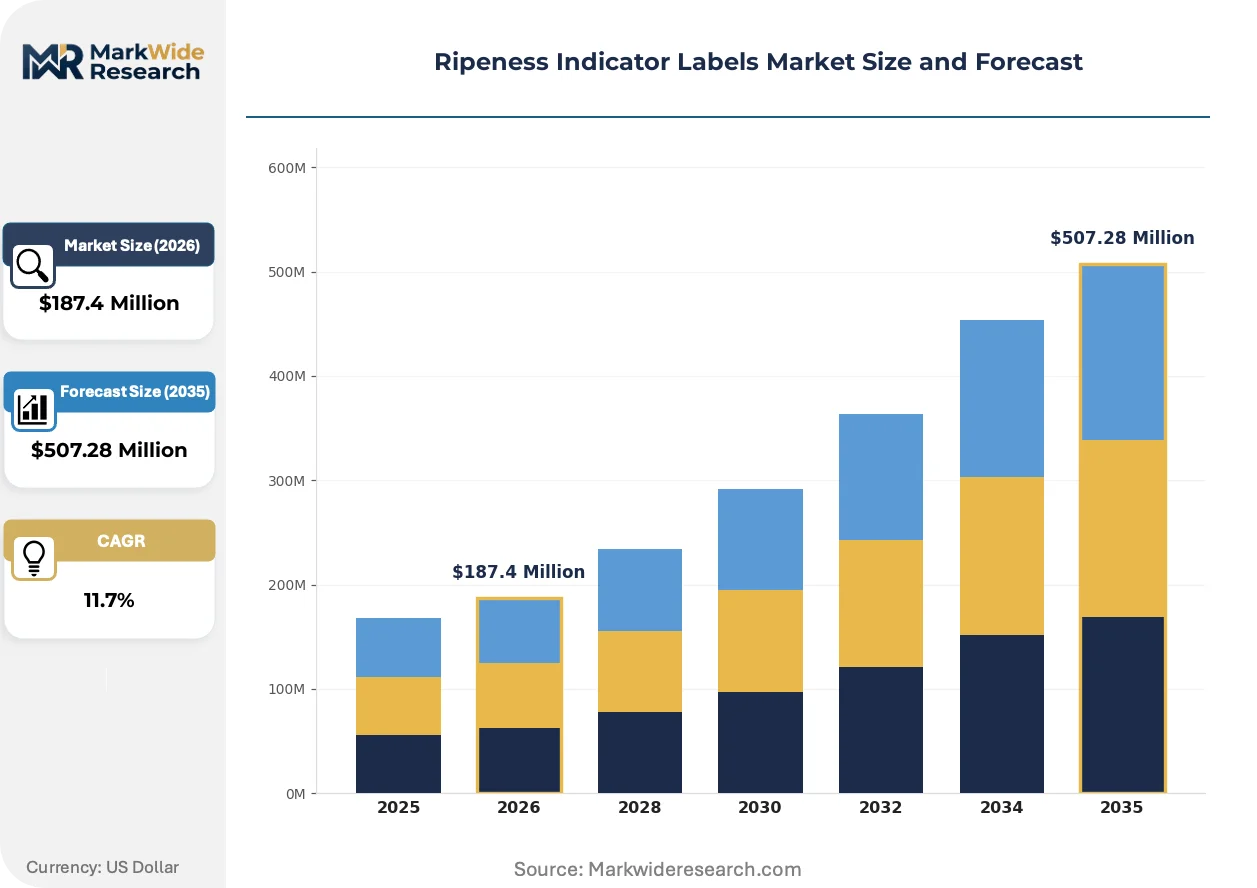
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Sticker, Tag, Sensor, Marker Material: Paper, Plastic, Biodegradable, Vinyl Application: Fruits, Vegetables, Herbs, Snacks End User: Retailers, Growers, Distributors, Consumers |
| Companies Covered | Jenkins Group, CCL Industries, Faubel, JH Bertrand, Denny Bros Holdings, CS Labels, Insignia Technologies, Freshpoint Label, Varcode, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ripeness Indicator Labels Market Evolving Landscape
Material science advances and regulatory compliance automation are compressing product development cycles while expanding the functional boundaries of what adhesive labels can communicate across cold-chain logistics.
Chromogenic ethylene detection chemistry is collapsing the cost barrier between premium sensor labels and commodity stickers. Mid-sized North American produce distributors now specify colorimetric indicators for stone fruit and avocado categories previously served by undifferentiated date-code labels. This technology compression enables private-label retailers to deploy freshness communication at scale without absorbing full electronic sensor costs.
REACH substance restrictions on certain adhesive plasticizers are forcing reformulation of pressure-sensitive label stocks across European converting operations. Suppliers serving German discount grocery chains must now validate alternative tackifier chemistries through ECHA notification procedures. The regulatory burden falls heaviest on small-format label converters lacking in-house toxicology assessment capabilities.
Retail buyer consolidation around centralized produce procurement desks is compressing supplier negotiation cycles and unbundling technical service from unit pricing. Major US supermarket cooperatives now source ripeness indicators through dedicated packaging category managers rather than decentralized store-level purchasing. This channel transformation concentrates volume with converters offering pan-national logistics and consolidated invoicing systems.
Ripeness Indicator Labels Market Segmentation
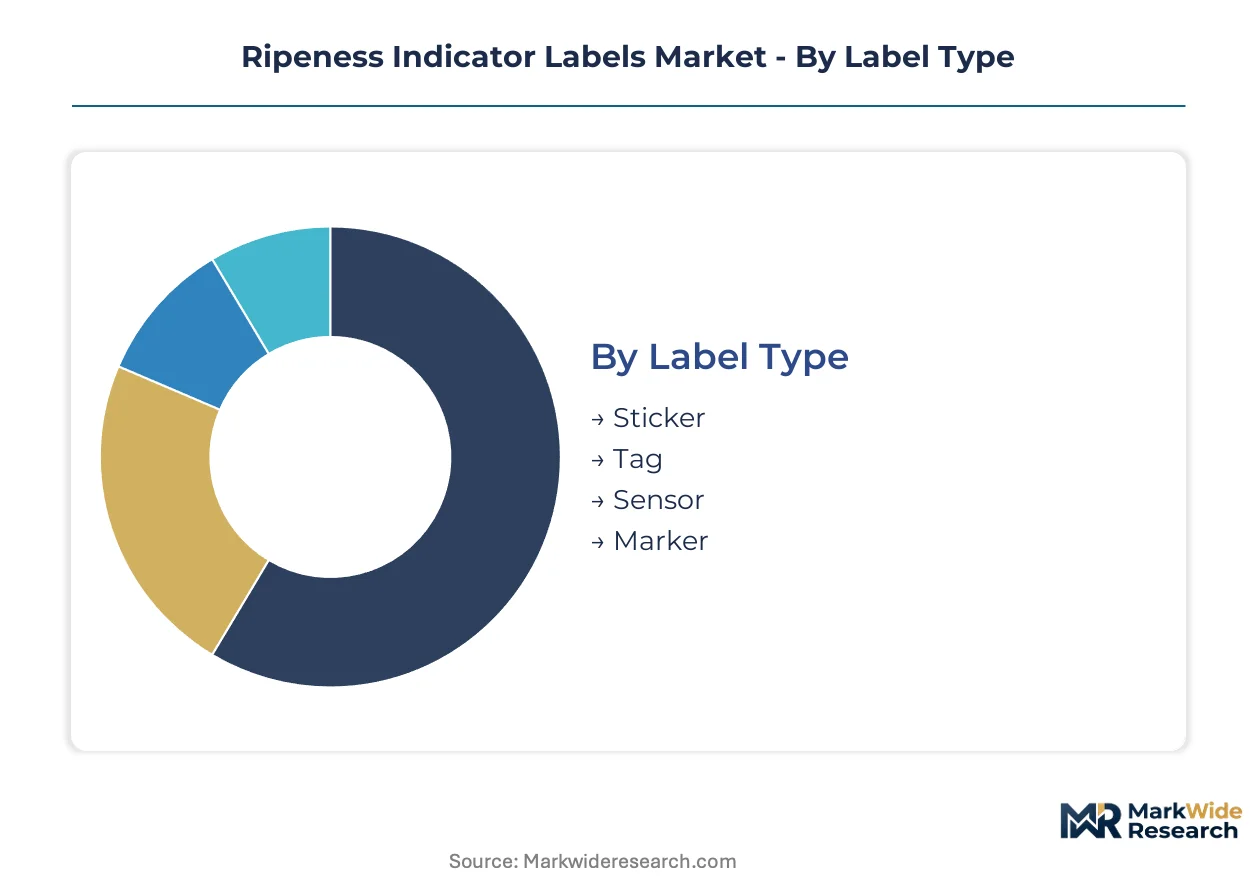
Ripeness indicator labels serve divergent technical and economic requirements across the fresh produce supply chain. Segmentation reveals where adhesive chemistry investments concentrate versus where commodity formats suffice.
Label Type:
Cost tier determines functional complexity and unit economics across adhesive formats.
- Sticker:Pressure-sensitive adhesive labels with chromogenic dye microencapsulation dominate high-volume stone fruit and avocado applications. German discount grocery chains specify these for centralized procurement of seasonal produce programs.
- Sensor:Printed electronics integrated with time-temperature indicator chemistry enable smartphone-readable freshness data. North American multinational produce distributors anchor premium contracts for cold-chain monitoring of berries and tropical imports.
- Tag:Suspended format indicators attach to stem or netting for bulk-display items.
- Marker:Direct-print chromogenic strips applied during packaging line operations.
Sticker formats command the established base. The steepest expansion runs through sensor integration with digital supply chain platforms.
Material:
Application environment and regulatory compliance dictate substrate selection across biodegradable and conventional stocks.
- Biodegradable:Polylactic acid and cellulose-based substrates carry 40-60% unit cost premiums but satisfy EU Green Deal packaging mandates. French and German retailers face extended producer responsibility fee structures that recalibrate total cost-of-ownership calculations.
- Plastic:Polypropylene stocks retain cost advantage for conventional supply chains outside regulated European markets.
- Paper:Uncoated and coated grades serve short-shelf-life applications with minimal moisture exposure.
- Vinyl:Synthetic substrates withstand high-humidity cold-chain environments for tropical produce logistics.
Plastic materials anchor incumbent volume. Biodegradable alternatives are gaining share fastest as REACH substance restrictions and ECHA notification procedures reshape European converter operations.
Application:
Perishability premiums and spoilage loss exposure create divergent willingness-to-pay across produce categories.
- Fruits:Ethylene-sensitive categories—avocados, stone fruits, berries—justify unit-cost investments through inventory turnover gains and waste reduction. Precision agriculture adoption in Germany concentrates procurement pull for ethylene-detection labels.
- Vegetables:Leafy greens and brassicas present underpenetrated expansion opportunity as perishability premiums have not yet matched fruit segment economics.
- Herbs:High-value but low-volume category with limited current label penetration.
- Snacks:Processed and packaged applications with minimal freshness-indicator relevance.
Fruit applications command the established base. Vegetable segments present the steepest expansion trajectory as retailers extend waste-reduction programs downstream from high-value categories.
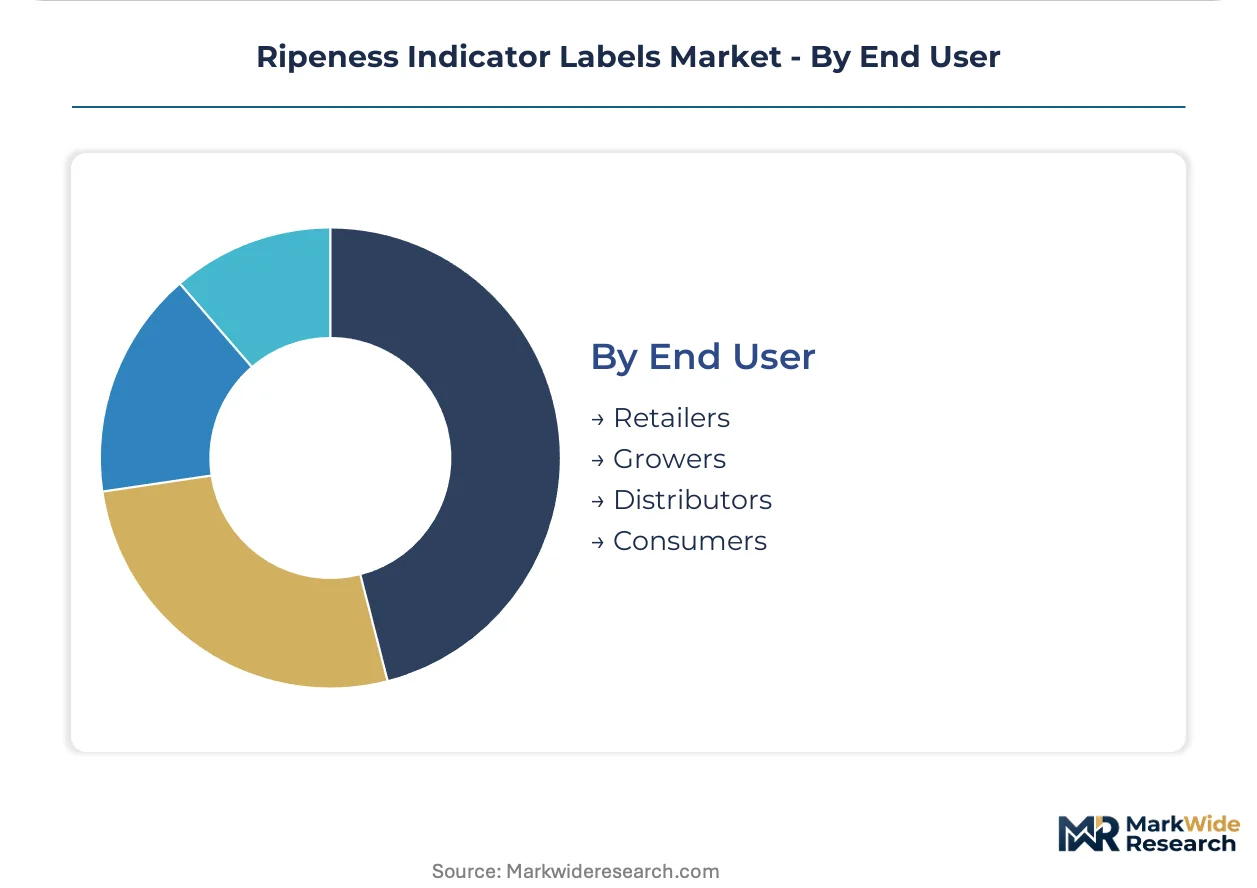
End User:
Customer type shapes procurement scale, technical specification complexity, and service bundling requirements.
- Retailers:Centralized produce procurement desks at US supermarket cooperatives compress supplier negotiation cycles and demand pan-national logistics with consolidated invoicing systems.
- Distributors:Mid-tier produce distributors specify colorimetric indicators for categories previously served by undifferentiated date-code labels.
- Growers:Direct specification remains limited to integrated operations with captive packing facilities.
- Consumers:Minimal direct procurement; indirect demand through retail-branded private label programs.
Retailers command the established base. Distributor channel consolidation drives the steepest expansion as procurement centralization concentrates volume with converters offering technical service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retailers deploy ethylene-sensitive labels for precision agriculture workflows while US distributors prioritize cost-efficient chromogenic stickers for stone fruit categories. This consumption-mix differential reflects tighter EU packaging mandates against North America's volume-driven procurement logic.
Germany
Discount grocery chains specify centralized ripeness indicator programs for seasonal produce, with Bavarian packing houses driving ethylene-detection adoption. The EU Packaging and Packaging Waste Regulation mandates recyclability disclosures that favor biodegradable substrate suppliers. Stuttgart-area converters qualify polylactic acid stocks through ECHA notification procedures for extended producer responsibility compliance.
United States
Mid-sized produce distributors specify colorimetric indicators for avocados and stone fruits previously served by date-code labels. FDA adhesive migration surveillance creates compliance-driven replacement cycles for non-conforming label stocks. California's Central Valley integrated packing operations anchor the highest concentration of sticker-format procurement volume.
France
Retail buyers consolidate around centralized produce procurement desks that compress supplier negotiation cycles. Extended producer responsibility fee structures recalibrate total cost-of-ownership calculations for biodegradable versus conventional plastic stocks. Île-de-France-based supermarket cooperatives demand pan-national logistics with consolidated invoicing systems.
United Kingdom
Private-label retailers deploy freshness communication at scale without absorbing full electronic sensor costs. REACH substance restrictions on adhesive plasticizers force reformulation of pressure-sensitive stocks through ECHA procedures. Midlands-based label converters face regulatory burden concentration lacking in-house toxicology assessment capabilities.
Netherlands
Rotterdam cold-chain logistics hubs specify sensor-integrated labels for tropical import monitoring through smartphone-readable platforms. The EU Green Deal accelerates biodegradable material qualification cycles across Dutch fresh produce supply chains. Eindhoven-region converters develop printed electronics integration for time-temperature indicator convergence.
Ripeness Indicator Labels Market Competitive Landscape
Capability concentration sits with specialized chemical converters; scale advantage sits with global label fabricators. The market structures around three tiers: multinational converters with pan-national logistics, mid-sized specialists in chromogenic chemistry, and regional sticker suppliers serving commodity produce segments. Dominant competitive moves include strategic partnerships between sensor-technology developers and retail procurement desks, plus portfolio diversification into biodegradable substrate qualification.
Within the specialized chemistry tier, Insignia Technologies and Faubel exemplify R&D-intensive positioning focused on reactive dye formulation and precision-printing calibration respectively. CCL Industries occupies a position at the scale-driven end, leveraging global converting infrastructure to anchor premium contracts with multinational produce distributors. These three entities represent the capability-scale spectrum: specialized chemistry expertise, precision-application calibration, and volume logistics integration.
| Leading Market Players |
|---|
| Jenkins Group |
| CCL Industries |
| Faubel |
| JH Bertrand |
| Denny Bros Holdings |
| CS Labels |
| Insignia Technologies |
| Freshpoint Label |
| Varcode |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp freight corridors shape cost dynamics across European ripeness indicator supply chains, concentrating pricing power with converters qualifying biodegradable substrates through ECHA notification procedures while downstream price differentiation separates compliant German retailers from cost-focused North American distributors.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational produce distributors and global label fabricators, while spot purchasing persists for mid-tier distributors specifying chromogenic stickers. Price differentiation hinges on ISO 22000 certification tier and volume scale, with certified suppliers commanding premiums over commodity sticker vendors. Cost compression in biodegradable substrates is intensifying because polylactic acid qualification cycles extend supplier overhead recovery timelines. Small-format vegetable growers exhibit highest price sensitivity; cold-chain logistics operators for tropical imports show least.
Supply Chain Analysis
Extended payment terms from German discount grocery chains are squeezing working capital for mid-sized European converters, accelerating supply-chain finance facility adoption. Manufacturing concentrates in Germany, the United States, and the Netherlands, with reactive dye formulation expertise anchored in specialized European chemical operations. Raw material dependencies include polylactic acid resins, microencapsulated chromogenic dyes, and pressure-sensitive adhesive stocks. Single-source vulnerability runs through concentrated reactive dye suppliers. Distribution feeds from converter operations through centralized produce procurement desks at supermarket cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as retail buyer consolidation around centralized procurement desks creates niches for specialized chemistry converters and biodegradable substrate innovators.
For Market Incumbents: Harden technical service bundling against unbundling pressure from category managers demanding consolidated invoicing. Deepen backward integration into microencapsulation chemistry to secure reactive dye supply against European converter concentration. Anchor capacity expansion in Stuttgart-area polylactic acid qualification hubs to capture EU Green Deal compliance premiums.
For New Entrants and Emerging Players: Pursue underpenetrated vegetable segments where perishability premiums have not yet justified fruit-category unit-cost investments. Target herb and leafy green applications through distributor channel partnerships bypassing centralized retail procurement. Lead with smartphone-readable sensor integration as differentiated go-to-market positioning against commodity sticker incumbents.
For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation enforcement reshapes the acquisition landscape toward biodegradable substrate qualification capabilities. Five-to-ten year viability favors converters with ECHA notification expertise and pan-national logistics infrastructure. Target mid-sized specialists in chromogenic chemistry with precision-printing calibration. Watch France's extended producer responsibility fee structure implementation as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Qualification | ECHA notification procedures unlock EU Green Deal compliance premiums for German retailers. |
| Backward Integration into Microencapsulation | In-house reactive dye production reduces dependency on three specialized European chemical converters. |
| Sensor-Platform Integration | Smartphone-readable freshness data anchors premium contracts with North American cold-chain operators. |
| Centralized Procurement Desk Partnerships | Pan-national logistics capabilities align with US supermarket cooperative consolidation trends. |
| ISO 22000 Certification Investment | Food safety management certification operates as de facto market-access threshold for major retail chains. |
Research Methodology
Cross-validation between primary interviews with produce procurement managers, label converter operations directors, and regulatory compliance officers anchors the qualitative findings against secondary validation through EU Packaging and Packaging Waste Regulation filings, FDA adhesive migration surveillance records, and ECHA substance restriction databases. Bottom-up demand modeling from distributor specification trends triangulates with top-down market sizing from biodegradable substrate trade flows and chromogenic dye import data.
Calibration against historical adoption curves for ethylene-detection labels across German precision agriculture workflows and US stone fruit categories shapes the analytical framework. Segmentation dimensions span label type, material substrate, produce application, and end-user procurement scale. CAGRs derive from logistic growth curve fitting to technology diffusion patterns. Forecast inputs include ECHA notification procedure throughput rates and centralized retail procurement desk expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by polylactic acid resin suppliers or breakthrough printed electronics cost reduction would shift outcomes. Macroeconomic deviation in fresh produce trade flows, regulatory acceleration of extended producer responsibility frameworks, or smartphone-integrated sensor technology breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Kraft Labels Market
Labels
Global Tamper Evident Labels Market
Labels
Global Sensormatic Labels Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Primary Packaging Labels Market
Labels
Holographic Labels Market
Labels
Multi-Part Labels Market
Labels
Wet Glue Labeling Machines Market
Labels
India Print Label Market
Labels
Linerless Labels Market
Labels
Die Cut Labels Market
Labels
Heat Shrink Sleeve Market
Labels
Warning Labels and Stickers Market
Labels
Braille Labels Market
Labels
Direct Thermal Linerless Labels Market
Labels
Print Label Market