
 Pre-Gummed Labels Market | 2026-2036
Pre-Gummed Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Gummed Labels Market Analytics
The pre-gummed labels market is repositioning around a widening split between premium specialty substrates and commodity paper grades. Avery Dennison leverages its materials science portfolio to dominate high-performance adhesive formulations. Consolidated Label specializes in short-run custom work for craft and boutique branding segments. CCL Industries anchors global volume through its multi-continent manufacturing footprint.
Pre-gummed labels are pressure-sensitive adhesive labels supplied with a pre-applied gum or resin-based adhesive layer protected by a release liner, typically activated by moisture or pressure without requiring separate adhesive application equipment. Roll labels lead volume in automated packaging lines, while eco-friendly material grades represent the fastest-expanding margin pool as brand owners face Scope 3 emissions scrutiny. Sheet labels retain strength in office supplies and small-batch crafting where desktop printers set the workflow pace.
FDA food-contact regulations govern adhesive migration limits for labels applied directly to consumable goods in the United States. The EU Packaging and Packaging Waste Regulation, alongside ECHA REACH compliance for adhesive chemistries, shapes substrate and formulation choices across European supply chains. Stakeholders must monitor how extended producer responsibility frameworks reshape cost allocation between label converters and their brand-owner customers.
Market Dynamics
The pre-gummed labels market is bifurcating around moisture-activated versus pressure-activated adhesive chemistries, with EU Packaging and Packaging Waste Regulation compliance costs forcing substrate reformulation across European supply chains.
Growth Catalysts
- E-commerce logistics automation:Parcel sortation hubs in Germany's Rhine-Ruhr corridor are retrofitting lines for roll-fed pre-gummed shipping labels, eliminating wet-glue stations.
- REACH-compliant bio-adhesives:ECHA authorization pathways for synthetic resin alternatives are accelerating plant-derived gum arabic formulations in food-contact applications.
- Scope 3 emissions accounting:Brand owners facing CSRD disclosure mandates are specifying FSC-certified face stocks with verified carbon footprints.
Market Restraints
- Release liner cost volatility:Silicone-coated glassine paper prices fluctuate with pulp futures, squeezing converter margins on commodity-grade sheet labels.
- Adhesive migration limits:FDA 21 CFR 175.105 testing timelines for indirect food-contact labels extend qualification cycles by 8-14 months.
- Digital print substitution:Thermal transfer and inkjet direct-to-package systems in short-run pharmaceutical labeling are displacing pre-gummed stock for serialized compliance codes.
Strategic Opportunities
- Extended producer responsibility frameworks:France's Citeo eco-modulation fees reward recyclable adhesive formulations, creating margin pools for wash-off hot-melt alternatives.
- Cold-chain pharmaceutical logistics:Temperature-stable acrylic adhesives for vaccine distribution labels represent an underpenetrated specification tier.
- Smart label convergence:Integration of NFC inlays with pre-gummed construction is electrifying traceability demand in luxury goods authentication.
Industry Challenges
- Adhesive chemist talent scarcity:Formulation expertise spanning pressure-sensitive rheology and food-contact safety is concentrated among retiring specialists in Basel and Ludwigshafen clusters.
- Legacy ERP integration:Converter MRP systems require custom middleware to track lot-level adhesive batch genealogy for EU Medical Device Regulation compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Gummed Labels Market |
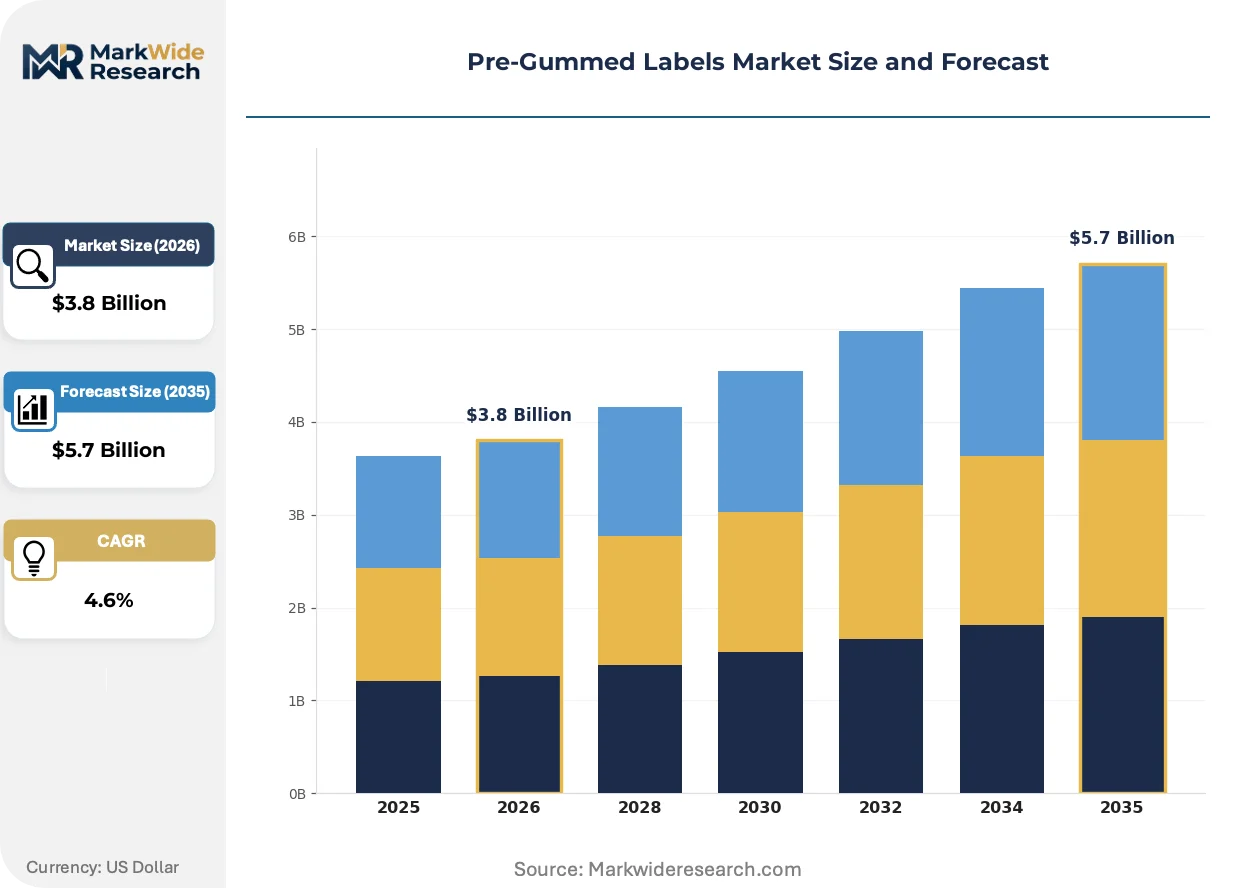
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll Labels, Sheet Labels, Custom Labels, Blank Labels Application: Packaging, Shipping, Branding, Crafting Material: Paper, Plastic, Vinyl, Eco-Friendly End User: Retail, Manufacturing, Logistics, Office Supplies |
| Companies Covered | Fortis Solutions Group, Consolidated Label, Avery Dennison, Multi-Color Corporation, Maverick Label, CCL Industries, Resource Label Group, WS Packaging Group, SAQ Labels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Gummed Labels Market Evolving Landscape
Water-based adhesive activation is displacing solvent systems as the dominant technical trajectory, with sustainability mandates and workplace safety regulations converging to reshape formulation priorities across packaging verticals.
Hot-melt moisture-activated adhesives with sub-second tack development are electrifying high-speed beverage canning lines. Coca-Cola European bottlers in France and Germany have retrofitted 600-container-per-minute fillers with these formulations. The technology is compressing changeover downtime and enabling thinner face-stock specifications that reduce fiber tonnage per thousand labels.
EU Packaging and Packaging Waste Regulation recyclability performance grades are mandating wash-off adhesive standards for PET container labels. Italian olive oil exporters and German dairy processors must reformulate by 2025 to avoid eco-modulation penalties. The regulation is forcing converters to maintain dual adhesive inventories: standard permanent grades for non-recyclable applications and alkaline-dispersible formulations for rPET streams.
Brand-owner sustainability scorecards now weight adhesive carbon intensity alongside substrate sourcing. Unilever and Nestlé procurement teams in the Netherlands and Switzerland are requesting cradle-to-gate LCA documentation for gum resin supply chains. This behavioral shift is compressing supplier qualification timelines and favoring converters with in-house life-cycle assessment capabilities.
Pre-Gummed Labels Market Segmentation
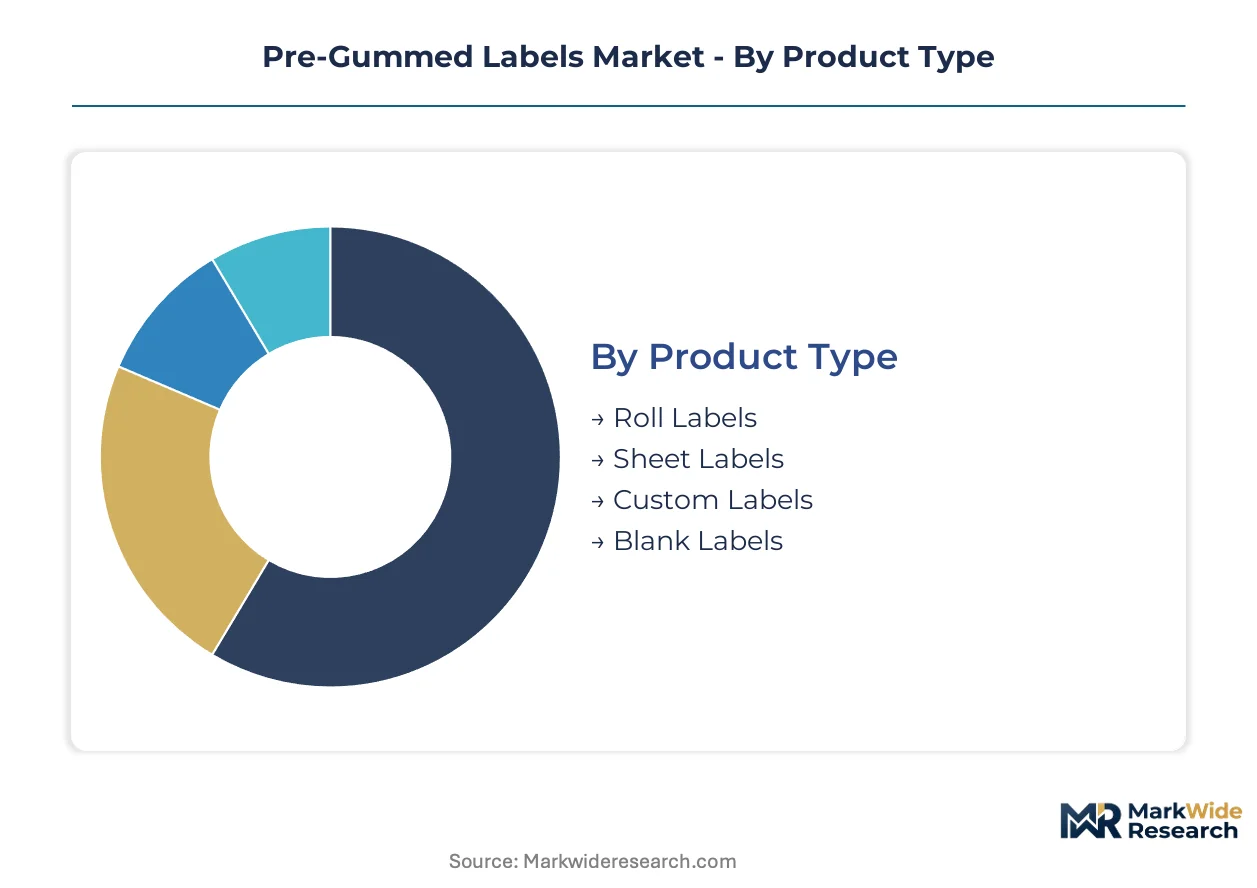
Pre-gummed labels serve divergent operational workflows across automated packaging lines, desktop printing environments, and hand-application stations. Understanding how product formats, material specifications, and end-use requirements intersect reveals where converter investments in adhesive formulation and substrate engineering generate sustainable margin premiums.
Product Type:
Roll formats dominate continuous-feed industrial integration, while sheet configurations anchor intermittent-use workflows where standalone activation matters most.
- Roll Labels:Continuous-web construction with perforated or butt-cut edges enables high-speed dispensing on automated applicators. Demand concentrates in German beverage canning facilities and Rhine-Ruhr logistics hubs where 600-container-per-minute lines require sub-second tack development. REACH-compliant bio-adhesive formulations are accelerating adoption in food-contact applications.
- Sheet Labels:Individual A4 or letter-sized pages feed through desktop laser and inkjet printers for small-batch production. Office supply retailers in France and Switzerland stock these for craft, boutique branding, and serialized pharmaceutical compliance where print-on-demand flexibility outweighs unit economics.
- Custom Labels:Die-cut shapes and specialty face stocks serve brand-owner sustainability scorecards requiring FSC-certified substrates with verified cradle-to-gate carbon documentation.
- Blank Labels:Unprinted stock allows end-users to apply variable data through thermal transfer or direct thermal printing in cold-chain pharmaceutical distribution.
Roll labels lead volumes today; custom labels are gaining share fastest.
Application:
Functional requirements split between protective transit documentation and permanent brand communication on primary packaging.
- Packaging:Primary container labels for food, beverage, and personal care products must satisfy FDA 21 CFR 175.105 migration limits and EU wash-off recyclability standards. Italian olive oil exporters and German dairy processors face dual inventory requirements for standard permanent and alkaline-dispersible adhesive grades.
- Shipping:E-commerce logistics operators in Germany's industrial corridor retrofit parcel sortation hubs with roll-fed pre-gummed formats, eliminating wet-glue stations and compressing changeover downtime.
- Branding:Luxury goods authentication integrates NFC inlays with pre-gummed construction, electrifying traceability demand among Swiss watchmakers and French cosmetics houses.
- Crafting:Small-batch decorative applications favor sheet formats compatible with consumer-grade cutting machines and desktop printers.
Shipping applications lead volumes today; packaging is climbing the fastest.
Material:
Substrate selection determines recyclability performance grades under extended producer responsibility frameworks.
- Paper:Glassine and kraft face stocks dominate commodity volume, though silicone-coated release liner cost volatility squeezes converter margins. FSC certification is becoming table stakes for Unilever and Nestlé procurement teams.
- Plastic:BOPP and PET films offer moisture resistance for beverage and chemical labeling, but face mounting pressure from EU Packaging and Packaging Waste Regulation eco-modulation fees.
- Vinyl:Flexible PVC constructions serve curved container surfaces and outdoor durability requirements in industrial manufacturing.
- Eco-Friendly:Wash-off hot-melt alternatives and plant-derived gum arabic formulations capture margin pools from France's Citeo incentive structures and CSRD disclosure mandates.
Paper leads volumes today; eco-friendly grades show the steepest expansion trajectory.
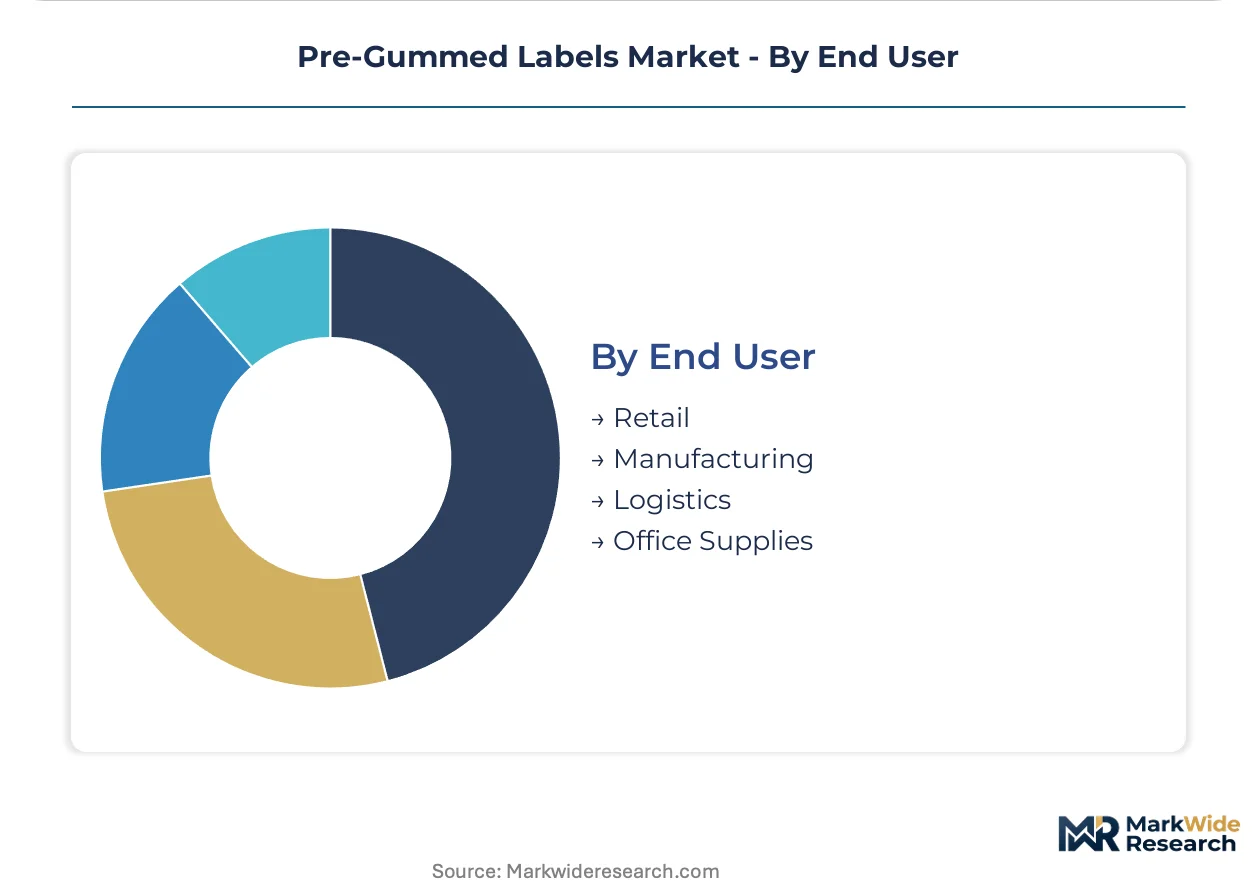
End User:
Procurement sophistication varies sharply between price-sensitive office supply channels and specification-heavy industrial accounts.
- Retail:Private-label and branded goods manufacturers specify adhesive performance across temperature ranges and container substrates. Cold-chain pharmaceutical logistics represent an underpenetrated specification tier for temperature-stable acrylics.
- Manufacturing:High-volume German automotive and chemical producers in Ludwigshafen and Basel clusters demand lot-level adhesive batch genealogy for EU Medical Device Regulation compliance.
- Logistics:Parcel carriers and third-party fulfillment operators prioritize activation speed and print compatibility over face-stock aesthetics.
- Office Supplies:Stationery wholesalers and e-commerce marketplaces stock commodity sheet labels where price per thousand drives assortment decisions.
Manufacturing leads volumes today; retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive chemists cluster in Basel and Ludwigshafen, anchoring European formulation expertise. Their concentration shapes where converters locate technical centers and qualification laboratories.
Germany
Beverage canning lines in the Rhine-Ruhr corridor demand sub-second tack development for 600-container-per-minute operations. ECHA REACH compliance mandates bio-adhesive alternatives for food-contact applications. Ludwigshafen chemical parks host formulation R&D for wash-off hot-melt grades serving dairy processors.
United States
FDA 21 CFR 175.105 migration limits extend qualification cycles for indirect food-contact labels by 8-14 months. E-commerce logistics operators retrofit parcel hubs with roll-fed formats, eliminating wet-glue infrastructure. Chicago and Dallas distribution corridors concentrate converter warehousing for mid-continental fulfillment.
France
Citeo eco-modulation fees reward recyclable adhesive formulations, creating margin pools for alkaline-dispersible alternatives. Olive oil exporters face 2025 reformulation deadlines for PET container labels. Paris-based procurement teams at Unilever and Nestlé request cradle-to-gate LCA documentation from gum resin suppliers.
Italy
Olive oil and wine exporters navigate dual inventory requirements for standard permanent and wash-off adhesive grades. EU Packaging and Packaging Waste Regulation recyclability performance grades mandate substrate reformulation. Emilia-Romagna packaging converters specialize in short-run custom work for craft branding segments.
Switzerland
Swissmedic medical device regulations require lot-level adhesive batch genealogy tracking for pharmaceutical labeling. CSRD disclosure mandates drive brand-owner specification of FSC-certified face stocks with verified carbon footprints. Basel clusters concentrate retiring adhesive chemist expertise in pressure-sensitive rheology.
Pre-Gummed Labels Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the pre-gummed labels market. Integrated substrate manufacturers with captive adhesive formulation capabilities occupy positions distinct from converters relying on third-party resin supply. Three archetypes dominate: diversified materials science conglomerates, mid-scale regional converters, and specialized short-run custom shops. M&A activity concentrates on acquiring REACH-compliant bio-adhesive formulation capabilities, while capacity expansion targets high-speed roll-fed lines for e-commerce logistics.
Among North American converters, Fortis Solutions Group and Consolidated Label exemplify contrasting scale positions within the custom-label archetype. Avery Dennison anchors the materials science tier with integrated substrate and adhesive portfolios. CCL Industries represents the multi-continent manufacturing footprint model, leveraging distributed production to serve brand-owner sustainability scorecard requirements across European and North American supply chains.
| Leading Market Players |
|---|
| Fortis Solutions Group |
| Consolidated Label |
| Avery Dennison |
| Multi-Color Corporation |
| Maverick Label |
| CCL Industries |
| Resource Label Group |
| WS Packaging Group |
| SAQ Labels |
| Others |
Value Network & Pricing Analysis
EU Packaging and Packaging Waste Regulation recyclability mandates are forcing brand owners to dual-source adhesive grades, compelling converters to maintain parallel inventories of standard permanent and alkaline-dispersible formulations that compress margins on commodity tiers.
Pricing Analysis
Bundled formulation-plus-certification services command premiums over unbundled commodity stock. Three-tier pricing structure across REACH-compliant specialty, FSC-certified standard, and uncoated economy levels separates converters by compliance depth. Price differentiation hinges on ECHA authorization status and volume scale. Pricing pressure stems from silicone-coated release liner cost volatility squeezing converter margins. Office supply channels exhibit highest price sensitivity; pharmaceutical and luxury goods buyers prioritize lot-level traceability over unit economics.
Supply Chain Analysis
Freight costs for silicone-coated glassine release liners fluctuate with pulp futures, amplifying margin vulnerability for sheet-label converters lacking long-term resin contracts. Raw material supply concentrates in Germany, Italy, and Switzerland where adhesive formulation expertise clusters around Basel and Ludwigshafen chemical parks. The supply chain draws from gum arabic harvests in Sudan and Chad, petroleum-derived synthetic resins, and FSC-certified pulp stocks. Single-source vulnerability sits with specialty silicone coating capacity for release liners. Distribution runs through converter technical centers serving Rhine-Ruhr logistics hubs and Paris-based procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pre-gummed labels market functions as a regulatory compounder where EU Packaging and Packaging Waste Regulation eco-modulation fees and CSRD disclosure mandates continuously reshape procurement specifications and supplier qualification requirements.
For Market Incumbents: Anticipate adhesive chemist retirement waves in Basel and Ludwigshafen by capturing formulation IP through structured knowledge-transfer programs and accelerated plant-derived gum arabic R&D. Defend margin position against digital print substitution in pharmaceutical serialization by embedding temperature-stable acrylic adhesives into cold-chain logistics contracts. Prioritize wash-off hot-melt capacity expansion to capture Citeo incentive structures in France. For New Entrants and Emerging Players: Boutique craft distillers and olive oil exporters in Italy represent an underserved buyer archetype requiring short-run custom labels with dual-adhesive flexibility for EU and non-EU export markets. White-space opportunity concentrates in NFC-integrated luxury authentication for Swiss watchmakers and French cosmetics houses. Penetrate through sustainability scorecard partnerships offering cradle-to-gate LCA documentation that Unilever and Nestlé procurement teams now mandate. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale converters possessing in-house REACH-compliant bio-adhesive formulation capabilities and established brand-owner sustainability audit relationships. Five-to-ten year viability favors assets with multi-substrate engineering competence spanning paper, BOPP, and emerging eco-friendly grades. Watch for inflection in extended producer responsibility framework expansion beyond France into Germany and Italy as acquisition timing signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gum Resin Supply | Secures plant-derived adhesive feedstock for ECHA REACH-compliant food-contact formulations. |
| Wash-Off Hot-Melt Capacity Expansion | Captures Citeo eco-modulation margins from French dairy and beverage exporters facing 2025 deadlines. |
| NFC Inlay Integration Partnership | Electrifies traceability demand among Swiss watchmakers and French luxury cosmetics houses. |
| Cold-Chain Pharmaceutical Certification | Opens underpenetrated specification tier for temperature-stable acrylic adhesives in vaccine distribution. |
| Life-Cycle Assessment Capability Buildout | Meets Unilever and Nestlé procurement requirements for verified cradle-to-gate carbon documentation. |
Research Methodology
Direct dialogue with adhesive formulation chemists, label converter operations directors, brand-owner procurement leads, and EU regulatory affairs specialists grounded this analysis. Primary insights combined with secondary validation from ECHA authorization databases, FDA 21 CFR 175.105 guidance documents, EU Packaging and Packaging Waste Regulation impact assessments, and FSC chain-of-custody certification records. Bottom-up volume modeling across adhesive chemistry tiers triangulated against top-down market sizing from trade flow data.
Segmented projections emerged across roll, sheet, custom, and blank label formats intersecting with packaging, shipping, branding, and crafting applications. Material-grade splits between paper, plastic, vinyl, and eco-friendly substrates anchored the analytical framework across the projection horizon. CAGRs derived from regression analysis of historical adoption curves for moisture-activated versus pressure-activated adhesive technologies, adjusted for regulatory acceleration effects from extended producer responsibility frameworks.
Underlying measurement precision varies by segment; roll labels and e-commerce shipping applications carry tighter precision than fragmented office supply channels. Forecasts embed assumptions regarding ECHA bio-adhesive authorization timelines and CSRD disclosure mandate enforcement intensity. Stakeholders should weight assumptions against their own operating context and regional regulatory implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Repositionable Labels Market
Labels
Global Label Adhesive Market
Labels
Screen Print Label Market
Labels
Self-Laminating Tags Market
Labels
North America Self-Adhesive Labels Market
Labels
Global Security Labels Market
Labels
Primary Packaging Labels Market
Labels
Sustainable Labels Market
Labels
HAZMAT Labels Market
Labels
Global Pressure Labels Market
Labels
Inspection and Inventory Labels Market
Labels
Braille Labels Market
Labels
Freezer Label Market
Labels
GHS Labels Market
Labels
Future-Proof Pharma Labels Market
Labels
Laser Markable Labels Market