
 Sustainable Labels Market | 2026-2036
Sustainable Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Labels Market Analytics
Food and beverage is pivoting toward compostable and recyclable label formats as major retailers impose packaging sustainability scorecards. Avery Dennison leverages its materials science portfolio to supply thin-film and paper-based solutions with certified recyclable adhesives. Constantia Flexibles anchors European supply through its specialized sustainable packaging division, while UPM Raflatac competes with bio-based face stock programs certified under forest stewardship protocols.
Sustainable labels are pressure-sensitive or adhesive-backed identifiers manufactured from recycled, renewable, or certified biodegradable substrates including FSC paper, PLA films, and post-consumer recycled plastics, designed to maintain print fidelity and adhesion performance while enabling end-of-life recyclability or compostability. Paper-based face stocks dominate current volume due to established recycling infrastructure and consumer familiarity, though plastic alternatives from bio-derived sources are capturing faster growth as cold-chain and moisture-resistant applications expand. Digital printing technology leads technology-based margin pools by eliminating plate costs and enabling shorter runs for brand versioning, while flexographic printing sustains scale economics for food and beverage volume contracts.
The EU Green Deal and REACH frameworks restrict hazardous adhesive chemistries and mandate recyclability disclosures, directly shaping product formulation roadmaps and supplier qualification requirements in Europe. FDA food contact regulations and state-level extended producer responsibility laws in California and New York govern US market access and material approvals. Stakeholders must monitor evolving certification schemes and regional packaging waste directives to align R&D investments with compliance timelines and avoid stranded inventory positions.
Market Dynamics
Retailer sustainability scorecards are forcing rapid material substitutions across label supply chains, compressing qualification timelines from 18 months to under 9 months as converters race to certify compostable and recyclable formats.
Growth Catalysts
- EU Green Deal packaging mandates:REACH restrictions on hazardous adhesive chemistries are accelerating bio-based formulation adoption across European converters.
- Food and beverage brand procurement:Major retailers now require certified recyclable or compostable label formats as a condition of shelf placement.
- German converter clustering:Co-location of packaging converters and brand headquarters in Baden-Württemberg and Bavaria shortens technical qualification cycles.
Market Restraints
- PLA film supply concentration:Bio-based polymer production remains concentrated among a limited set of European chemical suppliers, creating input cost volatility.
- Recycling infrastructure gaps:Inconsistent collection and sorting systems across municipalities limit actual end-of-life recyclability for certified labels.
- Adhesive performance trade-offs:Bio-based adhesives currently exhibit reduced adhesion under cold-chain conditions compared to conventional petrochemical alternatives.
Strategic Opportunities
- Digital printing convergence:Combination of inkjet technology with water-based inks eliminates plate costs and enables mass customization for craft beverage brands.
- Extended Producer Responsibility expansion:California and New York state-level EPR laws create compliance service revenue streams for certified label suppliers.
- Moisture-resistant paper substrates:Stone paper and mineral-coated face stocks open personal care and household chemical applications previously reserved for plastic films.
Industry Challenges
- Multi-certification complexity:Brands must simultaneously navigate FSC chain-of-custody, OK Compost, and APR recyclability protocols with conflicting test methodologies.
- Legacy press reconfiguration:Converters face capital intensity from retrofitting flexographic lines for thinner film substrates and water-based ink systems.
- Adhesive chemist talent scarcity:Formulation expertise spanning petrochemical and bio-based polymer science concentrates among retiring specialists at established suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Labels Market |
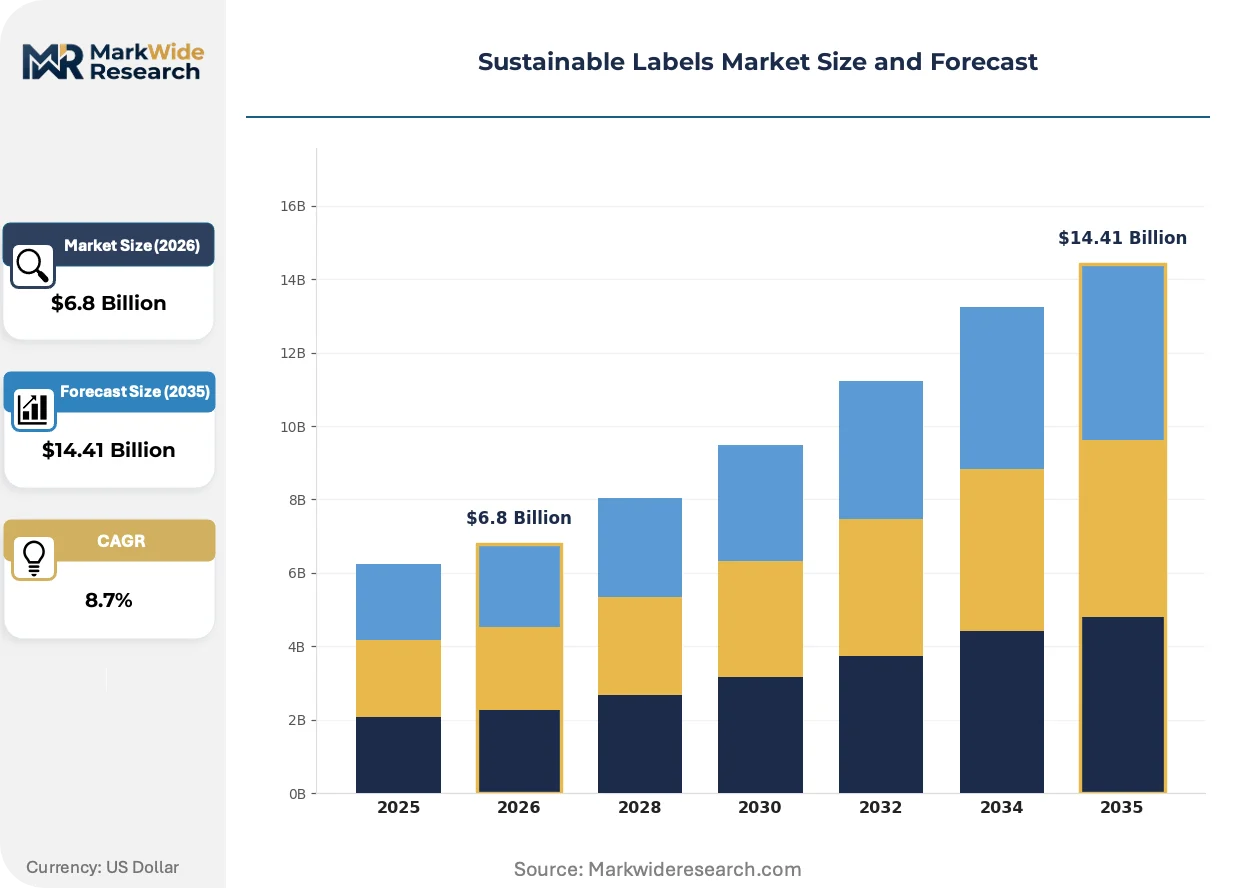
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Plastic, Metal, Fabric Application: Product Packaging, Shipping Labels, Brand Promotion, Pricing Tags Technology: Digital Printing, Flexographic Printing, Offset Printing, Screen Printing End User: Food & Beverage, Cosmetics, Electronics, Household Products |
| Companies Covered | Labels Unlimited, Constantia Flexibles, Avery Dennison, HUHTAMAKI, Amcor, CCL Industries, WS Packaging Group, UPM Raflatac, Multi-Color Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Labels Market Evolving Landscape
Material science breakthroughs and regulatory disclosure mandates are compressing product development cycles while fragmenting procurement authority from central packaging teams to sustainability officers and quality functions.
Laser die-cutting technology is rewriting production economics for short-run sustainable label orders. Craft spirits and specialty food brands in North America and Western Europe are adopting this equipment to eliminate tooling costs on seasonal and limited-edition SKUs. The technology is compressing minimum order quantities from 10,000 units toward 500-unit runs, enabling versioning strategies previously uneconomical for compostable formats.
REACH Article 33 disclosure requirements are forcing systematic chemical inventory audits across European label supply chains. Manufacturers must now document Substances of Very High Concern concentrations above 0.1% weight-by-weight in all adhesive and coating inputs. Food and beverage exporters to the EU are responding by pre-qualifying suppliers against ECHA's candidate list updates, shifting procurement criteria toward full formulation transparency.
Brand sustainability officers are consolidating label specification authority away from traditional packaging procurement teams. This organizational shift concentrates decision-making with executives accountable to CSRD reporting requirements and Science Based Targets initiative commitments. The pattern is most visible among multinational consumer packaged goods companies headquartered in Germany, France, and the Netherlands, where disclosure timelines accelerate material transitions.
Sustainable Labels Market Segmentation
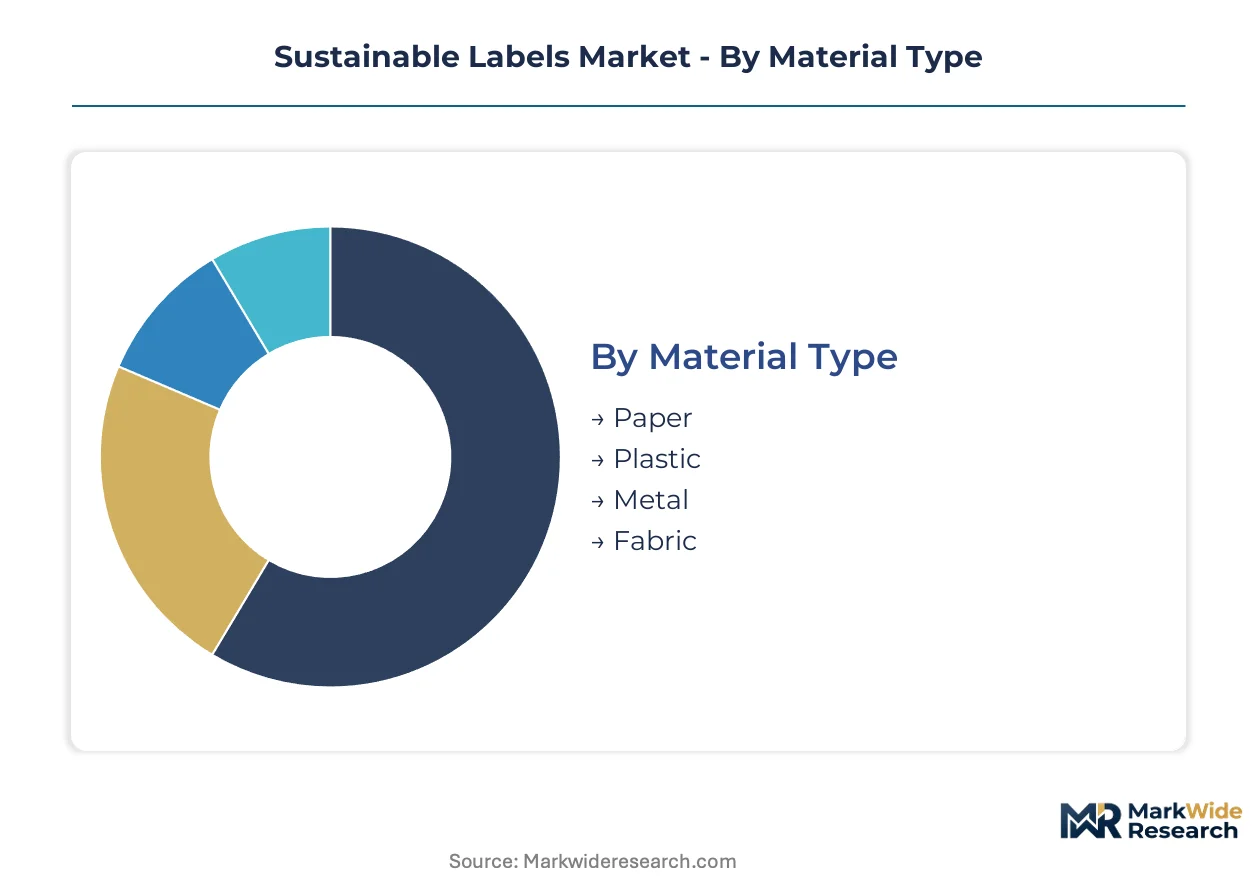
Material specifications and printing technology choices determine recyclability pathways and compliance eligibility for sustainable labels. Procurement teams segment specifications to match substrate performance against end-of-life requirements mandated by retailer scorecards and regional packaging laws.
Material Type:
Converters face recurring substrate upgrade cycles as REACH restrictions eliminate legacy adhesive systems and bio-based alternatives mature.
- Paper:FSC-certified face stocks and post-consumer recycled pulp grades dominate current procurement volumes. Food and beverage brands in Germany specify these substrates to meet retailer sustainability scorecards while leveraging established paper recycling infrastructure across the EU.
- Plastic:PLA films and bio-derived polyethylene substitutes capture expanding share in cold-chain and moisture-resistant applications. Demand concentrates among cosmetics and household product brands seeking barrier performance without compromising compostability certifications.
- Metal:Aluminum-based labels serve premium beverage and electronics segments requiring durability and heat resistance. European luxury goods brands specify thin-gauge metal substrates for circular economy compliance.
- Fabric:Woven and non-woven textile labels address apparel and reusable packaging applications. Specialty food brands in France adopt fabric identifiers for zero-waste retail concepts.
Volume placements concentrate in paper; the faster expansion belongs to plastic.
Application:
Application segmentation reflects diverging technical requirements across the value chain, from primary package identification through logistics tracking.
- Product Packaging:Primary labels on consumer goods face the strictest certification demands. Food and beverage brands in Baden-Württemberg pre-qualify compostable formats to meet EU Green Deal packaging mandates ahead of disclosure deadlines.
- Shipping Labels:E-commerce logistics drives demand for recyclable adhesive systems compatible with corrugated recycling streams. German packaging converters develop water-based adhesive formulations to satisfy dual certification under FSC and APR protocols.
- Brand Promotion:Promotional and limited-edition labels prioritize visual impact over end-of-life performance. Craft spirits producers leverage digital printing for short-run seasonal campaigns.
- Pricing Tags:Retail shelf labels require frequent update cycles and clean removability. Supermarket chains in Bavaria specify paper-based formats with certified recyclable adhesives.
Product packaging commands the largest placement volumes; shipping labels are climbing the fastest as e-commerce sustainability requirements tighten.
Technology:
Printing technology selection determines capital intensity, run-length economics, and ink chemistry compliance against evolving chemical disclosure rules.
- Digital Printing:Inkjet and toner-based systems eliminate plate costs and enable mass customization. Craft beverage brands adopt this technology for versioning strategies that were previously uneconomical at sub-1,000 unit quantities.
- Flexographic Printing:Rotogravure-style flexo lines sustain scale economics for food and beverage volume contracts. Major converters in Germany operate retrofitted equipment for thinner film substrates and water-based ink systems.
- Offset Printing:Lithographic methods retain cost advantages for long-run paper label production. Personal care brands specify offset-printed FSC paper for premium positioning.
- Screen Printing:Thick-film deposition suits industrial and electronics labeling requiring durability. Specialty chemical manufacturers specify screen-printed formats for solvent-resistant identification.
Flexographic placements retain volume leadership; digital printing gains share fastest as run lengths fragment and brand versioning accelerates.
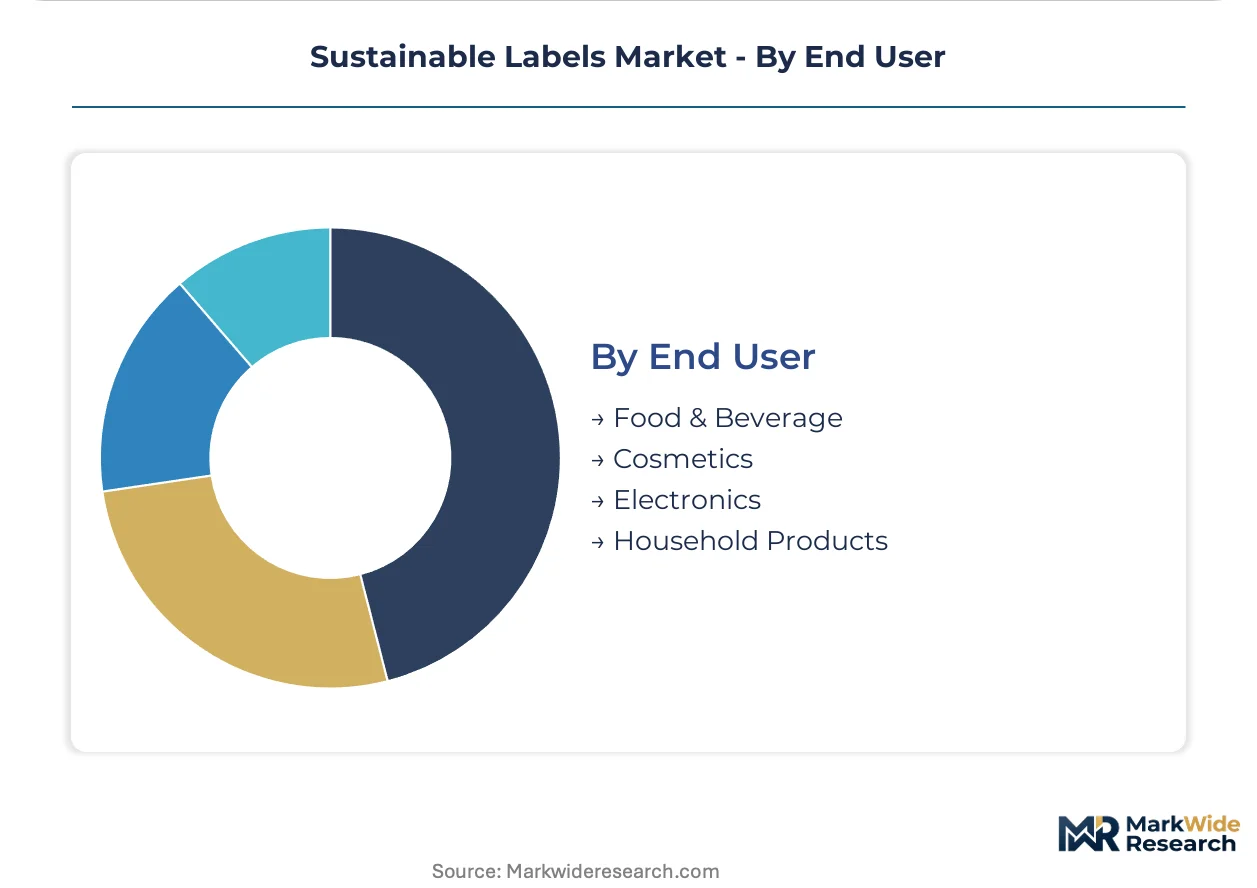
End User:
End-user segmentation captures diverging performance requirements across regulated consumer goods categories.
- Food & Beverage:Labels must satisfy FDA food contact regulations and EU food packaging migration limits. Major retailers now require certified recyclable or compostable formats as a condition of shelf placement.
- Cosmetics:Premium positioning demands combine with strict ingredient disclosure requirements. French beauty brands specify bio-based face stocks to align with CSRD reporting commitments.
- Electronics:Durability and heat resistance specifications dominate alongside WEEE directive compliance. German electronics manufacturers prioritize labels compatible with device recycling streams.
- Household Products:Chemical resistance and moisture tolerance requirements persist alongside sustainability mandates. Dutch cleaning product brands test stone paper substrates for plastic substitution.
Food and beverage anchors current volume; cosmetics represents the steepest expansion trajectory as clean beauty positioning intensifies material transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European converters dominate production capacity while North American brand procurement drives consumption growth. Asia-Pacific markets lag in regulatory alignment but accelerate capacity investments. Regional divergence in recycling infrastructure creates fragmented end-of-life performance for certified labels.
Germany
Baden-Württemberg and Bavaria host dense clusters of packaging converters co-located with food and beverage brand headquarters. REACH Article 33 disclosure mandates force systematic chemical inventory audits across adhesive supply chains. Stuttgart-based technical teams compress qualification cycles from 18 months to under 9 months for compostable formats.
United States
California and New York state-level extended producer responsibility laws create compliance service revenue streams for certified suppliers. FDA food contact regulations govern material approvals for primary package labels. Pacific Northwest craft beverage brands drive digital printing adoption for short-run sustainable label campaigns.
France
Paris-based multinational consumer goods companies consolidate specification authority with sustainability officers accountable to CSRD reporting requirements. ANSM and CNIL frameworks shape ingredient disclosure protocols for cosmetics applications. Île-de-French beauty brands specify bio-based face stocks to align with Science Based Targets initiative commitments.
United Kingdom
London-headquartered retailers impose packaging sustainability scorecards that mandate certified recyclable or compostable label formats. Post-Brexit regulatory divergence creates dual-track compliance requirements for exporters. Midlands-based converters retrofit flexographic lines for thinner film substrates and water-based ink systems.
Netherlands
Amsterdam and Rotterdam serve as distribution hubs for EU Green Deal-compliant label materials entering broader European markets. Dutch cleaning product brands test stone paper substrates for plastic substitution in household chemical applications. Randstad logistics networks enable rapid qualification sampling for German brand technical teams.
Sustainable Labels Market Competitive Landscape
Top-tier vendors anchor material science and certification capabilities, while mid-tier converters compete on regional qualification speed and digital printing flexibility. The vendor base stratifies across integrated materials suppliers, specialized sustainable packaging divisions, and regional digital print shops. Three archetypes dominate: multinational adhesive and film manufacturers with forest stewardship certifications, European flexible packaging specialists with dedicated sustainability units, and North American digital print service providers focused on craft beverage versioning. Competitive moves concentrate on M&A to secure bio-based polymer supply and strategic partnerships with retailer sustainability program managers.
Among the integrated materials tier, Avery Dennison and UPM Raflatac exemplify archetypes combining certified face stock programs with recyclable adhesive formulations. Constantia Flexibles anchors European supply through specialized sustainable packaging operations. These three occupy positions spanning the value chain from substrate manufacturing through converter technical support, representing distinct approaches to the tension between scale economics and customization demands.
| Leading Market Players |
|---|
| Labels Unlimited |
| Constantia Flexibles |
| Avery Dennison |
| HUHTAMAKI |
| Amcor |
| CCL Industries |
| WS Packaging Group |
| UPM Raflatac |
| Multi-Color Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters in Baden-Württemberg and Bavaria anchor European supply, enabling pricing discipline through co-located technical service and compressed qualification timelines. Their ownership structure supports patient capital allocation toward bio-based adhesive R&D, insulating margin positions against volatile PLA feedstock costs while major retailers impose sustainability scorecards.
Pricing Analysis
Margin tightening in standard-grade paper labels reflects REACH-driven adhesive reformulation costs and bio-based polymer premiums. Three-tier pricing structure across certified compostable, recyclable, and conventional formats separates FSC-certified face stocks with OK Compost verification from standard recycled pulp grades. Cost-down pressure on economy-tier labels accelerates as German supermarket chains consolidate procurement volumes. Private-label food brands exhibit highest price sensitivity; luxury cosmetics brands absorb premiums for bio-based face stocks without volume elasticity.
Supply Chain Analysis
OK Compost and APR recyclability certifications gate supplier access to major retailer-approved vendor lists, concentrating qualified capacity among established European converters. Manufacturing clusters in Germany, France, and the Netherlands feed from bio-based polymer suppliers in Belgium and the Netherlands. Raw material dependencies on PLA resin, FSC-certified pulp, and water-based adhesive chemistries create single-source vulnerability for specialty grades. Distribution runs through Randstad logistics hubs into German brand technical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sustainable labels occupy a materials-transition phase where digital printing and bio-based adhesives displace legacy flexographic and petrochemical systems. Water-based ink chemistry and laser die-cutting equipment are rewriting run-length economics and minimum order thresholds.
For Market Incumbents: Deepen backward integration into bio-based polymer supply to secure PLA resin allocations against chemical supplier concentration. Expand certification investment across FSC chain-of-custody, OK Compost, and APR protocols simultaneously to defend shelf placement against retailer scorecard tightening. Prioritize retrofit capital for flexographic lines handling thinner film substrates.
For New Entrants and Emerging Players: California and New York state-level extended producer responsibility laws open a window for compliance service bundling alongside certified label supply. Target craft beverage brands in the Pacific Northwest with digital printing-enabled versioning at sub-1,000 unit quantities. Lead with water-based ink systems and laser die-cutting to eliminate tooling barriers for seasonal SKUs.
For Investors and Strategic Acquirers: Consolidation of specification authority with sustainability officers is the leading indicator that certified label suppliers will command procurement priority over commodity converters. Long-term viability favors integrated materials suppliers with captive adhesive formulation and forest stewardship certifications. Acquisition focus: European flexible packaging specialists with dedicated sustainability divisions and established retailer program relationships. Watch for ECHA candidate list expansions triggering forced material substitutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Adhesive Formulation Partnership | Secures REACH-compliant chemistry ahead of ECHA restriction timelines for European converters. |
| Digital Printing Capacity Expansion | Captures craft beverage versioning demand with 500-unit minimums previously uneconomical for compostable formats. |
| Certification Portfolio Investment | Enables simultaneous FSC, OK Compost, and APR qualification required by German retailer scorecards. |
| Laser Die-Cutting Equipment Deployment | Eliminates tooling costs for seasonal SKUs in North American spirits and specialty food segments. |
| Extended Producer Responsibility Service Launch | Generates compliance revenue streams under California and New York state packaging laws. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with packaging converter technical directors, sustainability officers at multinational consumer goods companies, adhesive formulation chemists, and retailer procurement leads. ECHA candidate list updates, EU Green Deal implementation guidance, and FDA food contact notifications provided regulatory trajectory inputs. Bottom-up volume estimates triangulated against top-down market sizing from forest products and specialty chemicals trade data.
Reconciliation of shipment data, capacity utilization surveys, and brand procurement pipeline intelligence supported analytical framework construction across the projection horizon. Segmentation dimensions modeled include material type, printing technology, end-use application, and regional regulatory cluster. CAGRs derived from trend extrapolation of certification adoption curves and material substitution elasticities. Forecast inputs incorporated PLA resin supply expansion timelines and digital printing equipment installation rates.
The model assumes a particular technology adoption path; alternative pathways for water-based ink chemistry and laser die-cutting penetration would alter the outlook. Forecasts reflect assumptions regarding REACH enforcement intensity and retailer scorecard implementation timelines. A model refresh is warranted upon material change in ECHA candidate list composition or EU Green Deal packaging mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
India Print Label Market
Labels
Stand Alone Label Applicator Market
Labels
Future-Proof Pharma Labels Market
Labels
Tags Market
Labels
Barcode Label Market
Labels
ESD Protective Signage Labels Market
Labels
In-Mold Labeling (IML) Market
Labels
Self-Laminating Labels Market
Labels
Braille Labels Market
Labels
Print Label Market
Labels
Industrial Label Printers Market
Labels
Direct Thermal Labels Market
Labels
Global Cryogenic Label Market
Labels
Variable Data Printing Labels Market
Labels
Inventory Tags Market
Labels
Sleeve Label Market