
 Foil Labels Market | 2026-2036
Foil Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Foil Labels Market Foresight
ISO 9001 quality management certification is rotating as a baseline gate for supplier qualification across pharmaceutical and food-grade foil label procurement. Avery Dennison Corporation leverages its global substrate network to sustain premium supply agreements with multinational brand owners. UPM Raflatac anchors Nordic sustainability credentials through responsibly sourced paper and film backings. CCL Industries dominates narrow-web decorative foils for cosmetics and spirits, where metallic embellishment commands shelf differentiation.
Foil labels are pressure-sensitive or adhesive-backed constructions employing metalized films or thin-gauge metal foils, typically 12-50 micron aluminum, laminated to paper or polymer carriers with release liners; they deliver barrier properties, tamper evidence, and premium aesthetic transmission in packaging and identification systems. Aluminum foil substrates lead material type demand due to cost-efficient barrier performance and established recycling infrastructure, while digital inkjet printing technology captures the fastest expansion as brand owners shorten run lengths and pursue variable-data personalization. Pharmaceutical packaging applications concentrate margin pools where serialization compliance and cold-chain resistance justify specification premiums over standard paper labels.
FDA track-and-trace regulations and EU Falsified Medicines Directive enforcement compel pharmaceutical label investments with integrated authentication features, while REACH and RoHS frameworks restrict hazardous substance migration in food-contact and electronics applications. EMA guidance on anticounterfeiting measures and EPA volatile organic compound limits for flexographic presses add layered compliance costs that favor qualified converters with certified quality systems. Stakeholders must monitor evolving extended producer responsibility schemes and substrate recyclability mandates as these will determine which material combinations retain market access across European and North American supply chains.
Market Dynamics
Serialization mandates across pharmaceutical supply chains are forcing foil label converters to retool production lines for integrated track-and-trace capabilities, compressing lead times and elevating certification thresholds simultaneously.
Growth Catalysts
- EU Falsified Medicines Directive:Enforcement of unit-level serialization across European distribution networks compels pharmaceutical manufacturers to adopt tamper-evident foil constructions with embedded authentication layers.
- Digital inkjet printing:Variable-data personalization capabilities enable brand owners to execute shorter production runs with unique identifiers per label, reducing inventory carrying costs for seasonal and promotional SKUs.
- Germany's automotive corridor:Precision labeling demand from OEM and tier-one electronics exporters sustains premium aluminum foil specifications resistant to thermal cycling and chemical exposure.
Market Restraints
- Aluminum price volatility:Input cost swings for 12-50 micron foil substrates squeeze converter margins and complicate long-term contract pricing with multinational brand owners.
- Supply concentration in East Asian metallization:Dependence on vacuum deposition capacity concentrated in specific manufacturing clusters creates vulnerability to logistics disruptions and trade policy shifts.
- REACH substance restrictions:Evolving ECHA authorization lists limit adhesive and coating chemistries available for food-contact and electronics applications, forcing costly formulation redevelopment.
Strategic Opportunities
- India pharmaceutical exports:CDSCO alignment with international serialization standards creates demand for compliant cold-chain-resistant foil labels as domestic manufacturers expand regulated market access.
- Extended producer responsibility schemes:EU packaging waste directives incentivize mono-material aluminum constructions with established recycling infrastructure versus multi-layer alternatives.
- RFID-foil hybrid integration:Convergence of printed electronics with metalized substrates enables item-level inventory visibility for high-value cosmetics and spirits authentication.
Industry Challenges
- ISO 15378 certification timelines:Pharmaceutical-grade converter qualification demands 12-18 month validation cycles that strain working capital and technical staffing resources.
- Legacy flexographic asset base:Capital-intensive press replacement for digital hybrid configurations creates stranded equipment risk for mid-scale converters serving regional brand portfolios.
- Cross-functional serialization expertise:Scarce talent pools combining print engineering, data architecture, and regulatory compliance slow production line integration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foil Labels Market |
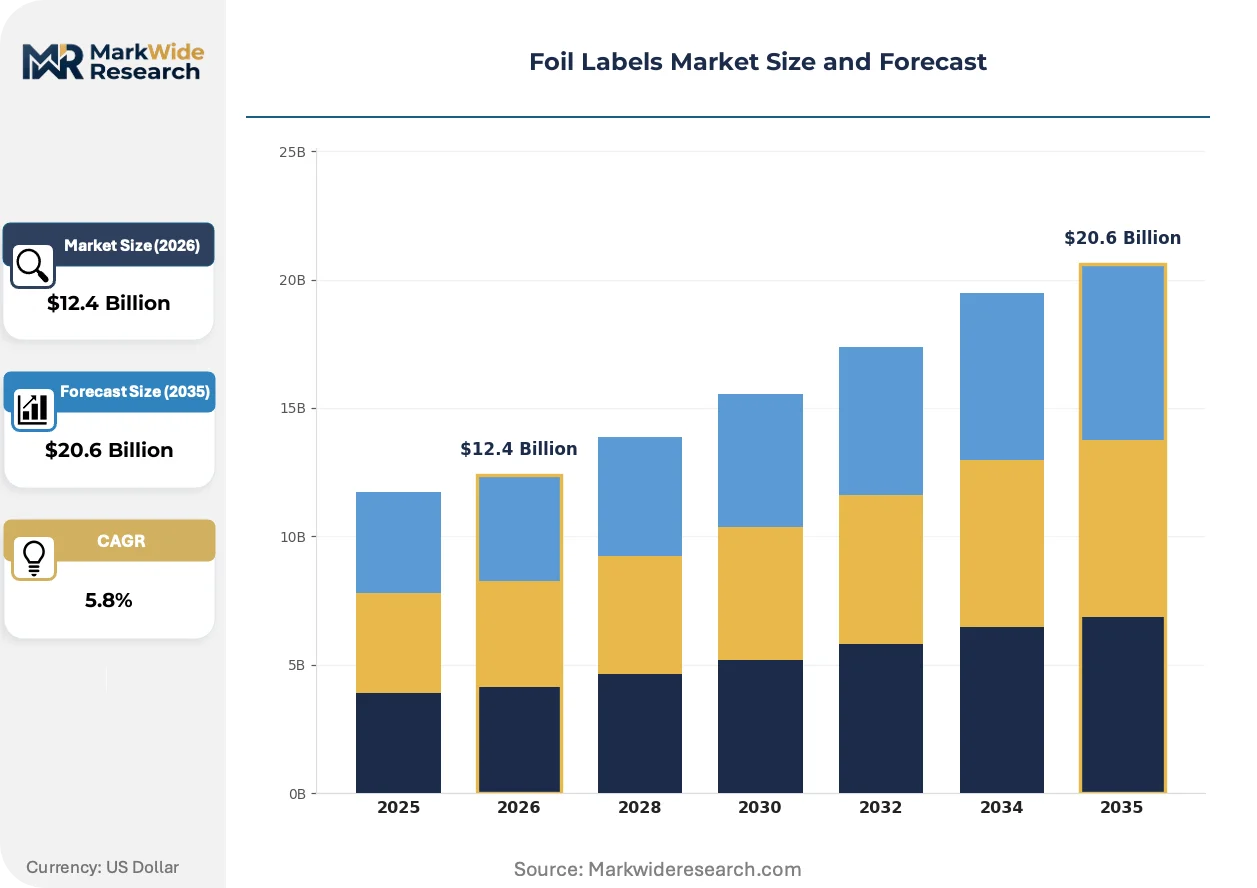
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum Foil, Copper Foil, Silver Foil, Polyester Foil, Vinyl Foil Application: Pharmaceutical Packaging, Food & Beverage, Electronics Identification, Cosmetic Branding, Industrial Labeling Printing Technology: Flexography, Digital Inkjet, Thermal Transfer, Screen Printing, Letterpress End User: Contract Manufacturers, Packaging Companies, Brand Owners, Label Printers |
| Companies Covered | Avery Dennison Corporation, UPM Raflatac, CCL Industries, Multi-Color Corporation, Constantia Flexibles, 3M Company, Kurz, Herma GmbH, Lintec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foil Labels Market Shifts & Advancements
Active materials and intelligent substrates are redefining functional performance boundaries in foil label applications, while regulatory pressure and procurement recalibration reshape competitive requirements across end-use verticals.
Digital inkjet systems with UV-curable metallic inks are decomposing the traditional trade-off between premium aesthetic quality and economic viability for short-run production. Cosmetics and spirits brand owners in France and Switzerland now execute seasonal campaigns with run lengths below five thousand units, collapsing minimum order thresholds that previously favored gravure and hot-stamp alternatives. This capability compression enables regional marketing teams to test localized packaging variants without central procurement approval cycles.
REACH authorization procedures and EPA volatile organic compound limits for flexographic operations are restricting solvent-based adhesive systems in food-contact and pharmaceutical applications. Converters with certified water-based and UV-curable alternatives capture specification premiums as EMA guidance tightens anticounterfeiting requirements for high-risk medicines. German and Swiss pharmaceutical packaging operations have accelerated supplier audits to verify compliance documentation across substrate, adhesive, and release liner components.
Brand owner technical sourcing teams now mandate recyclability certifications and carbon footprint disclosures as baseline qualification criteria alongside unit cost metrics. This specification evolution displaces multi-layer constructions with non-recyclable components in European personal care and premium beverage segments. Nordic markets exhibit the most pronounced preference rotation, with UPM Raflatac and comparable suppliers capturing volume through verified responsibly sourced paper and film backing portfolios.
Foil Labels Market Segmentation
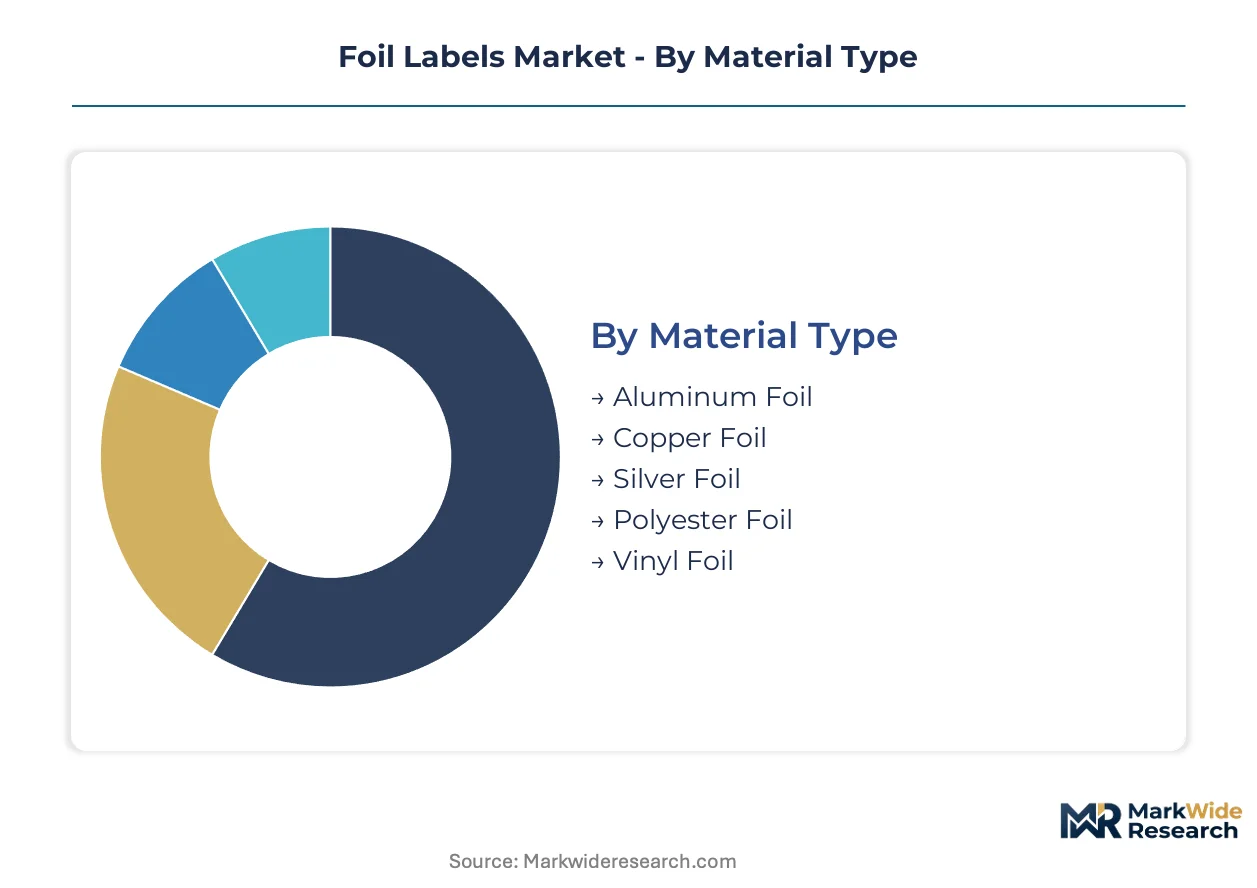
Foil label procurement splits across four distinct category hierarchies that determine specification requirements, compliance burdens, and margin capture. Material chemistry governs barrier performance and recycling pathways. Application verticals dictate authentication complexity and cold-chain demands.
Material Type:
Premium margin pools concentrate in thin-gauge metal foils where pharmaceutical serialization and tamper-evidence specifications command price premiums over polymer alternatives.
- Aluminum Foil:Laminated 12-50 micron substrates dominate pharmaceutical and food-contact applications through cost-efficient oxygen and moisture barrier performance. Demand concentrates in Germany's automotive corridor for thermal-cycling-resistant electronics identification. Established European and North American recycling infrastructure sustains specification preference under extended producer responsibility schemes.
- Copper Foil:High-conductivity substrates enable RFID-embedded constructions for item-level inventory tracking in cosmetics and spirits authentication. Japanese electronics manufacturers specify rolled-annealed grades for electromagnetic shielding labels on precision instrumentation exports.
- Silver Foil:Decorative metallization for premium beverage and personal care shelf differentiation with limited functional barrier role.
- Polyester Foil:Metalized PET films bridge cost and performance for mid-tier food packaging with moderate barrier requirements.
- Vinyl Foil:Flexible PVC constructions for curved-surface industrial labeling with chemical resistance specifications.
Aluminum foil holds installed capacity across European and North American converter networks. Copper foil is rotating up the share rankings through printed electronics convergence.
Application:
Volume concentration sits in food and beverage labeling, though value capture peaks in pharmaceutical verticals where FDA and EMA compliance mandates justify specification premiums.
- Pharmaceutical Packaging:Unit-level serialization constructions with integrated track-and-trace layers and cold-chain resistance. EU Falsified Medicines Directive enforcement and FDA track-and-trace regulations compel tamper-evident foil adoption across European and North American distribution networks.
- Food & Beverage:Barrier labels for oxygen-sensitive and moisture-critical product categories. German and Swiss organic food exporters specify recyclable mono-material aluminum constructions to satisfy Nordic retailer sustainability scorecards.
- Electronics Identification:Thermal-cycling-resistant specifications for automotive and industrial automation equipment.
- Cosmetic Branding:Metallic embellishment for shelf differentiation in premium fragrance and skincare segments.
- Industrial Labeling:Chemical and abrasion-resistant constructions for asset tracking in manufacturing environments.
Pharmaceutical packaging commands the steepest expansion trajectory through regulatory compliance layering. Food and beverage maintains volume leadership across installed converter capacity.
Printing Technology:
Technology selection determines run-length economics and variable-data capability, with digital systems capturing specification share from legacy analog processes.
- Digital Inkjet:UV-curable metallic ink systems enable sub-five-thousand-unit runs with unique identifiers per label. French and Swiss cosmetics brand owners execute seasonal campaigns without central procurement approval cycles. Variable-data personalization collapses inventory carrying costs for promotional SKU portfolios.
- Flexography:High-speed rotary printing for long-run food and beverage applications with established solvent and water-based ink chemistries. EPA volatile organic compound limits and REACH substance restrictions are forcing formulation redevelopment toward UV-curable alternatives.
- Thermal Transfer:On-demand variable printing for industrial asset labeling with moderate durability requirements.
- Screen Printing:Heavy ink deposit constructions for outdoor and chemical-exposure applications.
- Letterpress:Niche premium applications with tactile impression requirements in spirits and luxury goods.
Flexography retains installed press capacity across mid-scale converter footprints. Digital inkjet is climbing the fastest through brand owner demand for personalization and shortened lead times.
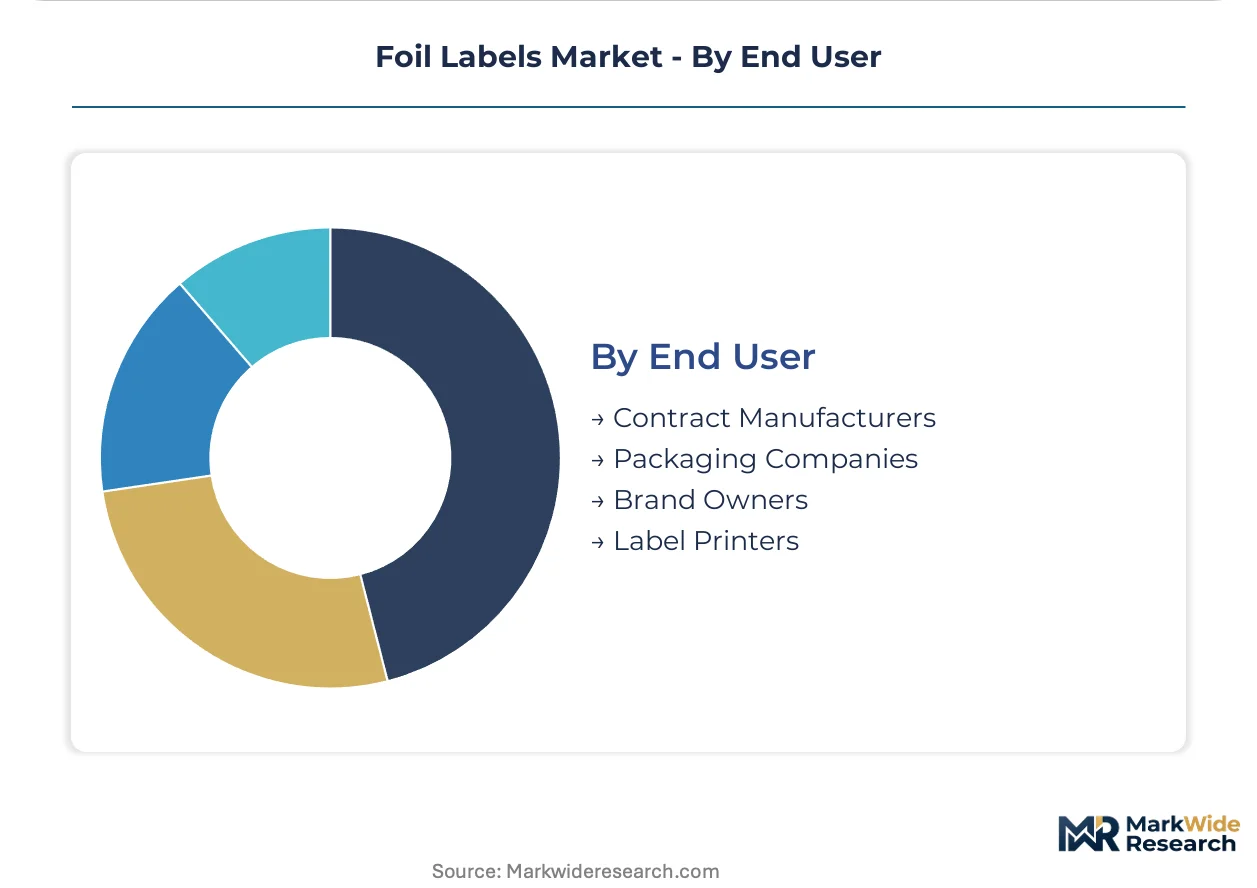
End User:
Procurement authority concentration varies by vertical, with brand owners directly specifying substrate and authentication requirements in pharmaceutical and premium cosmetics segments.
- Brand Owners:Direct specification of foil substrate, adhesive, and authentication layer requirements in pharmaceutical and premium personal care verticals. Technical sourcing teams now mandate recyclability certifications and carbon footprint disclosures alongside unit cost metrics.
- Contract Manufacturers:Pharmaceutical packaging execution for multiple brand portfolios with ISO 15378 certification requirements. Twelve-to-eighteen-month validation cycles strain working capital and technical staffing resources.
- Packaging Companies:Integrated design and conversion services for food and beverage clients with sustainability compliance documentation.
- Label Printers:Regional conversion specialists serving mid-tier brand portfolios with legacy flexographic asset bases.
Brand owners concentrate specification authority. Contract manufacturers are gaining procurement influence through pharmaceutical serialization mandate execution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance and FDA serialization mandates are redrawing procurement geography across pharmaceutical and food-contact foil label supply chains. Germany's industrial corridor anchors premium aluminum foil demand for automotive electronics exports. India's CDSCO alignment with international track-and-trace standards is accelerating cold-chain label investments.
United States
FDA track-and-trace regulations compel pharmaceutical manufacturers to adopt tamper-evident foil constructions with embedded authentication layers. EPA volatile organic compound limits for flexographic presses restrict solvent-based adhesive chemistries in food-contact applications. New Jersey and Pennsylvania host concentrated converter networks serving East Coast pharmaceutical packaging operations.
Germany
EMA guidance on anticounterfeiting measures tightens specification requirements for high-risk medicine labels. REACH substance restrictions limit adhesive and coating chemistries available for electronics and food-contact applications. Baden-Württemberg's automotive corridor sustains premium aluminum foil demand for thermal-cycling-resistant electronics identification.
India
CDSCO alignment with international serialization standards creates demand for compliant cold-chain-resistant foil labels. Extended producer responsibility schemes under draft packaging waste regulations favor recyclable mono-material constructions. Maharashtra and Gujarat pharmaceutical clusters drive specification upgrades for regulated export market access.
Switzerland
Swissmedic enforcement of unit-level serialization sustains premium foil label procurement for pharmaceutical exports. Brand owner technical sourcing teams mandate carbon footprint disclosures alongside unit cost metrics. Basel and Zurich cosmetic packaging operations execute seasonal campaigns with sub-five-thousand-unit digital inkjet runs.
Japan
METI industrial standards guide thermal-cycling-resistant specifications for automotive and precision instrumentation labels. PMDA serialization requirements align with international pharmaceutical track-and-trace frameworks. Chubu region electronics manufacturers specify rolled-annealed copper foil grades for electromagnetic shielding applications.
Foil Labels Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and substrate technology portfolios. The vendor base clusters around three strategic archetypes: global substrate networks with pharmaceutical-grade certification, regional converters with sustainability credentials, and narrow-web specialists serving premium cosmetics and spirits segments. Dominant competitive moves include ISO 15378 qualification investments and digital hybrid press conversions for variable-data serialization.
Within the premium certification tier, Avery Dennison Corporation and CCL Industries exemplify archetype positioning. Avery Dennison leverages its global substrate network to sustain supply agreements with multinational brand owners requiring multi-continent compliance documentation. CCL Industries occupies a position in narrow-web decorative foils where metallic embellishment commands shelf differentiation. UPM Raflatac anchors Nordic sustainability credentials through responsibly sourced paper and film backings, representing the environmental compliance archetype.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| UPM Raflatac |
| CCL Industries |
| Multi-Color Corporation |
| Constantia Flexibles |
| 3M Company |
| Kurz |
| Herma GmbH |
| Lintec Corporation |
| Others |
Supply & Pricing Matrix
Converter capacity utilization above 80 percent in Germany's automotive corridor and Switzerland's pharmaceutical clusters creates pricing power concentration among ISO 15378-certified suppliers, while East Asian metallization capacity at 65-75 percent utilization sustains raw material cost floors that resist downward negotiation.
Pricing Analysis
Certification level creates the primary spread, with ISO 15378 pharmaceutical-grade foil labels commanding substantial premiums over standard industrial specifications due to validation cycle investments and audit documentation burdens. Three-tier pricing structure separates serialized authentication constructions from barrier-only food-contact grades and basic industrial identification labels. Cost compression in mid-tier polyester foil segments is intensifying as digital inkjet converters absorb margin erosion to capture promotional SKU volumes. Contract manufacturers exhibit highest price sensitivity due to working capital constraints, while multinational brand owners prioritize compliance documentation over unit cost minimization.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for vacuum-deposited metallized films sourced from East Asian manufacturing clusters. Raw material supply concentrates in China, South Korea, and Japan for aluminum foil substrates and metallization equipment, with German and Swiss converters drawing from these sources for thin-gauge specifications. Adhesive chemistry and release liner components hinge on petrochemical feedstocks with exposure to crude price volatility. Single-source vulnerability characterizes specialized copper foil grades for RFID-embedded constructions. Distribution runs through converter networks with direct pharmaceutical packaging relationships, bypassing traditional label distributor channels for serialization-mandate compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where ISO 15378 certification cycles and EMA audit documentation create switching costs that protect qualified incumbent positions against price-based competition.
For Market Incumbents: Consolidate through selective acquisition of regional converters with pharmaceutical-grade certification gaps, capturing stranded customer relationships before digital-native competitors achieve validation status. Backward integration into metallized film production reduces exposure to East Asian supply concentration and aluminum price volatility. Prioritize capacity addition in India's Maharashtra and Gujarat clusters to capture CDSCO-aligned serialization demand before domestic converters achieve international certification parity. For New Entrants and Emerging Players: Differentiate on sustainability credentialing with verified mono-material aluminum constructions and carbon footprint disclosures that displace multi-layer alternatives in Nordic personal care and premium beverage procurement. Target India's pharmaceutical export corridor with cold-chain-resistant foil specifications as domestic manufacturers expand regulated market access. Pursue co-development partnerships with French and Swiss cosmetics brand owners seeking sub-five-thousand-unit digital inkjet capabilities for seasonal campaign execution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturers with ISO 15378 validation and multi-brand pharmaceutical packaging portfolios, where serialization mandate execution locks in long-term supply relationships. Acquisition focus should center on narrow-web converters with digital hybrid press configurations and established EMA compliance documentation. Watch FDA track-and-trace enforcement acceleration and EU packaging waste directive implementation as inflection indicators for specification premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | Twelve-to-eighteen-month validation cycles create defensive moats against unqualified competitors in pharmaceutical verticals. |
| Digital Hybrid Press Conversion | Variable-data personalization capabilities capture promotional SKU volumes from gravure and hot-stamp alternatives in cosmetics segments. |
| Backward Integration into Metallization | In-house vacuum deposition capacity reduces exposure to East Asian supply concentration and trade policy disruption risks. |
| Mono-Material Aluminum Portfolio Expansion | Recyclable constructions with established European infrastructure satisfy extended producer responsibility scheme requirements. |
| India Pharmaceutical Cluster Establishment | CDSCO-aligned serialization demand from Maharashtra and Gujarat exporters creates first-mover advantage in regulated market access. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical packaging procurement directors, converter operations managers, brand owner technical sourcing leads, and regulatory affairs specialists, then refined through secondary validation against FDA guidance documents, EMA anticounterfeiting directives, REACH authorization lists, and customs trade data for aluminum foil substrate flows. Bottom-up demand modeling across material type, application vertical, printing technology, and end-user category was triangulated with top-down market sizing from converter capacity assessments and metallization equipment installation records.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension, with CAGRs derived from regression analysis of historical pharmaceutical serialization adoption curves and digital printing penetration rates. The analytical framework incorporates aluminum price elasticity coefficients, certification timeline distributions, and regional regulatory enforcement intensity scores as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EMA serialization mandate enforcement and stable East Asian metallization capacity utilization; material deviation in trade policy or regulatory delay would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Glue-Applied Labels Market
Labels
Barcode Label Printer Market
Labels
Syringe Labels Market
Labels
Global Label Adhesive Market
Labels
Braille Labels Market
Labels
Global Automotive Labels Market
Labels
Coated Wet Glue Label Market
Labels
Eco-Friendly Labels Market
Labels
Ripeness Indicator Labels Market
Labels
GCC Labeling Market
Labels
Printable Tags Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Non-Adhesive Tags Market
Labels
North America Self-Adhesive Labels Market
Labels
Pre-Gummed Labels Market
Labels
Barcode Label Market