
 Wet Glue Labeling Machines Market | 2026-2036
Wet Glue Labeling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Glue Labeling Machines Market Outlook
Equipment leasing and project finance is fragmenting competitive access across the wet glue labeling machines landscape. Krones AG leverages captive financing arms to anchor large-format brewery installations across Europe. Barry-Wehmiller Companies sustains mid-market penetration through decentralized service networks that reduce total cost of ownership for regional bottlers.
Wet glue labeling machines apply cold-setting adhesives to glass, metal, or plastic containers at speeds ranging from 50 to 60,000 bottles per hour, serving primary identification and regulatory compliance functions in high-volume consumer goods packaging. Automatic systems dominate capital deployment among multinational food and beverage producers seeking line integration with existing filling equipment. Semi-automatic configurations compete for share in pharmaceutical and cosmetics batch operations where frequent changeovers and validated cleaning protocols command premium positioning.
FDA cGMP guidelines and EU MDR labeling traceability requirements shape machine validation protocols and adhesive qualification documentation for pharmaceutical adopters. EPA VOC emission standards and REACH substance restrictions constrain adhesive chemistry options, pushing OEMs toward water-based and bio-derived formulations. Stakeholders must monitor evolving Extended Producer Responsibility frameworks in the EU and emerging state-level packaging regulations in the United States to anticipate retrofit demand and compliance-driven replacement cycles.
Market Dynamics
Equipment refresh cycles in beverage bottling are compressing as craft producers diversify container formats, forcing OEMs to engineer modular labeling platforms that accommodate frequent changeovers without line downtime.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants is mandating validated adhesive temperature controls in labeling equipment, creating replacement demand across German and Italian packaging clusters.
- Craft beverage diversification:Premium spirits and small-batch breweries are adopting non-standard bottle geometries that require flexible wet glue systems capable of handling 50 to 500 milliliter variants on shared lines.
- Water-based adhesive chemistry:Bio-derived formulations are gaining qualified status under REACH substance restrictions, opening compliance pathways for pharmaceutical adopters facing EPA VOC emission scrutiny.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margin buffers for mid-tier OEMs sourcing frames and contact parts from Asian mill networks.
- Adhesive supply concentration:Specialty cold-setting resin production clusters in Germany and the Netherlands, creating single-source exposure for North American converters.
- Speed-throughput tradeoffs:Semi-automatic systems max out below 12,000 bottles per hour, structurally excluding them from multinational filling line integrations.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO traceability mandates and expanding domestic vaccine production are driving demand for validated wet glue systems in Pune and Hyderabad manufacturing corridors.
- Extended Producer Responsibility frameworks:EU packaging waste directives are incentivizing equipment retrofits that enable clean label removal and container reuse cycles.
- Vision-guided robotics convergence:Integration of machine vision with servo-driven labeling heads is collapsing changeover times for cosmetics batch operations requiring frequent SKU rotation.
Industry Challenges
- Mechatronics technician scarcity:Servo motor calibration and HMI programming skills are in short supply across Midwest US manufacturing hubs, extending commissioning timelines.
- IQ/OQ/PQ documentation burden:FDA cGMP validation protocols for pharmaceutical installations demand 18-to-24-month qualification cycles, delaying revenue recognition.
- Legacy line integration friction:Proprietary communication protocols in 1990s-era filling equipment obstruct seamless wet glue machine connectivity, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Glue Labeling Machines Market |
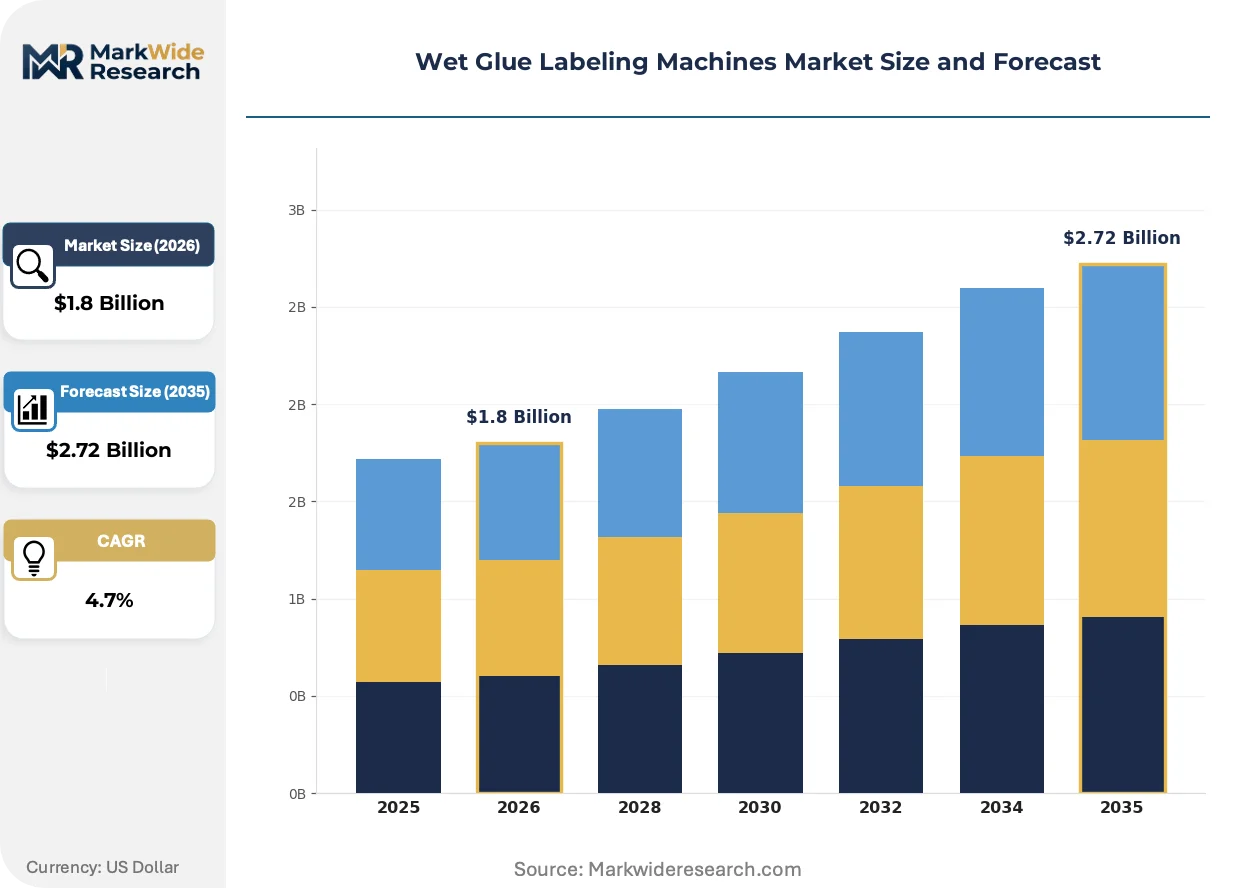
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Specialized End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Pressure Sensitive, Roll-fed, Sheet-fed, In-mold Application: Container Labeling, Product Labeling, Packaging Labeling, Branding |
| Companies Covered | Krones AG, Sidel Group, Barry-Wehmiller Companies, P.E. Labellers S.p.A., Herma GmbH, Label-Aire, Quadrel Labeling Systems, Sacmi Labeling, Accraply, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Glue Labeling Machines Market Strategic Shifts
Adhesive chemistry innovation and machine intelligence are converging to redefine throughput economics, with temperature-controlled application systems and predictive maintenance architectures emerging as decisive competitive differentiators.
Servo-driven vacuum drum transfer technology is collapsing mechanical complexity in high-speed wet glue labeling. Pharmaceutical contract packagers in Germany and Switzerland are retrofitting existing lines with these systems to achieve validated repeatability below 0.5 millimeter placement variance. The elimination of mechanical cams and gear trains is compressing maintenance intervals and spare parts inventory requirements.
REACH substance restrictions and EPA VOC emission standards are forcing adhesive reformulation toward water-based and bio-derived chemistries. Equipment OEMs are redesigning glue pots and application rollers to accommodate higher-viscosity, slower-setting formulations without sacrificing line speed. Pharmaceutical adopters in the United States and EU are prioritizing machinery with documented adhesive qualification protocols to preempt regulatory audit findings.
Equipment-as-a-service contracting is displacing outright purchase in mid-market beverage operations. Regional bottlers in Italy and Spain are subscribing to wet glue systems with bundled maintenance and adhesive supply, transferring capex risk to OEM financing arms. This model is most visible among craft spirits producers seeking production flexibility without balance sheet encumbrance.
Wet Glue Labeling Machines Market Segmentation
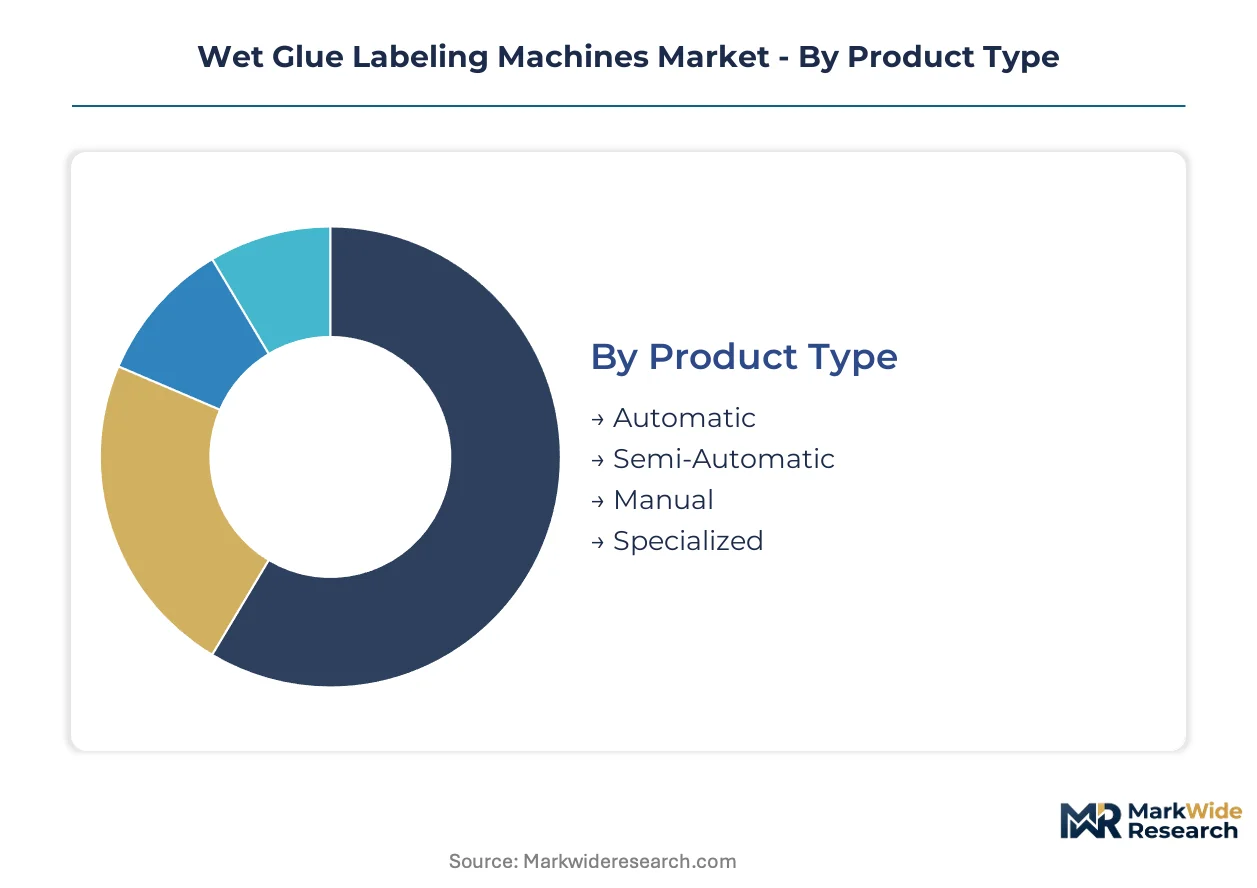
Wet glue labeling machine procurement splits sharply between high-volume beverage installations and batch-scale pharmaceutical operations. Equipment specifications diverge across adhesive chemistry, line speed requirements, and validation protocols, creating distinct competitive arenas for OEMs.
Product Type:
Mature automatic platforms anchor capital deployment in multinational bottling corridors, while emerging specialized configurations capture craft producer flexibility premiums.
- Automatic:Servo-driven vacuum drum systems achieve 60,000 bottles per hour with validated repeatability below 0.5 millimeter placement variance. Demand concentrates in Germany and Italy where Krones AG and Sidel Group serve Heineken and Diageo filling line integrations requiring continuous operation.
- Semi-Automatic:Modular platforms accommodate 50 to 12,000 bottles per hour with tool-free changeover protocols. Cosmetics contract packagers in Switzerland and pharmaceutical batch operators in the United States prioritize these systems for validated cleaning cycles between SKU rotations.
- Manual:Benchtop units serve micro-breweries and artisanal spirits producers with sub-500 bottle hourly throughput requirements.
- Specialized:Custom-engineered systems handle non-standard container geometries including hexagonal spirits bottles and tapered wine vessels.
Automatic systems retain volume leadership; specialized configurations hold the steepest expansion curve as craft beverage diversification accelerates.
End User:
Cost tier stratification separates validated pharmaceutical installations from price-sensitive chemical packaging operations.
- Food & Beverage:High-volume bottling lines drive equipment refresh cycles with integrated filling-capping-labeling sequences. EU F-Gas Regulation compliance mandates adhesive temperature controls in German and Italian brewery installations.
- Pharmaceuticals:FDA cGMP and EU MDR traceability requirements impose 18-to-24-month IQ/OQ/PQ validation cycles. Pune and Hyderabad manufacturing corridors in India show expanding demand for CDSCO-compliant wet glue systems in domestic vaccine production.
- Cosmetics:Frequent SKU rotation and premium positioning command servo-driven platforms with vision-guided robotics for sub-minute changeovers.
- Chemicals:Corrosion-resistant Grade 316 stainless steel construction addresses aggressive solvent exposure in industrial adhesive and cleaning product packaging.
Food & Beverage dominates absolute unit shipments; Pharmaceuticals commands the highest average selling prices per installation.
Technology:
Application geometry determines technology selection, with cylindrical container dominance favoring roll-fed architectures.
- Pressure Sensitive:Self-adhesive label stocks bypass glue application entirely, competing for share in short-run promotional labeling.
- Roll-fed:Continuous web handling achieves maximum line efficiency in beverage and food canning operations with minimal splice downtime.
- Sheet-fed:Cut-and-stack formats accommodate pre-printed decorative labels for premium spirits and cosmetics where foil stamping and embossing quality differentiates brand positioning.
- In-mold:Label integration during container blow-molding eliminates post-forming decoration steps for high-volume personal care bottles.
Roll-fed systems retain volume leadership; sheet-fed configurations gain share fastest in premium beverage and cosmetics segments.
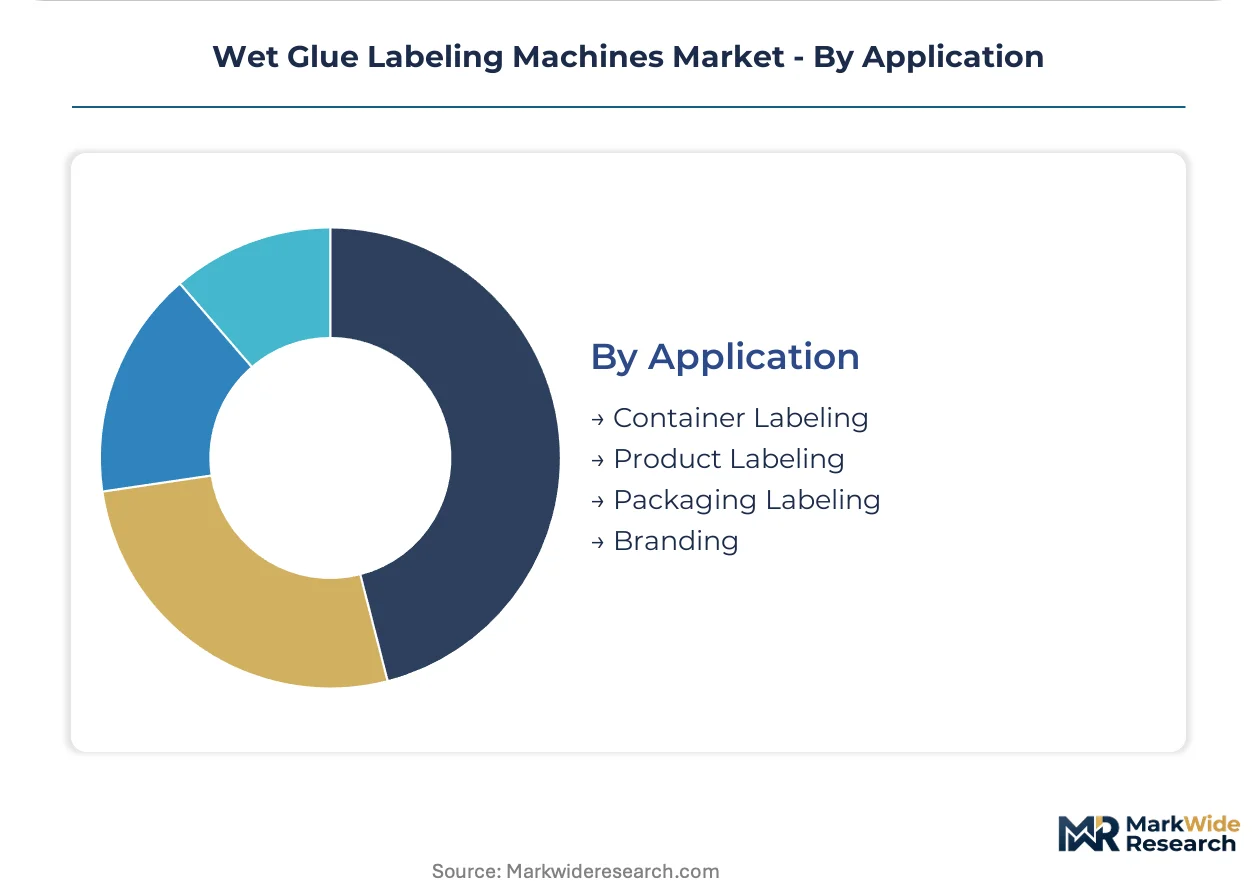
Application:
Customer type splits between regulatory compliance mandates and brand differentiation objectives.
- Container Labeling:Primary identification functions on glass, metal, and plastic vessels serve regulatory compliance and supply chain traceability. EPA VOC emission standards and REACH substance restrictions push converters toward water-based adhesive formulations.
- Product Labeling:Individual unit decoration addresses batch coding, expiration dating, and multilingual regulatory text requirements.
- Packaging Labeling:Secondary and tertiary packaging identification supports warehouse automation and retail-ready display configurations.
- Branding:Decorative and promotional labels leverage metallic substrates, tactile varnishes, and holographic security features for premium positioning.
Container labeling retains volume leadership; branding applications show the steepest expansion curve as craft producers invest in differentiated shelf presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phasedown and FDA cGMP validation protocols are redistributing wet glue labeling machine procurement across concentrated packaging clusters in Germany, Italy, the United States, India, and Switzerland.
Germany
Bavarian brewery corridors and Baden-Württemberg pharmaceutical packaging hubs drive equipment refresh demand as EU F-Gas Regulation mandates validated adhesive temperature controls. ECHA REACH substance restrictions push converters toward machinery with documented water-based adhesive qualification. Stuttgart-area OEM clusters serve Heineken and Diageo filling line integrations requiring continuous 60,000 bottles per hour operation.
Italy
Emilia-Romagna food canning operations and Lombardy cosmetics contract packagers anchor semi-automatic system deployment for frequent SKU rotation. CDSCO-aligned traceability protocols from Indian pharmaceutical importers shape export machine specifications. Bologna and Parma manufacturing corridors specialize in modular platforms accommodating 50 to 12,000 bottles per hour with tool-free changeover protocols.
United States
FDA cGMP guidelines impose 18-to-24-month IQ/OQ/PQ validation cycles on pharmaceutical installations in New Jersey and North Carolina research triangles. EPA VOC emission standards constrain adhesive chemistry options, pushing Midwest bottlers toward water-based formulations. Pacific Northwest craft spirits producers in Oregon and Washington adopt specialized systems for non-standard hexagonal bottle geometries.
India
CDSCO traceability mandates and expanding domestic vaccine production drive validated wet glue system demand in Pune and Hyderabad pharmaceutical manufacturing corridors. BIS certification requirements for imported packaging machinery create specification barriers for European OEMs. Gujarat chemical packaging clusters specify Grade 316 stainless steel construction for aggressive solvent exposure applications.
Switzerland
Swissmedic pharmaceutical regulations and premium cosmetics positioning command servo-driven platforms with vision-guided robotics for sub-minute changeovers. Basel-area contract packagers retrofit existing lines with vacuum drum transfer systems achieving validated repeatability below 0.5 millimeter placement variance. Zurich industrial clusters specialize in equipment-as-a-service contracting for mid-market beverage operations seeking production flexibility without balance sheet encumbrance.
Wet Glue Labeling Machines Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata defined by financing capability and service network density. Consolidation pressure concentrates among multinational bottling integrators seeking single-source accountability for filling-capping-labeling sequences. Three archetypes dominate: captive-financing equipment OEMs with leasing arms, decentralized service-network specialists, and precision-engineering contract manufacturers. Geographic expansion through regional assembly partnerships and adhesive supply bundling represent the dominant competitive moves.
Among German-incorporated machinery fabricators, Krones AG and Herma GmbH exemplify the captive-financing archetype, while Sidel Group occupies a position anchoring multinational beverage line integration. Barry-Wehmiller Companies represents the decentralized service-network model sustaining mid-market penetration through regional bottler relationships. These three entities collectively illustrate how equipment-as-a-service contracting and validated pharmaceutical qualification capabilities differentiate competitive positioning across price-sensitive and premium-tier procurement channels.
| Leading Market Players |
|---|
| Krones AG |
| Sidel Group |
| Barry-Wehmiller Companies |
| P.E. Labellers S.p.A. |
| Herma GmbH |
| Label-Aire |
| Quadrel Labeling Systems |
| Sacmi Labeling |
| Accraply |
| Others |
Value Chain & Pricing Dynamics
German and Italian specialty adhesive resin production clusters concentrate upstream supply for wet glue labeling machine converters, anchoring margin pools in validated pharmaceutical qualification documentation and captive financing arms rather than hardware fabrication alone.
Pricing Analysis
Certification level (FDA-grade/CE-marked/ISO-standard) creates the primary spread across wet glue labeling machine procurement, with pharmaceutical-grade installations commanding substantial premiums over beverage-tier equipment. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, adhesive chemistry compatibility, and bundled after-sales service density. Pricing pressure stems from stainless steel input volatility compressing margin buffers for mid-tier OEMs sourcing Grade 304 and 316 from Asian mill networks. Regional bottlers in Southern Europe exhibit highest price sensitivity, while Swiss pharmaceutical contract packagers prioritize placement precision over capital expenditure minimization.
Supply Chain Analysis
Specialty cold-setting resin feedstock draws from concentrated production clusters in Germany, the Netherlands, and Belgium, with limited qualified alternatives for REACH-compliant pharmaceutical formulations. Grade 304 and 316 stainless steel frames, servo motor assemblies, and vacuum drum transfer components constitute critical input dependencies. Single-source vulnerability in adhesive chemistry creates exposure for North American converters facing EU export allocation constraints. Distribution runs through OEM-direct channels for multinational installations and regional distributor networks for mid-market craft beverage producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting expands faster than hardware shipment growth, transforming wet glue labeling machines into recurring-revenue platforms where adhesive supply bundling and predictive maintenance subscriptions eclipse upfront capital recognition.
For Market Incumbents: Entrench market position by deepening captive financing capabilities to match Krones AG's brewery leasing dominance and accelerating IQ/OQ/PQ documentation libraries to compress pharmaceutical validation cycles. Pressure from vision-guided robotics convergence in cosmetics batch operations demands servo-driven platform standardization. Vertical integration into specialty adhesive qualification protocols defends margin pools against commoditization. For New Entrants and Emerging Players: Pursue white-space opportunity in Indian pharmaceutical packaging corridors where CDSCO traceability mandates outpace domestic OEM capacity, and Pacific Northwest craft spirits producers seeking hexagonal bottle handling without multinational minimum order constraints. Equipment-as-a-service contracting with bundled maintenance represents the most penetrable go-to-market angle for balance-sheet-constrained regional bottlers. For Investors and Strategic Acquirers: Capital is best deployed toward precision-engineering contract manufacturers with documented FDA cGMP and EU MDR qualification capabilities, as consolidation pressure intensifies among multinational bottling integrators seeking single-source accountability. Long-term viability hinges on adhesive chemistry flexibility and mechatronics technician training infrastructure. Watch for Extended Producer Responsibility framework implementation velocity as inflection indicator for retrofit demand cyclicality.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Transfers capex risk to OEM financing arms while locking in adhesive supply recurring revenue. |
| Vision-Guided Robotics Integration | Collapses changeover times for Swiss cosmetics contract packagers requiring sub-minute SKU rotation. |
| Adhesive Chemistry Qualification Investment | Preempts FDA audit findings for pharmaceutical adopters facing EPA VOC emission scrutiny. |
| Regional Assembly Partnership Expansion | Reduces landed cost exposure for Indian pharmaceutical corridors requiring BIS certification compliance. |
| Predictive Maintenance Platform Development | Compresses spare parts inventory requirements for vacuum drum transfer system retrofit demand. |
Study Parameters
A spread of perspectives from plant engineers at multinational bottling facilities, aftermarket service heads at decentralized OEM networks, pharmaceutical packaging quality directors, and craft spirits production managers converged on the working assumptions. Primary interview insights combined with secondary validation from FDA cGMP guidance documents, ECHA REACH substance restriction databases, EU F-Gas Regulation implementation notices, and SEC filings from listed packaging machinery OEMs. Bottom-up equipment shipment tallies and top-down packaging line investment flow analysis provided triangulation discipline.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning automation tier, end-use vertical, adhesive chemistry compatibility, and regional regulatory cluster stringency. CAGRs derived from equipment refresh cycle compression rates, craft beverage format diversification velocity, and pharmaceutical validation protocol evolution. Industry-specific forecast inputs incorporated stainless steel price index trajectories and CDSCO traceability mandate implementation schedules.
Sensitivities concentrate around EU F-Gas Regulation phasedown velocity, REACH substance restriction expansion scope, and Indian BIS certification barrier evolution. Forecasts reflect documented assumptions regarding technician scarcity resolution timelines and adhesive supply concentration persistence. Cross-checking against customs records for German and Italian packaging machinery export flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Label Market
Labels
APAC on-Demand Color Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
ESD Protective Signage Labels Market
Labels
Printable Tags Market
Labels
Variable Data Printing Labels Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Hot Melt Glue Labeler Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Shipping Label Market
Labels
Global Waterproof Labels Market
Labels
Wet Glue Labels Market
Labels
Freshness Indicator Label Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Tags Market
Labels
Glue-Applied Labels Market