
 Roll-fed Wraparound Label Substrates Market | 2026-2036
Roll-fed Wraparound Label Substrates Market Size, Share, and Industry Trends Forecast 2026-2036
Roll-fed Wraparound Label Substrates Market Insights
Maintenance-linked substrate supply contracts is consolidating purchasing power among large beverage and personal care brand owners. Mondi Group leverages its European paper and film manufacturing footprint to anchor long-term supply agreements with bottlers. Constantia Flexible Packaging competes through specialized metalized film capabilities for premium cosmetic applications. Cosmo Films sustains cost leadership in biaxially oriented polypropylene through integrated resin-to-film operations in India.
Roll-fed wraparound label substrates are continuous web materials, typically 30-80 micron caliper, engineered for high-speed application onto cylindrical containers using hot-melt or pressure-sensitive adhesive systems. Polypropylene dominates volume due to moisture resistance and printability on flexographic and gravure presses. Food & Beverage applications command the largest share of substrate consumption, though Pharmaceuticals represents the fastest-expanding margin pool as serialization and tamper-evidence requirements multiply. Coating technology selection increasingly stratifies by end-use: UV coated finishes lead in personal care for shelf impact, while matte and satin treatments expand in organic food positioning.
FDA regulations on indirect food contact substances govern substrate composition for beverage applications in the United States. REACH and the EU Packaging and Packaging Waste Regulation impose recyclability and substance restriction mandates across European supply chains. India's BIS certification requirements for packaging materials create compliance thresholds for imported substrates. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional substrate qualification investments versus centralized manufacturing with freight cost absorption.
Market Dynamics
High-speed bottling line conversion is compressing substrate specification windows, forcing converters to synchronize caliper tolerances with applicator mechanics across three continents.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates in Europe are pulling polypropylene substrates into beverage supply chains ahead of paper alternatives.
- Hot-melt adhesive compatibility:Substrate surface energy engineering now enables 600-bottle-per-minute lines without label flagging or wrinkling.
- India:Bottling capacity expansion in Maharashtra and Gujarat is generating concentrated demand for 40-micron BOPP webs.
Market Restraints
- Propylene monomer volatility:Crude-linked resin pricing creates margin compression for non-integrated film producers.
- German substrate concentration:Three specialized coating facilities supply premium UV-finished stocks to European cosmetic brand owners.
- Paper substrate moisture failure:Hydrophilic fiber swelling limits beverage cold-chain applications below 4°C.
Strategic Opportunities
- Pharmaceutical serialization:Tamper-evident wraparound formats are capturing compliance-driven demand from track-and-trace mandates.
- Digital print convergence:Electrophotographic presses paired with pressure-sensitive substrates enable lot-size-one customization for craft beverage segments.
- Extended producer responsibility frameworks:Germany's VerpackG and France's Citeo eco-modulation are rewarding mono-material polypropylene label structures with fee reductions.
Industry Challenges
- Gravure cylinder lead times:Eight-week engraving queues delay brand owner packaging refreshes.
- Adhesive-substrate matching:Hot-melt formulation changes require requalification of face stock release properties.
- ISO 9001 certification backlog:Converter audit scheduling stretches to five months in high-demand periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roll-fed Wraparound Label Substrates Market |
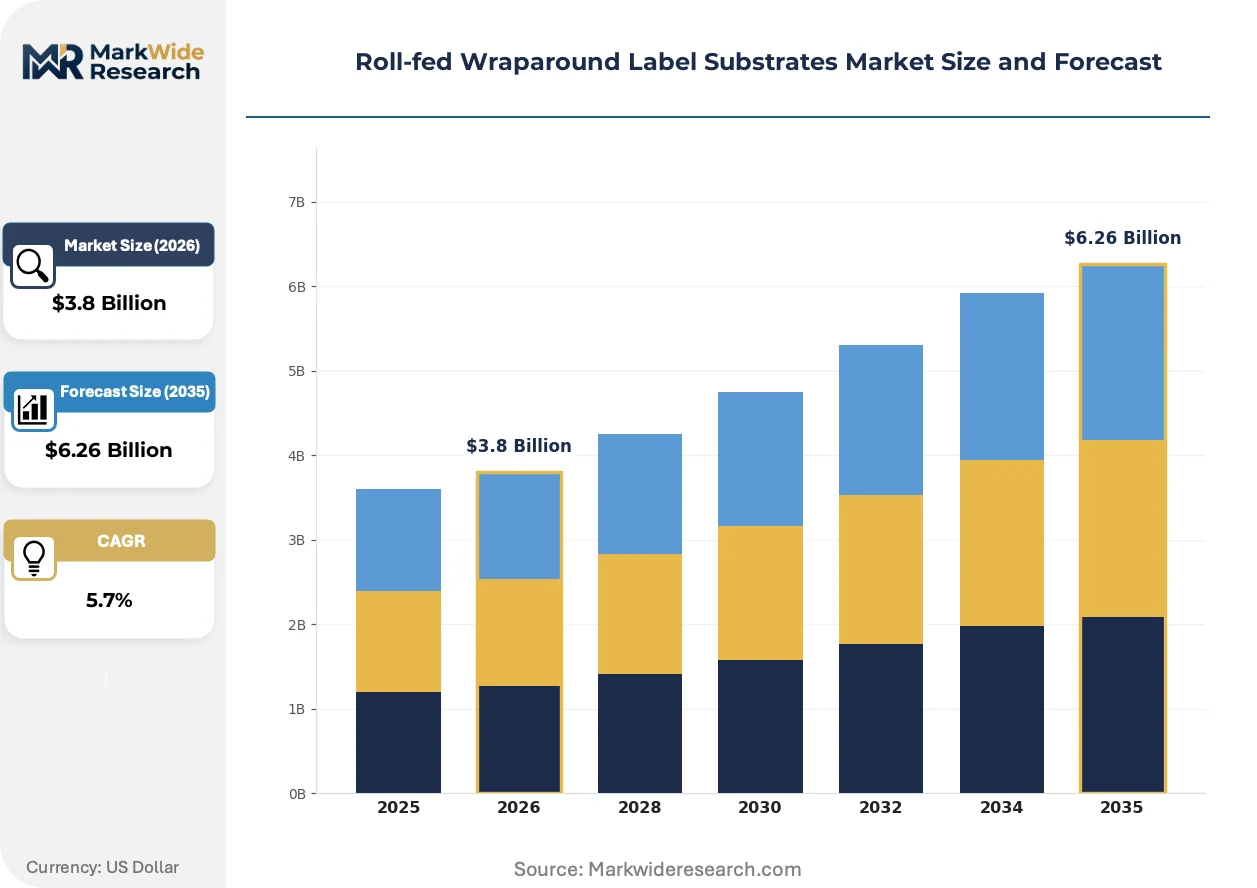
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyester, Polyethylene, PVC, Paper, Metalized Films Application: Food & Beverage, Personal Care, Pharmaceuticals, Chemicals, Electronics, Household Products End User: Manufacturers, Packaging Converters, Label Printers, Brand Owners, Contract Packagers, Distributors Coating Technology: Glossy, Matte, Satin, Embossed, UV Coated, Varnished |
| Companies Covered | Mondi Group, Constantia Flexible Packaging, Cosmo Films, Fort Dearborn Company, Inland Packaging, Traco Manufacturing, Roll On Labels, Vintech Polymers, Grip Tight Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll-fed Wraparound Label Substrates Market Trends and Innovations
Water-based coating chemistry is displacing solvent systems across European converting facilities, altering capital equipment planning and emission compliance strategies simultaneously.
Digital print integration is decentralizing short-run label production from centralized gravure houses to regional converting operations. Craft distillers and regional beverage brands are adopting web-to-print workflows for seasonal SKUs. This capability is compressing minimum order quantities from 500,000 labels to 10,000 while fragmenting substrate purchasing across smaller converters.
REACH substance restriction updates are forcing reformulation of UV varnish photoinitiators used in cosmetic label finishing. ECHA's 2024 candidate list expansion targets specific aromatic amine derivatives common in high-gloss coatings. Personal care brand owners in France and Germany are accelerating qualification of amine-free alternative chemistries ahead of authorization deadlines.
Direct brand owner engagement with substrate producers is displacing traditional distributor relationships in North American beverage procurement. Large bottlers are negotiating specification-lock contracts that bypass regional paper merchants. This pattern concentrates purchasing power among three multinational beverage corporations while squeezing margin structures for independent label converters in California and Texas.
Roll-fed Wraparound Label Substrates Market Segmentation
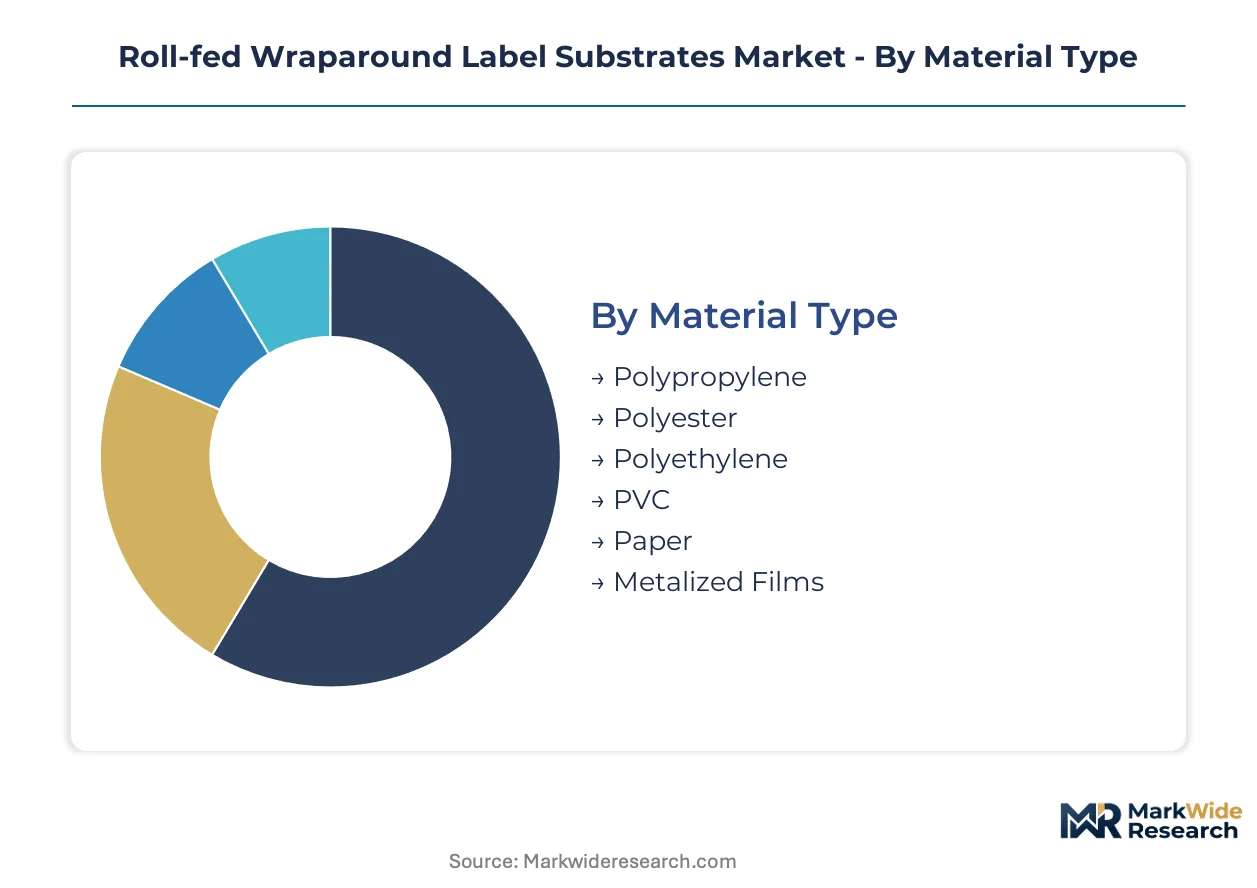
Substrate specification windows are compressing as bottling line speeds climb past 600 bottles per minute. Material selection now hinges on adhesive compatibility, print method, and recyclability credentials rather than cost alone. Each segmentation axis reveals distinct margin pools and technical barriers to entry.
Material Type:
Biaxial orientation and surface energy engineering separate commodity film from performance-grade substrate.
- Polypropylene:Moisture-resistant BOPP webs dominate beverage cold-chain applications through dimensional stability across 4°C to 40°C temperature swings. German bottlers and Maharashtra-based converters are locking in 40-micron specifications for high-speed roll-fed lines. REACH-compliant mono-material structures qualify for reduced extended producer responsibility fees under France's Citeo eco-modulation.
- Polyester:PET substrates deliver superior tensile strength for tamper-evident pharmaceutical wraps requiring precise die-cutting. FDA indirect food contact clearance and EMA serialization mandates are pulling polyester into compliance-driven European pharma supply chains. Thermal stability supports hot-fill applications beyond polypropylene limits.
- Polyethylene:Lower modulus LDPE films suit squeezable personal care containers where conformability trumps stiffness.
- PVC:Shrinking regulatory acceptance in EU packaging streams limits PVC to legacy industrial chemical labeling.
- Paper:Hydrophilic fiber swelling restricts paper substrates to dry-goods applications above 4°C storage thresholds.
- Metalized Films:Vacuum-deposited aluminum layers create premium cosmetic shelf impact through reflectivity and barrier properties.
Polypropylene leads on scale; metalized films lead on momentum.
Application:
End-use specifications stratify by regulatory exposure and line speed requirements.
- Food & Beverage:Cold-chain distribution and carbonation pressure demand moisture-resistant substrates with hot-melt adhesive compatibility. Indian bottling expansion in Gujarat and United States craft beverage digital print adoption are fragmenting order quantities from 500,000 to 10,000 units. FDA food contact substance regulations govern substrate composition for domestic US bottlers.
- Pharmaceuticals:Serialization and tamper-evidence mandates are expanding margin pools fastest as track-and-trace regulations multiply across EU member states and India. UV coating chemistries face REACH substance restrictions on aromatic amine photoinitiators, forcing reformulation of high-gloss finishes ahead of ECHA authorization deadlines.
- Personal Care:Shelf-impact requirements favor UV-coated and embossed finishes for premium positioning.
- Chemicals:GHS labeling compliance drives durable substrate selection for hazard communication durability.
- Electronics:Anti-static properties and cleanroom compatibility constrain material options for component labeling.
- Household Products:Cost-optimized polyethylene substrates serve high-volume bleach and detergent applications.
Food & Beverage commands volume concentration; Pharmaceuticals climbs the fastest.
End User:
Purchasing power is consolidating among entities controlling specification lock and volume commitment.
- Brand Owners:Direct substrate producer engagement is displacing distributor relationships in North American beverage procurement. Large bottlers negotiate specification-lock contracts that bypass regional paper merchants, concentrating purchasing power among three multinational corporations.
- Packaging Converters:Gravure cylinder eight-week lead times and ISO 9001 certification backlogs stretching to five months create operational bottlenecks.
- Label Printers:Digital print integration enables web-to-print workflows for regional craft distillers and seasonal SKU proliferation.
- Manufacturers:In-house film extrusion capabilities anchor cost positions for integrated producers.
- Contract Packagers:Flexible substrate sourcing requirements serve multi-brand fulfillment operations.
- Distributors:Margin compression from direct brand owner procurement is squeezing independent converter relationships in California and Texas.
Brand owners lead on scale; label printers lead on momentum.
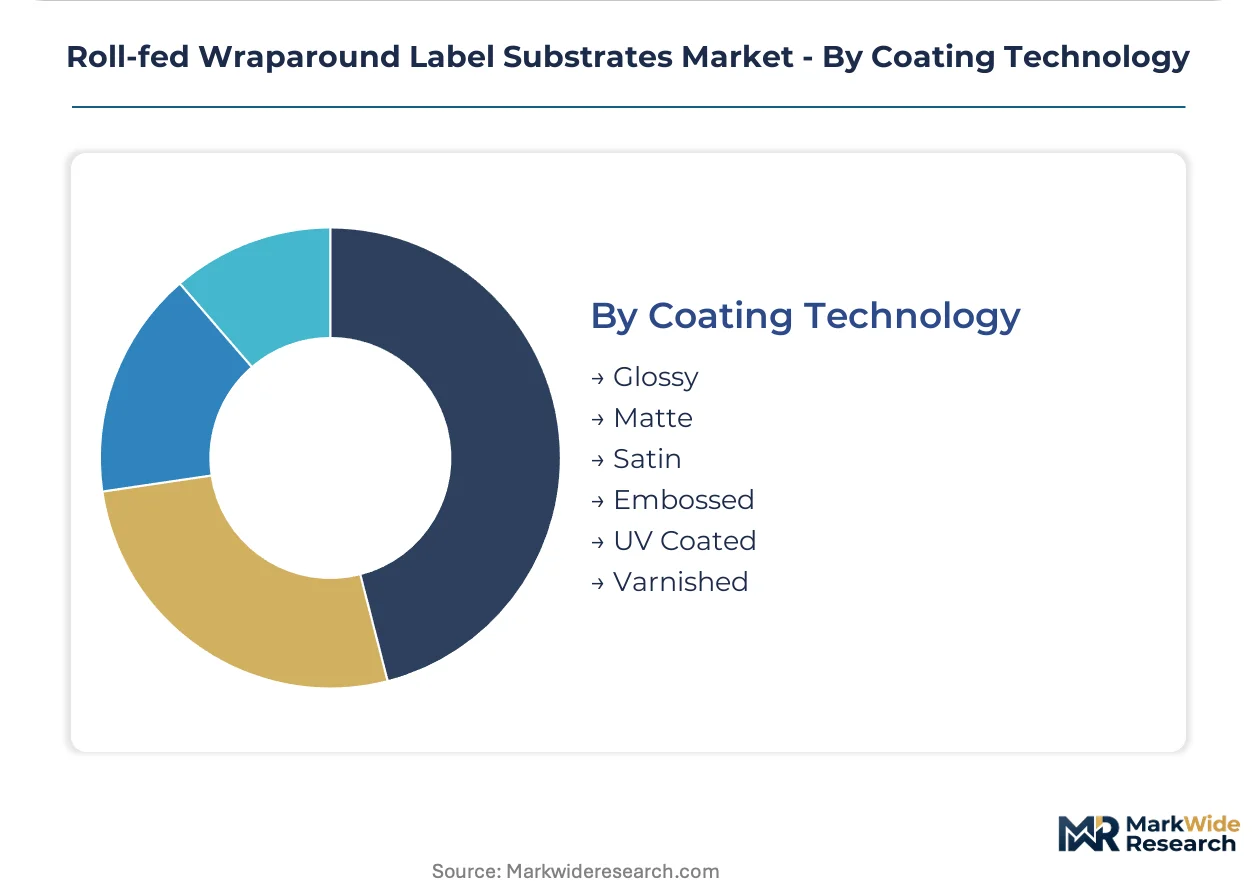
Coating Technology:
Surface finish selection increasingly signals product positioning and regulatory compliance status.
- UV Coated:High-gloss finishes dominate personal care shelf impact but face REACH-driven reformulation of photoinitiator chemistries. ECHA's candidate list expansion targets specific aromatic amine derivatives, accelerating amine-free alternative qualification in France and Germany.
- Matte:Satin and matte treatments expand in organic food positioning where understated aesthetics signal sustainability credentials.
- Glossy:Standard solvent-based glossy coatings are yielding to water-based chemistry across European converting facilities.
- Satin:Intermediate reflectivity serves mass-market beverage applications balancing cost and appearance.
- Embossed:Tactile finishes create premium differentiation for cosmetic and spirits applications.
- Varnished:Conventional varnish systems retain share in cost-sensitive industrial labeling.
UV coated leads on scale; matte leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between REACH-mandated reformulation costs in Europe and BIS certification thresholds in India is redirecting substrate qualification investments toward lower-compliance-cost manufacturing clusters. Production migration follows the cost-of-compliance gap.
United States
FDA indirect food contact substance regulations govern beverage substrate composition, forcing converters to maintain dual qualification tracks for domestic and export-bound stocks. Direct brand owner procurement is displacing regional paper merchant relationships in California and Texas bottling corridors. Large multinational beverage corporations now negotiate specification-lock contracts that bypass traditional distribution channels entirely.
Germany
VerpackG extended producer responsibility framework rewards mono-material polypropylene structures with fee reductions, pulling recyclable substrates ahead of paper alternatives. ECHA's 2024 candidate list expansion targets aromatic amine photoinitiators in UV varnish systems, forcing amine-free chemistry qualification ahead of authorization deadlines. Three specialized coating facilities in Baden-Württemberg and North Rhine-Westphalia supply premium UV-finished stocks to European cosmetic brand owners.
India
BIS certification requirements for packaging materials create compliance thresholds for imported substrates, favoring domestic resin-to-film integration. Bottling capacity expansion in Maharashtra and Gujarat is generating concentrated demand for 40-micron BOPP webs from high-speed roll-fed applicator conversions. Cosmo Films anchors cost leadership through captive resin production at integrated operations serving regional converters.
France
Citeo eco-modulation fee structures reward mono-material label architectures with reduced extended producer responsibility contributions. Personal care brand owners in the Île-de-France cluster are accelerating qualification of REACH-compliant coating chemistries ahead of ECHA substance restriction deadlines. Paris-based cosmetic houses are driving specification windows for embossed and tactile finishes in premium spirits applications.
Roll-fed Wraparound Label Substrates Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated film producers capturing margin in commodity BOPP while coating specialists defend position in premium cosmetic finishes. The vendor base stratifies into three tiers: multinational converters with captive resin supply, regional specialists with gravure and flexographic asset bases, and digital-enabled job shops serving fragmented craft beverage demand. Two dominant competitive moves are reshaping positioning: backward integration into resin production to offset propylene monomer volatility, and specification-lock contracting that concentrates purchasing power among three multinational beverage corporations.
Within the integrated-film tier, Mondi Group leverages its European manufacturing footprint to anchor long-term supply agreements, while Cosmo Films exemplifies cost leadership through resin-to-film integration at Indian operations. Constantia Flexible Packaging occupies a position among specialized converters where metalized film capabilities serve premium cosmetic applications requiring barrier and reflectivity performance. These three entities represent distinct archetypes: geographic-scale bundling, vertical cost control, and premium specialization respectively.
| Leading Market Players |
|---|
| Mondi Group |
| Constantia Flexible Packaging |
| Cosmo Films |
| Fort Dearborn Company |
| Inland Packaging |
| Traco Manufacturing |
| Roll On Labels |
| Vintech Polymers |
| Grip Tight Packaging |
| Others |
Pricing and Supply Chain Analysis
Specification-lock procurement by three multinational beverage corporations is compressing distributor margins and forcing substrate producers toward direct contracting models that eliminate traditional paper merchant intermediaries. This buyer consolidation concentrates volume commitments into long-term supply agreements, shifting pricing power upstream while squeezing independent converters in California and Texas bottling corridors.
Pricing Analysis
Distributor margin compression now defines the channel economics as brand owners negotiate direct-to-producer contracts that bypass regional merchants entirely. Three-tier pricing structure across premium, standard, and economy levels stratifies by coating sophistication and certification grade, with UV-finished cosmetic stocks commanding substantial premiums over commodity BOPP. Cost compression in standard-grade polypropylene is intensifying because integrated resin producers leverage captive feedstock supply, while independent film converters face margin erosion from propylene monomer volatility. Craft beverage brand owners exhibit highest price sensitivity due to fragmented order quantities, whereas pharmaceutical serialization mandates render compliance-grade polyester buyers relatively insensitive to unit cost.
Supply Chain Analysis
Recyclable substrate returns and post-consumer polypropylene collection flows are emerging as critical inputs for closed-loop manufacturing systems in Germany and France. Resin-to-film production concentrates in India, Germany, and the United States, with captive propylene supply anchoring cost positions for integrated operators. Raw material dependencies center on propylene monomer, photoinitiator chemistries for UV coatings, and hot-melt adhesive formulations. Single-source vulnerability in gravure cylinder engraving creates eight-week bottlenecks that delay packaging refreshes. Distribution runs through specification-locked direct contracts with multinational bottlers, supplemented by regional converter networks serving fragmented craft beverage demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where premium coating specifications and REACH-compliant chemistries capture expanding margin pools as brand owners prioritize shelf impact and regulatory compliance over unit cost minimization.
For Market Incumbents: Acquire specialized coating facilities in Baden-Württemberg and North Rhine-Westphalia to defend premium cosmetic substrate positioning against metalized film specialists. Backward integration into resin production offsets propylene monomer volatility, while ISO 9001 certification investments reduce audit scheduling backlogs that currently stretch operational timelines. For New Entrants and Emerging Players: Regional craft distillers and seasonal SKU producers represent the most penetrable buyer archetype as digital print adoption fragments order quantities from 500,000 to 10,000 units. Web-to-print workflow partnerships with decentralized converting operations offer a viable go-to-market angle, bypassing capital-intensive gravure infrastructure while capturing margin from short-run label proliferation. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated resin-to-film producers possessing captive propylene supply and BIS certification for Indian domestic market access. Long-term viability hinges on qualification for extended producer responsibility fee reductions under Germany's VerpackG and France's Citeo eco-modulation. Practitioners should monitor ECHA substance restriction timelines for aromatic amine photoinitiators as inflection indicators for coating chemistry reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive propylene supply insulates margin from crude-linked monomer volatility affecting non-integrated competitors. |
| REACH-Compliant Coating Qualification | Amine-free UV varnish chemistry secures extended producer responsibility fee reductions under France's Citeo framework. |
| Digital Print Infrastructure Deployment | Electrophotographic press capacity captures fragmented craft beverage demand for lot-size-one customization. |
| Specification-Lock Contract Negotiation | Direct brand owner agreements in North America bypass distributor margins and secure multi-year volume commitments. |
| BIS Certification Investment | Domestic Indian qualification creates compliance barriers against imported substrates in Maharashtra and Gujarat bottling corridors. |
Research Methodology
Direct dialogue with substrate procurement managers at multinational beverage corporations, coating facility technical directors in Germany, gravure converter operations heads, and regulatory affairs specialists at personal care brand owners anchored qualitative findings. Secondary validation drew from FDA indirect food contact substance filings, ECHA candidate list updates, BIS packaging material certifications, and EU Packaging and Packaging Waste Regulation implementation guidance. Bottom-up and top-down triangulation reconciled converter capacity data with brand owner procurement volume disclosures.
Bottom-up modeling aggregated substrate consumption by material type, coating technology, and end-use application across the projection horizon. Segmentation dimensions included polypropylene versus polyester versus metalized film grades, UV-coated versus matte versus embossed finishes, and food and beverage versus pharmaceutical versus personal care applications. CAGRs were derived from trend extrapolation of bottling line conversion rates and regulatory compliance cost trajectories. Forecast inputs incorporated propylene monomer price elasticity and digital print adoption curves in craft beverage segments.
Underlying measurement precision varies by segment; commodity BOPP specifications carry tighter precision than emerging pharmaceutical serialization substrates where qualification timelines remain uncertain. Forecasts reflect assumptions regarding REACH substance restriction implementation pacing and Indian bottling capacity expansion trajectories. Practitioners should monitor ECHA authorization deadlines and extended producer responsibility fee schedule revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Linerless Labels Market
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Global QR Code Labels Market
Labels
Laser Printable Wristbands Market
Labels
Waterproof and Weatherproof Label Market
Labels
Pin Feed Labels Market
Labels
Hot Melt Glue Labeler Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Inspection and Inventory Labels Market
Labels
Global Sensormatic Labels Market
Labels
Integrated Labeling System Market
Labels
Shrink Sleeve Labels Market
Labels
Extended Text Labels Market
Labels
Self-Adhesive Labels Market
Labels
Hang Tags Market
Labels
Label Applicator Market