
 Cutting Tool Packaging Market | 2026-2036
Cutting Tool Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cutting Tool Packaging Market Outlook
Specialized fabricators serving aerospace and medical device supply chains is redrawing procurement priorities across the cutting tool packaging landscape. Kennametal Ltd. leverages captive manufacturing scale to control protective format specifications for its own inserts and round tools. Seco Tools AB anchors its packaging strategy through integrated design centers in Sweden that synchronize box and blister development with coating workflows. rose plastic competes via deep specialization in customizable compartment boxes for indexable insert sets.
Cutting tool packaging encompasses engineered protective enclosures—typically fabricated from thermoformed plastics, die-cut cardboard, or injection-molded compartments—designed to prevent edge damage, corrosion, and dimensional degradation of precision cutting inserts, drills, and end mills during transit and storage. Blister formats with vacuum-formed PET or PVC cavities dominate high-volume insert distribution due to their unit cost structure and retail visibility, while rigid multi-compartment boxes command premium positioning among manufacturers requiring customized cavity layouts for mixed SKU sets. Plastic remains the leading material category by volume, though cardboard-foam hybrid formats are gaining traction among distributors responding to EU Packaging Directive recyclability mandates.
REACH in Europe restricts phthalate-based plasticizers in PVC blister films, compelling converters to validate alternative formulations or shift toward PET mono-material structures. FDA guidelines for indirect food-contact packaging materials influence U.S. exporters serving cutting tool applications with downstream food-processing equipment exposure. Stakeholders must monitor evolving extended producer responsibility schemes across multiple jurisdictions, as these frameworks will determine which material formats retain cost-competitive market access through the forecast horizon.
Market Dynamics
REACH compliance deadlines and EU Packaging Directive recyclability mandates are forcing converters to abandon multi-layer PVC blister formats in favor of mono-material PET structures, compressing legacy equipment utilization rates across European thermoforming operations.
Growth Catalysts
- Precision machining contractor expansion:Aerospace and medical device fabricators in Germany's Stuttgart corridor are scaling protective packaging procurement for indexable insert sets, creating sustained order flow for rigid compartment box formats.
- REACH Article 33 disclosure requirements:ECHA enforcement is accelerating validation of phthalate-free plasticizer alternatives, opening substitution contracts for converters with certified mono-material capabilities.
- Thermoformed PET cost convergence:Vacuum-forming equipment retrofits for mono-material processing are reaching payback thresholds faster than multi-layer line replacements, pulling mid-cap converters into compliant format production.
Market Restraints
- Raw material volatility in petroleum-derived films:Naphtha price swings transmit directly to PET and PVC sheet costs, squeezing converter margins on fixed-price annual contracts with cutting tool distributors.
- Equipment lock-in at legacy thermoformers:Multi-layer blister lines in Solingen and Stuttgart industrial zones face stranded asset risk as mono-material retrofits require capital outlays exceeding 60% of replacement value.
- Cardboard-foam hybrid substitution:EU Packaging Directive recyclability preferences are diverting volume toward fiber-based formats that compete on sustainability credentials despite inferior moisture protection for coated inserts.
Strategic Opportunities
- Medical device packaging certification:ISO 11607 compliance for sterile barrier systems opens adjacent revenue streams for converters already validating cleanroom thermoforming for cutting tool applications.
- Extended producer responsibility schemes:Germany's Verpackungsgesetz modulation fees reward mono-material designs with lower compliance costs, creating margin expansion for early format adopters.
- Digital printing integration:Inline variable data printing on thermoformed cavities enables lot-traceable packaging for aerospace supply chains without secondary labeling operations.
Industry Challenges
- Multi-material separation expertise:Converters lack technical staff trained in mono-material rheology optimization, slowing production ramp-ups for compliant blister formats.
- Validation timeline compression:ECHA substance of very high concern candidate list updates require 18-month requalification cycles that outpace converter R&D staffing levels.
- Coating workflow synchronization:Packaging design centers must align cavity specifications with PVD coating thickness variations, creating interdepartmental coordination friction at integrated cutting tool manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutting Tool Packaging Market |
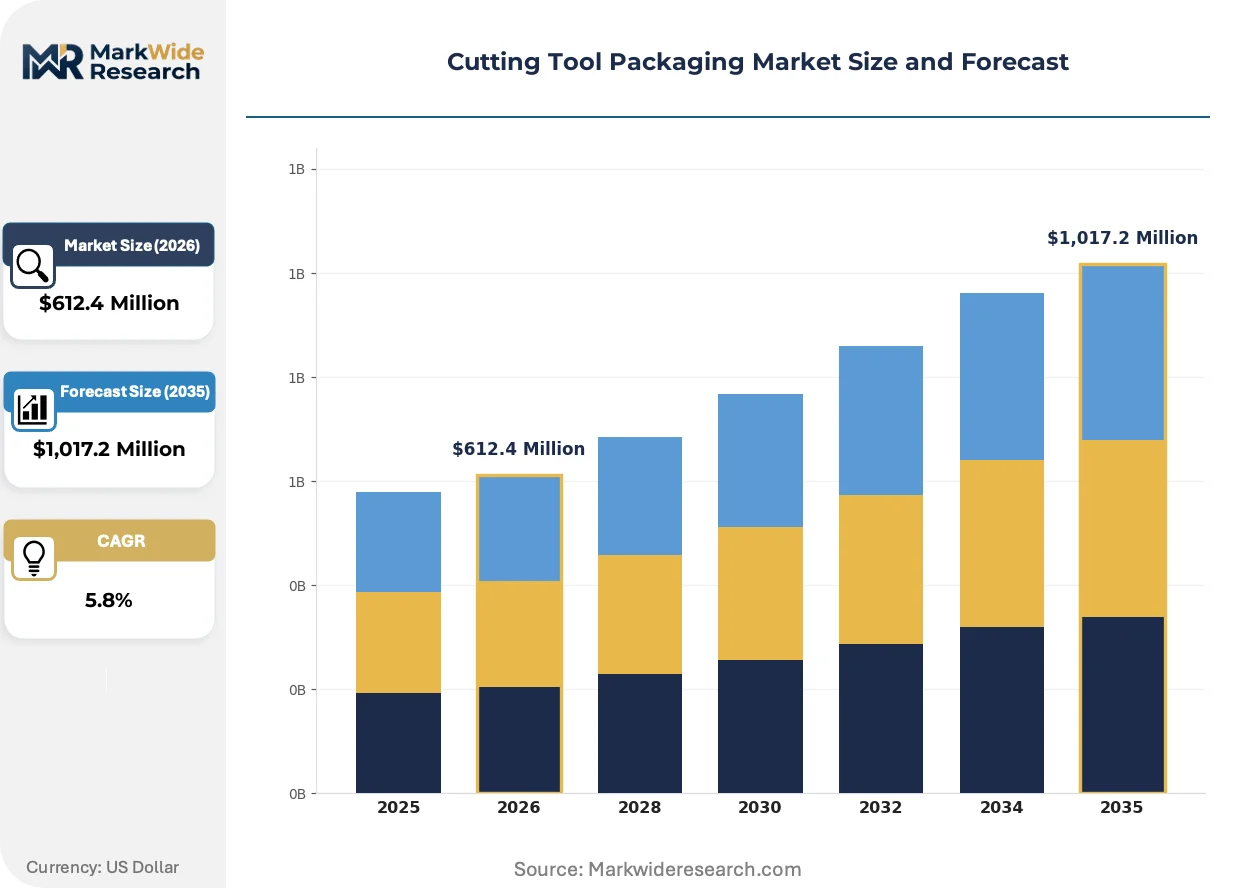
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Blisters, Tubs, Pouches Material: Plastic, Metal, Cardboard, Foam Feature: Durability, Customization, Transparency, Stackability End User: Manufacturers, Retailers, Distributors, Fabricators |
| Companies Covered | Dormer Pramet, Seco Tools AB, Plasel Plastic, Mapal Dr. Kress KG, OSG Corporation, rose plastic, Kennametal Ltd., Emuge Corporation, American Cutting Edge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutting Tool Packaging Market Strategic Shifts
Mono-material thermoforming is decomposing legacy multi-layer supply relationships while digital traceability requirements and circular economy compliance are rewriting format selection criteria across European precision manufacturing supply chains.
Mono-material PET thermoforming is decomposing the established PVC-PET-PE multi-layer structure that dominated high-volume insert packaging for two decades. Precision machining contractors in Germany are specifying vacuum-formed PET cavities exclusively for new supplier qualifications, compressing demand for legacy equipment at converters still running multi-layer lines. The structural consequence is accelerated asset retirement in industrial zones where thermoforming capacity was optimized for phthalate-plasticized PVC formulations.
REACH Annex XIV authorization requirements for di(2-ethylhexyl) phthalate are forcing immediate formulation switches across European blister film supply chains. Converters serving cutting tool distributors must validate alternative plasticizers or complete PET mono-material line conversions before sunset date enforcement. Medical device packaging applications face the tightest compliance timelines, with notified body reviews extending qualification cycles beyond typical procurement lead times.
Consolidated procurement desks at aerospace tier-one suppliers are unbundling packaging specification authority from cutting tool purchasing decisions. Category managers now mandate recyclable mono-material formats independent of tool performance metrics, displacing legacy supplier relationships where packaging was bundled with insert supply contracts. This pattern concentrates in Germany's Baden-Württemberg industrial corridor, where Stuttgart-based fabricators coordinate sustainability requirements across multi-site machining operations.
Cutting Tool Packaging Market Segmentation
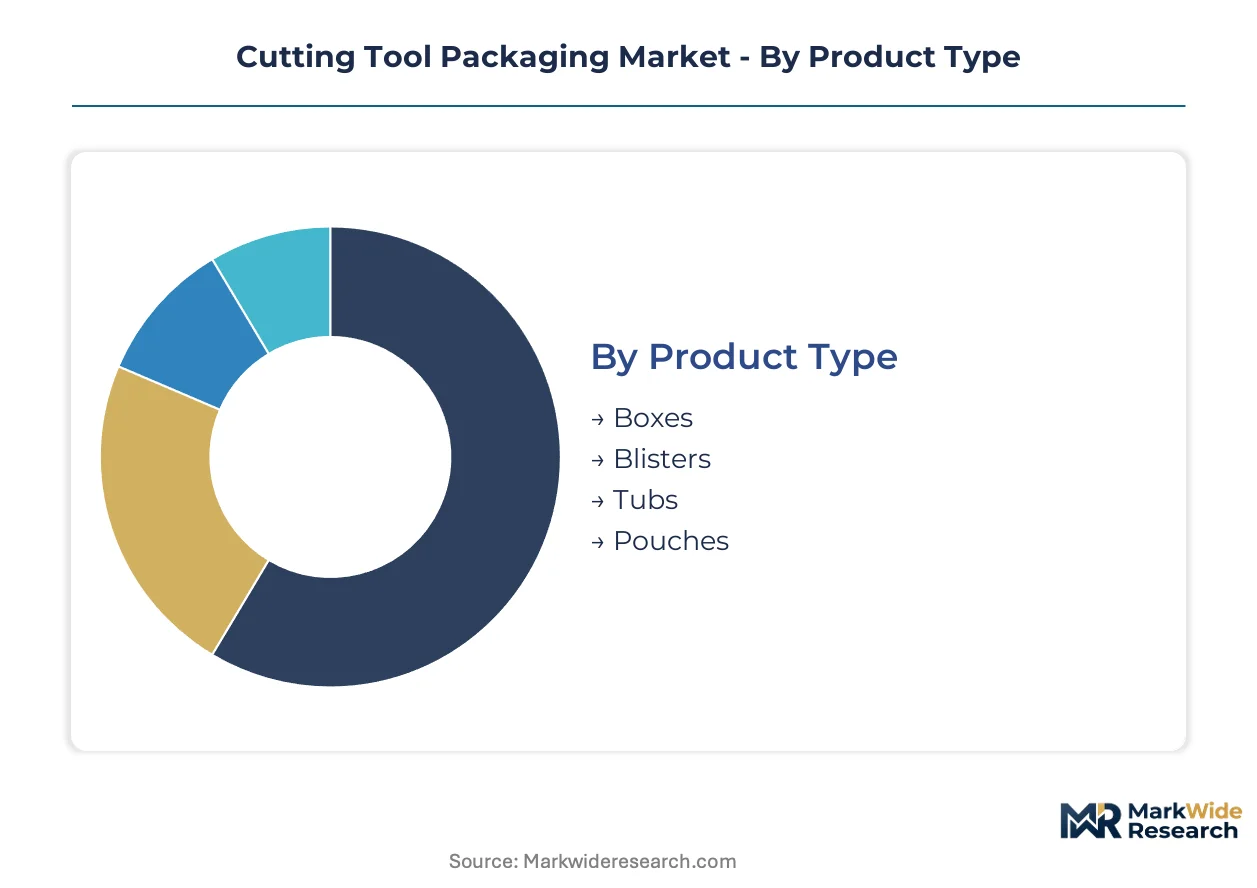
Packaging format selection in the cutting tool sector hinges on regulatory compliance thresholds, coating compatibility requirements, and supply chain traceability mandates. Each segmentation dimension carries distinct technical and commercial weight across aerospace, medical device, and precision machining procurement workflows.
Product Type:
REACH Article 33 disclosure requirements and EU Packaging Directive recyclability mandates are forcing specification divergence across protective enclosure categories.
- Boxes:Rigid multi-compartment designs fabricated from injection-molded polypropylene or ABS dominate indexable insert sets requiring customized cavity layouts. Stuttgart-based aerospace fabricators specify these formats exclusively for mixed SKU procurement, prioritizing dimensional stability during automated handling.
- Blisters:Vacuum-formed PET cavities with heat-sealed lidding films command high-volume distribution channels due to unit cost structures and retail visibility. ECHA enforcement against phthalate-based plasticizers is accelerating converter migration from PVC-PET-PE multi-layer structures toward mono-material alternatives.
- Tubs:Deep-drawn thermoformed containers serve bulk round tool shipments where vertical stacking strength outweighs individual cavity precision.
- Pouches:Flexible barrier films with desiccant integration protect coated inserts in moisture-sensitive PVD coating workflows.
Established volume favors Boxes; emerging adoption favors Blisters as mono-material retrofits reach payback thresholds.
Material:
Cost tier differentiation separates commodity formats from certified alternatives in regulated end-uses.
- Plastic:Thermoformed PET and injection-molded polypropylene constitute the leading volume category, with mono-material designs gaining modulation fee advantages under Germany's Verpackungsgesetz.
- Metal:Aluminum alloy trays and steel compartment systems serve reusable closed-loop logistics between coating facilities and machining centers, commanding premium positioning despite higher per-unit costs.
- Cardboard:Fiber-based formats with foam inserts are climbing fastest as distributors respond to EU recyclability preferences, though moisture protection limitations restrict deployment for coated insert applications.
- Foam:Polyethylene and polyurethane cushioning materials function primarily as hybrid components rather than standalone enclosures, integrated into cardboard-foam combinations or plastic tray inserts.
Plastic retains dominant volume; Cardboard-foam hybrids are expanding most quickly among sustainability-focused procurement desks.
Feature:
Application severity determines which functional attributes command specification priority across end-use verticals.
- Durability:Impact-resistant wall thicknesses and corner reinforcement specifications protect cutting edges during long-haul transit to remote machining operations.
- Customization:Cavity-specific designs accommodating insert geometry variations, coating thickness tolerances, and mixed SKU configurations dominate aerospace tier-one supplier requirements.
- Transparency:Visual identification without unsealing supports inventory verification in cleanroom environments and reduces handling contamination risks for medical device applications.
- Stackability:Interlocking geometric features maximize pallet density for distributor warehouse operations and automated storage retrieval systems.
Customization commands premium positioning; Stackability drives standard format adoption in high-volume distribution channels.
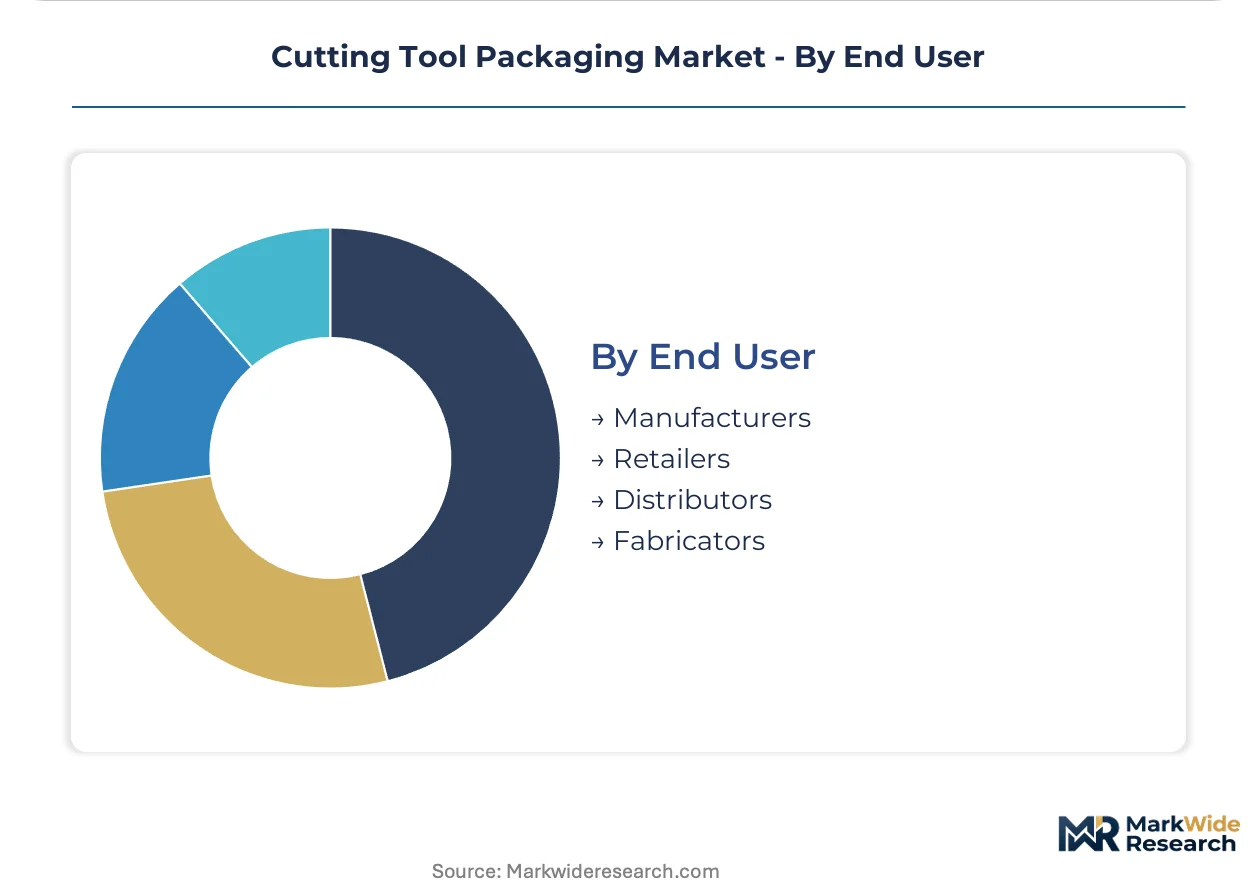
End User:
Customer type segmentation reveals divergent specification authority and sustainability mandate intensity.
- Manufacturers:Integrated cutting tool producers like Kennametal and Seco Tools specify captive packaging formats synchronized with coating workflows and brand presentation requirements.
- Retailers:Industrial supply distributors prioritize shelf-ready blister formats with standardized footprint compatibility across automated replenishment systems.
- Distributors:Independent channel intermediaries face the sharpest cost-recyclability tension, balancing EU Packaging Directive compliance against margin pressure from fixed-price annual contracts.
- Fabricators:Precision machining contractors in Germany's Baden-Württemberg corridor are consolidating procurement authority and mandating mono-material formats independent of tool performance metrics.
Manufacturer specifications anchor format innovation; Fabricator procurement consolidation is displacing legacy bundled supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German packaging converters supply thermoformed PET formats to precision machining contractors across Central Europe, with Stuttgart-based fabricators driving specification authority for mono-material designs.
Germany
Baden-Württemberg's aerospace fabricators mandate recyclable mono-material packaging for indexable insert procurement. ECHA enforces REACH Article 33 disclosure deadlines for phthalate-based plasticizers. Solingen's industrial corridor faces stranded asset risk as multi-layer thermoforming lines require retrofit capital exceeding replacement thresholds.
United States
FDA guidelines for indirect food-contact materials influence exporters serving downstream food-processing equipment applications. Precision machining contractors in Michigan and Ohio scale protective packaging procurement for automotive supply chains. Chicago-area distributors balance fixed-price annual contracts against petroleum-derived film volatility.
Japan
OSG Corporation anchors domestic demand for high-volume blister formats serving automotive and electronics machining. METI circular economy roadmaps encourage mono-material adoption across industrial packaging categories. Nagoya's Chubu manufacturing belt concentrates coating workflow synchronization requirements.
Sweden
Seco Tools AB integrates packaging design centers with PVD coating operations in Fagersta. ECHA substance of very high concern candidate list updates compress validation timelines for cleanroom thermoforming applications. Stockholm-based converters develop ISO 11607-compliant sterile barrier systems for adjacent medical device revenue streams.
China
Domestic cutting tool manufacturers source thermoformed compartments from local PET sheet processors serving export-oriented precision machining. MIIT industrial upgrading guidelines emphasize material efficiency in packaging supply chains. Yangtze River Delta converters retrofit vacuum-forming equipment for mono-material processing to meet EU importer specifications.
Cutting Tool Packaging Market Competitive Environment
Player mix skews toward integrated cutting tool manufacturers with captive packaging operations and specialized thermoforming converters serving distributor channels. Market structure concentrates around two strategic tiers: scale-driven producers synchronizing formats with coating workflows, and mid-cap specialists delivering customizable cavity layouts for mixed SKU sets. Dominant competitive moves include equipment retrofits for mono-material compliance and geographic expansion into medical device packaging adjacencies.
Among European-based fabricators, Seco Tools AB and rose plastic occupy distinct positioning vectors. Seco Tools AB exemplifies the integrated manufacturer archetype with in-house design capabilities. rose plastic represents specialized compartment box fabrication for indexable insert sets. Kennametal Ltd. anchors the North American tier through captive manufacturing scale controlling protective format specifications.
| Leading Market Players |
|---|
| Dormer Pramet |
| Seco Tools AB |
| Plasel Plastic |
| Mapal Dr. Kress KG |
| OSG Corporation |
| rose plastic |
| Kennametal Ltd. |
| Emuge Corporation |
| American Cutting Edge |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XIV authorization timelines for di(2-ethylhexyl) phthalate simultaneously gate supplier qualification and stratify price tiers across European thermoforming operations, compressing margins for converters lacking mono-material retrofit capabilities while rewarding early adopters with modulation fee advantages.
Pricing Analysis
Legacy multi-layer PVC-PET-PE blister lines, transitional mono-material PET retrofits, and next-generation digital-traceable formats command divergent price points across the procurement landscape. Three-tier pricing structure across premium, standard, and economy levels separates ISO 11607-certified medical-grade enclosures from industrial blister formats and commodity cardboard-foam hybrids. Cost compression in standard-tier PET sheet contracts is intensifying because naphtha price volatility transmits directly to fixed-price annual agreements with Stuttgart-based distributors. Precision machining contractors in Germany's Baden-Württemberg corridor exhibit lowest price sensitivity due to sustainability mandate compliance requirements, while independent distributors face acute margin pressure from recyclability-driven format switches.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for PET sheet imports serving Yangtze River Delta thermoforming clusters. Supply concentrates in Germany, China, and Japan, with Fagersta-based integrated manufacturers and Nagoya's Chubu belt anchoring coating-workflow-synchronized packaging production. Raw material dependencies span naphtha-derived PET resins, phthalate-free plasticizer formulations, and aluminum alloy substrates for reusable closed-loop systems. Single-source vulnerability concentrates in European PVC-PET-PE multi-layer film supply following ECHA enforcement actions. Distribution runs through captive manufacturing at integrated cutting tool producers, independent converter networks, and industrial supply distributors serving aerospace tier-one procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH implementation timelines and EU Packaging Directive enforcement windows creates white-space opportunities for converters with certified mono-material capabilities and medical device packaging adjacencies.
For Market Incumbents: Compound defensive positioning through captive coating-workflow integration and accelerated mono-material line retrofits in Solingen and Stuttgart industrial corridors. Threat substitution from cardboard-foam hybrid formats demands immediate response via moisture-barrier certification investments. Priority lever rests on ISO 11607 sterile barrier system qualification to capture medical device revenue streams before validation timeline compression eliminates qualification windows. For New Entrants and Emerging Players: ISO 11607 certification fast-track unlocks medical device packaging white space where incumbent validation backlogs extend beyond typical procurement lead times. Most penetrable segment concentrates in precision machining contractor procurement consolidation across Germany's Baden-Württemberg corridor. Go-to-market angle emphasizes digital printing integration for lot-traceable aerospace supply chain compliance without secondary labeling operations. For Investors and Strategic Acquirers: REACH sunset date enforcement reshapes the acquisition landscape toward converters with completed mono-material retrofits and cleanroom thermoforming capabilities. Long-term viability across the analysis window favors mid-cap specialists with deep customization expertise for mixed SKU indexable insert sets. Target acquisition archetype: European-based fabricators with validated phthalate-free formulations and established relationships with Stuttgart aerospace tier-one suppliers. Signal to monitor: ECHA substance of very high concern candidate list updates accelerating 18-month requalification cycles beyond converter R&D staffing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Retrofit | ECHA enforcement against phthalate plasticizers strands legacy multi-layer equipment without compliant format conversion. |
| ISO 11607 Certification Investment | Medical device sterile barrier qualification opens adjacent revenue streams beyond cutting tool applications. |
| Digital Printing Integration | Inline variable data capability enables lot-traceable packaging for aerospace supply chains. |
| Coating Workflow Synchronization | Packaging design center integration with PVD operations reduces interdepartmental specification friction. |
| Extended Producer Responsibility Optimization | Germany's Verpackungsgesetz modulation fees reward mono-material designs with lower compliance costs. |
Study Parameters
Initial hypotheses were tested against primary input from thermoforming operations managers, precision machining procurement directors, packaging design engineers, and regulatory compliance officers, then refined through secondary validation across ECHA substance restriction databases, EU Packaging Directive implementation reports, customs trade flow records, and SEC filings from integrated cutting tool manufacturers. Bottom-up volume estimates from converter capacity utilization and top-down demand segmentation from end-use procurement patterns were triangulated to constrain forecast variance.
Variance decomposition across product format, material substrate, functional feature tier, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory enforcement timelines. Industry-specific forecast inputs incorporated coating workflow synchronization requirements and extended producer responsibility fee structures under Germany's Verpackungsgesetz.
Underlying assumptions cover ECHA enforcement consistency, PET sheet cost convergence, and medical device packaging qualification timeline stability, with deviation risk concentrated in raw material volatility and regulatory timeline acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Thermal Insulation Packaging Market
Packaging Materials
China Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
Global Food Processing Seals Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Coconut Wraps Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Nigeria Packaging Market
Packaging Materials
Fanfold Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Water Soluble Pods Packaging Market