
 Wall Bed Market | 2026-2036
Wall Bed Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Bed Market Intelligence
Skilled carpentry and precision metalworking labor is bifurcating the wall bed competitive landscape, as craftsmanship-intensive European producers compete against automated Asian manufacturers. BESTAR Inc. leverages North American distribution scale to sustain volume leadership in the mid-market segment. Clei Srl anchors premium positioning through Italian design heritage and engineered hardware systems. Spaceman Innovations Pte Ltd. specializes in motorized, tech-integrated configurations for compact urban apartments across Southeast Asian cities.
A wall bed is a space-saving sleeping apparatus hinged at one end for vertical storage against a wall or within a cabinet enclosure, typically incorporating counterbalanced lift mechanisms rated for cycles between five thousand and fifteen thousand uses. The primary purpose is to reclaim floor area in residential, hospitality, and commercial environments where square footage commands premium value. Murphy Bed configurations dominate structural demand due to their established hardware ecosystem and contractor familiarity, while Sofa Bed hybrids capture the fastest growth as multifunctionality becomes a non-negotiable purchase criterion. Metal framing materials lead in commercial and student housing deployments for durability compliance, though Wood variants retain margin concentration in bespoke residential projects where aesthetic customization drives pricing power.
ISO 7170 furniture durability standards, the EU's CE marking requirements under the General Product Safety Directive, and the U.S. Consumer Product Safety Commission's tip-over prevention guidelines collectively shape product design mandates and market access conditions across major producing regions. Compliance with these frameworks determines whether manufacturers can supply institutional buyers in hospitality and student accommodation sectors. Stakeholders must monitor evolving fire-retardant material specifications and evolving building code definitions of permanent versus temporary sleeping fixtures, as these distinctions will determine which product categories qualify for specific zoning allowances and insurance classifications.
Market Dynamics
Urban housing densification in North American and European cities is compressing residential square footage, forcing developers to specify space-efficient sleeping apparatuses as standard fixtures rather than optional upgrades. This structural shift from discretionary to mandatory specification is rewiring procurement relationships between furniture manufacturers and institutional housing developers.
Growth Catalysts
- EU CE marking requirements under the General Product Safety Directive:Harmonized safety standards reduce cross-border compliance costs for manufacturers, accelerating market access across twenty-seven member states.
- Student accommodation developers:Purpose-built student housing in Germany, the United States, and Japan is specifying Murphy Bed configurations at scale to maximize bed density per floor plate.
- Counterbalanced lift mechanisms:Hardware innovations rated for fifteen thousand use cycles are extending product lifespans in commercial deployments, reducing total cost of ownership calculations for hospitality procurement teams.
Market Restraints
- Steel and aluminum input volatility:Metal framing materials face commodity price swings that compress margins on commercial-grade wall bed contracts with fixed pricing terms.
- Precision metalworking labor scarcity:European producers dependent on skilled craftsmanship face capacity constraints against automated Asian competitors with standardized output.
- Sofa Bed substitution:Multifunctional hybrid configurations capture buyer preference in residential segments, constraining pure wall bed volume in consumer markets.
Strategic Opportunities
- Motorized tech-integrated configurations:Voice-activated and app-controlled wall bed systems open premium positioning in compact urban apartments across Singapore, Hong Kong, and Tokyo.
- Fire-resistance code evolution in the United States:Updated building code definitions of permanent versus temporary sleeping fixtures create new zoning allowances for institutional specification.
- Micro-unit residential developers:Emerging cohort of single-occupancy housing projects in London, New York City, and Vancouver represents underpenetrated specification channel.
Industry Challenges
- ISO 7170 durability certification timelines:Third-party testing protocols for furniture cycle ratings extend product launch schedules by six to nine months.
- Tip-over prevention compliance complexity:U.S. Consumer Product Safety Commission anchoring requirements demand engineering redesigns for cabinet-enclosure systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Bed Market |
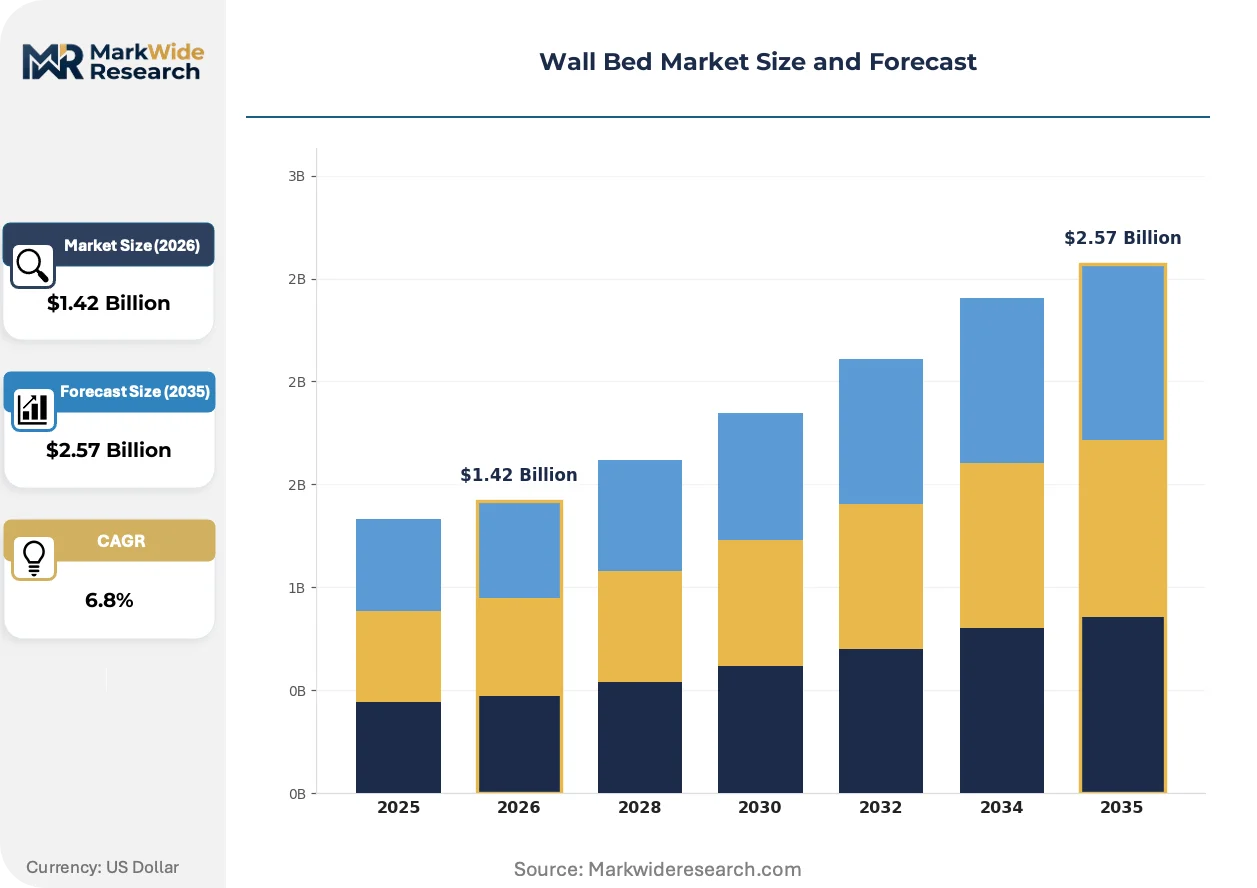
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Murphy Bed, Foldable Bed, Sofa Bed, Convertible Bed Material: Wood, Metal, Fabric, Composite End User: Residential, Hospitality, Office, Student Accommodation Distribution Channel: Online Retail, Specialty Stores, Furniture Outlets, Direct Sales |
| Companies Covered | The London Wallbed Company, Spaceman Innovations Pte Ltd., Murphy Wall Beds Hardware Inc., BESTAR Inc., The Bedder Way Company, SICO Incorporated, Wilding Wallbeds, Clei Srl, FlyingBeds International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Bed Market Strategic Shifts & Innovations
Hardware engineering and material science advances are fragmenting the wall bed competitive landscape into craftsmanship-preserving and automation-driven camps. Three distinct vectors are determining which manufacturers capture specification authority in institutional and residential channels.
Motorized lift systems with integrated sensor arrays are bifurcating the premium segment from manual counterbalance offerings. Hospitality developers in Tokyo and Singapore are specifying these configurations for serviced apartment portfolios. The technology is compressing price competition in the mid-market by establishing performance-based specification criteria that automated manufacturers can satisfy at scale.
REACH chemical restrictions and evolving EU fire-retardant material specifications are reshaping component sourcing decisions for cabinet enclosures and upholstery. Manufacturers serving institutional buyers must reformulate material specifications to maintain CE marking eligibility. German and Italian producers with captive finishing capabilities are responding faster than importers dependent on third-party coating suppliers.
Specification authority is migrating from individual consumers to procurement consortia representing multi-site student housing and hospitality operators. These concentrated buyers are unbundling installation services from product supply, forcing manufacturers to certify third-party contractor networks. The shift is most visible in the United States, where national student housing REITs now mandate standardized hardware platforms across their portfolios.
Wall Bed Market Segmentation
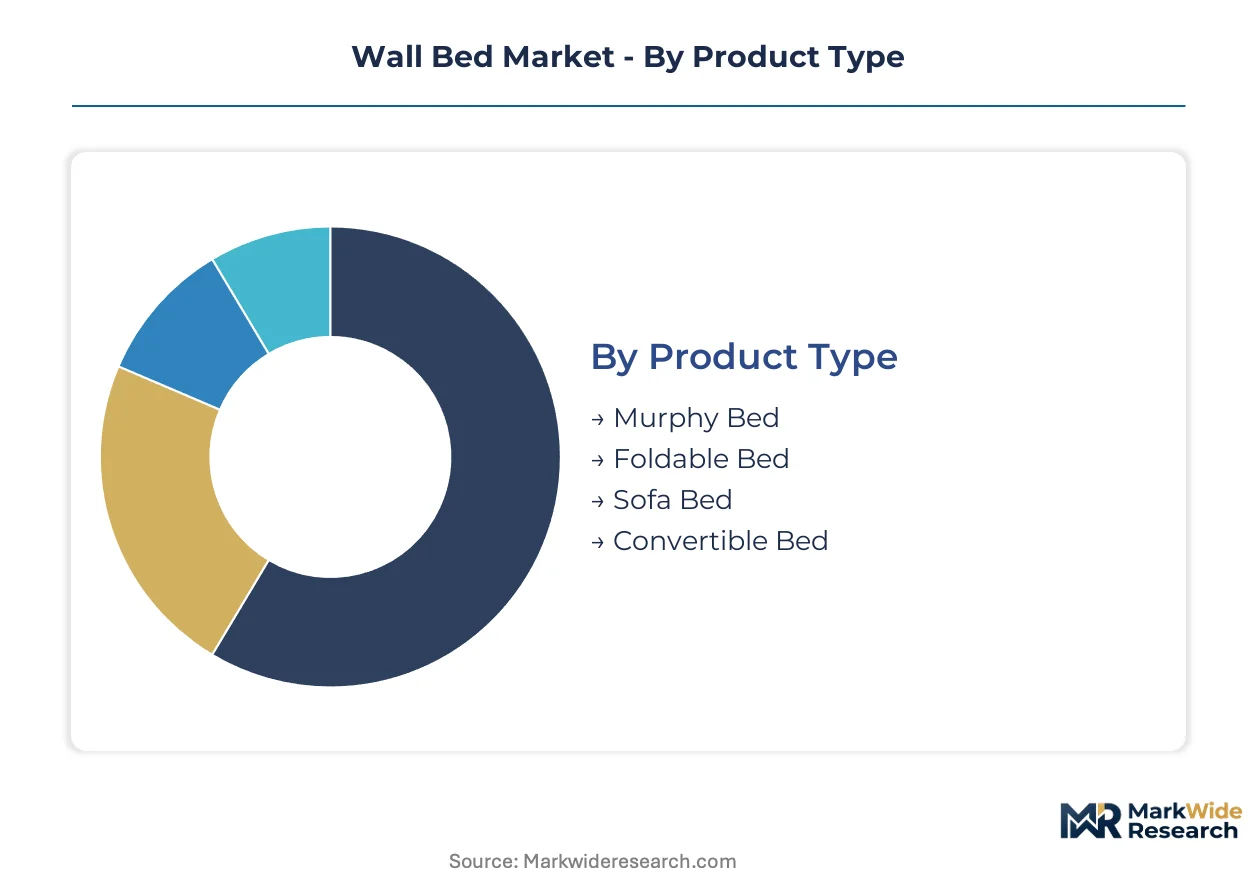
Wall bed procurement patterns diverge sharply across institutional and residential channels, with specification authority concentrating in distinct buyer types. Regulatory compliance requirements and installation complexity create natural segmentation boundaries that manufacturers must navigate to capture volume.
Product Type:
CE marking under the EU General Product Safety Directive and U.S. Consumer Product Safety Commission tip-over prevention guidelines impose divergent engineering requirements on each configuration, shaping which products qualify for institutional specification.
- Murphy Bed:Vertical wall-mounted systems with counterbalanced lift mechanisms rated for five thousand to fifteen thousand cycles. Demand concentrates in German and Japanese student housing developments where bed density per floor plate drives procurement decisions.
- Sofa Bed:Hybrid configurations integrating seating and sleeping functions through fold-out or pull-out mechanisms. Multifunctionality commands premium positioning in compact urban apartments across Singapore and Hong Kong, where single-room living mandates dual-purpose furniture.
- Foldable Bed:Collapsible frames without wall mounting, prioritizing portability over space reclamation.
- Convertible Bed:Modular systems transforming between desk, storage, and sleeping configurations.
Established volume favors Murphy Bed configurations; emerging adoption favors Sofa Bed hybrids.
Material:
Cost tier differentiation separates premium residential projects from high-volume commercial deployments, with raw material selection directly determining warranty terms and cycle ratings.
- Metal:Steel and aluminum framing systems delivering durability compliance for institutional buyers. Hospitality developers in the United States specify metal constructions for serviced apartment portfolios requiring fifteen-year replacement cycles.
- Wood:Solid hardwood and engineered timber variants retaining margin concentration in bespoke residential channels. Italian and German producers leverage captive finishing capabilities to satisfy REACH chemical restrictions on cabinet enclosures.
- Fabric:Upholstered surfaces for hybrid seating-sleeping configurations.
- Composite:Engineered wood-plastic and mineral-board materials balancing weight reduction with fire-resistance ratings.
Metal dominates commercial procurement volume; wood captures premium residential margin.
End User:
Customer type determines whether sales cycles run through contractor specification or direct consumer purchase, with institutional buyers unbundling installation from product supply.
- Student Accommodation:Purpose-built housing developers in Germany, the United States, and Japan specifying standardized hardware platforms at scale. National student housing REITs mandate cycle-rated mechanisms across multi-site portfolios.
- Residential:Individual homeowners and micro-unit developers prioritizing aesthetic customization. Bespoke projects in London and New York City command three-tier pricing stratification across premium, standard, and economy levels.
- Hospitality:Serviced apartment and extended-stay hotel operators.
- Office:Corporate wellness and nap room installations.
Student Accommodation drives standardization; Residential preserves customization premium.
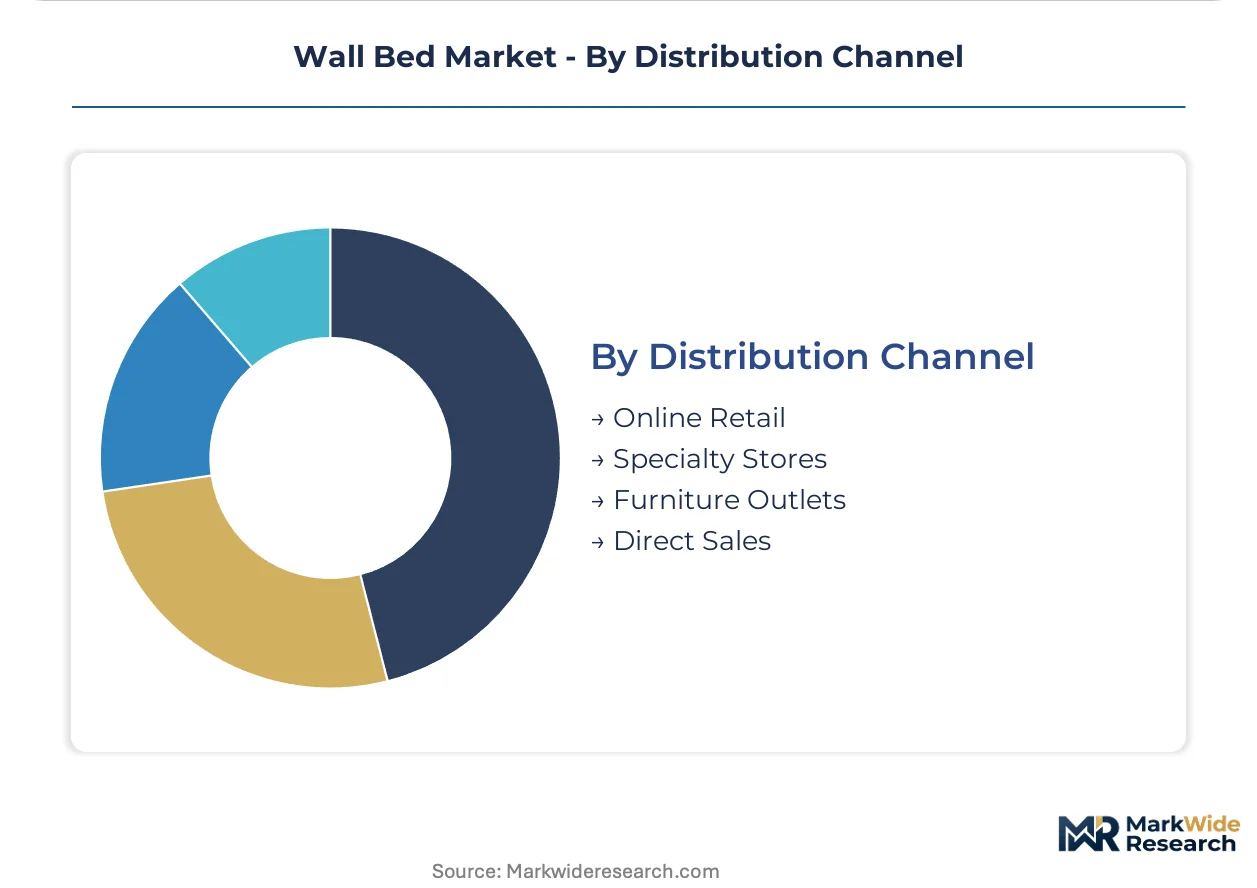
Distribution Channel:
Supply concentration in contractor networks versus direct-to-consumer platforms shapes margin retention and brand control for manufacturers.
- Specialty Stores:Curated showrooms with installation services attached. Physical presence in Tokyo and Vancouver markets enables specification authority for micro-unit developers requiring contractor certification.
- Direct Sales:Manufacturer-controlled channels bypassing retail markup. Hospitality procurement consortia in the United States leverage direct relationships to unbundle installation and negotiate volume pricing.
- Online Retail:E-commerce platforms with freight-to-curb delivery.
- Furniture Outlets:Mass-market retailers with limited assembly support.
Specialty Stores anchor premium positioning; Direct Sales captures institutional volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Consumer Product Safety Commission's tip-over prevention guidelines anchor regulatory influence in the largest national market, while CE marking under the EU General Product Safety Directive governs cross-border commerce across continental Europe. Japan's METI standards and building codes shape product specifications in dense urban corridors.
United States
Student housing REITs and micro-unit developers in New York City and San Francisco drive specification volume for cycle-rated Murphy Bed configurations. The U.S. Consumer Product Safety Commission mandates anchoring hardware for cabinet-enclosure systems, extending product development timelines. Dallas-Fort Worth and Austin housing clusters concentrate contractor networks certified for institutional installation.
Germany
Purpose-built student housing developments in Berlin and Munich specify standardized hardware platforms at scale to maximize bed density per floor plate. REACH chemical restrictions and EU CE marking requirements reshape component sourcing for cabinet enclosures. The Baden-Württemberg industrial corridor hosts producers with captive finishing capabilities responding faster than import-dependent competitors.
Japan
Tokyo and Osaka serviced apartment operators specify motorized lift systems with integrated sensor arrays for premium hospitality portfolios. METI durability standards and evolving fire-resistance codes determine product eligibility for institutional procurement. The Nagoya manufacturing cluster supplies precision-engineered counterbalance mechanisms rated for fifteen thousand use cycles.
Singapore
Compact urban apartment developers prioritize multifunctional Sofa Bed hybrids for single-room living configurations where dual-purpose furniture is mandatory. The country's building control regulations classify permanent versus temporary sleeping fixtures, affecting zoning allowances. Marina Bay and Orchard Road residential towers represent concentrated demand for tech-integrated space-saving solutions.
United Kingdom
London micro-unit developers command three-tier pricing stratification across premium, standard, and economy levels for bespoke residential projects. The UK's furniture fire safety regulations impose material specifications distinct from EU harmonized standards. Manchester and Birmingham student accommodation clusters drive mid-market volume for metal-framed commercial deployments.
Wall Bed Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the wall bed competitive landscape. Automated Asian manufacturers compete against craftsmanship-intensive European producers on cycle ratings and precision metalworking. Three strategic archetypes dominate: North American volume distributors leveraging scale, Italian design heritage specialists commanding premium positioning, and Southeast Asian motorized configuration innovators. Competitive moves concentrate on geographic expansion through third-party contractor certification and portfolio diversification into hybrid seating-sleeping configurations.
Within the craftsmanship-preserving tier, Clei Srl exemplifies Italian design heritage positioning through engineered hardware systems. BESTAR Inc. represents North American distribution scale advantages in mid-market segment penetration. Spaceman Innovations Pte Ltd. anchors the motorized tech-integration archetype for compact urban apartments. These three occupy distinct competitive spaces without direct overlap in specification channels or pricing tiers.
| Leading Market Players |
|---|
| The London Wallbed Company |
| Spaceman Innovations Pte Ltd. |
| Murphy Wall Beds Hardware Inc. |
| BESTAR Inc. |
| The Bedder Way Company |
| SICO Incorporated |
| Wilding Wallbeds |
| Clei Srl |
| FlyingBeds International |
| Others |
Cost & Logistics Intelligence
Automated Asian manufacturing scale compresses cost floors for metal-framed commercial configurations, while European craftsmanship-intensive producers defend premium positioning through captive finishing capabilities. This divergence concentrates supply authority in distinct pricing tiers, with procurement consortia exploiting the bifurcation to unbundle installation from product supply.
Pricing Analysis
Geographic price spreads separate Italian design heritage premiums from mass-market Asian imports, with three-tier pricing structure across premium, standard, and economy levels dominating residential channels. Price differentiation hinges on certification grade—ISO 7170 cycle ratings and CE marking compliance—and volume scale for institutional contracts. Pricing pressure stems from steel and aluminum commodity volatility compressing margins on fixed-price commercial agreements. Student accommodation developers exhibit highest price sensitivity through standardized hardware mandates, while hospitality operators in Tokyo and Singapore absorb premiums for motorized sensor-integrated systems.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes disrupt just-in-time delivery schedules for precision-engineered counterbalance mechanisms sourced from the Nagoya manufacturing cluster. Supply concentrates in China for automated metal framing production, Italy for captive hardwood finishing, and Germany for engineered hardware systems. Raw material dependencies include cold-rolled steel, aluminum extrusions, and REACH-compliant coating formulations. Tariff exposure on Chinese-manufactured components presents structural risk. Distribution runs through certified contractor networks for institutional buyers, with direct sales channels capturing hospitality procurement consortia volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wall bed market is recovering from cyclical compression in residential construction, with student housing development velocity serving as the primary demand accelerator. Procurement standardization across multi-site portfolios is consolidating specification authority, rewarding scale-aligned players.
For Market Incumbents: Secure cycle-rated mechanism certification across third-party testing protocols to defend against automated Asian competitors on institutional tenders. Invest in backward integration into precision metalworking capacity within the Baden-Württemberg corridor to mitigate skilled labor scarcity. Prioritize fire-resistance code compliance engineering to capture evolving U.S. zoning allowances for permanent sleeping fixture reclassification.
For New Entrants and Emerging Players: Installation service gaps in micro-unit residential developments across London and Vancouver represent white-space opportunity. Target motorized tech-integrated configurations for compact urban apartments in Singapore and Hong Kong where incumbent coverage is thin. Pursue direct-to-developer sales models bypassing established specialty store channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hospitality procurement consortia with multi-site service contracts and parts-replacement programs. Long-term viability over a five-to-ten year horizon favors manufacturers with captive hardware engineering and certified contractor network scale. Monitor student housing REIT capital deployment announcements as inflection signal for specification volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Contractor Network Certification | Institutional buyers unbundle installation, mandating certified third-party capacity. |
| Motorized System Development | Voice-activated and app-controlled configurations command premium in Tokyo and Singapore. |
| Fire-Resistance Compliance Investment | Updated U.S. building codes create zoning allowances for permanent fixture classification. |
| Backward Integration into Hardware | Captive counterbalance mechanism production defends margin against commodity volatility. |
| REACH-Compliant Material Reformulation | EU chemical restrictions require cabinet enclosure sourcing shifts to maintain CE marking. |
Research Approach
Operator-level perspectives from student housing developers, hospitality procurement directors, furniture contractors, and specialty store buyers anchored the qualitative base. Primary interviews combined with secondary validation against EU CE marking documentation, U.S. Consumer Product Safety Commission guidelines, ISO 7170 certification records, and trade flow data for steel and aluminum inputs. Bottom-up segment sizing triangulated against top-down macro housing density indicators across North American and European urban corridors.
Sensitivity analysis tested forecast robustness across commodity price scenarios and regulatory implementation timelines over the projection horizon. Segmentation dimensions modeled include product type, material grade, end-user category, and distribution channel, with regional adoption patterns capturing country-specific building code evolution. CAGRs derived from installed base replacement cycles and new construction penetration assumptions, incorporating student housing pipeline data and serviced apartment development registrations as volume anchors.
Forecasts assume regulatory continuity in EU REACH enforcement and U.S. tip-over prevention guidelines; material policy shifts would require re-modeling. Commodity price volatility and precision metalworking labor availability present specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Bed Head Panel Market
Bedroom Furniture
Global Mattress Market
Bedroom Furniture
Children Mattress Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
Luxury and Premium Mattress Market