
 India Upholstered Furniture Market | 2026-2036
India Upholstered Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
India Upholstered Furniture Market Foresight
Corporate office fit-outs is rebalancing toward co-working spaces and hybrid workplace configurations across Indian metros. Godrej & Boyce Manufacturing anchors its position through captive manufacturing scale across multiple states. Durian differentiates via specialized ergonomic seating lines targeting IT parks and BPO campuses. Featherlite leverages extensive retail showroom networks in South India to control last-mile customer access.
Uphstered furniture comprises padded seating and reclining products constructed with internal spring or foam cushioning systems, external textile or leather coverings, and engineered wood or metal framing, designed for comfort-driven residential and commercial interior applications. Fabric upholstery leads volume shipments due to cost accessibility and design versatility for Indian middle-class households, while leather commands concentrated margin pools in premium corporate and hospitality specification. The residential end-user segment dominates absolute consumption, though hospitality procurement is expanding fastest as hotel chains upgrade properties in tier-two cities.
BIS furniture safety standards, state-level fire safety codes under CEA guidelines for commercial buildings, and evolving ESG disclosure requirements under SEBI's BRSR framework collectively shape product certification and material sourcing obligations for manufacturers. Compliance costs are pushing mid-tier producers toward standardized component platforms that simplify multi-regulatory testing. Stakeholders must monitor how state-level municipal zoning reforms affect showroom expansion economics and last-mile delivery density.
Market Dynamics
Organized retail expansion into tier-two cities is compressing distribution timelines and forcing upholstery manufacturers to regionalize component sourcing around Maharashtra, Gujarat, and Tamil Nadu manufacturing clusters.
Growth Catalysts
- BIS flammability standards:Mandatory certification for upholstered seating in commercial buildings is filtering out unorganized competitors and consolidating procurement toward certified manufacturers.
- Co-working fit-outs:Flexible workspace operators across Bangalore and Mumbai are standardizing bulk ergonomic seating purchases, creating predictable volume pipelines for modular upholstery suppliers.
- Hotel property upgrades:Mid-market hospitality chains expanding into Jaipur, Kochi, and Chandigarh are driving specification-grade fabric upholstery demand for guest room renovations.
Market Restraints
- Polyester staple fiber volatility:Synthetic textile input costs fluctuate with crude-linked petrochemical pricing, squeezing margin predictability for fabric-upholstery producers serving price-sensitive residential segments.
- Tannery supply concentration:Finished leather availability clusters around Kanpur and Chennai processing hubs, exposing premium upholstery lines to localized environmental compliance shutdowns and hide supply interruptions.
- CEA electrical fire codes:Commercial building safety inspections under central electricity authority guidelines delay showroom openings and co-working space certifications, extending sales cycles for project-based upholstery orders.
Strategic Opportunities
- Kerala and Punjab residential penetration:Organized furniture retail remains underdeveloped in these high-disposable-income states, creating first-mover advantages for branded upholstery chains establishing exclusive dealership networks.
- SEBI BRSR disclosure mandates:Large listed corporations must now report sustainable sourcing metrics, creating preference pull for upholstery suppliers with certified recycled foam and FSC-tracked engineered wood framing.
- Direct-to-consumer digital configuration:Online platforms enabling custom fabric selection and modular dimension specification are bypassing traditional multi-level distribution markups in metro apartment buyer segments.
Industry Challenges
- Master upholsterer scarcity:Traditional hand-finishing skills for premium leather stitching and tufting are concentrated among aging craftsmen in Kolkata and Chennai, constraining quality-scalable production expansion.
- Multi-standard testing timelines:Simultaneous BIS safety certification, state fire code compliance, and corporate ESG documentation requirements extend product launch cycles by four to six months for mid-tier manufacturers.
- Legacy distributor credit exposure:Tier-two and tier-three furniture retailers operate on extended payment terms, forcing upholstery producers to absorb working capital strain or cede market access to cash-rich competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Upholstered Furniture Market |
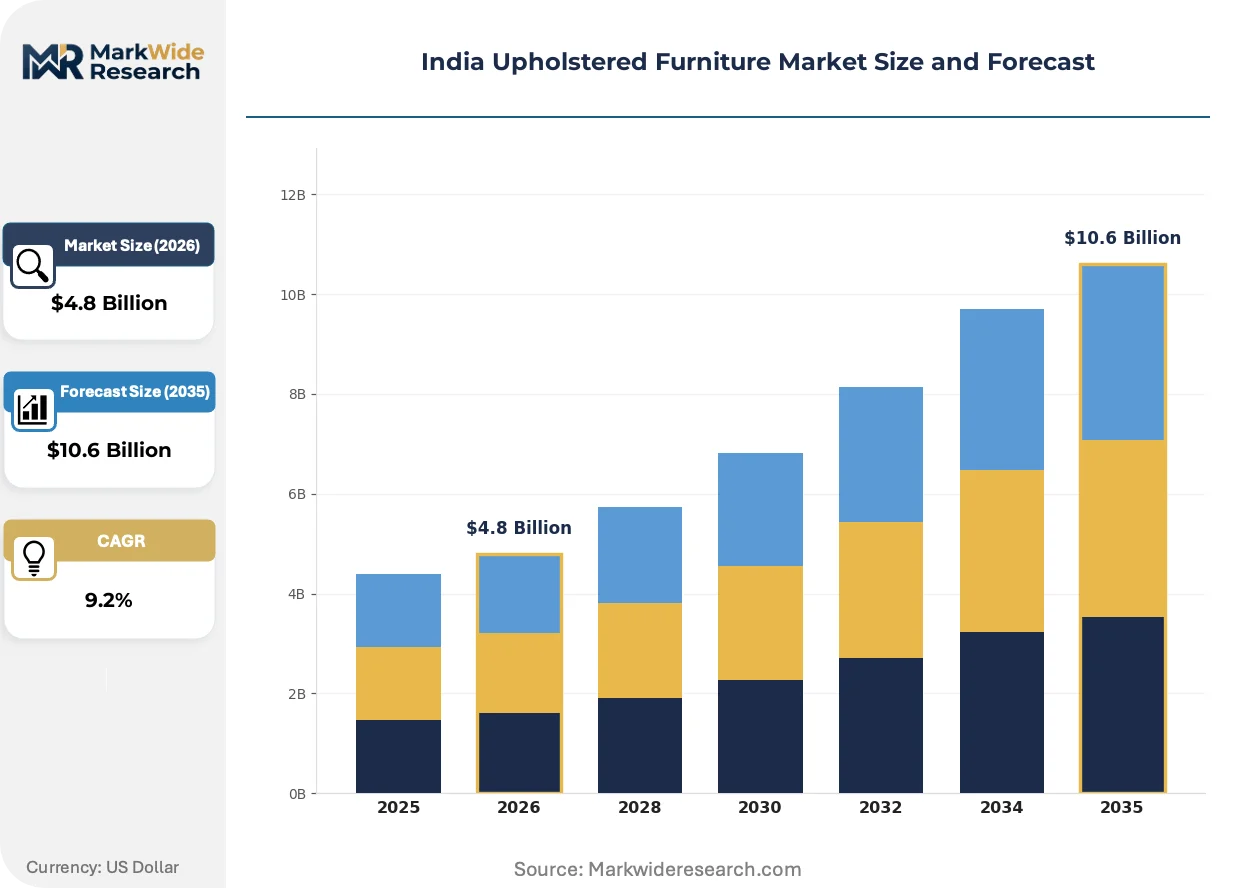
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Sectionals, Ottomans Material: Leather, Fabric, Velvet, Synthetic End User: Residential, Commercial, Hospitality, Corporate Distribution Channel: Online, Offline, Retail Showrooms, Direct Sales |
| Companies Covered | Featherlite, Tangent, Godrej & Boyce Manufacturing, Renaissance, BP Ergo, Durian, Nilkamal, Millennium Lifestyles, Haworth, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Upholstered Furniture Market Shifts & Advancements
Digital configuration tools and sustainable material substitution are compressing traditional upholstery procurement cycles while elevating compliance documentation requirements across Indian residential and commercial segments.
Modular foam-core seating systems with interchangeable cover mechanisms are electrifying specification practices among co-working space designers and hospitality procurement teams. Bangalore-based IT campus operators now demand rapid component replacement protocols to minimize downtime during reconfigurations. This technology is compressing replacement furniture spend into discrete cover and cushion refresh cycles rather than full-unit replacement.
BIS furniture safety standards revision cycles are tightening flammability testing protocols for polyurethane foam and synthetic fabric combinations. Manufacturers serving Mumbai and Delhi commercial fit-out markets must now maintain updated test certificates for every dye lot and foam density variant. Premium hospitality upholstery suppliers have responded by consolidating material platforms around pre-certified component families that reduce per-SKU compliance burden.
Apartment buyers in Pune and Hyderabad are prioritizing certified sustainable framing materials and low-VOC foam systems over pure cost minimization. Branded furniture retailers are responding with transparent supply chain documentation and extended warranty positioning that displaces unorganized local carpentry alternatives. This preference shift concentrates in metro residential segments where indoor air quality awareness intersects with disposable income thresholds for certified product premiums.
India Upholstered Furniture Market Segmentation
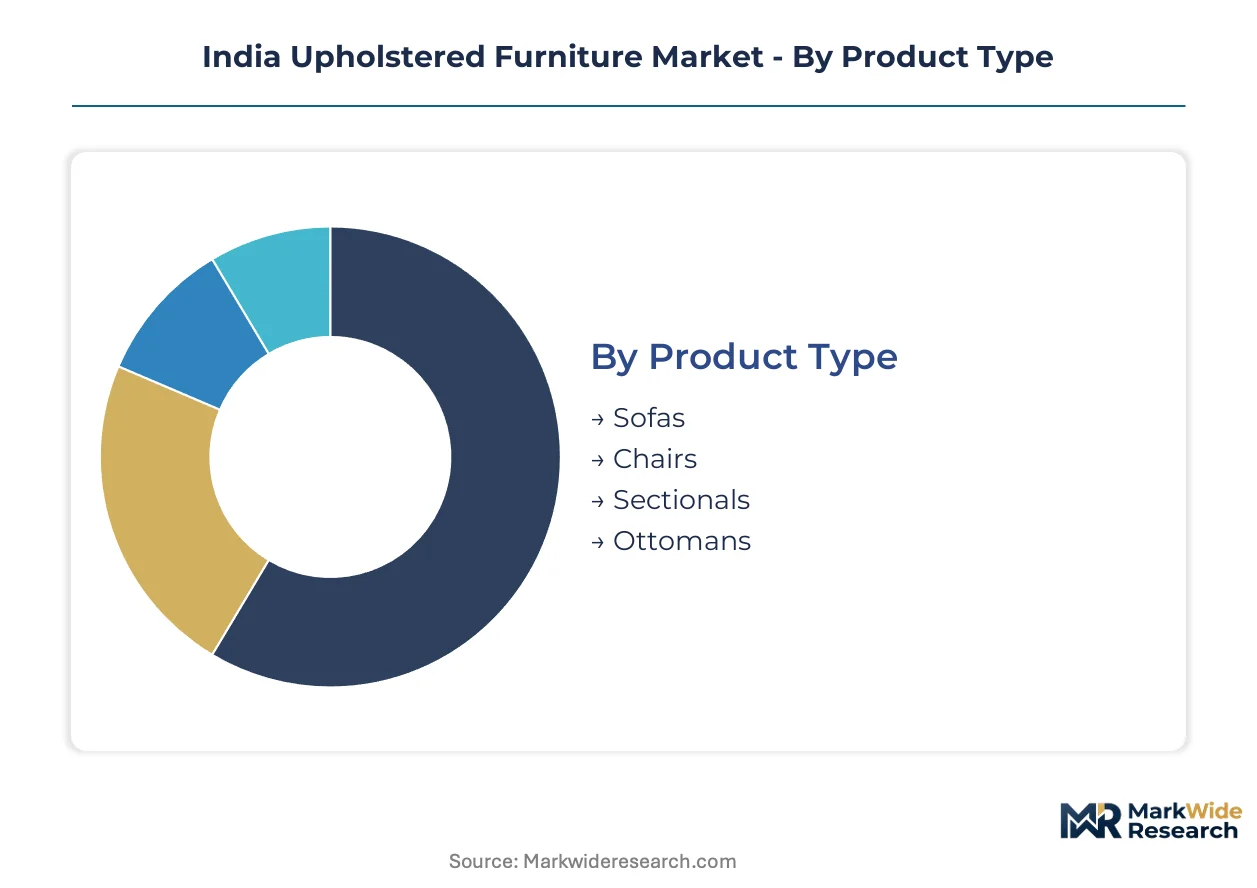
Segmentation in the India upholstered furniture market reveals distinct upgrade cycles across residential renovation waves, commercial fit-out rotations, and hospitality property refresh programs. Understanding these replacement rhythms helps manufacturers align inventory builds with predictable demand windows.
Product Type:
Replacement intensity varies sharply across product categories, with seating systems facing shorter functional lifespans than storage-integrated frames in Indian usage conditions.
- Sofas:Three-seat and L-configured upholstered frames dominate residential living room specifications across Mumbai and Bangalore apartment formats. Maharashtra and Karnataka buyers prioritize modular designs that accommodate elevator-constrained high-rise deliveries.
- Chairs:Ergonomic task seating with adjustable lumbar support and breathable mesh-fabric hybrids captures bulk procurement from Bangalore IT parks and Hyderabad BPO campuses. Co-working operators standardize on 4-5 year replacement cycles for high-use workstations.
- Sectionals:Corner-joining modular systems with reversible chaise extensions suit larger Pune and Chennai residential footprints where living-dining open plans predominate.
- Ottomans:Storage-integrated footrests and coffee-table hybrids serve secondary seating roles in compact Mumbai apartments where multi-function furniture maximizes floor efficiency.
Sofas sits at the top of the volume ranking, with Chairs climbing the fastest.
Material:
Cost tier positioning determines material selection patterns, with synthetic and fabric options anchoring mass-market penetration while leather and velvet concentrate margin extraction in premium specification channels.
- Leather:Full-grain and corrected-grain hides from Kanpur and Chennai tannery clusters supply corporate boardroom and five-star hospitality specifications. BIS flammability testing requirements and CEA electrical fire code compliance add certification overhead that filters out small-scale competitors.
- Fabric:Cotton-polyester blends and solution-dyed acrylics lead residential volume shipments through cost accessibility and design versatility. Polyester staple fiber input cost volatility squeezes margin predictability for producers serving price-sensitive segments.
- Velvet:Dense pile synthetics and cotton-silk blends command premium positioning in boutique hospitality properties across Jaipur and Kochi renovation cycles.
- Synthetic:PU-coated textiles and microfiber alternatives target entry-level apartment buyers in tier-two cities where durability concerns override tactile preferences.
Fabric commands absolute volume leadership, with Leather expanding most quickly in commercial specification channels.
End User:
Application context shapes performance requirements, with residential buyers prioritizing cost-duration tradeoffs while commercial and hospitality procurement teams enforce standardized durability protocols.
- Residential:Individual apartment buyers across Maharashtra, Gujarat, and Tamil Nadu drive absolute consumption through renovation-triggered replacement cycles. Organized retail expansion into tier-two cities compresses distribution timelines for branded upholstery chains.
- Commercial:Co-working space operators in Bangalore and Mumbai standardize bulk ergonomic seating purchases, creating predictable volume pipelines for modular upholstery suppliers with rapid reconfiguration capabilities.
- Hospitality:Mid-market hotel chains upgrading properties in Jaipur, Kochi, and Chandigarh drive specification-grade fabric upholstery demand for guest room renovations.
- Corporate:Large listed corporations under SEBI BRSR disclosure mandates generate preference pull for suppliers with certified recycled foam and FSC-tracked engineered wood framing.
Residential dominates absolute consumption, with Hospitality gaining share fastest through tier-two city property upgrade cycles.
Distribution Channel:
Customer type and geography together determine channel selection, with metro apartment buyers embracing digital configuration while tier-two procurement relies on physical verification.
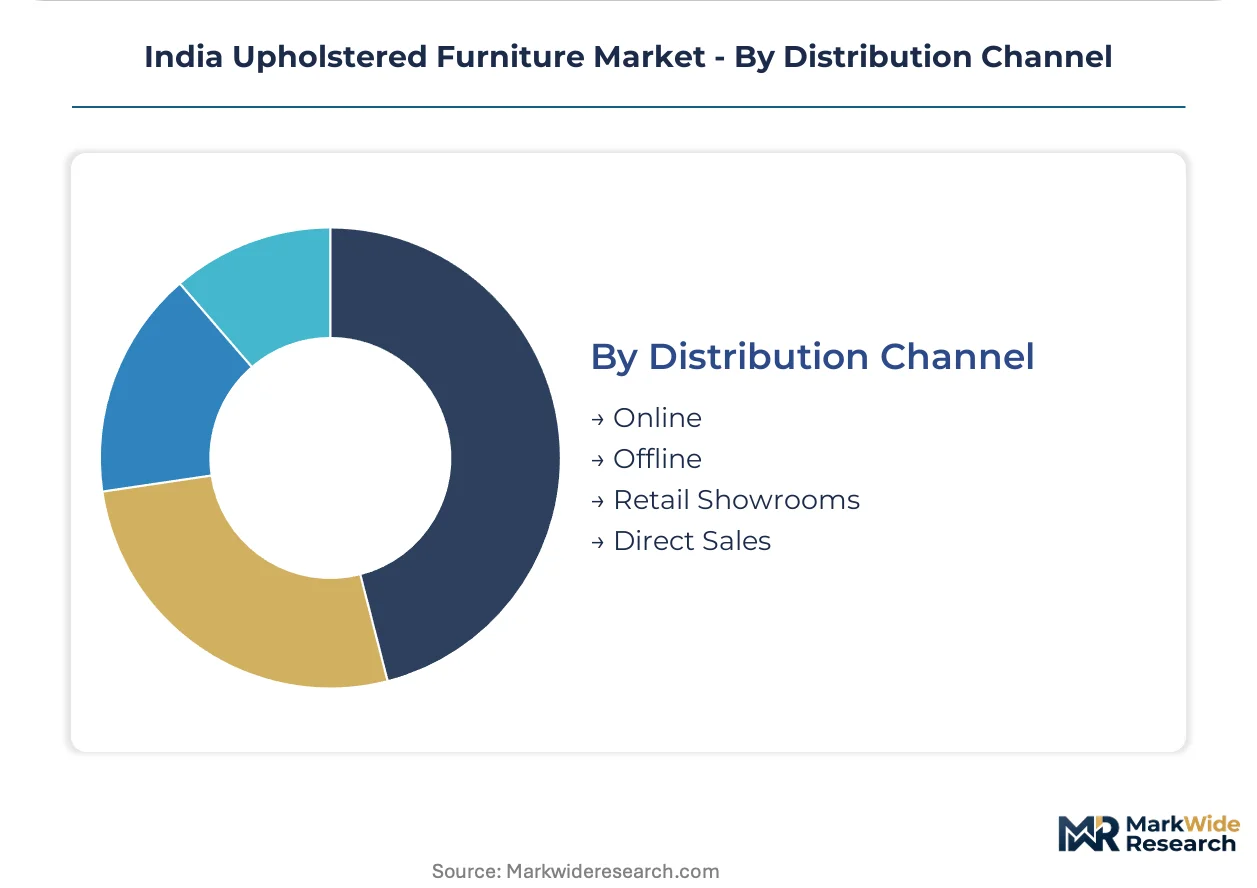
- Online:Direct-to-consumer platforms enabling custom fabric selection and modular dimension specification bypass traditional multi-level distribution markups in metro apartment buyer segments.
- Offline:Multi-brand furniture retailers in organized sector malls serve verification-dependent buyers across Gujarat and Tamil Nadu manufacturing cluster catchments.
- Retail Showrooms:Exclusive brand outlets in South India control last-mile customer access through tactile product demonstration and immediate delivery scheduling.
- Direct Sales:Project-based contracting for corporate fit-outs and hospitality renovations operates through manufacturer-direct relationships with procurement teams.
Offline maintains volume leadership, with Online expanding most quickly among metro residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting upholstery production toward states with streamlined BIS certification pathways and lower fire-code compliance costs, compressing manufacturing timelines for exporters serving Maharashtra and Karnataka demand centers.
Maharashtra
Mumbai's high-rise residential towers and Thane-Belapur industrial corridor generate concentrated demand for modular sofa systems designed around elevator-constrained deliveries. BIS furniture safety standards enforcement through the Mumbai municipal corporation accelerates certified manufacturer preference. Manufacturing clusters in Pune and Nashik supply component assemblies to organized retail chains expanding across western India.
Gujarat
Surat and Ahmedabad's textile processing infrastructure supports fabric upholstery producers seeking backward integration into polyester and acrylic supply chains. State-level industrial policy incentives under Gujarat's manufacturing promotion schemes attract component fabricators from Maharashtra. The Sanand-Vithalapur belt hosts engineered wood framing suppliers serving premium residential segments in Gandhinagar and Vadodara.
Tamil Nadu
Chennai's hospitality renovation cycles and Coimbatore's leather processing heritage create dual-channel demand for specification-grade upholstery. CEA electrical fire code inspections for commercial buildings in Chennai metro delay showroom openings, favoring manufacturers with pre-certified product platforms. The Ambur-Vaniyambadi tanning cluster supplies finished hides to premium seating lines targeting five-star hotel procurement.
Karnataka
Bangalore's IT park density and co-working space proliferation standardize bulk ergonomic seating procurement with four-to-five-year replacement cycles. SEBI BRSR disclosure mandates for listed corporations headquartered in the city generate preference pull for suppliers with FSC-tracked framing documentation. The Peenya industrial area hosts foam cushioning manufacturers serving modular upholstery assemblers in Whitefield and Electronic City.
Delhi-NCR
Gurgaon's corporate headquarters concentration and Noida's retail mall development drive specification demand for boardroom and hospitality seating. BIS flammability certification requirements for commercial buildings in Delhi municipal jurisdiction filter procurement toward organized sector manufacturers. Faridabad's metal framing fabricators supply structural components to upholstery assemblers serving the National Capital Region's fit-out contractors.
India Upholstered Furniture Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers regionalize component sourcing around Maharashtra, Gujarat, and Tamil Nadu clusters to compress distribution timelines. The vendor base stratifies across three tiers: integrated conglomerates with captive manufacturing, specialized ergonomic seating producers, and regional fabricators serving price-sensitive residential segments. Strategic archetypes include scale-driven platform suppliers, sustainability-certified premium specialists, and rapid-turnaround modular configurators. M&A activity and backward integration into foam and framing supply chains represent the dominant competitive moves.
Among India-based fabricators, Godrej & Boyce Manufacturing, Durian, and Featherlite exemplify distinct strategic positioning within this tiered structure. Godrej & Boyce Manufacturing anchors the integrated conglomerate archetype through multi-state manufacturing scale. Durian occupies a position within the specialized ergonomic seating tier, with its nomenclature suggesting focused expertise. Featherlite represents the retail-network-driven model, controlling last-mile customer access through showroom density. These three entities collectively illustrate how geographic coverage, product specialization, and channel strategy differentiate competitive positioning in India's upholstery market.
| Leading Market Players |
|---|
| Featherlite |
| Tangent |
| Godrej & Boyce Manufacturing |
| Renaissance |
| BP Ergo |
| Durian |
| Nilkamal |
| Millennium Lifestyles |
| Haworth |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators concentrated in Maharashtra and Gujarat exercise asymmetric pricing power over tier-two distributors, translating raw material cost spikes into selective pass-through while absorbing volatility in branded retail channels to preserve showroom relationships.
Pricing Analysis
Distributor margin layers in tier-two and tier-three cities absorb 18-25 percentage points before retail markup, compressing manufacturer netbacks for residential fabric upholstery while direct-to-OEM contracting for Bangalore IT campus fit-outs bypasses intermediaries entirely. Three-tier pricing structure across premium leather, certified fabric, and entry-level synthetic separates BIS-compliant commercial specification from unorganized residential alternatives. Cost compression in polyester staple fiber inputs is intensifying because crude-linked petrochemical volatility squeezes margin predictability for mass-market producers. Price-sensitive apartment buyers in tier-two cities drive volume at the economy tier, while SEBI BRSR-mandated corporate procurement shows minimal price elasticity for FSC-tracked framing documentation.
Supply Chain Analysis
Dual-sourcing requirements from Mumbai and Delhi-NCR hospitality procurement teams mandate qualification of both Kanpur and Chennai tannery clusters for premium leather lines, insulating against localized environmental compliance shutdowns. Geographic supply concentration centers on India for engineered wood framing, China for specialized foam chemical precursors, and Italy for high-performance upholstery textiles. Raw material dependencies rest on polyurethane foam systems, polyester staple fiber, and finished hides from named processing hubs. Single-source vulnerability in Kanpur tannery concentration exposes premium lines to hide supply interruptions. Distribution runs through organized retail chains in Maharashtra, Gujarat, and Tamil Nadu manufacturing cluster catchments, with direct-to-consumer platforms gaining share in metro residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India upholstered furniture market functions as a stable compounder, with residential renovation cycles and commercial fit-out rotations generating predictable replacement demand across Maharashtra, Karnataka, and Tamil Nadu demand centers.
For Market Incumbents: Acquire distressed tannery assets in the Ambur-Vaniyambadi belt to secure finished hide supply against environmental compliance shutdowns threatening premium leather lines. Consolidate component fabrication capacity around Pune and Nashik to compress logistics costs for western India distribution. Certification investment in pre-certified BIS component families reduces testing timeline exposure from multi-standard compliance requirements. For New Entrants and Emerging Players: Direct-to-consumer digital configuration platforms bypass traditional multi-level distribution markups in Mumbai and Bangalore apartment buyer segments. Kerala and Punjab residential penetration offers first-mover advantages through exclusive dealership networks in high-disposable-income states with underdeveloped organized retail. Modular foam-core seating systems with interchangeable cover mechanisms capture co-working space procurement with rapid reconfiguration protocols. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier fabricators with fragmented component sourcing and no captive tannery relationships, presenting consolidation targets for scale-driven platform builders. Long-term viability hinges on backward integration into foam and framing supply chains that insulate margin from petrochemical volatility. The signal to watch is municipal zoning reform implementation pace affecting showroom expansion economics and last-mile delivery density in tier-two cities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Assets | Captive hide supply from Ambur-Vaniyambadi clusters insulates premium leather lines against environmental compliance shutdowns. |
| Pre-Certified Component Platform Consolidation | Standardized BIS-compliant material families compress multi-standard testing timelines by four to six months. |
| Direct-to-Consumer Digital Configuration Launch | Custom fabric selection tools bypass distributor markups in Mumbai and Bangalore metro apartment segments. |
| Exclusive Dealership Network Expansion | First-mover positioning in Kerala and Punjab captures high-disposable-income residential demand with minimal organized competition. |
| Modular Foam-Core Seating System Development | Interchangeable cover mechanisms electrify co-working procurement in Bangalore with rapid reconfiguration protocols. |
Research Methodology
Multiple input streams — primary interviews with upholstery manufacturing executives and procurement managers at co-working operators, secondary validation through BIS certification databases and SEBI BRSR disclosure filings, and customs records for textile and leather trade flows — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included plant managers at Maharashtra and Tamil Nadu manufacturing clusters, category buyers at organized furniture retail chains, hospitality procurement directors overseeing Jaipur and Kochi property renovations, and foam chemical suppliers in the Peenya industrial area.
Historical volume trajectories were cross-referenced against panel input from manufacturing executives to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled encompass product type, material grade tier, end-use application, and distribution channel complexity. CAGRs were derived from replacement cycle analysis for residential renovation waves, commercial fit-out rotations, and hospitality property refresh programs, with specific incorporation of BIS flammability standard implementation timelines and CEA electrical fire code enforcement patterns affecting showroom certification delays.
The model assumes a particular technology adoption path; alternative pathways for digital configuration tools and sustainable material substitution would alter the outlook for traditional distribution markups and component sourcing economics. Forecasts reflect assumptions about regulatory enforcement consistency, petrochemical input cost trajectories, and municipal zoning reform implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
GCC Multifunctional Furniture Market
Furniture
United Kingdom Furniture Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Sanded Plywood Market
Furniture
North America Furniture Market
Furniture
Contract Furniture Market
Furniture
Bean Bag Chairs Market
Furniture
Spain Furniture Market
Furniture
Entryway Furniture Market
Furniture
Kids and Nursery Furniture Market
Furniture
Brazil Furniture Market
Furniture
Europe Home Furniture Market
Furniture
RTA Furniture Market
Furniture
Europe Luxury Furniture Market
Furniture
Italy Office Furniture Market
Furniture
Portering Chair Market