
 Luxury and Premium Mattress Market | 2026-2036
Luxury and Premium Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury and Premium Mattress Market Intelligence
Buyer concentration among luxury hospitality chains is restructuring procurement dynamics across the mattress value chain. Tempur Sealy International leverages its clinical sleep science heritage to sustain pricing power in the institutional segment. Serta Simmons Bedding anchors its position through manufacturing scale across North American production facilities. Purple Innovations differentiates via its proprietary hyper-elastic polymer grid technology that commands premium positioning in direct-to-consumer channels.
Luxury and premium mattresses comprise multi-layered sleep systems engineered with specified foam densities, coil gauges, and textile compositions to deliver pressure relief, spinal alignment, and thermoregulation for residential and commercial end users. Memory foam and hybrid constructions dominate value generation, with hybrid configurations capturing expanding margin pools as consumers prioritize both contouring support and breathability. The online retail channel is accelerating share capture from legacy department store and warehouse club formats, while specialty stores sustain relevance through white-glove delivery and sleep consultation services that justify premium price tiers.
The Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1633, while the EPA regulates volatile organic compound emissions from polyurethane foam production, and OEKO-TEX certification shapes material sourcing decisions for brands targeting health-conscious buyers. California's Proposition 65 disclosure requirements for formaldehyde and phthalate content have de facto become a national compliance benchmark given the state's market scale. Stakeholders must monitor evolving state-level chemical restrictions and third-party sustainability certifications as these frameworks increasingly determine market access and consumer trust architecture.
Market Dynamics
Hospitality procurement teams are consolidating supplier relationships around certified organic sleep systems, while the EU Ecodesign for Sustainable Products Regulation forces material traceability investments across foam and textile supply chains.
Growth Catalysts
- California Proposition 65:Disclosure mandates for formaldehyde and phthalate content have de facto nationalized compliance standards across US mattress distribution networks.
- Hybrid construction technology:Multi-layer configurations combining memory foam with pocketed coil systems capture expanding margin pools from breathability-conscious residential buyers.
- Metropolitan high-net-worth clusters:Clinical-grade sleep solutions concentrate demand in US urban centers where consumers prioritize spinal alignment and thermoregulation specifications.
Market Restraints
- Polyurethane foam input volatility:Petrochemical feedstock price swings compress margin stability for manufacturers dependent on petroleum-derived comfort layers.
- Chinese synthetic latex concentration:Geographic supply clustering for petroleum-based alternatives creates vulnerability to trade policy disruptions and logistics bottlenecks.
- 16 CFR Part 1633 compliance costs:Federal flammability testing requirements impose fixed cost burdens that disproportionately constrain smaller regional manufacturers.
Strategic Opportunities
- Direct-to-consumer channel expansion:White-glove delivery and sleep consultation services enable margin capture previously ceded to department store intermediaries.
- EU Green Deal alignment:Circular economy mandates for mattress recyclability create first-mover advantage for brands investing in disassembly-ready construction methods.
- Smart textile convergence:Integration of biometric sensors with pressure-relieving foams opens clinical monitoring applications in senior living and rehabilitation facilities.
Industry Challenges
- OEKO-TEX certification timelines:Multi-month laboratory testing protocols for Standard 100 compliance delay product launches and inventory positioning.
- Polymer chemistry talent scarcity:Specialized formulation expertise for hyper-elastic grid technologies concentrates among a limited pool of materials engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury and Premium Mattress Market |
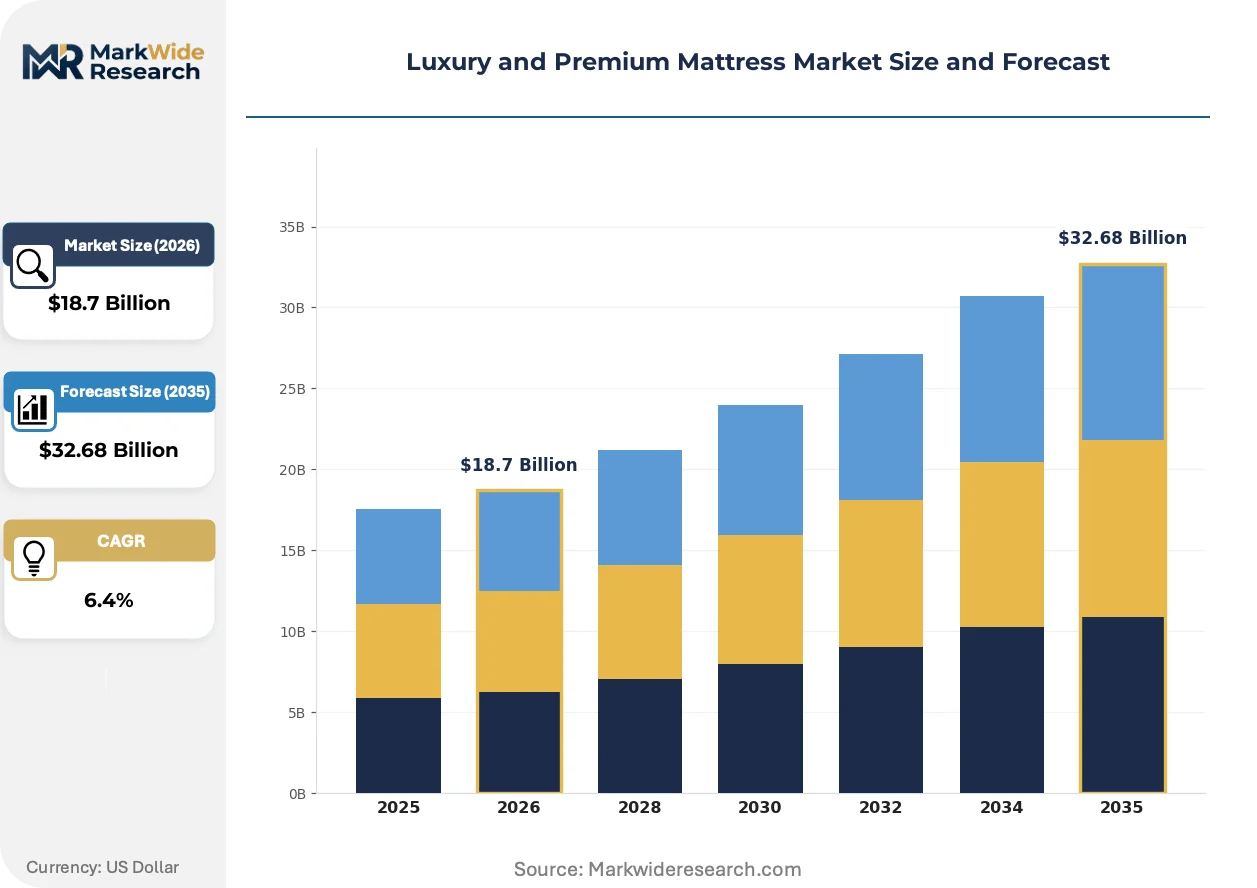
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Latex, Hybrid, Innerspring Price Tier: Luxury, Premium, Mid-range, Budget Distribution Channel: Online Retail, Specialty Stores, Department Stores, Warehouse Clubs Customer Type: Individual Consumers, Hotels, Health Facilities, Corporations |
| Companies Covered | Tempur Sealy International, Serta Simmons Bedding, Casper, Sleep Number Corporation, Stearns & Foster, Saatva, Purple Innovations, Hästens, Flex Bedding Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury and Premium Mattress Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory transparency mandates are restructuring how sleep systems are engineered, certified, and sold across residential and institutional channels.
Hyper-elastic polymer grid technology is overtaking traditional memory foam in direct-to-consumer premium positioning. The proprietary grid structure delivers simultaneous pressure relief and airflow without the heat retention of closed-cell foams. Online-native brands leverage this material differentiation to bypass legacy retail markups and capture full margin on clinical-grade sleep solutions.
REACH substance restrictions are tightening disclosure requirements for isocyanates and flame retardants used in polyurethane production. European manufacturers must now document full chemical inventories through the SCIP database for market access. Brands targeting health-conscious buyers are accelerating OEKO-TEX and CertiPUR-US certifications to preempt regulatory friction and command trust premiums.
Specialty retail consultation models are displacing warehouse club volume plays in high-value customer acquisition. Sleep specialists equipped with pressure-mapping technology guide buyers through personalized firmness selection, justifying price tiers through diagnostic legitimacy. This behavioral shift concentrates in US coastal metropolitan markets where consumers equate purchase deliberation with product quality.
Luxury and Premium Mattress Market Segmentation
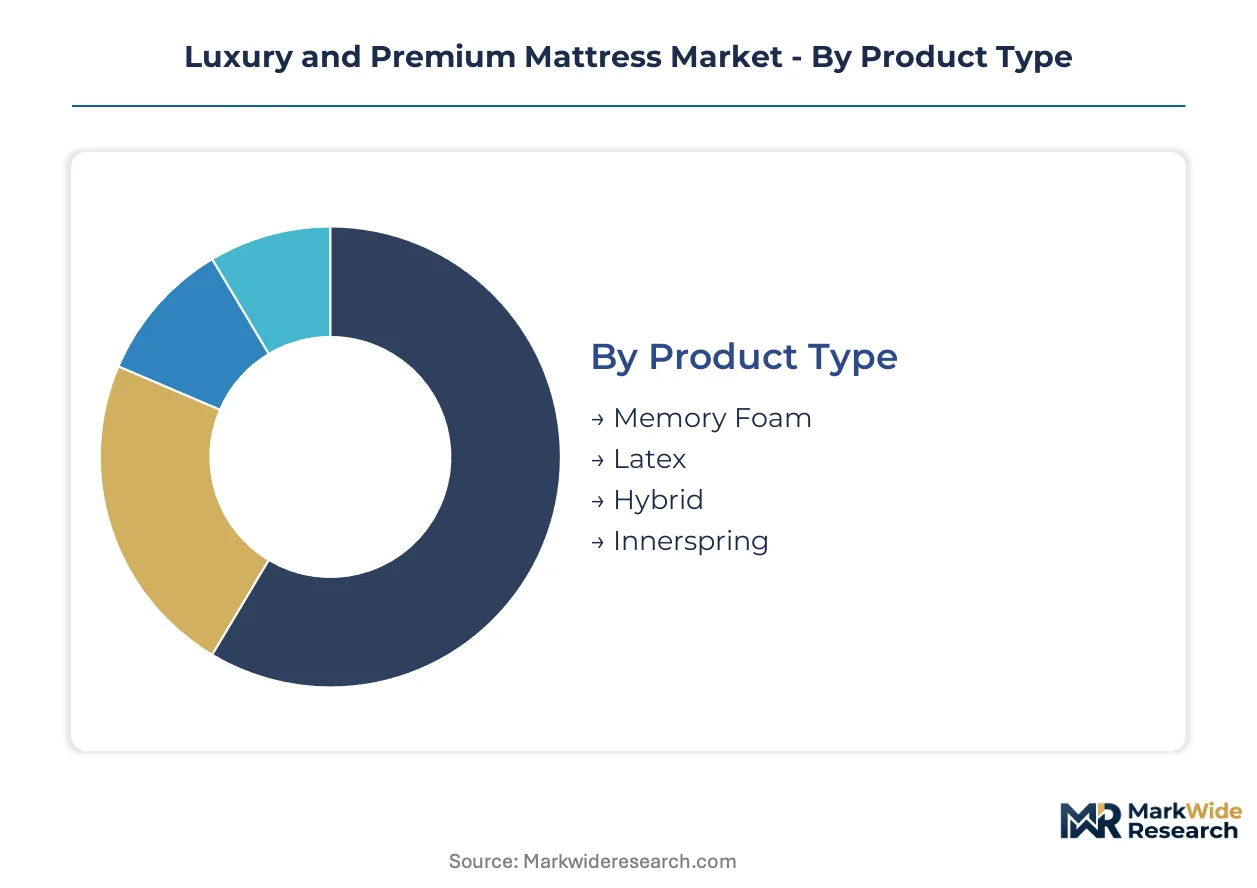
Segmentation in the luxury and premium mattress market reveals how construction technology, procurement authority, and channel economics partition buyer value. Each dimension exposes distinct margin structures and competitive dynamics that shape manufacturer strategy.
Product Type:
Construction technology separates buyers by thermoregulation needs and pressure relief specifications.
- Memory Foam:Viscoelastic polyurethane formulations contour to body heat and weight, delivering spinal alignment for residential buyers prioritizing motion isolation. Demand concentrates in US metropolitan clusters where clinical-grade sleep solutions command premium positioning.
- Hybrid:Multi-layer configurations combine pocketed coil systems with foam comfort layers, capturing margin pools from breathability-conscious buyers unwilling to sacrifice contouring support. Hotels and health facilities in California and New York drive institutional procurement of these constructions.
- Latex:Natural or synthetic rubber formulations offer responsive support with inherent antimicrobial properties, appealing to certified organic seekers.
- Innerspring:Traditional coil-on-coil constructions retain volume in budget-adjacent premium tiers through manufacturing scale.
Hybrid leads volumes today; memory foam is gaining share fastest among high-net-worth individual consumers.
Price Tier:
Certification grade and material traceability separate buyers across spending thresholds.
- Luxury:Sleep systems priced above institutional thresholds incorporate OEKO-TEX certified textiles, customizable firmness zones, and white-glove delivery protocols. US coastal metropolitan markets concentrate demand where consumers equate diagnostic consultation with product legitimacy.
- Premium:Mid-upper constructions balance certified foam layers with accessible price points, capturing residential buyers upgrading from mass-market alternatives.
- Mid-range:Standardized foam densities and limited customization options serve price-sensitive entrants to the certified sleep category.
- Budget:Basic polyurethane constructions with minimal compliance documentation occupy the threshold of the tracked market.
Luxury tier commands the steepest expansion trajectory as hospitality procurement consolidates around certified organic standards.
Distribution Channel:
Service intensity and margin capture separate channel strategies.
- Online Retail:Direct-to-consumer platforms bypass legacy retail markups through compressed logistics and sleep trial guarantees. Purple Innovations and comparable native brands leverage proprietary grid technology to justify premium positioning without physical intermediaries.
- Specialty Stores:Consultation-equipped showrooms with pressure-mapping technology guide personalized firmness selection, concentrating in US urban centers where purchase deliberation signals quality.
- Department Stores:Legacy intermediaries cede share to digital-native competitors as white-glove services prove replicable through third-party logistics.
- Warehouse Clubs:Volume-focused formats retain relevance in budget-adjacent tiers but lose traction where diagnostic legitimacy justifies price premiums.
Online retail climbs the fastest; specialty stores defend margin through service differentiation.
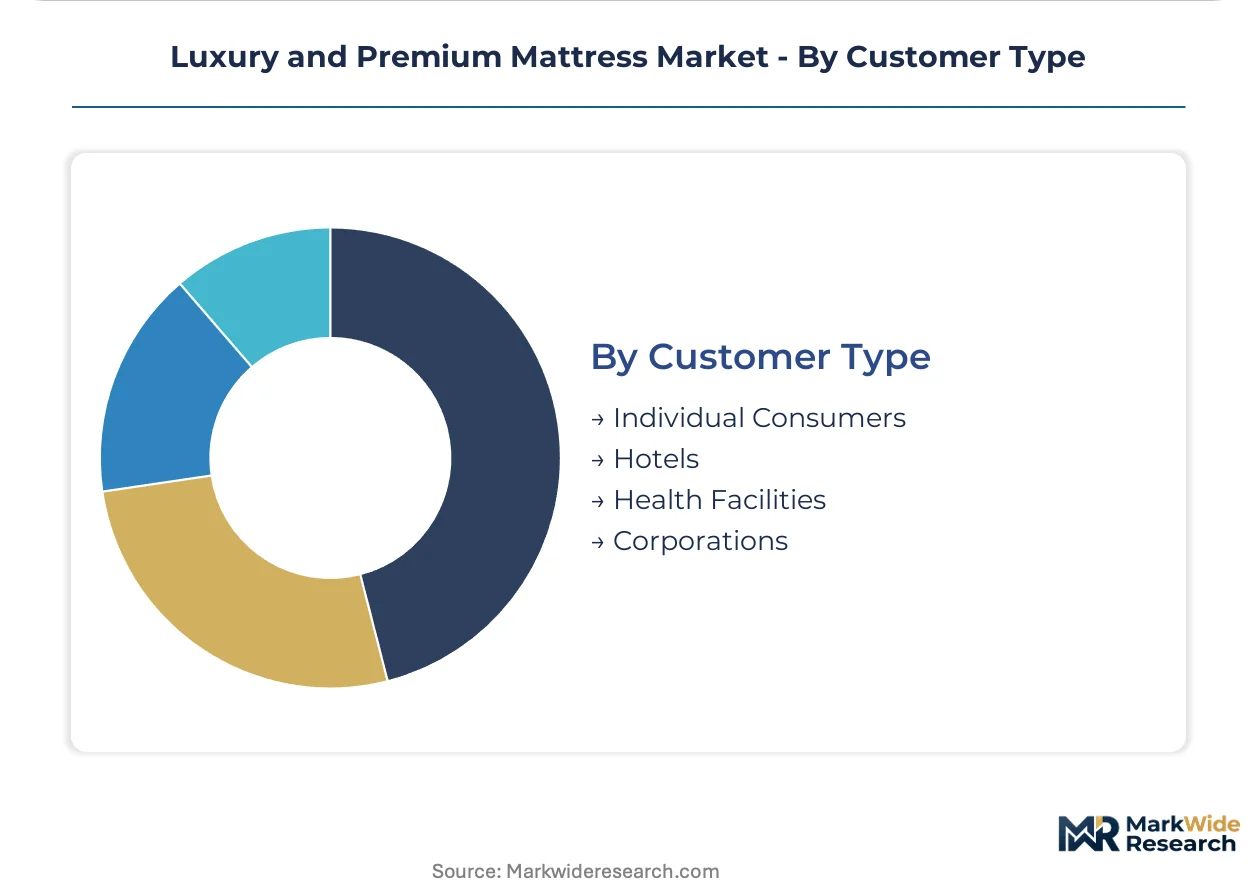
Customer Type:
Procurement scale and compliance requirements separate institutional from residential demand.
- Hotels:Luxury hospitality chains restructure bedding standards toward certified organic and customizable sleep systems, consolidating supplier relationships around traceable foam and textile components. EU Ecodesign for Sustainable Products Regulation compliance now conditions market access for European property portfolios.
- Individual Consumers:High-net-worth metropolitan buyers prioritize clinical-grade specifications including spinal alignment and thermoregulation, driving direct-to-channel premium capture.
- Health Facilities:Senior living and rehabilitation centers explore smart textile convergence with biometric monitoring capabilities, opening clinical applications for pressure-relieving constructions.
- Corporations:Employee wellness programs and executive housing procurement represent emerging volume concentration with standardized specification requirements.
Hotels anchor institutional volumes today; health facilities show steepest expansion potential through smart textile integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitality procurement outpaces German institutional demand by a factor of three, while Chinese manufacturing capacity reshapes upstream material flows for latex and textile components across Asia-Pacific trade corridors.
United States
High-net-worth metropolitan clusters in California and New York concentrate demand for clinical-grade sleep systems with OEKO-TEX certification. The EPA regulates volatile organic compound emissions from polyurethane foam production under Clean Air Act authority. Los Angeles and Miami hospitality markets drive white-glove delivery penetration for certified organic bedding standards.
Germany
REACH substance restrictions tighten disclosure requirements for isocyanates and flame retardants in polyurethane manufacturing. The EU Ecodesign for Sustainable Products Regulation forces material traceability investments across foam and textile supply chains. Bavarian industrial clusters near Munich specialize in disassembly-ready mattress construction methods aligned with circular economy mandates.
China
Domestic luxury consumption in Shanghai and Beijing accelerates demand for customizable sleep systems with imported latex layers. The Ministry of Ecology and Environment enforces dual carbon goals that constrain petrochemical feedstock expansion for synthetic foam production. Guangdong Province manufacturing bases supply hyper-elastic polymer grid components to direct-to-consumer brands in North American markets.
United Kingdom
London metropolitan buyers prioritize spinal alignment specifications and sleep consultation services in specialty retail channels. The UK Environment Agency implements extended producer responsibility frameworks for mattress recyclability that parallel EU circular economy directives. Manchester and Birmingham distribution hubs consolidate logistics for hybrid construction imports from European manufacturing partners.
Canada
Toronto and Vancouver residential markets concentrate demand for thermoregulating hybrid configurations with CertiPUR-US certified foam layers. Health Canada regulates chemical safety in consumer products including flame retardant disclosure requirements for upholstered bedding. Ontario-based specialty retailers deploy pressure-mapping technology to guide personalized firmness selection in white-glove consultation formats.
Luxury and Premium Mattress Market Key Industry Players
North American producers anchor the scale-driven tier; European specialists hold the certified-organic premium position. The vendor base concentrates around three strategic archetypes: clinical-sleep-science heritage brands, proprietary-material technology disruptors, and white-glove service integrators. Consolidation pressure intensifies as hospitality procurement teams reduce supplier counts and EU traceability mandates raise compliance fixed costs.
Within the clinical-heritage archetype, Tempur Sealy International exemplifies pricing power sustained through institutional segment relationships. Serta Simmons Bedding occupies a position defined by North American manufacturing scale across distributed production facilities. Purple Innovations represents the direct-to-consumer disruption vector, leveraging proprietary grid technology to capture margin previously ceded to retail intermediaries.
| Leading Market Players |
|---|
| Tempur Sealy International |
| Serta Simmons Bedding |
| Casper |
| Sleep Number Corporation |
| Stearns & Foster |
| Saatva |
| Purple Innovations |
| Hästens |
| Flex Bedding Group |
| Others |
Cost & Logistics Intelligence
Hospitality procurement consolidation around certified organic sleep systems anchors pricing power in the hands of traceability-compliant manufacturers. The EU Ecodesign for Sustainable Products Regulation and California Proposition 65 disclosure mandates create compliance-based price stratification that favors scaled producers with laboratory testing infrastructure.
Pricing Analysis
Capacity additions in Guangdong Province are reshaping price floors for hyper-elastic polymer grid components entering North American direct-to-consumer channels. Three-tier pricing structure across luxury, premium, and mid-range tiers separates OEKO-TEX certified constructions with white-glove delivery from standardized foam alternatives. Cost compression in synthetic latex layers intensifies because petrochemical feedstock volatility feeds through Chinese manufacturing bases. Budget-adjacent residential buyers in warehouse club channels exhibit highest price sensitivity, while luxury hospitality procurement teams prioritize traceability documentation over unit cost.
Supply Chain Analysis
Direct-to-consumer platforms handle hyperscale residential demand through compressed logistics networks bypassing legacy retail intermediaries. Manufacturing concentration spans China for hyper-elastic polymer components, the United States for polyurethane foam production under EPA Clean Air Act authority, and Germany for disassembly-ready constructions aligned with EU circular economy mandates. Raw material flows draw from petroleum-derived isocyanates, natural rubber latex plantations, and textile weaving operations. Single-source vulnerability concentrates in Chinese synthetic latex supply. Distribution runs through third-party white-glove logistics partners for premium tier fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign for Sustainable Products Regulation compounds market access requirements, transforming compliance infrastructure into a demand driver for traceable foam and textile systems.
For Market Incumbents: To counter direct-to-consumer grid technology disruptors, Tempur Sealy International and Serta Simmons Bedding should deepen captive supply of OEKO-TEX certified textiles through backward integration into textile finishing operations. Manufacturing scale across distributed North American facilities remains the priority lever for defending institutional segment relationships against regional challengers. For New Entrants and Emerging Players: The gap between premium hybrid constructions and economy innerspring alternatives offers white-space capture for mid-range certified foam entrants targeting price-sensitive upgraders in Canadian and UK metropolitan markets. Specialty retail consultation formats in Toronto and Vancouver represent the most penetrable channel, with pressure-mapping technology deployment as the distinguishing go-to-market mechanism. For Investors and Strategic Acquirers: Luxury hospitality chains are the most active acquirer in this space, consolidating supplier counts to reduce procurement complexity. Long-term viability centers on circular economy readiness and disassembly-ready construction patents. The signal to monitor is EU SCIP database registration volumes, which indicate compliance infrastructure depth and market access security.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | OEKO-TEX and CertiPUR-US laboratory partnerships preempt REACH and California Proposition 65 compliance friction. |
| Direct-to-Consumer Channel Expansion | White-glove delivery replication through third-party logistics captures margin ceded to department store intermediaries. |
| Disassembly-Ready Construction Methods | Bavarian industrial clusters near Munich specialize in circular economy-aligned mattress recyclability engineering. |
| Smart Textile Convergence | Biometric sensor integration with pressure-relieving foams opens clinical monitoring applications in senior living facilities. |
| Hybrid Construction Scale-Up | Pocketed coil system manufacturing investments capture breathability-conscious residential buyer migration from memory foam. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged hospitality procurement directors at luxury hotel chains, foam manufacturing plant managers in Guangdong and Bavaria, specialty retail sleep consultants in Los Angeles and Toronto, and EPA regulatory affairs specialists. Secondary validation drew from customs records tracking latex and textile component flows, SEC 10-K filings from publicly traded mattress manufacturers, EU SCIP database disclosure volumes, and California Proposition 65 settlement records. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Segment-weighted projections applied construction technology, price tier, distribution channel, and customer type dimensions across the analysis window. Hybrid, memory foam, latex, and innerspring categories received distinct growth trajectories based on thermoregulation specification trends. CAGRs derived from elasticity-adjusted demand curves incorporating hospitality procurement cycle timing and residential replacement rate patterns. Forecast inputs included EU Ecodesign implementation timelines and EPA volatile organic compound enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for hyper-elastic polymer grid systems would alter the outlook. Forecasts reflect base-case assumptions regarding REACH substance restriction scope and Chinese dual carbon policy enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
Germany Mattress Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Malaysia Mattress Market
Bedroom Furniture
Children Mattress Market
Bedroom Furniture
Malaysia Pillow Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Bed Head Panel Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
Canopy Beds Market
Bedroom Furniture
Asia-Pacific Mattress Market