
 Hardwood Flooring Market | 2026-2036
Hardwood Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Hardwood Flooring Market Intelligence
Subscription-based floor care and refinishing programs is realigning how manufacturers monetize installed hardwood surfaces. Mohawk Industries leverages captive distribution networks to sustain margin control across North American retail channels. Kährs Holding AB specializes in engineered hardwood with proprietary multi-layer construction that reduces raw timber consumption per square meter. Shaw Industries Group anchors its position through backward integration into timberlands and sawmill operations.
Hardwood flooring consists of timber planks milled from deciduous species such as oak, maple, and walnut, typically ranging from three-quarters to five-sixteenths of an inch in thickness, serving as a structural or decorative walking surface in interior environments. Engineered hardwood dominates volume production due to dimensional stability across humidity zones, while solid hardwood commands premium positioning in heritage restoration and luxury residential specifications. Prefinished hardwood captures share in commercial fast-track construction where on-site finishing introduces schedule risk. Click lock installation systems expand the addressable market by enabling floating applications over concrete subfloors without adhesive.
The EPA regulates formaldehyde emissions in composite wood products under TSCA Title VI, directly affecting engineered hardwood core layer specifications. ECHA enforces REACH restrictions on wood treatment chemicals entering European supply chains, while CARB ATCM standards in California extend de facto national benchmarks for North American manufacturers. Stakeholders must monitor evolving LCA disclosure requirements under the EU Green Deal and emerging state-level embodied carbon legislation that will reshape material sourcing decisions.
Market Dynamics
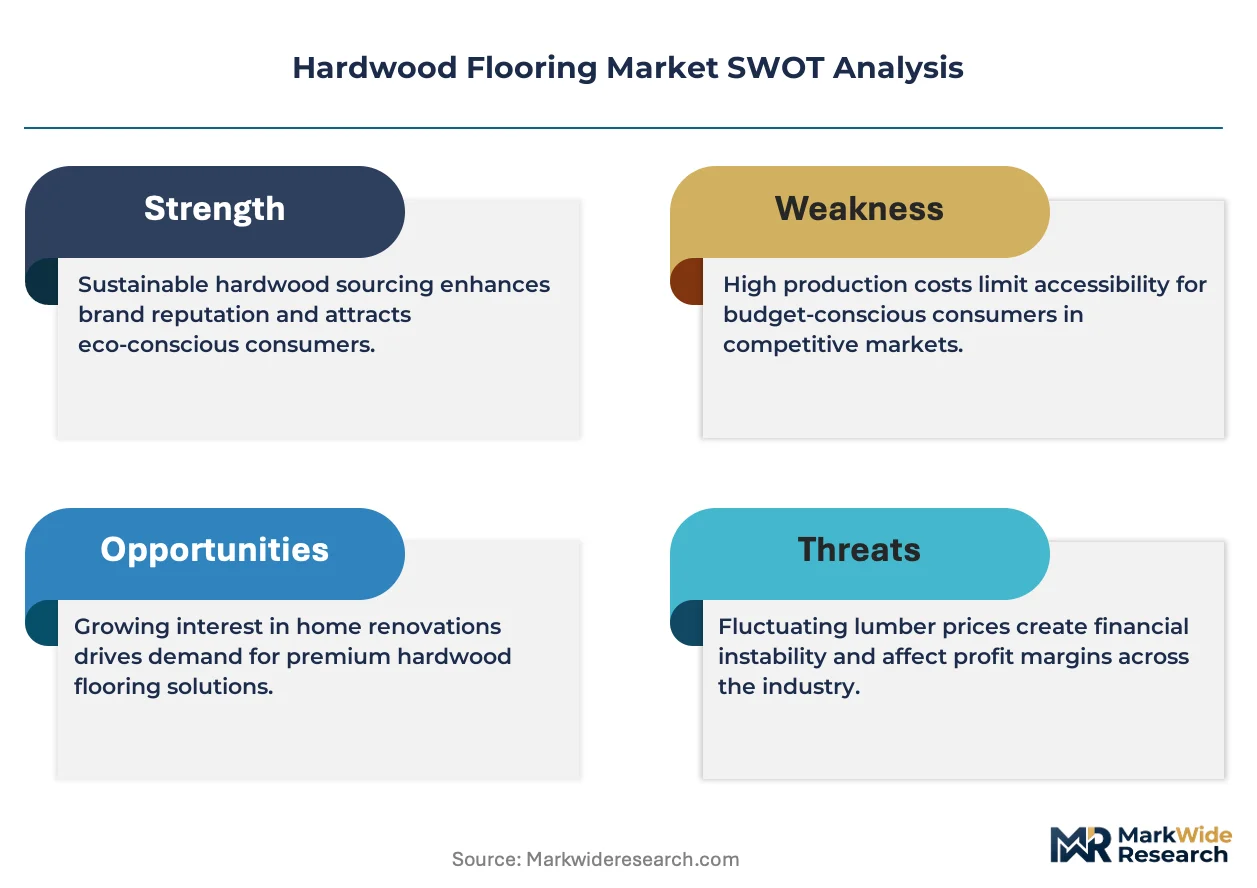
LEED certification requirements and embodied carbon disclosure mandates are compressing material specifications toward lower-emission engineered products, forcing manufacturers to reconfigure core layer chemistry and timber sourcing protocols.
Growth Catalysts
- Residential renovation cycles:Aging housing stock across the United States requires floor replacement at 15-25 year intervals, sustaining replacement demand independent of new construction volatility.
- CARB ATCM formaldehyde standards:California's emission benchmarks have de facto nationalized low-formaldehyde core specifications, accelerating compliant engineered hardwood adoption across North American distribution channels.
- Click-lock floating installation:Mechanical fastening systems eliminate adhesive curing time and subfloor preparation costs, expanding contractor capacity and reducing skilled labor requirements.
Market Restraints
- White oak supply concentration:Appalachian and Ozark timberlands supply 70% of North American hardwood feedstock, creating geographic vulnerability to climate-driven harvest disruptions.
- REACH chemical restrictions:ECHA's evolving wood treatment substance bans limit preservative options for European exports, forcing reformulation of surface finishes and anti-microbial coatings.
- Luxury vinyl tile substitution:Waterproof rigid core LVT captures moisture-prone residential segments with lower installed cost and reduced maintenance requirements.
Strategic Opportunities
- German Passivhaus construction:Ultra-low-energy building standards specify thermally massive floor assemblies, creating specification pull for thick engineered hardwood over lightweight alternatives.
- EU Green Deal LCA disclosure:Mandatory environmental product declarations reward manufacturers with verified carbon-negative supply chains, differentiating certified producers in public procurement.
- Direct-to-installer digital platforms:Bypassing traditional distributor markups through contractor-facing e-commerce captures margin and builds loyalty among independent flooring specialists.
Industry Challenges
- Moisture acclimation expertise:Site-specific humidity management requires trained installers, and contractor skill gaps produce callbacks and warranty claims that erode brand equity.
- Multi-jurisdiction certification timelines:Simultaneous EPA TSCA, CARB, and ECHA compliance testing extends product launch cycles and strains R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardwood Flooring Market |
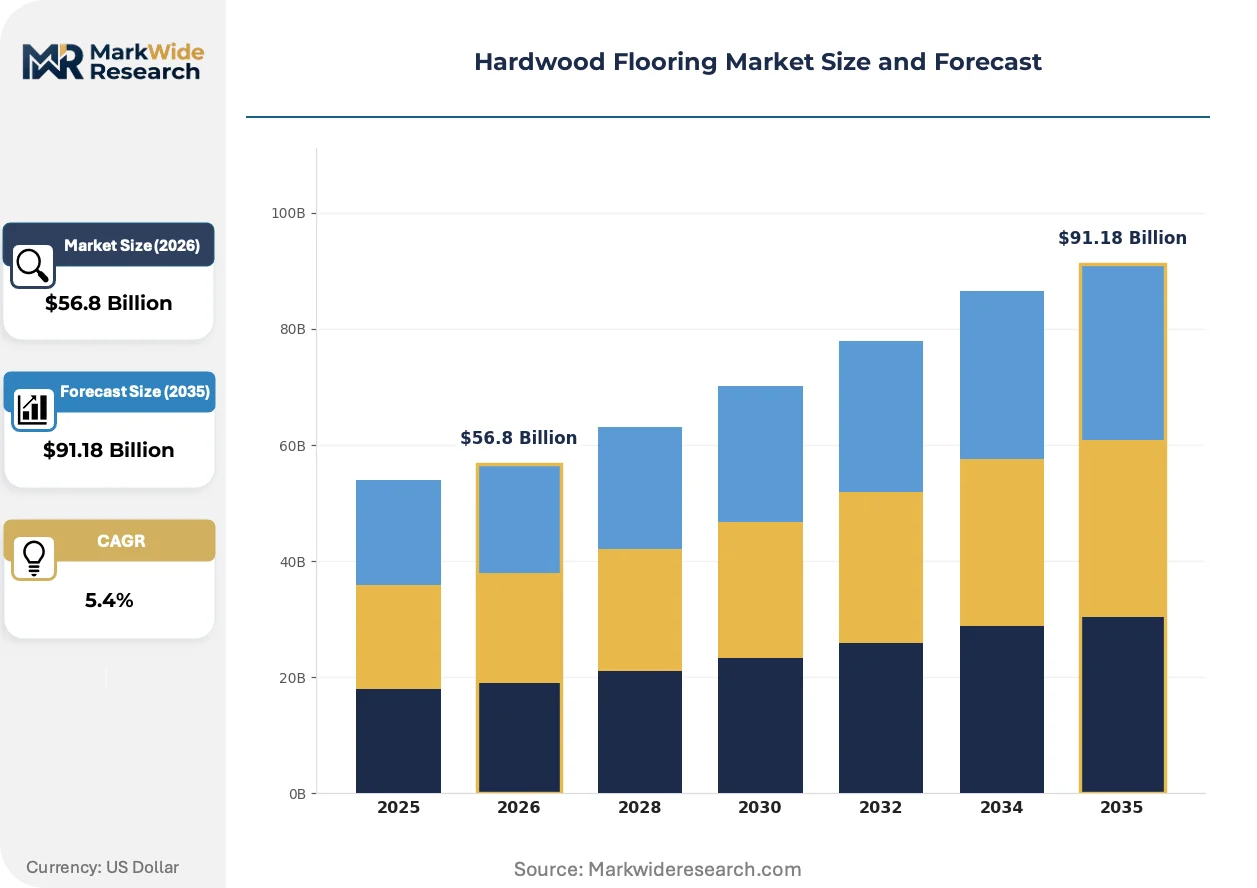
| Market Size in 2026 | $56.8 Billion |
| Market Size in 2035 | $91.18 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engineered Hardwood, Solid Hardwood, Prefinished Hardwood, Unfinished Hardwood Installation Type: Nail Down, Glue Down, Floating, Click Lock End User: Residential, Commercial, Industrial, Institutional Finish Type: Satin, Gloss, Matte, Hand-Scraped |
| Companies Covered | Mohawk Industries, Inc., Shaw Industries Group, Inc., Armstrong Flooring, Inc., Mannington Mills, Inc., Tarkett S.A., AHF Products, Beaulieu International Group, Somerset Hardwood Flooring, Inc., Kährs Holding AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardwood Flooring Market Strategic Shifts & Innovations
Digital moisture sensing and predictive maintenance platforms are transforming hardwood from a passive material into a monitored building system, altering warranty structures and service revenue models.
Cross-laminated timber core technology is unifying structural and finish-layer functions in a single factory-fabricated panel. Multi-family developers in Germany and Austria specify these hybrid floor-wall systems for accelerated enclosure schedules. The technology is compressing traditional trade boundaries between structural framing and interior finish contractors.
EPA's TSCA Title VI enforcement expansion is tightening third-party certification requirements for composite wood cores. Manufacturers must maintain chain-of-custody documentation from veneer mill to finished plank. Small and mid-sized producers face disproportionate compliance costs, accelerating consolidation among engineered hardwood fabricators.
Facility managers in commercial office and hospitality verticals now specify performance-based floor care contracts rather than capital purchase with separate maintenance. Service providers install sensor-equipped surfaces and charge per square foot per year for guaranteed appearance retention. This model concentrates in United States Class A office buildings where tenant turnover demands rapid refresh cycles.
Hardwood Flooring Market Segmentation
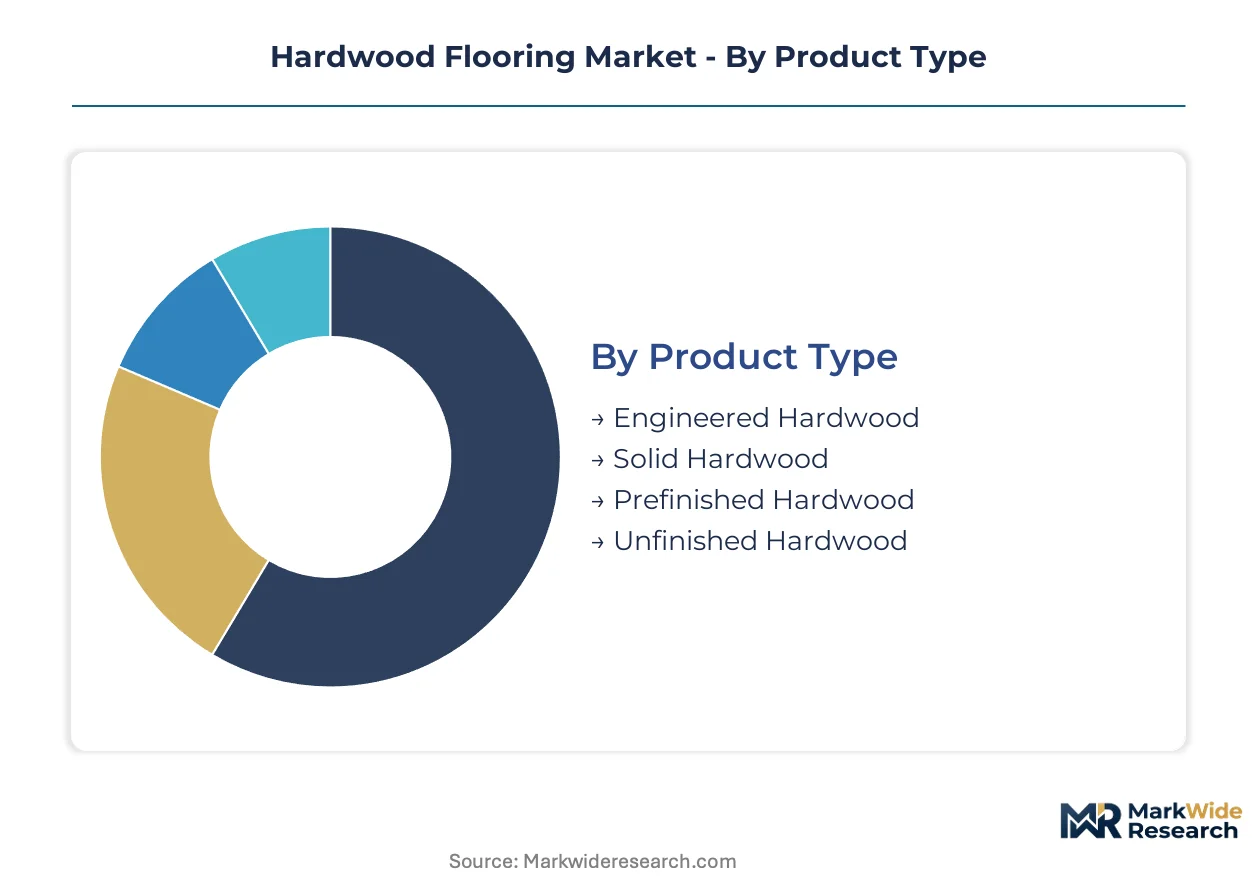
Hardwood flooring segmentation reveals how manufacturing capacity, installation labor economics, and specification requirements fragment across distinct product architectures and application contexts. Understanding these divisions exposes where margin pools concentrate and which technology transitions reshape competitive positioning.
Product Type:
Supply concentration tilts heavily toward multi-layer construction methods that reduce raw timber intensity per square meter while maintaining specification-grade performance.
- Engineered Hardwood:Cross-laminated timber cores bonded with decorative hardwood veneers provide dimensional stability across humidity zones. Demand concentrates in United States multi-family residential and German Passivhaus construction where thermal mass requirements favor thick assemblies over lightweight alternatives. CARB ATCM compliance mandates accelerate specification of low-formaldehyde core formulations.
- Solid Hardwood:Single-species planks milled to three-quarters inch thickness dominate heritage restoration and luxury residential specifications in affluent United States suburbs. Appalachian white oak supply concentration creates vulnerability to climate-driven harvest disruptions, compressing availability for wide-plank premium grades.
- Prefinished Hardwood:Factory-applied UV-cured coatings eliminate on-site finishing schedules for commercial fast-track construction in United States Class A office buildings.
- Unfinished Hardwood:Site-sanded and stained planks retain specification in custom residential projects where color matching to existing millwork takes priority.
Engineered hardwood absorbs the bulk of installed capacity; prefinished hardwood is expanding most quickly.
Installation Type:
Cost tier differentiation separates premium adhesive systems from mechanical fastening methods that reduce skilled labor requirements and accelerate project schedules.
- Click Lock:Precision-milled tongue-and-groove profiles enable floating installations over concrete subfloors without adhesive curing delays. Demand concentrates in United States residential renovation where contractor capacity constraints favor reduced subfloor preparation. The technology expands addressable market to moisture-prone basements previously excluded from hardwood specification.
- Nail Down:Pneumatic fastening to wood subfloors remains standard for solid hardwood in new United States single-family construction where plywood or OSB substrates predominate. The method demands trained installers and produces callbacks when moisture acclimation protocols fail.
- Glue Down:Full-spread adhesive application dominates commercial specifications in Germany and Austria where sound transmission ratings require bonded assemblies.
- Floating:Interlocking systems without adhesive or mechanical fastening serve rental property renovations in United States coastal markets where tenant turnover demands rapid refresh cycles.
Nail down retains the largest installed base; click lock is gaining share fastest.
End User:
Application requirements fragment procurement patterns across sectors with diverging performance specifications, maintenance protocols, and replacement cycles.
- Residential:Aging United States housing stock sustains replacement demand independent of new construction volatility, with floor replacement intervals of 15-25 years driving recurring revenue. Specification splits between engineered products for basements and moisture-prone areas versus solid hardwood for above-grade living spaces.
- Commercial:Facility managers in United States hospitality and office verticals increasingly specify performance-based floor care contracts with sensor-equipped surfaces and per-square-foot annual charges.
- Institutional:Schools and healthcare facilities in Germany specify engineered hardwood for durability under heavy foot traffic with mandatory LCA disclosure compliance.
- Industrial:Light manufacturing and showroom applications in China prioritize cost-optimized engineered products with basic wear layer specifications.
Residential absorbs the bulk of volume; commercial is climbing the fastest.
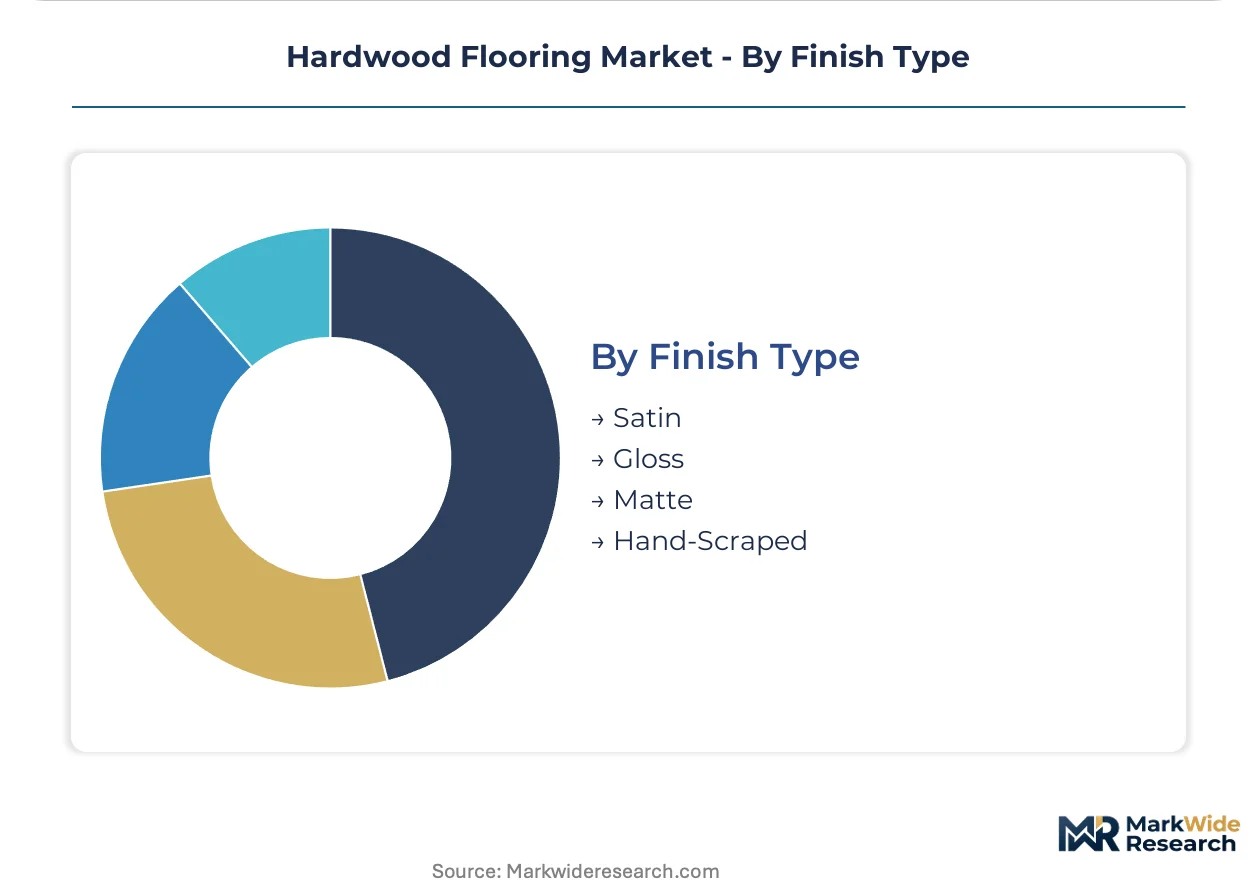
Finish Type:
Margin structure stratifies across aesthetic differentiation levels, with hand-worked surfaces commanding substantial premiums over standardized sheen grades.
- Hand-Scraped:Artisan-distressed textures replicate vintage patina for luxury residential specifications in United States heritage restoration markets. The finish conceals wear patterns and extends aesthetic service life in high-traffic areas.
- Matte:Low-sheen factory finishes align with contemporary interior design preferences in German and Austrian residential markets. The specification reduces visible scratching and defers maintenance intervals.
- Satin:Medium-luster finishes balance reflectivity with scratch concealment across broad United States residential segments.
- Gloss:High-sheen surfaces retain niche specification in formal commercial environments where appearance retention is monitored under performance contracts.
Satin finishes absorb the bulk of production volume; matte is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calhoun, Georgia anchors North American hardwood flooring manufacturing through dense clustering of engineered wood production facilities and captive distribution infrastructure.
United States
Residential renovation cycles in aging suburban housing stock sustain replacement demand at 15-25 year intervals, independent of new construction volatility. EPA's TSCA Title VI enforcement tightens third-party certification requirements for composite wood cores, forcing chain-of-custody documentation from veneer mill to finished plank. Appalachian timberlands in Kentucky and Tennessee supply 70% of white oak feedstock, creating geographic concentration risk amid climate-driven harvest disruptions.
Germany
Passivhaus construction standards specify thermally massive floor assemblies, pulling specification toward thick engineered hardwood over lightweight alternatives. ECHA's REACH restrictions on wood treatment chemicals limit preservative options, forcing reformulation of surface finishes and anti-microbial coatings for export compliance. Industrial clusters in Bavaria and Baden-Württemberg host precision milling operations serving Central European distribution networks.
China
Multi-family residential development in coastal provinces absorbs cost-optimized engineered products with basic wear layer specifications for rapid installation schedules. The country's national environmental regulator enforces dual carbon goals that compress embodied carbon thresholds in building materials procurement. Manufacturing concentration in the Yangtze River Delta supplies both domestic consumption and export markets across Southeast Asia.
Sweden
Heritage restoration markets in Stockholm and Gothenburg sustain demand for premium-grade solid hardwood with artisan surface treatments. EU Green Deal LCA disclosure mandates reward manufacturers with verified carbon-negative supply chains, differentiating certified producers in public procurement competitions. Kährs Holding AB's engineered hardwood production exemplifies proprietary multi-layer construction reducing raw timber intensity per square meter.
Canada
Moisture-prone basement renovations in Toronto and Vancouver expand addressable market for click-lock floating installations over concrete subfloors without adhesive curing delays. Health Canada and PMRA regulate wood preservative chemistry entering residential supply chains, parallel to California's CARB ATCM standards. Quebec's hardwood sawmill corridor feeds cross-border engineered flooring fabrication serving United States distribution channels.
Hardwood Flooring Market Key Industry Players
Capital-heavy producers compete with asset-light designers across tiered market positions. Consolidation pressures concentrate among engineered hardwood fabricators facing disproportionate EPA compliance costs. Three archetypes dominate: vertically integrated timberland owners, specialty engineered product innovators, and diversified flooring conglomerates with captive retail distribution. Competitive moves center on backward integration into sawmill operations and direct-to-installer digital platform development.
Among United States-based diversified manufacturers, Mohawk Industries, Inc. and Shaw Industries Group, Inc. occupy positions exemplifying scale-driven consolidation with captive distribution networks. Swedish producer Kährs Holding AB represents the specialty engineered tier through proprietary multi-layer construction expertise. These three anchors illustrate how geographic origin and corporate structure correlate with strategic archetype positioning across North American and European demand centers.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Shaw Industries Group, Inc. |
| Armstrong Flooring, Inc. |
| Mannington Mills, Inc. |
| Tarkett S.A. |
| AHF Products |
| Beaulieu International Group |
| Somerset Hardwood Flooring, Inc. |
| Kährs Holding AB |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between CARB ATCM-compliant engineered hardwood and untreated commodity alternatives manifests in both margin capture and supply chain configuration. Premium tiers command pricing power through captive timberland sourcing and third-party chain-of-custody documentation, while commodity producers absorb cost volatility from spot-market veneer procurement.
Pricing Analysis
Cost-down pressure on standard-grade engineered hardwood accelerates because Appalachian white oak supply concentration limits feedstock alternatives. Three-tier pricing structure across heritage restoration, certified residential, and economy multi-family levels stratifies by veneer thickness and core emission ratings. Brand premiums attach to verified low-formaldehyde formulations under EPA TSCA Title VI. Price sensitivity concentrates among Chinese coastal developers optimizing for installation speed over wear-layer durability.
Supply Chain Analysis
Third-party certification gating under EPA TSCA Title VI and ECHA REACH restrictions fragments supplier qualification tiers. Manufacturing concentrates in the United States, Germany, and China. Raw material flows draw from Appalachian timberlands, Bavarian precision milling operations, and Yangtze River Delta resin formulation. Single-source vulnerability sits with white oak harvest concentration in Kentucky and Tennessee. Distribution runs through captive retail networks and direct-to-installer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardwood flooring operates as a cost-of-compliance story where EPA TSCA Title VI certification creates a barrier-to-entry moat for incumbent producers with established chain-of-custody systems.
For Market Incumbents: Deepen backward integration into sawmill operations to secure white oak feedstock against climate-driven harvest disruptions. Expand captive distribution infrastructure to defend margin control against direct-to-installer platform entrants. Luxury vinyl tile substitution in moisture-prone residential segments demands accelerated engineered hardwood innovation in click-lock waterproof cores. For New Entrants and Emerging Players: Digital moisture sensing platforms offer a technology-first wedge into United States Class A office building performance-based floor care contracts. Target commercial facility managers specifying sensor-equipped surfaces with per-square-foot annual service charges. White-space availability concentrates in German Passivhaus construction where thick engineered hardwood thermal mass specifications remain underpenetrated by Asian producers. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty engineered product innovators with proprietary multi-layer construction and verified carbon-negative supply chains. Long-term viability favors producers with demonstrated EPD compliance under EU Green Deal mandates. Watch EPA enforcement expansion against small and mid-sized fabricators as consolidation inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timberlands | Secures white oak feedstock against Appalachian climate disruption. |
| Direct-to-Installer Digital Platform | Bypasses distributor markups to capture margin among independent flooring specialists. |
| Low-Formaldehyde Core Certification | Unlocks specification in CARB ATCM-compliant North American distribution channels. |
| Cross-Laminated Timber Core Development | Unifies structural and finish-layer functions for German Passivhaus multi-family developers. |
| Sensor-Equipped Surface Installation | Enables performance-based floor care contracts in United States commercial office verticals. |
Research Approach
Document review covered EPA TSCA Title VI certification databases, ECHA REACH substance restriction filings, and CARB ATCM compliance registries, complemented by interviews with engineered hardwood plant managers, timberland procurement leads, flooring distributor channel partners, and commercial facility specification managers. Secondary validation drew from customs trade data, SEC 10-K filings of diversified flooring conglomerates, and EU Green Deal LCA disclosure frameworks. Bottom-up production capacity modeling triangulated against top-down renovation cycle demand estimation.
Segment-level value outputs across the projection horizon reflect product type, installation method, end-use sector, and finish specification dimensions. CAGRs derive from regression analysis against residential renovation cycle intervals, new construction permit flows, and regulatory compliance adoption curves. Industry-specific inputs include white oak harvest volume projections and Passivhaus construction penetration rates in German-speaking markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated LVT substitution or Appalachian harvest disruption scenarios. Model outputs reflect documented assumptions regarding regulatory enforcement intensity and contractor skill availability. A model refresh is warranted upon material change in EPA third-party certification timelines or EU embodied carbon disclosure mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market