
 Bed Formers Market | 2026-2036
Bed Formers Market Size, Share, and Industry Trends Forecast 2026-2036
Bed Formers Market Analytics
Skilled tractor-operator shortages across major agricultural belts is redrawing competitive dynamics for bed forming equipment. Deere & Company leverages its precision agriculture ecosystem to bundle bed formers with guidance and telemetry packages. AGCO Corporation anchors its position through Fendt and Massey Ferguson distribution networks in European arable farming regions. Grimme specializes in root-crop bed forming systems where ridge geometry directly impacts harvester efficiency.
Bed formers are soil-engaging implements that shape tilled ground into raised ridges or flat-topped beds to optimize drainage, root development, and mechanized planting access; hydraulic folding frames now commonly span 6–12 meters for transport compliance while maintaining structural rigidity at field depth. Conventional technology still dominates unit shipments among smallholder cooperatives, yet precision and automated configurations capture disproportionate margin pools through RTK-guided depth control and variable-rate shaping. Hydraulic product types lead commercial agriculture deployments where field resistance demands real-time force modulation, while pneumatic systems gain traction in greenhouse and horticulture settings requiring lighter soil disturbance profiles.
Federal emissions compliance through EPA Tier 4 Final and upcoming Stage V alignment through EU machinery directives are elevating powertrain costs and favoring equipment with longer depreciation cycles. OSHA agricultural machinery guarding standards and ISO 4254 safety specifications shape frame design, hydraulic hose routing, and operator platform configuration for North American and European export eligibility. Stakeholders must weigh retrofit compatibility against full-platform redesigns as electrification architectures mature for mid-horsepower tractor classes.
Market Dynamics
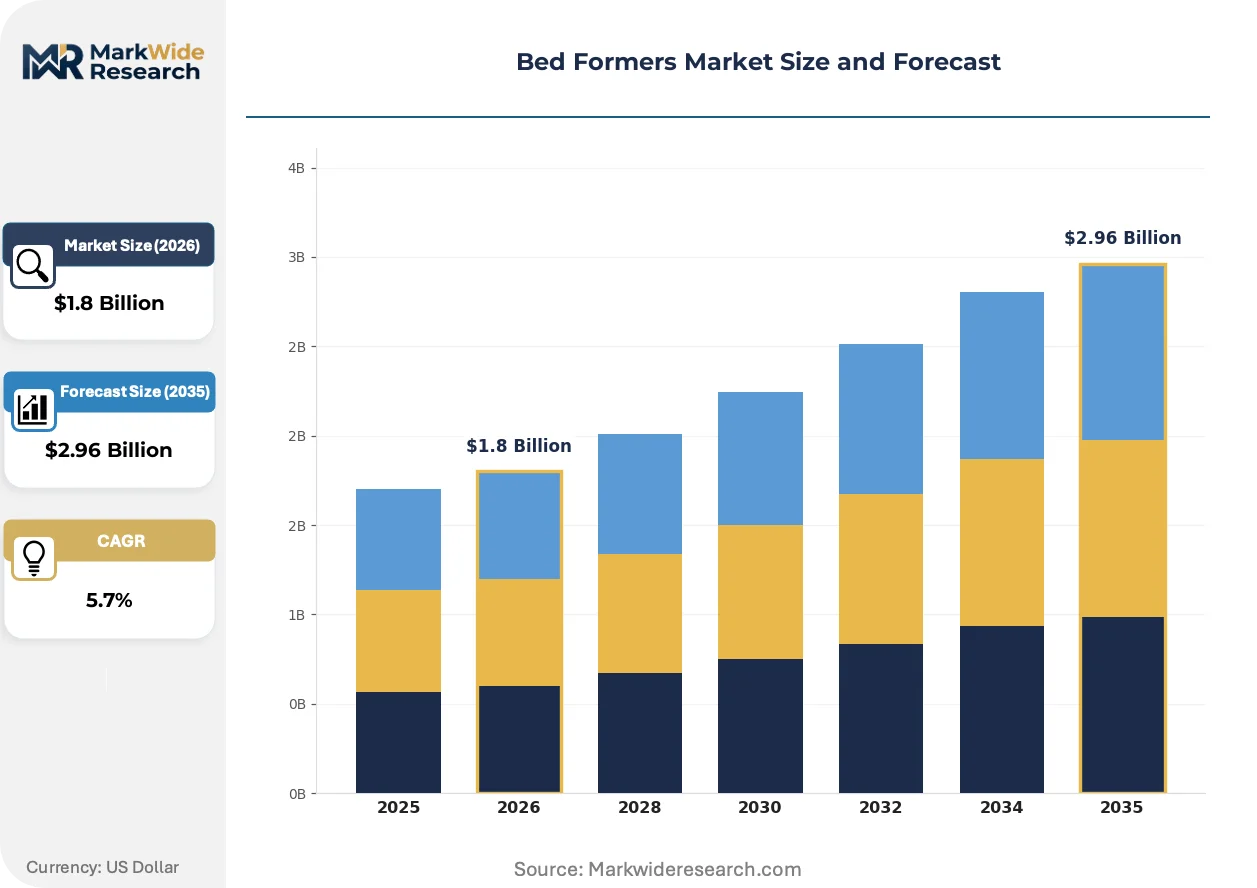
EPA Tier 4 Final emissions mandates and EU Stage V alignment are compressing powertrain supplier margins while extending equipment replacement cycles across mechanized tillage operations.
Growth Catalysts
- Precision Agriculture Mandates:California's SGMA groundwater regulations compel specialty vegetable producers to adopt RTK-guided bed forming for water-efficient ridge geometry. Contract farming obligations in the Central Valley accelerate mechanized capacity expansion.
- Labor Scarcity Economics:Tractor-operator shortages across US agricultural belts push cooperatives toward automated hydraulic folding systems spanning 6–12 meters. Reduced field passes cut per-acre labor hours.
- Root-Crop Harvester Integration:Ridge geometry standardization for Grimme and comparable harvester fleets creates pull-through demand for precision bed forming in potato and sugar beet operations.
Market Restraints
- Powertrain Cost Inflation:EPA Tier 4 Final after-treatment systems and DEF infrastructure add 15–25% to diesel engine costs, squeezing mid-horsepower tractor attachment economics.
- Steel Input Volatility:Frame and disc blade fabrication depends on hot-rolled coil pricing subject to Section 232 tariff fluctuations and energy cost pass-through from European mills.
- Hydraulic Component Concentration:Bosch Rexroth and Parker Hannifin dominate high-pressure valve and cylinder supply, creating single-source vulnerability for real-time force modulation systems.
Strategic Opportunities
- Electrification Retrofit Kits:Mid-horsepower tractor electrification architectures from John Deere and AGCO create white space for compatible electric bed former attachments with reduced hydraulic complexity.
- Greenhouse Horticulture Expansion:Pneumatic bed forming systems address lighter soil disturbance requirements in Netherlands and Spain protected agriculture, displacing conventional tillage in high-value substrate operations.
- OSHA Guarding Compliance Services:ISO 4254 safety specification alignment for frame design and hydraulic hose routing opens recurring revenue streams for certification consulting and retrofit engineering.
Industry Challenges
- Mechatronics Skill Gap:RTK-guided depth control and variable-rate shaping require technicians fluent in both hydraulic systems and GNSS calibration, a competency scarce in rural equipment dealer networks.
- Legacy Fleet Integration:CAN bus telemetry from new bed formers must interface with 10–15 year-old tractor electronics lacking standardized protocol support, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bed Formers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Hydraulic, Pneumatic, Electrical End User: Agriculture, Horticulture, Greenhouses, Landscaping Technology: Conventional, Precision, Automated, Semi-Automated Application: Soil Preparation, Seed Bed Creation, Mulching, Irrigation |
| Companies Covered | Grimme, Dewulf, McHugh, Bourgault, Sola, Orthman, CHECCHI & MAGLI, Deere & Company, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bed Formers Market Evolving Landscape
Active depth sensing and autonomous contour following are compressing the skill gap between veteran operators and entry-level hires across mechanized tillage fleets.
Electro-hydraulic load sensing is supplanting purely mechanical depth control in commercial agriculture deployments. Large-scale vegetable operations in California's Central Valley and Florida's Everglades Agricultural Area are retrofitting existing frames with real-time force modulation at 15–20% annual adoption velocity. This technology is compressing fuel consumption per acre by 8–12% while extending disc blade life through optimized engagement angles.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transition in cab climate systems, indirectly affecting operator retention economics for extended field hours. Manufacturers must redesign HVAC integration points on folding frame platforms to accommodate lower-GWP alternatives. German and French arable farming regions show earliest compliance-driven equipment refresh activity.
Cooperative procurement consortia are consolidating equipment specification authority away from individual farm managers. Midwestern US grain and specialty crop operations now delegate bed former selection to centralized technical committees standardizing on telemetry-compatible platforms. This concentration shifts negotiation leverage toward OEMs with integrated precision agriculture ecosystems.
Bed Formers Market Segmentation
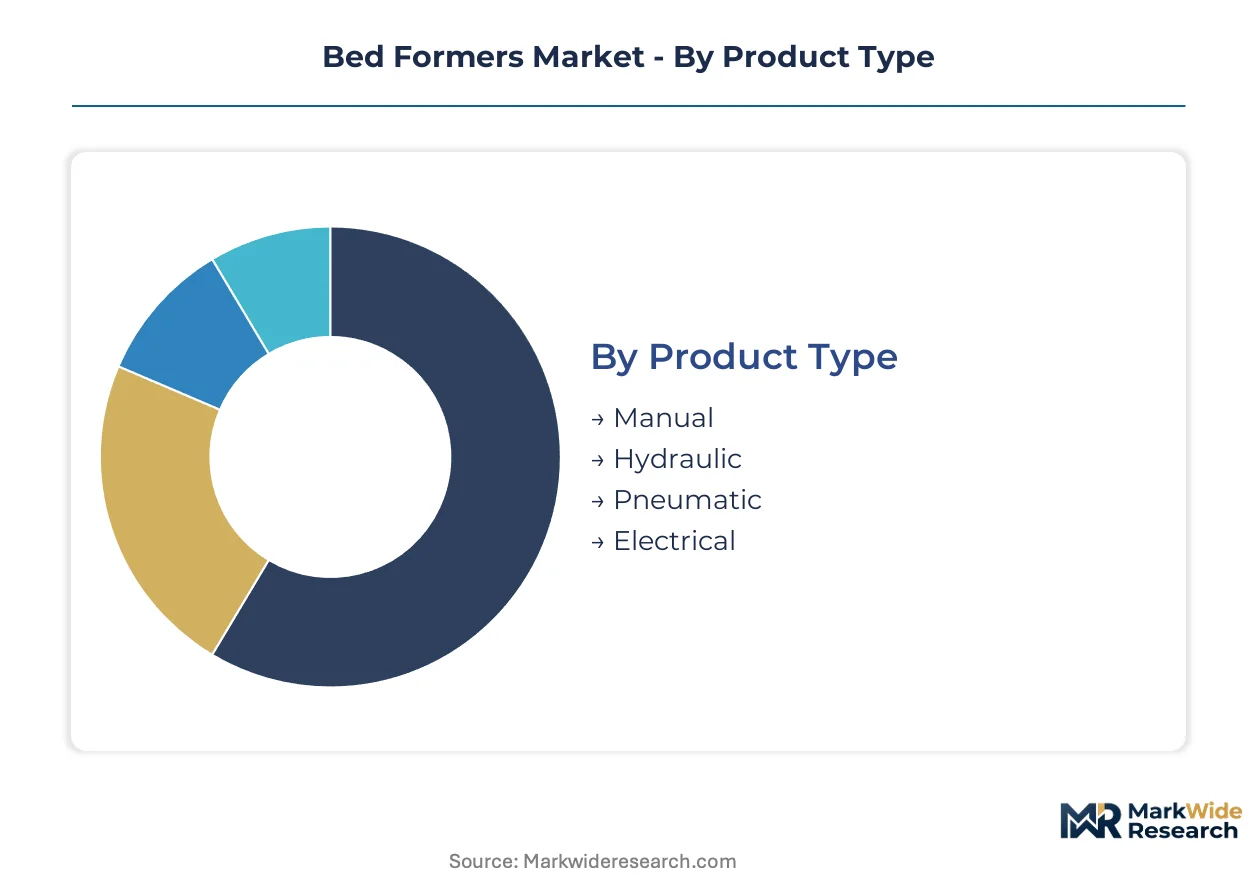
Bed former segmentation reveals distinct equipment specifications across power systems, operational environments, and control architectures. Channel strategies diverge sharply between commodity tillage dealers serving broadacre grain operations and specialized horticulture distributors focused on protected agriculture systems.
Product Type:
Hydraulic units dominate commercial dealer networks in California's Central Valley and Florida's Everglades Agricultural Area, while pneumatic systems flow through greenhouse supply channels in the Netherlands and Spain.
- Hydraulic:Real-time force modulation handles field resistance in commercial vegetable operations. Demand concentrates in California specialty crop zones where SGMA groundwater regulations mandate precision ridge geometry for water efficiency. EPA Tier 4 Final compliance costs extend replacement cycles, favoring durable hydraulic architectures.
- Pneumatic:Lighter soil disturbance profiles suit greenhouse substrate operations and high-value horticulture settings. Protected agriculture expansion in the Netherlands and Spain drives specification through specialized equipment distributors rather than traditional farm machinery dealers.
- Manual:Entry-level cooperatives and smallholder operations in developing agricultural belts.
- Electrical:Emerging compatibility with mid-horsepower tractor electrification architectures from major OEMs.
By volume, Hydraulic leads. By growth pace, Pneumatic is ahead in protected agriculture clusters.
End User:
Margin concentration follows water regulation intensity and labor scarcity economics, with premium equipment penetration highest where contract farming obligations enforce mechanization standards.
- Agriculture:Broadacre grain and specialty vegetable producers across mechanized belts. Ridge geometry standardization for potato and sugar beet harvester fleets creates pull-through demand in German and French arable regions. OSHA agricultural machinery guarding standards and ISO 4254 safety specifications shape frame design for North American eligibility.
- Horticulture:High-value protected cropping operations requiring precise bed geometry for substrate management. Labor scarcity across US agricultural belts accelerates automated hydraulic folding adoption in this segment.
- Greenhouses:Netherlands and Spain lead specification authority through cooperative procurement consortia.
- Landscaping:Municipal and commercial turf preparation with lighter duty cycle requirements.
Agriculture captures the largest equipment value per unit. Horticulture shows the steepest expansion trajectory in telemetry-compatible platform adoption.
Technology:
Capital deployment patterns separate depreciation-heavy conventional fleets from precision agriculture ecosystem investments where RTK guidance bundles justify premium positioning.
- Precision:RTK-guided depth control and variable-rate shaping capture disproportionate margin pools. California Central Valley vegetable producers adopt at accelerated velocity to meet contract farming water efficiency obligations. CAN bus telemetry integration challenges legacy tractor fleet compatibility.
- Automated:Active depth sensing and autonomous contour following compress operator skill requirements. Electro-hydraulic load sensing retrofits proceed at measured pace in large-scale vegetable operations.
- Conventional:Dominates unit shipments among smallholder cooperatives with extended replacement cycles.
- Semi-Automated:Intermediate specification for operations transitioning from mechanical to sensor-based control.
Precision technology commands the highest attachment premiums. Automated configurations are gaining share fastest in labor-constrained operations.
Application:
Specification requirements vary by downstream crop system, with irrigation-integrated bed forming commanding engineering complexity premiums in drought-stressed production regions.
- Soil Preparation:Primary tillage integration with disc harrow and field cultivator sequences. Steel input volatility from hot-rolled coil pricing affects frame and disc blade fabrication economics.
- Seed Bed Creation:Ridge geometry precision directly impacts planter performance and harvester efficiency in root-crop systems. Grimme and comparable harvester fleet standardization drives specification conformity.
- Mulching:Bed surface preparation for plastic mulch laying in vegetable production systems.
- Irrigation:Furrow geometry optimization for drip and flood irrigation compatibility in water-regulated districts.
Soil Preparation handles the greatest equipment throughput. Seed Bed Creation shows the strongest technology upgrade momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards anchor the United States as the dominant geography shaping bed former specification requirements. Equipment procurement concentrates where labor scarcity intersects water regulation intensity.
United States
California's Central Valley vegetable producers expand mechanized bed forming capacity under SGMA groundwater mandates. OSHA agricultural machinery guarding standards and ISO 4254 safety specifications frame export-eligible equipment design. Fresno and Kern Counties drive RTK-guided precision adoption for contract farming water efficiency obligations.
Germany
EU Stage V alignment through machinery directives elevates powertrain costs across arable farming regions. The F-Gas Regulation phase-down accelerates cab climate system redesign for extended field hours. Lower Saxony and Bavaria anchor ridge geometry standardization for potato and sugar beet harvester fleet integration.
Netherlands
Protected agriculture expansion drives pneumatic bed forming specification through greenhouse supply channels. Cooperative procurement consortia consolidate equipment authority away from individual farm managers. The Westland municipality cluster leads substrate operation mechanization for high-value horticulture.
Spain
Almería and Valencia greenhouse belts adopt lighter soil disturbance profiles for year-round vegetable production. National water stress policies intensify precision tillage adoption in irrigated districts. Equipment flows through specialized horticulture distributors rather than traditional farm machinery dealers.
France
EU machinery directives and F-Gas Regulation compliance shape equipment refresh cycles in arable regions. Root-crop harvester integration demands ridge geometry conformity across northern beet production zones. Picardy and Nord-Pas-de-Calais concentrate precision bed forming deployment for Grimme-compatible operations.
Bed Formers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the bed formers market. The vendor base separates into precision agriculture ecosystem bundlers, specialized root-crop equipment fabricators, and regional tillage implement suppliers. Strategic archetypes include integrated tractor OEMs with telemetry platforms, harvester-aligned specialists with ridge geometry expertise, and independent frame builders serving commodity tillage. Dominant competitive moves encompass precision agriculture ecosystem bundling and hydraulic component supply chain consolidation.
Among harvester-aligned specialists, Grimme and Dewulf exemplify the root-crop integration archetype where ridge geometry standardization creates pull-through demand. Deere & Company anchors the integrated ecosystem tier, leveraging precision agriculture bundling across guidance and telemetry packages. These three companies represent distinct competitive positions: Grimme and Dewulf occupy the harvester-compatibility vector, while Deere & Company sits within the platform-integration tier where bed formers attach to broader mechanization systems.
| Leading Market Players |
|---|
| Grimme |
| Dewulf |
| McHugh |
| Bourgault |
| Sola |
| Orthman |
| CHECCHI & MAGLI |
| Deere & Company |
| AGCO Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at European hydraulic component foundries directly shapes price floors for precision bed forming systems, concentrating supply power among Bosch Rexroth and Parker Hannifin while forcing mid-tier frame builders toward commoditized positioning in manual and semi-automated tiers.
Pricing Analysis
California Central Valley commands 15-25% premiums over Midwest grain belt pricing for RTK-guided precision configurations, reflecting SGMA compliance-driven specification intensity. Three-tier pricing structure across premium, standard, and economy levels separates telemetry-integrated precision systems from conventional hydraulic frames and entry-level manual units. Cost compression in standard-tier hydraulic systems is intensifying because EPA Tier 4 Final after-treatment costs squeeze mid-horsepower tractor attachment economics. Smallholder cooperatives exhibit highest price sensitivity, while contract farming operations in water-regulated districts show lowest elasticity due to mechanization mandate enforcement.
Supply Chain Analysis
Bosch Rexroth valve production concentration in Germany and Parker Hannifin cylinder manufacturing in the United States create single-source vulnerability for real-time force modulation systems. Frame fabrication draws from hot-rolled steel coil supply anchored in domestic US mills and European producers, with disc blade hardfacing dependent on tungsten carbide sourcing from Chinese powder metallurgy specialists. Tariff exposure on Section 232 steel imports threatens margin stability for North American frame builders. Distribution runs through Deere and AGCO dealer networks for precision agriculture bundles, while pneumatic systems flow through specialized greenhouse supply channels in the Netherlands and Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment specification authority fragmentation across cooperative procurement consortia and centralized technical committees creates niche entry points for specialized players outside integrated OEM ecosystems.
For Market Incumbents: Compound telemetry platform dominance by embedding bed formers deeper into precision agriculture subscription bundles, locking in California Central Valley vegetable producers through SGMA compliance-aligned water efficiency analytics. Defend against harvester-aligned specialists by securing exclusive ridge geometry standardization agreements with Grimme-compatible root-crop operations. Prioritize backward integration into hydraulic valve supply through captive sourcing partnerships with Bosch Rexroth to offset Tier 4 Final cost inflation. For New Entrants and Emerging Players: Lead with pneumatic system specialization for Netherlands and Spain protected agriculture clusters, where greenhouse expansion outpaces traditional farm machinery dealer coverage. Target the semi-automated technology tier where legacy fleet CAN bus integration challenges delay incumbent platform refreshes. Pursue OEM white-label supply agreements with mid-tier tractor manufacturers seeking electrification-compatible attachment portfolios. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision agriculture ecosystem bundlers over standalone frame fabricators as RTK guidance and telemetry integration become table stakes. Long-term viability rests on recurring revenue attachment rates rather than equipment shipment volumes. Signal to watch: cooperative procurement consortia consolidation velocity in Midwestern US grain operations as an indicator of pricing power shift toward integrated platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Ecosystem Bundling | Deere and AGCO telemetry integration locks in California Central Valley contract farming operations through SGMA compliance data services. |
| Harvester Compatibility Standardization | Ridge geometry conformity with Grimme and Dewulf fleets creates pull-through demand in German and French root-crop zones. |
| Electrification Retrofit Architecture | Mid-horsepower tractor electric platforms from major OEMs open white space for compatible bed former attachments with reduced hydraulic complexity. |
| Pneumatic System Channel Development | Netherlands and Spain greenhouse supply networks offer specialized distribution outside traditional farm machinery dealer concentration. |
| OSHA Guarding Compliance Services | ISO 4254 safety specification alignment opens recurring revenue streams for certification consulting and retrofit engineering. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA emissions filings, EU machinery directive documentation, and agricultural equipment customs records through structured interviews with precision agriculture product managers, hydraulic systems engineers, cooperative procurement committee chairs, and aftermarket service directors at major dealer networks. Bottom-up shipment triangulation from frame builder production data cross-validates against top-down tractor attachment market sizing from OEM disclosure analysis.
Segmentation dimensions modeled span power system architecture, operational environment intensity, control technology tier, and downstream crop system application across the analysis window. CAGRs derive from equipment replacement cycle analysis, regulatory compliance deadline mapping, and water regulation enforcement trajectory in key production districts. Forecast inputs incorporate labor scarcity indices for tractor-operator availability and SGMA groundwater basin sustainability targets.
The analysis sits within stated boundaries; outcomes outside EPA Tier 4 Final and EU Stage V alignment timelines, or absent accelerated SGMA enforcement, would require recalibration. Forecasts reflect documented assumptions on steel input cost trajectories and hydraulic component supply continuity. Practitioners should keep alternative scenarios live as electrification architecture maturation and F-Gas Regulation HVAC redesign requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
Bed Wedge Market
Bedroom Furniture
United States Mattress Market
Bedroom Furniture
Bed Head Panel Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
US Daybeds Market