
 Children Mattress Market | 2026-2036
Children Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Children Mattress Market Outlook
REACH compliance is hardening material sourcing requirements for European-bound production, elevating testing costs for new entrants. Naturepedic leverages domestic organic cotton supply chains to preempt certification bottlenecks. Serta Simmons Bedding anchors wholesale relationships with major retail chains, sustaining volume throughput against direct-to-consumer challengers. Tempur Sealy International navigates premium positioning through adaptive foam formulations that command higher price realization.
A children mattress is a sleep surface engineered for pediatric ergonomic support, typically incorporating polyurethane foam cores, coil systems, or natural latex layers with firmness ratings between 8 and 10 on the ILD scale to reduce suffocation risk and promote spinal alignment during developmental growth. Memory foam segments face margin compression from petrochemical volatility, while hybrid constructions combining pocketed coils with latex comfort layers capture expanding preference among parents seeking durability. The bed-in-a-box form factor disrupts traditional retail by compressing logistics costs and enabling trial-period returns that reshape customer acquisition economics.
The US Consumer Product Safety Commission enforces mandatory flammability standards under 16 CFR Part 1633, while the EU REACH regulation restricts chemical flame retardants in imported foam substrates. CertiPUR-US and OEKO-TEX Standard 100 certifications increasingly function as non-tariff market access requirements rather than optional premium markers. Stakeholders must monitor evolving state-level chemical disclosure laws in California and New York that threaten to fragment compliance obligations across distribution footprints.
Market Dynamics
Direct-to-consumer distribution channels are compressing traditional wholesale margins while forcing incumbent manufacturers to reconfigure fulfillment infrastructure around compressed vacuum-sealed logistics and trial-period return economics.
Growth Catalysts
- 16 CFR Part 1633 Flammability Mandate:The US Consumer Product Safety Commission's stringent standards are accelerating certified organic material adoption as manufacturers phase out chemical flame retardants to achieve compliance.
- Pediatric Sleep Health Prioritization:Parents in the United States, China, and Germany are elevating ergonomic support specifications in purchase decisions, driving premium positioning for products with ILD 8-10 firmness ratings.
- Latex-Coil Hybrid Construction:This material combination is capturing preference share among durability-focused buyers seeking to extend replacement cycles beyond standard polyurethane foam lifespans.
Market Restraints
- Petrochemical Input Volatility:Memory foam segments face margin compression from crude oil derivative price swings that destabilize cost forecasting for polyurethane core production.
- European REACH Compliance Burden:ECHA chemical restrictions on imported foam substrates are elevating testing expenditures and certification timelines for new entrants targeting EU distribution.
- Organic Cotton Supply Concentration:Certified organic fiber sourcing bottlenecks in domestic US supply chains are constraining production scaling for premium product lines.
Strategic Opportunities
- Subscription-Based Replacement Models:Mattress-as-a-service frameworks targeting developmental growth stages offer recurring revenue potential as children transition through size categories.
- Smart Sensor Integration:Convergence of pressure-mapping foams with sleep monitoring hardware creates premium tier differentiation for health-data-oriented parents.
- State-Level Chemical Disclosure Laws:California and New York transparency mandates are fragmenting compliance obligations, creating advisory service opportunities for certification specialists.
Industry Challenges
- CertiPUR-US Testing Backlogs:Laboratory capacity constraints are extending certification timelines from weeks to months, delaying product launches and inventory positioning.
- Reverse Logistics Complexity:Trial-period return policies require specialized decompression and refurbishment infrastructure that most manufacturers lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children Mattress Market |
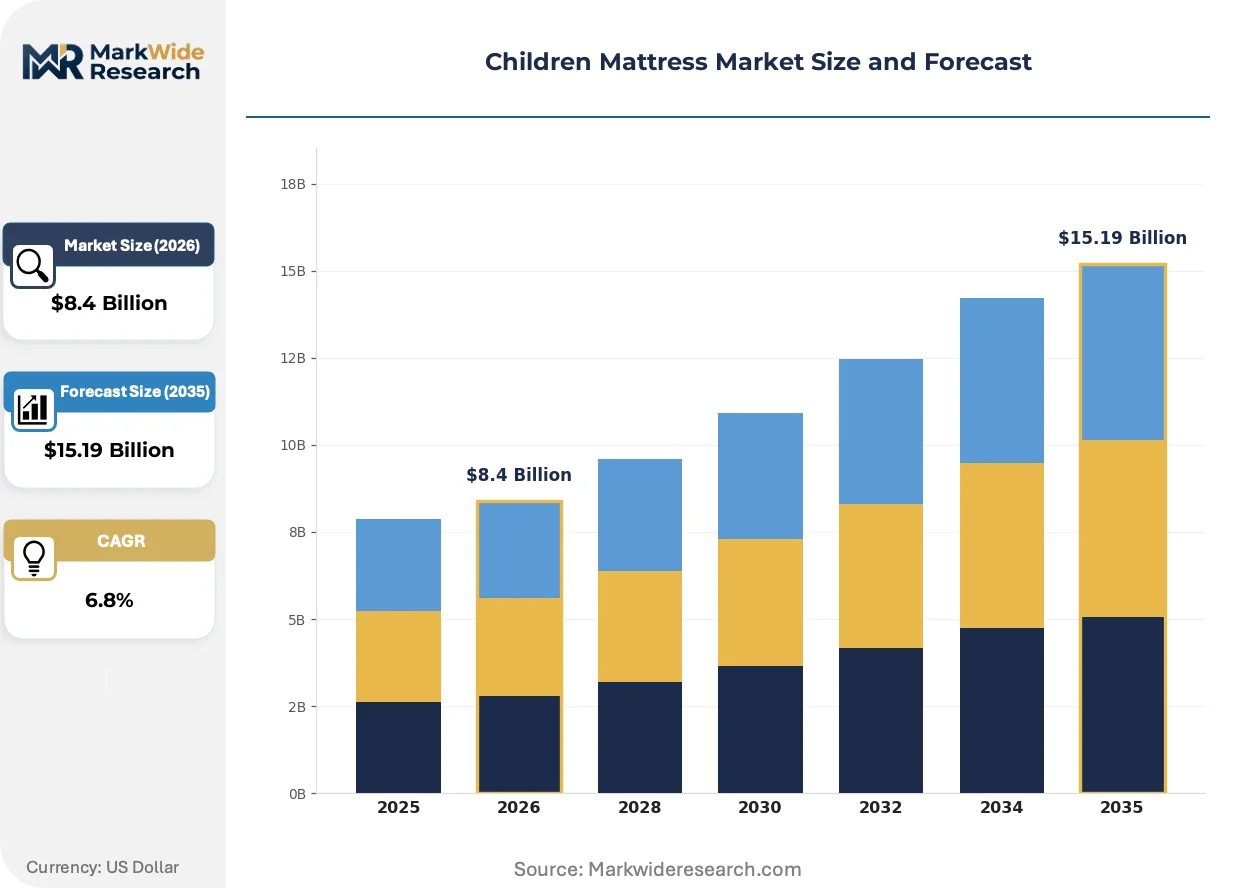
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Innerspring, Latex, Hybrid Size: Crib, Twin, Full, Bunk Bed Form: Mattress Protector, Mattress Topper, Bed-in-a-Box, Pillow Customer Type: Parents, Schools, Daycares, Retailers |
| Companies Covered | Naturepedic, Saatva, Helix Sleep, Avocado Green Mattress, Serta Simmons Bedding, Tempur Sealy International, Purple Innovation, Moonlight Slumber, Colgate Mattress, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children Mattress Market Strategic Shifts
Adaptive material science and compressed logistics formats are restructuring how pediatric sleep products reach end-users, with certification standards evolving from optional premiums to mandatory market access conditions.
Phase-change material coatings applied to foam surfaces are electrifying thermal regulation performance in children's mattresses. Parents in premium segments are adopting these products at accelerating rates despite 40-60% price premiums over standard constructions. This technology is compressing competitive differentiation around temperature management rather than traditional firmness metrics alone.
REACH regulation amendments through ECHA are restricting halogenated flame retardants in foam substrates imported into European Union member states. Manufacturers are reformulating core layers with phosphorus-based alternatives or natural fiber barriers, increasing R&D expenditure allocation. German and French distribution channels are most affected, with buyers now demanding OEKO-TEX Standard 100 documentation as table stakes.
Pediatricians and parenting influencers are reshaping purchase criteria through sleep-development content that elevates spinal alignment specifications over brand recognition. Traditional retail showrooms are losing traffic to video-centric social platforms where unboxing and firmness-testing content drives discovery. This behavioral shift concentrates in United States suburban markets where millennial parent demographics dominate household formation.
Children Mattress Market Segmentation
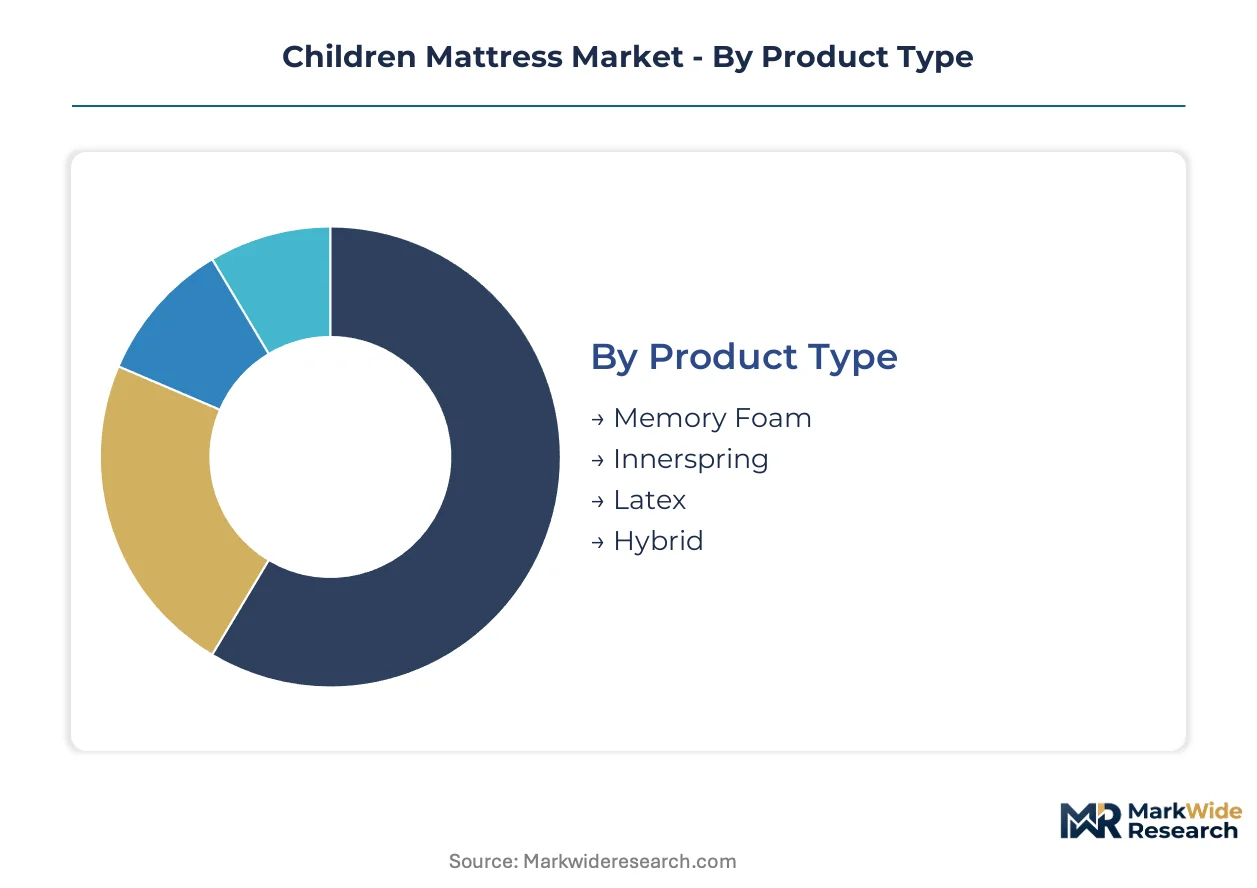
Segmentation in the children mattress market reveals how safety regulations, sleep-development science, and logistics economics fragment demand across distinct product configurations. Manufacturers must align material specifications and distribution formats with the purchasing authority and risk tolerance of each buyer type.
Product Type:
Customization versus standardization tension runs deepest in core construction, where material chemistry directly determines flammability compliance pathways and ergonomic performance claims.
- Memory Foam:Viscoelastic polyurethane formulations with density ratings between 3.0 and 5.0 pounds per cubic foot dominate mid-tier positioning. US Consumer Product Safety Commission 16 CFR Part 1633 compliance costs are compressing margins as manufacturers reformulate away from halogenated retardants toward phosphorus-based alternatives.
- Hybrid:Pocketed coil support cores layered with latex or foam comfort zones command premium positioning through durability claims and extended warranty terms. German and Chinese parents seeking replacement cycles beyond seven years are concentrating demand in this configuration, though coil sourcing from specialized wire mills creates supply bottlenecks.
- Innerspring:Continuous or Bonnell coil systems with border rod reinforcement remain the lowest-cost core technology, prevalent in institutional procurement for schools and daycares where budget constraints override ergonomic specifications.
- Latex:Natural rubber sap derivatives or synthetic SBR blends offer inherent flame resistance without chemical additives, satisfying EU REACH restrictions for European-bound production, though certified organic latex carries 40-60% raw material premiums over polyurethane equivalents.
Most installed capacity flows through Memory Foam. Expansion is steepest in Hybrid.
Size:
Dimensional requirements track developmental stages and spatial constraints in residential versus institutional settings, with replacement frequency varying dramatically across the progression from infant to adolescent sleep surfaces.
- Crib:Standardized dimensions of 27.5 by 51.5 inches with maximum 6-inch thickness per ASTM F2933 safety specifications. Parents in the United States prioritize firmness ratings of ILD 8-10 to reduce suffocation risk, creating a narrow technical window for competitive differentiation.
- Twin:38 by 75 inch dimensions serve the largest volume segment as children transition from cribs through early adolescence. Chinese urban households with limited bedroom square footage are driving demand for extra-long variants (80 inches) to extend usable lifespan.
- Full:54 by 75 inch surfaces accommodate shared sleeping arrangements or older children requiring more surface area, with demand concentrating in suburban US markets where bedroom sizes permit larger furniture footprints.
- Bunk Bed:Specialized low-profile constructions, typically 6 to 8 inches thick, with reinforced edges for guardrail compatibility. Schools and multi-child households in Germany specify these for space efficiency in shared bedrooms.
Volume concentrates in Twin configurations. Premium realization is strongest in Crib.
Form:
Physical presentation determines logistics economics and trial-period return infrastructure, with compressed formats disrupting traditional retail throughput while creating new reverse logistics burdens.
- Bed-in-a-Box:Vacuum-compressed and rolled mattresses in compact cartons reduce shipping costs by 60-70% versus flat delivery, enabling direct-to-consumer economics. The format demands specialized decompression and refurbishment capabilities for returned units that most manufacturers lack in-house.
- Mattress Protector:Waterproof barriers with polyurethane membrane or vinyl backing layers address incontinence and allergy concerns, with US parents treating these as mandatory accessories rather than optional add-ons.
- Mattress Topper:2-4 inch supplementary comfort layers allow parents to adjust firmness without full mattress replacement, extending core product lifespans while capturing incremental revenue per household.
- Pillow:Pediatric-specific designs with contoured shapes or adjustable fill volumes for neck support, though this category competes with general bedding specialists rather than mattress-focused manufacturers.
Distribution velocity is highest in Bed-in-a-Box. Margin pressure is most acute in Pillow.
Customer Type:
Purchasing authority and decision criteria diverge sharply between individual consumers prioritizing developmental health claims and institutional buyers governed by procurement regulations and liability exposure.
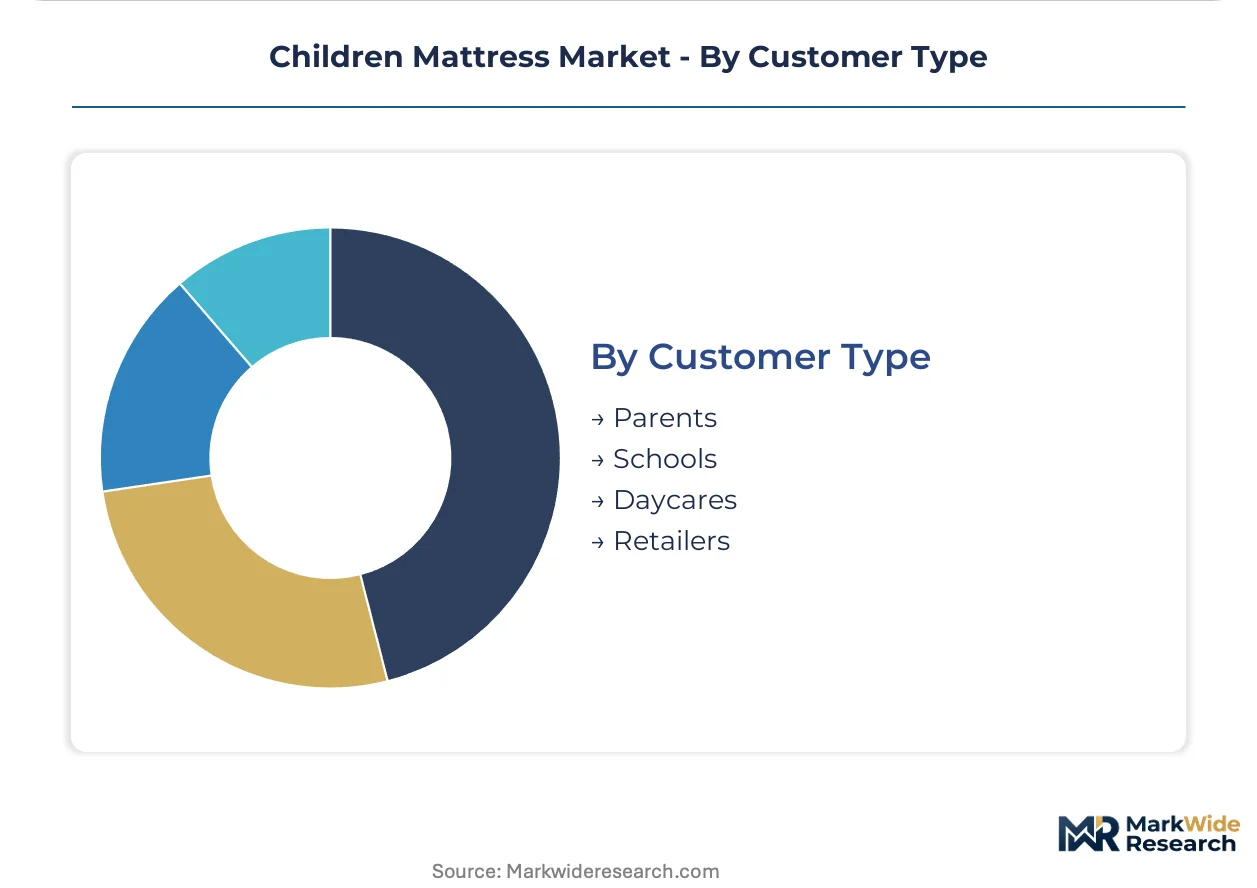
- Parents:Individual consumers responding to pediatrician recommendations and social media content elevating spinal alignment and sleep quality metrics. Millennial demographics in United States suburban markets are shifting discovery toward video-centric platforms and away from traditional retail showrooms.
- Schools:Public and private educational institutions with formal procurement processes, bulk purchasing requirements, and extended payment terms. Compliance with state-level chemical disclosure laws in California and New York fragments vendor qualification requirements.
- Daycares:Licensed childcare facilities subject to state-specific safety inspections and nap-time duration regulations, creating demand for durable, easily sanitized surfaces with waterproof barriers as standard features.
- Retailers:Wholesale and specialty bedding stores, including online marketplaces, that control shelf placement and co-marketing investments. Serta Simmons Bedding and similar incumbents anchor these relationships through volume rebates and exclusive product lines.
Revenue concentration sits with Parents. Contract volume expansion is fastest in Schools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The children mattress industry traces its modern scaling to post-war United States manufacturing clusters that standardized crib dimensions and flammability testing protocols, later diffusing production expertise to European and Asian markets through licensing agreements and joint ventures.
United States
Millennial parents in suburban markets prioritize ergonomic firmness ratings and organic certifications in purchase decisions. The US Consumer Product Safety Commission enforces 16 CFR Part 1633 flammability standards that accelerate certified organic material adoption. Manufacturing concentrates in North Carolina furniture corridors and Midwest industrial zones where foam conversion and textile finishing capabilities cluster.
Germany
German consumers extend replacement cycles through latex-coil hybrid constructions that command durability premiums. ECHA REACH restrictions on halogenated flame retardants in imported foam substrates elevate testing expenditures for new entrants. Production gravity sits in Bavaria and North Rhine-Westphalia where bedding specialists maintain integrated supply chains from wire drawing to final assembly.
China
Urban households with limited bedroom square footage drive demand for twin extra-long variants that extend usable lifespan through adolescence. The country's national standards regulator mandates GB protocol compliance for juvenile product safety that overlaps with export certification requirements. Manufacturing clusters in Yangtze River Delta provinces supply both domestic consumption and contract production for North American and European brands.
India
Rising middle-class households in metropolitan areas are elevating sleep health awareness for pediatric development. The Bureau of Indian Standards enforces ISI marking requirements for mattress safety that fragment compliance across state-level enforcement variations. Production concentrates in Maharashtra and Gujarat where polyurethane foam slabstock operations serve regional distribution networks.
Children Mattress Market Competitive Environment
The competitive structure tilts toward direct-to-consumer challengers compressing traditional wholesale margins. Incumbent manufacturers anchor retail relationships through volume rebates and exclusive product lines while vacuum-sealed logistics formats reshape customer acquisition economics. Three archetypes dominate: organic certification specialists, scale-driven wholesale incumbents, and adaptive foam technology licensors. M&A activity concentrates on brand portfolio diversification and geographic expansion into European REACH-regulated markets.
Among US-based specialists, Naturepedic exemplifies the organic certification archetype through domestic cotton supply chain control. Serta Simmons Bedding occupies the scale-driven wholesale position anchoring major retail chain relationships. Tempur Sealy International represents the technology-licensing tier through premium adaptive foam formulations that command higher price realization.
| Leading Market Players |
|---|
| Naturepedic |
| Saatva |
| Helix Sleep |
| Avocado Green Mattress |
| Serta Simmons Bedding |
| Tempur Sealy International |
| Purple Innovation |
| Moonlight Slumber |
| Colgate Mattress |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between OEKO-TEX Standard 100 holders and uncertified producers manifests in both pricing power and raw material sourcing configurations. Premium organic cotton supply chains in the United States command 40-60% raw material premiums over conventional alternatives, while REACH-compliant foam substrates for European-bound production require dual-sourcing strategies that reshape procurement economics.
Pricing Analysis
Bed-in-a-box bundled service splits dominate transaction structures, pairing compressed logistics with trial-period return guarantees against traditional flat-delivery unbundled alternatives. Three-tier pricing structure across premium organic, certified standard, and economy polyurethane tiers differentiates primarily on flammability certification grade and domestic versus imported coil sourcing. Pricing pressure stems from petrochemical input volatility in memory foam segments, compressing margins for mid-tier producers. Schools and daycares exhibit highest price sensitivity through formal procurement processes, while millennial parents in United States suburban markets demonstrate lowest sensitivity for certified organic crib configurations.
Supply Chain Analysis
Dual-sourcing requirements from major retail chains and direct-to-consumer platforms mandate multi-supplier qualification for foam converters and wire mills alike. Manufacturing concentrates in the United States, China, and Germany, with polyurethane foam slabstock operations in North Carolina and Yangtze River Delta provinces feeding regional assembly. Raw material dependencies center on certified organic cotton fiber, natural rubber latex sap, and specialized coil wire from dedicated mills. Single-source vulnerability in certified organic cotton supply chains constrains production scaling for premium lines. Distribution runs through wholesale retail anchors, online direct-to-consumer platforms, and institutional procurement channels with diverging fulfillment infrastructure requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The children mattress market functions as a regulatory compounder where 16 CFR Part 1633 flammability mandates and EU REACH amendments continuously elevate compliance costs, transforming certification holdings into durable competitive moats that reshape buyer willingness-to-pay.
For Market Incumbents: Cement wholesale retail relationships through exclusive product lines and volume rebate structures that raise switching costs for major chains. Incumbents must simultaneously build in-house decompression and refurbishment capabilities to capture trial-period return economics that direct-to-consumer challengers exploit. The threat of compressed logistics formats displacing traditional flat-delivery throughput demands fulfillment infrastructure investment as the priority defensive lever. For New Entrants and Emerging Players: Pediatric sleep influencers represent the most penetrable channel partner type for bypassing traditional showroom discovery. New entrants should target United States suburban millennial parents through video-centric social platforms where unboxing content drives purchase consideration. The white-space opportunity sits in subscription-based replacement models for developmental growth stages, with smart sensor integration as the differentiated go-to-market angle for premium tier establishment. For Investors and Strategic Acquirers: Consolidation pressure builds where laboratory certification backlogs extend product launch timelines and fragment compliance obligations across state-level chemical disclosure laws. Long-term viability favors targets with captive organic cotton supply chains and established OEKO-TEX documentation rather than reformulation-dependent foam specialists. The acquisition target archetype combines domestic certification holdings with direct-to-consumer logistics capabilities. Watch CertiPUR-US testing capacity expansion as the signal for inflection in new entrant launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | Preempts 16 CFR Part 1633 and REACH compliance bottlenecks that delay market access. |
| Direct-to-Consumer Channel Launch | Captures millennial parent discovery shift away from traditional retail showrooms. |
| Domestic Organic Cotton Integration | Secures supply chain control against certified fiber sourcing concentration risks. |
| Reverse Logistics Infrastructure Buildout | Enables trial-period return economics that reshape customer acquisition costs. |
| Smart Sensor Technology Partnership | Creates premium tier differentiation through sleep monitoring hardware convergence. |
Study Parameters
Direct dialogue with foam conversion plant managers, organic cotton procurement leads at textile suppliers, retail category buyers, pediatric sleep consultants, and regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from US Consumer Product Safety Commission enforcement records, ECHA REACH amendment documentation, CertiPUR-US certification databases, and customs trade data for foam substrate imports. Bottom-up capacity modeling across manufacturing clusters triangulated against top-down demand segmentation to produce convergent estimates.
Segmentation-level outputs across product type, size configuration, distribution form, and customer archetype populated the analytical framework over the projection horizon. CAGRs derived from regression analysis against pediatric population demographics, household formation rates, and channel shift velocity. Industry-specific forecast inputs included polyurethane raw material price indices and state-level chemical disclosure law adoption timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA REACH amendment scope, petrochemical derivative volatility, and organic cotton supply expansion rates. Deviation in flammability standard enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
US Wall Beds Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Heated Bedding Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
Global Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Baby Cribs and Cots Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Australia Mattress Market