
 Bed Head Panel Market | 2026-2036
Bed Head Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Bed Head Panel Market Intelligence
Acute care hospitals are reorganizing capital expenditure toward fully integrated patient room infrastructure, displacing standalone medical gas outlets and surface-mounted electrical assemblies. Drägerwerk AG & Co. KGaA anchors its position through captive manufacturing of gas delivery components that lock into proprietary bed head architectures. BeaconMedaes competes on geographic dominance across North American hospital networks with standardized modular platforms. Getinge Group differentiates through vertical control over sterilization-adjacent room design, extending its clinical environment expertise into wall-based patient services.
A bed head panel is a permanently installed wall-mounted unit, typically constructed from aluminum extrusions, antimicrobial-coated steel, or high-pressure laminate composites, that integrates medical gas terminals, low-voltage electrical outlets, data ports, lighting controls, and communication interfaces into a single clinical workstation. Metal panels dominate healthcare specifications where infection control protocols demand non-porous, chemically resistant surfaces capable of withstanding repeated disinfection cycles. Composite panels represent the fastest-growing product category as manufacturers layer thermoplastic skins over aluminum framing to reduce weight while maintaining structural rigidity for gas pipeline anchoring. Hospitality applications favor wood and plastic panels where aesthetic customization outweighs clinical functionality, though these segments carry thinner margin pools due to commoditized supply chains.
The EU Medical Device Regulation (MDR) and CE marking framework classify permanently installed bed head panels as medical devices when they incorporate gas delivery functions, compelling manufacturers to maintain technical documentation and quality management systems audited by notified bodies. The US FDA regulates gas outlet components under 21 CFR 868 while electrical assemblies fall under FCC Part 15 and NFPA 99 healthcare facility codes, creating a multi-agency compliance landscape that favors established players with dedicated regulatory affairs capacity. Stakeholders must monitor how evolving interoperability standards for patient monitoring data streams reshape panel architecture requirements and determine whether to develop proprietary interface ecosystems or adopt open-protocol designs that accommodate third-party device integration.
Market Dynamics
Hospital procurement departments are consolidating specifications around integrated bed head panels that merge medical gas delivery, electrical infrastructure, and nurse communication into unified wall systems, compressing supplier lists and favoring manufacturers with captive component production.
Growth Catalysts
- EU MDR compliance mandates:The Medical Device Regulation classification of gas-integrated panels as Class I medical devices forces hospital procurement toward certified suppliers with notified body audits, eliminating uncertified competitors from tender processes.
- German hospital modernization:Federal and state-level infrastructure programs prioritize infection-control-compliant wall systems, creating concentrated demand for antimicrobial-coated aluminum and steel panel architectures.
- Composite material advances:Thermoplastic-over-aluminum construction reduces panel weight by 30-40% while maintaining pipeline anchoring integrity, enabling faster installation and reduced structural load requirements in retrofit projects.
Market Restraints
- Aluminum price volatility:Extrusion-grade aluminum and antimicrobial coating chemicals face commodity market swings that compress manufacturer margins on fixed-price hospital contracts.
- European supply concentration:Gas terminal and valve component production clusters in Germany and northern Italy, creating geographic single-source risk for panel assemblers outside these regions.
- Legacy infrastructure lock-in:Surface-mounted electrical and gas systems in older hospital wings require complete wall demolition for panel installation, deterring partial modernization budgets.
Strategic Opportunities
- India hospital expansion:Government and private hospital construction under Ayushman Bharat infrastructure schemes lacks established bed head panel suppliers, opening white space for early entrants with localized assembly.
- Modular retrofit platforms:Clip-on panel systems that overlay existing wall surfaces without demolition address the installed base of aging hospitals in Western Europe and North America.
- IoT convergence:Integration of environmental sensors and patient monitoring data ports into panel architectures creates recurring service revenue streams beyond hardware sales.
Industry Challenges
- Multi-agency certification timelines:Panels require simultaneous FDA 510(k) or EU MDR technical documentation, NFPA 99 electrical compliance, and FCC Part 15 radio approvals, extending product launch cycles.
- Gas pipeline integration complexity:Field connection of medical gas terminals to hospital central supply systems demands certified medical gas installer labor that faces acute shortage in several markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bed Head Panel Market |
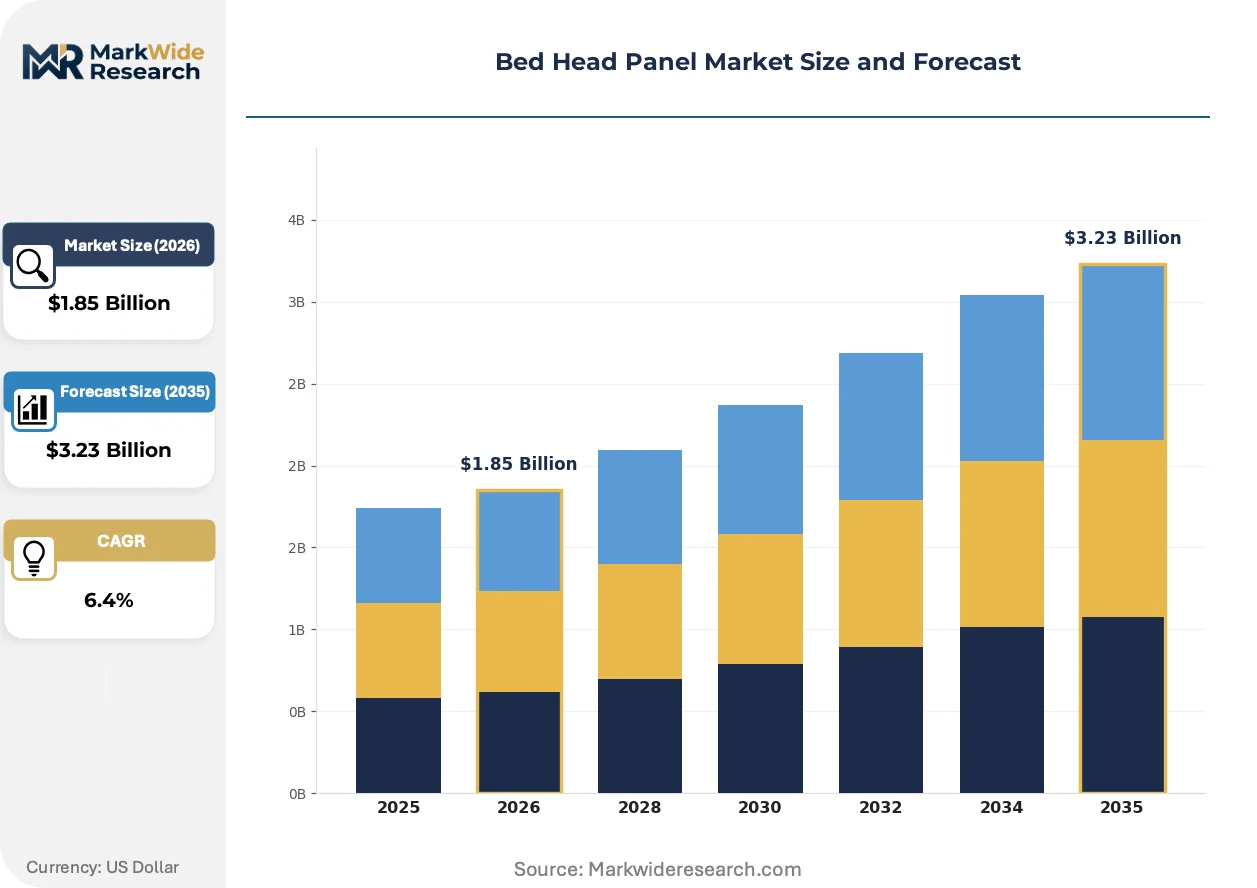
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Panel, Metal Panel, Plastic Panel, Composite Panel Application: Residential, Commercial, Hospitality, Healthcare Installation Type: Wall Mounted, Free Standing, Modular, Integrated End User: Homeowners, Contractors, Interior Designers, Property Managers |
| Companies Covered | Baxter International Inc., Drägerwerk AG & Co. KGaA, Amico Corporation, Precision UK Ltd., Getinge Group, BeaconMedaes, Stryker Medical, Capsa Healthcare, Novair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bed Head Panel Market Strategic Shifts & Innovations
Bed head panel architecture is splitting between clinical-grade metal systems and lightweight composite alternatives, with regulatory pressure and installation economics pulling specifications in opposing directions across hospital construction and renovation segments.
Antimicrobial surface technology is bifurcating market positioning. Silver-ion-impregnated powder coatings on aluminum extrusions deliver durable chemical resistance for high-acuity wards. Copper-alloy touch surfaces command premium positioning in infection-control-sensitive departments. German hospital groups specify silver-ion systems for standard wards while reserving copper surfaces for oncology and transplant units. This material divergence is compressing mid-tier suppliers lacking either coating capability into commodity wood-plastic hospitality segments.
EU MDR technical documentation requirements are reshaping competitive access. Permanently installed panels with gas delivery functions now require quality management system audits by notified bodies, technical file maintenance, and post-market surveillance protocols. Manufacturers without existing medical device regulatory infrastructure face 18-24 month compliance timelines. Established suppliers with captive notified body relationships are securing preferred vendor status in French and Benelux hospital tenders ahead of smaller competitors.
Specification authority is migrating from facilities managers to clinical engineering departments. Biomedical equipment teams now dominate bed head panel selection to ensure interoperability with patient monitoring ecosystems and nurse call networks. This shift favors suppliers offering open-protocol communication interfaces over proprietary architectures. US academic medical centers increasingly mandate HL7 FHIR-compatible data ports in panel specifications, forcing legacy manufacturers to retrofit connectivity modules or exit premium segments.
Bed Head Panel Market Segmentation
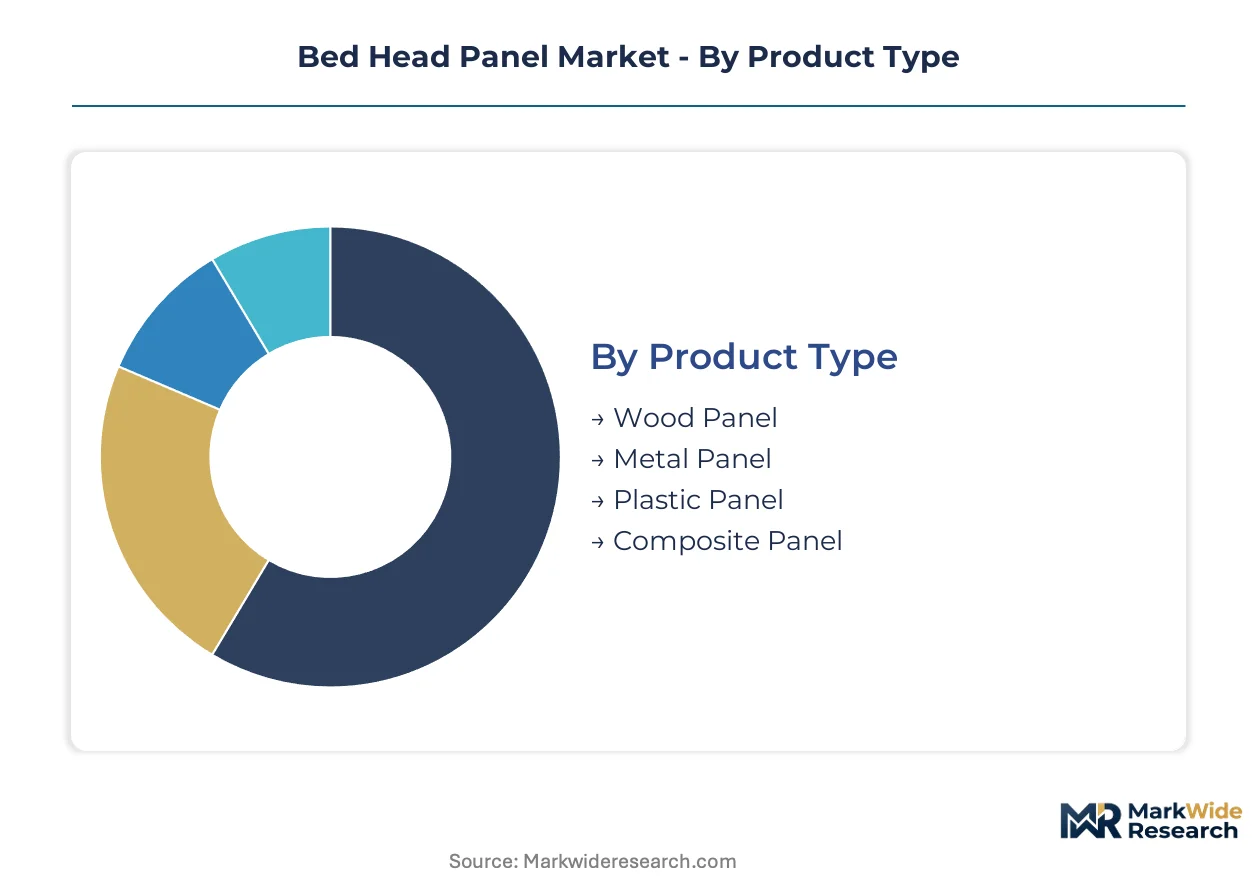
Bed head panel procurement channels diverge sharply across clinical and non-clinical environments. Hospital systems route integrated metal systems through group purchasing organizations, while hospitality and residential segments flow through architectural specification firms and direct contractor relationships.
Product Type:
Metal and composite panels dominate hospital procurement channels where infection-control certification gates supplier eligibility, while wood and plastic alternatives serve hospitality and residential markets through less regulated specification paths.
- Metal Panel:Aluminum extrusions and antimicrobial-coated steel constructions anchor high-acuity healthcare specifications. German hospital modernization programs and EU MDR compliance mandates concentrate demand for silver-ion-impregnated powder coatings that withstand repeated disinfection cycles.
- Composite Panel:Thermoplastic skins layered over aluminum framing reduce weight by 30-40% while maintaining pipeline anchoring integrity. Retrofit projects in aging Western European and North American hospitals favor this construction for reduced structural load and faster installation timelines.
- Wood Panel:Hospitality applications specify veneered hardwoods where aesthetic customization outweighs clinical functionality, though commoditized supply chains compress margins.
- Plastic Panel:Polymer constructions serve budget residential and light commercial segments with limited regulatory burden but thinner pricing power.
By volume, metal panels lead hospital procurement. By growth pace, composite constructions are expanding most quickly.
Application:
Cost tier stratification separates clinical-grade specifications from aesthetic-driven segments, with certification requirements creating pricing cliffs between healthcare and non-healthcare deployments.
- Healthcare:Acute care hospitals, long-term care facilities, and outpatient clinics demand integrated systems consolidating gas outlets, electrical infrastructure, and nurse call interfaces. EU MDR classification as Class I medical devices when gas delivery functions are present eliminates uncertified competitors from tender processes.
- Hospitality:Hotels and cruise ship cabins prioritize visual customization and rapid installation over clinical functionality, sourcing through interior design specification channels with shorter procurement cycles.
- Commercial:Office buildings and institutional spaces deploy standardized panel systems for cable management and power distribution without medical gas integration.
- Residential:High-end home installations and senior living apartments represent fragmented demand with limited standardization and price-sensitive procurement.
Healthcare commands premium pricing tiers. Hospitality delivers volume scale with compressed margins.
Installation Type:
Volume concentration favors wall-mounted permanent installations in new hospital construction, while modular and integrated alternatives address the substantial retrofit opportunity in aging clinical infrastructure.
- Wall Mounted:Permanent aluminum or steel extrusion systems anchored to structural walls dominate new hospital construction. German federal infrastructure programs and US academic medical center expansions drive specification authority toward clinical engineering departments.
- Modular:Clip-on overlay systems attach to existing wall surfaces without demolition, addressing the installed base of aging hospitals where complete renovation budgets are unavailable. Western Europe and North American retrofit markets favor this approach.
- Integrated:Factory-preassembled units combining gas terminals, electrical assemblies, and communication modules reduce field installation time and labor certification requirements.
- Free Standing:Limited deployment in temporary clinical spaces and non-healthcare environments where wall modification is prohibited.
Wall-mounted systems anchor new construction volumes. Modular platforms are gaining share fastest in renovation segments.
End User:
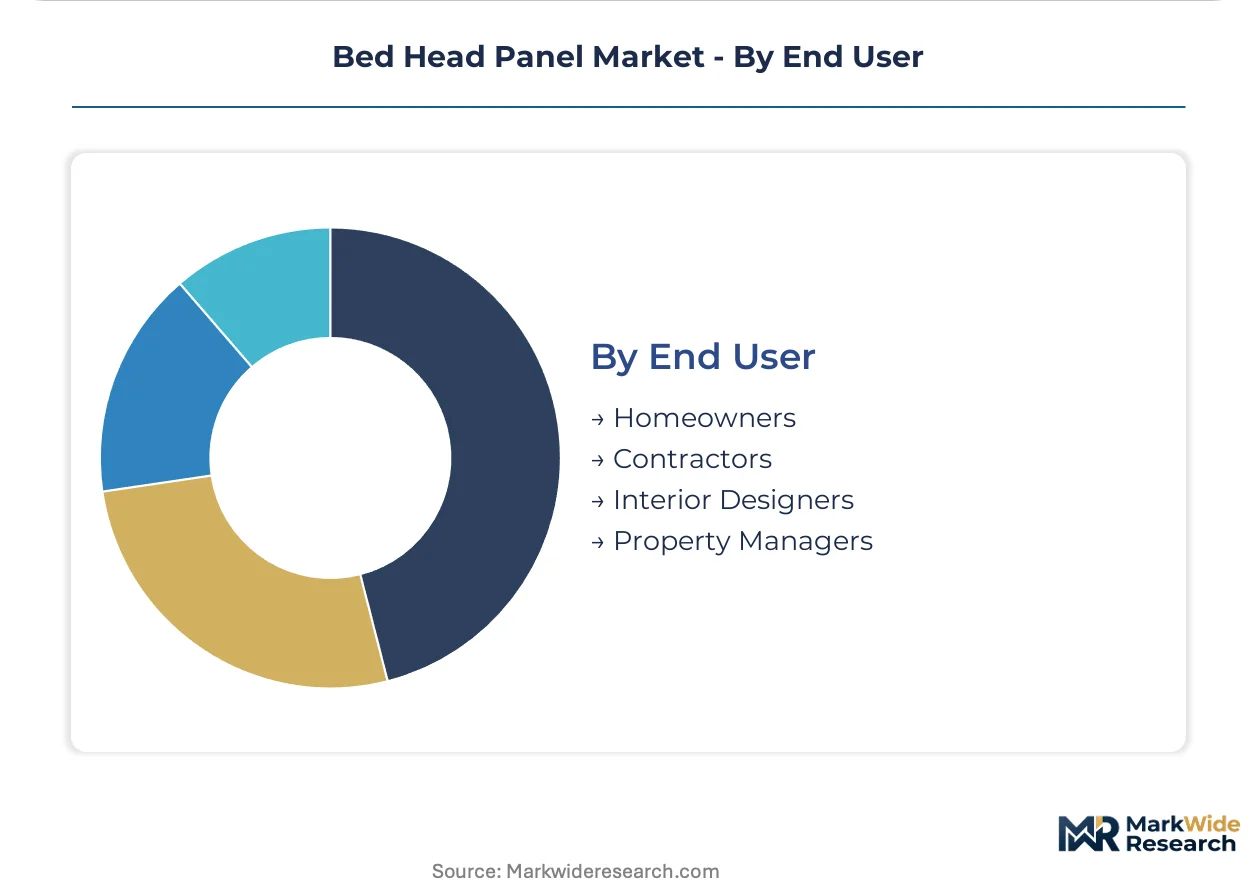
Customer type determines specification authority and procurement cycle length, with clinical engineering departments displacing facilities managers in hospital panel selection while contractors and designers dominate non-clinical channels.
- Contractors:General and specialty contractors control procurement for new hospital construction and large hospitality projects, bundling panel systems into broader infrastructure packages with consolidated supplier relationships.
- Interior Designers:Specification authority in hospitality and premium residential segments favors aesthetic customization and rapid lead times over clinical certification.
- Property Managers:Commercial building operators prioritize standardized replacement cycles and minimize vendor fragmentation for maintenance efficiency.
- Homeowners:Fragmented direct demand with limited volume concentration and high price sensitivity in residential renovation markets.
Contractors consolidate procurement scale. Interior designers drive customization premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dense hospital network and federal infrastructure corridors anchor European bed head panel demand, while manufacturing clusters in Bavaria and North Rhine-Westphalia concentrate component supply chains for cross-border distribution.
Germany
Hospital modernization programs in Bavaria and Baden-Württemberg prioritize infection-control-compliant wall systems with antimicrobial-coated aluminum extrusions. The EU MDR classification of gas-integrated panels as Class I medical devices eliminates uncertified suppliers from federal and state tender processes. Manufacturing clusters around Stuttgart and Munich concentrate gas terminal and valve component production, serving hospital construction across the Benelux region.
United States
Academic medical centers in Boston and the Research Triangle drive specification authority toward clinical engineering departments demanding open-protocol data interfaces. The FDA regulates gas outlet components under 21 CFR 868 while FCC Part 15 governs embedded communication modules, creating multi-agency compliance requirements. Hospital construction corridors in Texas and Florida absorb modular retrofit platforms for aging infrastructure in the Northeast and Midwest.
India
Government hospital construction under Ayushman Bharat infrastructure schemes generates white-space demand for localized panel assembly lacking established supplier networks. The Central Drugs Standard Control Organization (CDSCO) medical device registration requirements apply to gas delivery functions, though enforcement timelines vary by state. Private hospital construction in Maharashtra and Karnataka attracts early entrants with captive manufacturing partnerships.
United Kingdom
NHS capital expenditure shifts toward integrated patient room infrastructure consolidating gas, electrical, and nurse call systems into unified wall-mounted units. The Medicines and Healthcare products Regulatory Agency (MHRA) post-Brexit framework maintains EU MDR alignment for medical device classification. Hospital renovation projects in Greater Manchester and the West Midlands favor clip-on modular systems avoiding complete wall demolition.
France
Public hospital groups in Île-de-France and Auvergne-Rhône-Alpes specify silver-ion-impregnated powder coatings for standard wards while reserving copper-alloy surfaces for oncology departments. ANSM medical device oversight applies to permanently installed gas delivery panels, requiring notified body audits for market access. Regional hospital procurement consortia concentrate tender volumes, compressing supplier lists toward established CE-marked manufacturers.
Bed Head Panel Market Key Industry Players
Listed leaders compete with private specialists across regulatory certification capacity, creating a tiered structure where public company scale advantages meet family-owned technical depth. Market concentration favors manufacturers with captive gas component production and established notified body relationships. Three archetypes dominate: diversified medical technology conglomerates with vertical control over clinical environments; specialized gas infrastructure fabricators with regional hospital network penetration; and modular construction specialists addressing retrofit demand. Competitive moves center on M&A to acquire regulatory documentation archives and strategic partnerships with architectural specification firms.
Within the diversified medical technology tier, Drägerwerk AG & Co. KGaA and Getinge Group exemplify players with backward integration into gas delivery components and sterilization-adjacent room design expertise. Among specialized fabricators, BeaconMedaes occupies a position representing geographic dominance across North American hospital networks with standardized modular platforms. Precision UK Ltd. sits within the regional specialist archetype, anchoring British and Irish hospital procurement channels through proximity to NHS specification authority.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Drägerwerk AG & Co. KGaA |
| Amico Corporation |
| Precision UK Ltd. |
| Getinge Group |
| BeaconMedaes |
| Stryker Medical |
| Capsa Healthcare |
| Novair |
| Others |
Cost & Logistics Intelligence
EU MDR technical documentation requirements and notified body audits simultaneously gate supplier qualification and stratify pricing tiers, compressing uncertified competitors into commodity hospitality segments while elevating certified manufacturers to premium hospital procurement channels. Hospital procurement departments leverage multi-year framework agreements to extract volume discounts from established CE-marked suppliers, while aluminum price volatility and antimicrobial coating chemical costs transmit margin pressure back through fixed-price contracts.
Pricing Analysis
Volume-discount tiering structures anchor hospital procurement, with three-tier pricing separating copper-alloy oncology specifications from silver-ion standard wards and economy-grade hospitality panels. Price differentiation hinges on CE marking tier and antimicrobial coating grade, with MDR-certified gas-integrated units commanding substantial premiums over non-medical-device alternatives. Cost compression in mid-tier composite panels is intensifying because thermoplastic-over-aluminum construction democratizes lightweight retrofit solutions. Contractors exhibit highest price sensitivity in hospitality bundling, while clinical engineering departments prioritize interoperability over unit economics in acute care specifications.
Supply Chain Analysis
Inbound logistics costs from Hamburg-Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes elevate landed costs for extrusion-grade aluminum and antimicrobial coating chemicals. Manufacturing concentrates in Germany, Italy, and China, with gas terminal and valve component production clustering in Bavaria and northern Italy. Raw material dependencies rest on aluminum extrusions, copper-alloy sheet, and silver-ion powder coatings. Single-source vulnerability in European gas component fabrication threatens panel assembler margins. Distribution runs through group purchasing organizations for hospital systems and architectural specification firms for hospitality channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT-enabled environmental sensing and patient monitoring data integration layers expand recurring service revenue faster than hardware sales, transforming bed head panels from capital equipment into service-attach platforms with multi-year monitoring contracts.
For Market Incumbents: Fortify regulatory documentation archives and notified body relationships to defend against MDR compliance timeline compression that eliminates smaller competitors from French and Benelux tenders. Deepen backward integration into gas terminal production to offset aluminum price volatility and secure pipeline anchoring component supply. Prioritize open-protocol HL7 FHIR compatibility to maintain specification authority as clinical engineering departments displace facilities managers in US academic medical centers. For New Entrants and Emerging Players: Differentiate on modular retrofit platforms that overlay existing wall surfaces without demolition, targeting the substantial installed base of aging hospitals in Western Europe and North America where complete renovation budgets remain unavailable. Penetrate India's Ayushman Bharat hospital construction corridors through localized assembly partnerships with Maharashtra and Karnataka private hospital developers, exploiting white-space demand lacking established supplier networks. For Investors and Strategic Acquirers: EU MDR full enforcement reshapes the acquisition landscape toward targets with existing notified body audits and quality management system infrastructure that compress 18-24 month compliance timelines. Five-to-ten-year viability favors specialized fabricators with captive gas component production over diversified conglomerates with diluted clinical environment focus. Monitor CDSCO medical device registration enforcement consistency across Indian states as inflection indicator for emerging market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR classification as Class I medical devices eliminates uncertified competitors from German federal tenders. |
| Hospital System Partnership | Group purchasing organization consolidation compresses supplier lists toward manufacturers with captive component production. |
| Software Companion Development | HL7 FHIR-compatible data ports satisfy US academic medical center clinical engineering specifications. |
| Backward Integration into Gas Terminals | Captive valve component production insulates margins from European supply concentration in Bavaria and northern Italy. |
| Modular Retrofit Platform Launch | Clip-on overlay systems address aging hospital infrastructure in NHS Greater Manchester and West Midlands renovation corridors. |
Research Approach
The analysis maps metal panel, composite panel, wood panel, and plastic panel sub-sectors, each validated through hospital procurement managers, biomedical engineers, group purchasing organization contract directors, and architectural specification consultants. Primary interviews with clinical engineering departments and facilities managers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, NHS procurement records, and hospital construction pipeline data. Bottom-up installation volume estimates triangulate against top-down healthcare infrastructure expenditure benchmarks.
Consistency checks against external hospital construction databases and medical device registration filings validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include material construction type, installation configuration, application environment, and end-user procurement channel. CAGRs derive from installation run-rate analysis and replacement cycle assumptions, with aluminum price trajectory and antimicrobial coating adoption curves as key forecast inputs.
Material uncertainties — aluminum commodity volatility, EU MDR enforcement intensity variations, and Indian state-level CDSCO registration timeline divergence — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding hospital modernization program continuity and infection-control specification migration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
United Kingdom Mattress Market
Bedroom Furniture
Australia Mattress Market
Bedroom Furniture
Germany Mattress Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Malaysia Mattress Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
Bed Wedge Market