
 Bed Slats Market | 2026-2036
Bed Slats Market Size, Share, and Industry Trends Forecast 2026-2036
Bed Slats Market Insights
The gap between premium ergonomic slat systems and commodity flat-wood replacements is repositioning procurement priorities across the bedding supply chain. IKEA leverages its captive flat-pack logistics network to dominate cost-engineered flexible slat volumes in Europe. Hill-Rom sustains clinical-grade adjustable slat development for healthcare facilities through in-house production of motorized support frames. Brother Furniture anchors Asian export competitiveness with laminated birch slat specialization for Japanese hospitality buyers.
Bed slats are load-distributing support members installed between bed frames and mattresses, typically manufactured from kiln-dried hardwood, cold-rolled steel, or glass-reinforced polymer composites with center-to-center spacing of 50–75 millimeters to prevent mattress sagging and extend foam core longevity. Wood material segments retain the largest volume share but face margin compression from volatile lumber tariffs, while metal slat categories are gaining traction in commercial hospitality specifications for fire-code compliance and extended duty cycles. Flexible slat systems command premium positioning in European markets through differentiated zone-density engineering that adapts to sleeper body mass distribution.
California's Bureau of Electronic and Appliance Repair enforces TB 117-2013 smolder resistance standards that shape foam-slatted bed construction for US residential and hospitality channels, while REACH restrictions on formaldehyde emissions in laminated wood products constrain European supply chain chemistry choices. China's GB/T 3324 national standard for wooden furniture establishes minimum slat thickness and fastener pull-out strength for domestic retail and export certification. Stakeholders must monitor evolving flammability test protocols and bio-based composite material qualifications as regulatory divergence between North American and European frameworks intensifies compliance complexity for multinational suppliers.
Market Dynamics
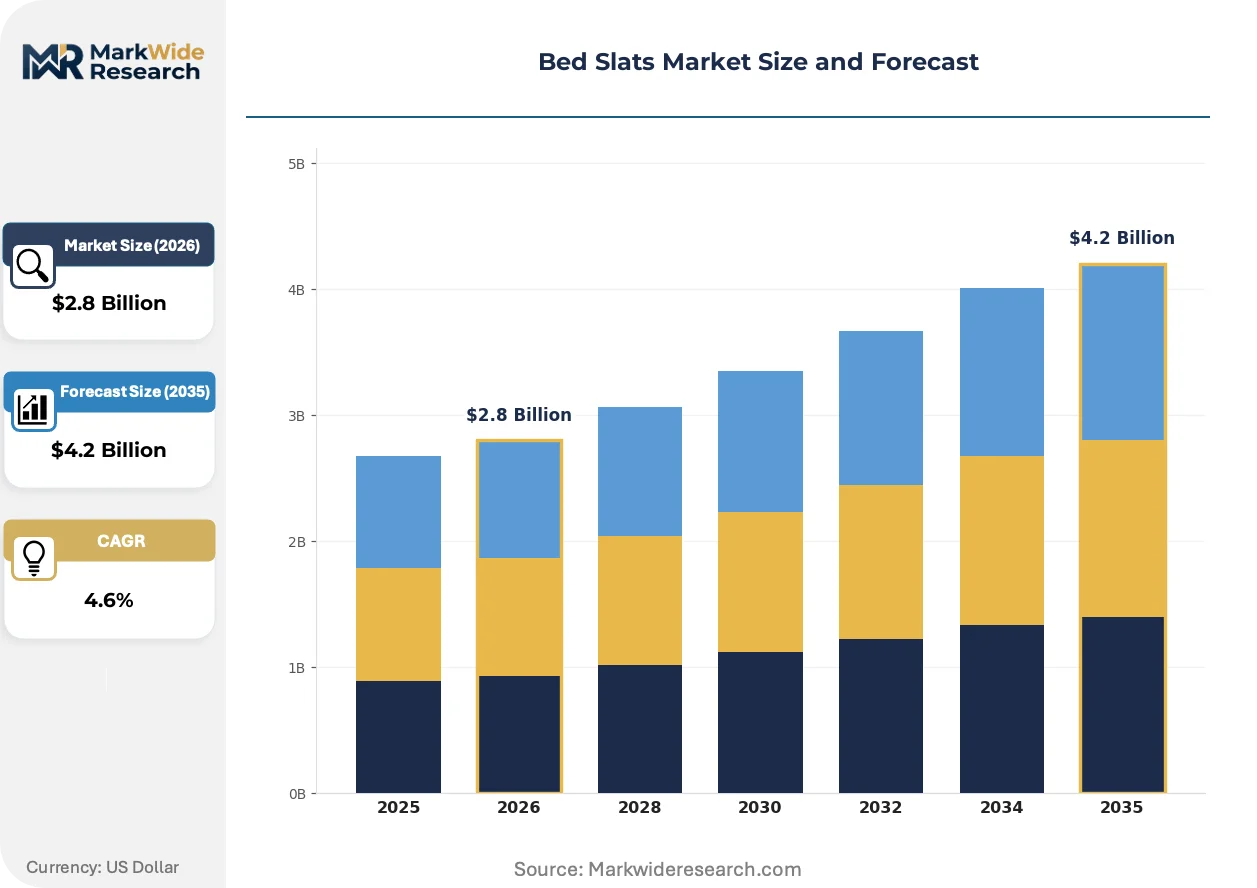
The bed slats market is restructuring around compliance-driven material substitution as TB 117-2013 and REACH force hospitality buyers toward fire-resistant metal and low-emission laminated systems, compressing margins on conventional kiln-dried hardwood while elevating certified composite specifications.
Growth Catalysts
- TB 117-2013 Enforcement:California's smolder resistance mandate compels US hospitality chains to replace wood slats with steel or intumescent-coated systems, generating replacement demand across 50,000-plus hotel properties.
- REACH Formaldehyde Limits:ECHA restrictions on laminated wood emissions redirect European procurement toward certified birch and beech slat suppliers with third-party E1/E0 validation.
- Ergonomic Zone Engineering:Flexible slat systems with variable tension zones penetrate German and Austrian residential markets as orthopedic mattress brands bundle differentiated support frames.
Market Restraints
- Lumber Tariff Volatility:US Section 301 duties on Chinese hardwood plywood spike input costs for flat-wood slat assemblers dependent on imported birch cores.
- Dongguan Supply Concentration:China's mass-manufacturing hub around Guangdong province concentrates 60-plus percent of Asian export capacity, exposing buyers to single-region logistics disruption.
- Steel Price Cyclicality:Cold-rolled coil fluctuations compress metal slat margins during commodity upswings, deterring capital investment in automated roll-forming lines.
Strategic Opportunities
- Indian Hospitality Buildout:Marriott and IHG expansion into tier-2 Indian cities creates demand for fire-code metal slats as BIS certification requirements tighten for commercial lodging.
- GB/T 3324 Export Certification:China's national furniture standard enables qualified domestic slat producers to bypass redundant testing for Japanese and Korean hospitality procurement.
- Glass-Reinforced Polymer Convergence:Pultruded composite slats combining thermoset resin with fiberglass roving offer corrosion resistance for coastal resort applications in Florida and Southeast Asia.
Industry Challenges
- Dual Certification Timelines:Simultaneous TB 117-2013 and REACH compliance testing extends product launch cycles by 8-14 months for multinational slat suppliers.
- Zone-Density Engineering Talent:Flexible slat system design requires specialized biomechanical modeling capabilities scarce outside German and Swiss technical institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bed Slats Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Metal, Plastic, Bamboo, Composite, Aluminum Product Type: Fixed Slats, Flexible Slats, Adjustable Slats, Folding Slats, Curved Slats End User: Furniture Manufacturers, Bedding Retailers, Hospitality Providers, Healthcare Facilities, Residential Consumers Distribution Channel: Online Retail, Specialty Stores, Wholesale Suppliers, Direct Sales, Home Improvement Centers |
| Companies Covered | Ashley Furniture, IKEA, Rooms To Go, Brother Furniture, Master & Zest, Qumei, Landbond, Hill-Rom, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bed Slats Market Trends and Innovations
Material science advances and procurement digitization are compressing traditional supply chain layers while elevating performance-certified products. Three developments dominate current investment patterns.
Glass-reinforced polymer composite slats are absorbing market share in coastal hospitality and healthcare applications where moisture corrosion degrades steel and wood alternatives. Marriott's Caribbean and Florida properties specify pultruded slats for exterior-facing guest rooms with humidity exposure. The technology is absorbing premium positioning from stainless steel in salt-air environments while commanding 40-60 percent price multiples over cold-rolled equivalents.
REACH Annex XVII restrictions on formaldehyde-releasing agents in laminated wood products are forcing European slat manufacturers to reformulate adhesives and migrate toward phenol-resorcinol or bio-based soy systems. German precision-engineered slat clusters face 12-18 month requalification cycles for existing product lines. Hospitality procurement teams in France and the Netherlands now require E1-plus or E0 emission certifications as standard bid prerequisites, filtering out uncertified Asian suppliers.
Direct-to-facility procurement platforms are disintermediating traditional furniture distributor networks for large hospitality chains. IHG and Hilton corporate sourcing teams now issue slat specifications directly to certified manufacturers in Dongguan and Bavaria, compressing margin layers previously captured by regional bedding distributors. This channel shift is most visible in North American limited-service hotel construction where standardized room packages enable bulk slat procurement without intermediary specification consulting.
Bed Slats Market Segmentation
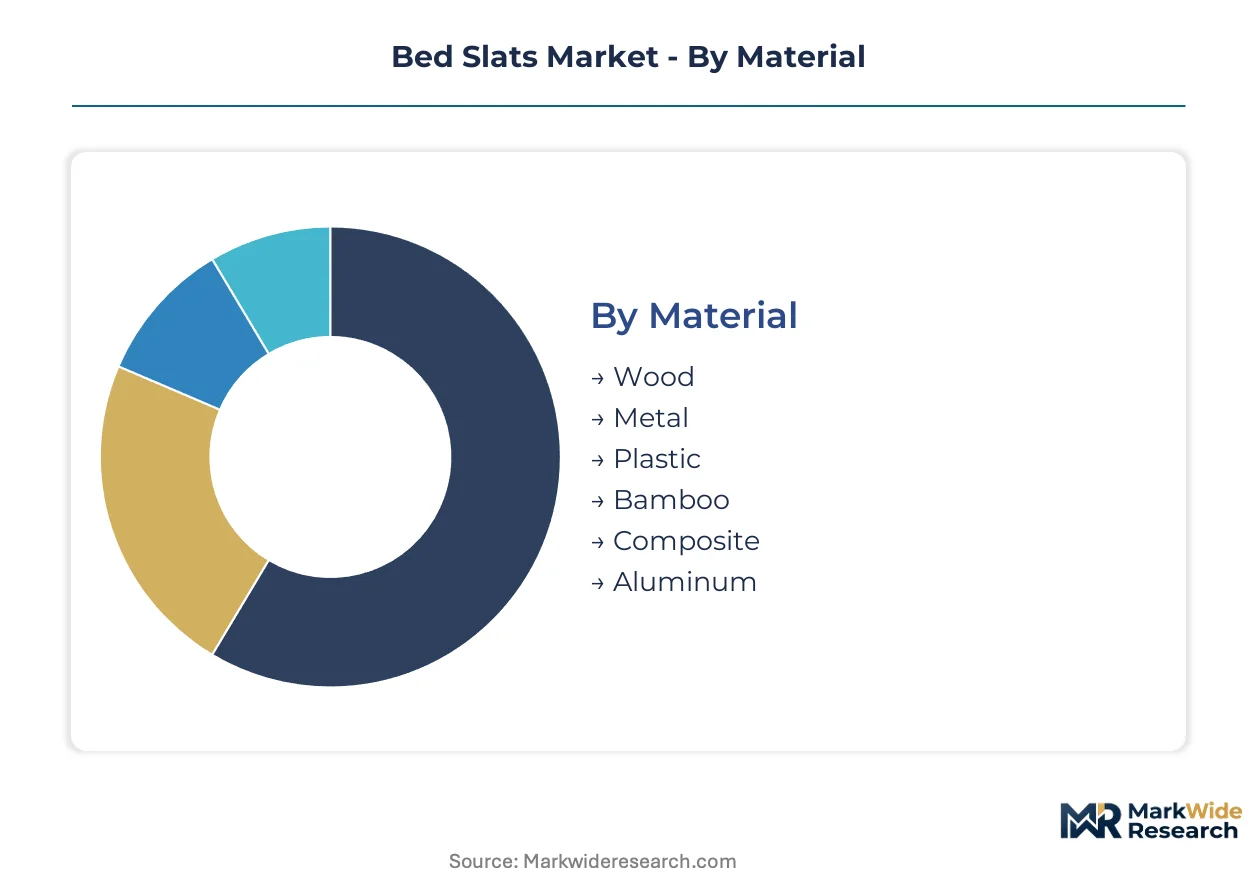
Bed slat procurement varies sharply by integration depth. Some segments supply standalone replacement components for aftermarket repair; others embed into complete bed systems sold through furniture OEMs. Understanding this layering exposes where margin capture concentrates and which channels face disintermediation pressure from direct sourcing platforms.
Material:
Standalone wood and bamboo slats dominate aftermarket replacement channels, while metal and composite systems increasingly embed into hospitality procurement contracts requiring fire-code certification.
- Wood:Kiln-dried hardwood slats—typically beech, birch, or oak—remain the default specification for European residential furniture OEMs. German precision-engineered slat clusters in Bavaria and Baden-Württemberg supply calibrated moisture-content boards with E1 emission certifications under REACH Annex XVII. Lumber tariff volatility from US Section 301 duties compresses margins for flat-wood assemblers dependent on imported birch cores.
- Metal:Cold-rolled steel slats with powder-coated or zinc-plated finishes embed into commercial hospitality specifications demanding TB 117-2013 smolder resistance compliance. Marriott and IHG properties across California and Florida specify steel systems for extended duty cycles and reduced replacement frequency.
- Plastic:Injection-molded polypropylene slats serve budget residential replacement markets with limited load-bearing requirements.
- Bamboo:Laminated bamboo strips target eco-positioned retail channels in Japan and South Korea with JIS-certified sustainable sourcing claims.
- Composite:Glass-reinforced polymer pultrusions combine thermoset resin with fiberglass roving for corrosion-resistant coastal hospitality applications in Florida and Southeast Asia.
- Aluminum:Extruded aluminum slats with anodized finishes penetrate premium adjustable bed frames where weight reduction justifies cost multiples.
Wood leads volumes today; composite is gaining share fastest in salt-air hospitality environments.
Product Type:
Cost tier stratification separates commodity fixed systems from engineered flexible and adjustable platforms commanding premium positioning.
- Fixed Slats:Rigid parallel boards spaced at 50-75 millimeter centers deliver basic mattress support for entry-level bed frames. Chinese mass-manufacturing hubs around Dongguan produce fixed slat bundles at scale for IKEA flat-pack distribution across Europe and North America.
- Flexible Slats:Zone-density engineered systems with variable tension elements adapt to sleeper body mass distribution. German orthopedic mattress brands bundle differentiated support frames with flexible slat technology developed through biomechanical modeling capabilities concentrated in Swiss and German technical institutes.
- Adjustable Slats:Motorized support frames with programmable positioning embed into clinical-grade healthcare specifications. Hill-Rom sustains in-house production for hospital and long-term care facility contracts requiring precise elevation control.
- Folding Slats:Hinged configurations enable compact shipping for e-commerce direct-to-consumer channels with limited last-mile logistics capacity.
- Curved Slats:Arched profiles provide progressive spring response for specialty mattress constructions in Austrian and Czech residential markets.
Fixed slats anchor volume economics; flexible systems command the steepest expansion trajectory in European ergonomic positioning.
End User:
Customer type determines specification intensity, with hospitality and healthcare buyers imposing certification burdens that residential channels bypass.
- Furniture Manufacturers:OEM procurement of slat systems for integrated bed frame assembly concentrates in Poland, Vietnam, and China's Guangdong province. These buyers demand consistent dimensional tolerance for automated assembly lines.
- Bedding Retailers:Specialty mattress stores source replacement slat sets for aftermarket accessory sales, with Brother Furniture anchoring Asian export competitiveness through laminated birch specialization for Japanese hospitality buyers.
- Hospitality Providers:Hotel chains issue direct specifications to certified manufacturers, bypassing traditional distributor networks. IHG and Hilton corporate sourcing teams now engage Dongguan and Bavarian producers directly for standardized limited-service room packages.
- Healthcare Facilities:Clinical-grade adjustable slat development requires motorized support frame engineering with FDA-registered component traceability for US hospital procurement.
- Residential Consumers:Online retail and home improvement center purchases drive replacement demand for degraded or broken slat systems in existing bed frames.
Hospitality procurement channels are expanding most quickly as direct-to-facility platforms compress traditional distributor margins.
Distribution Channel:
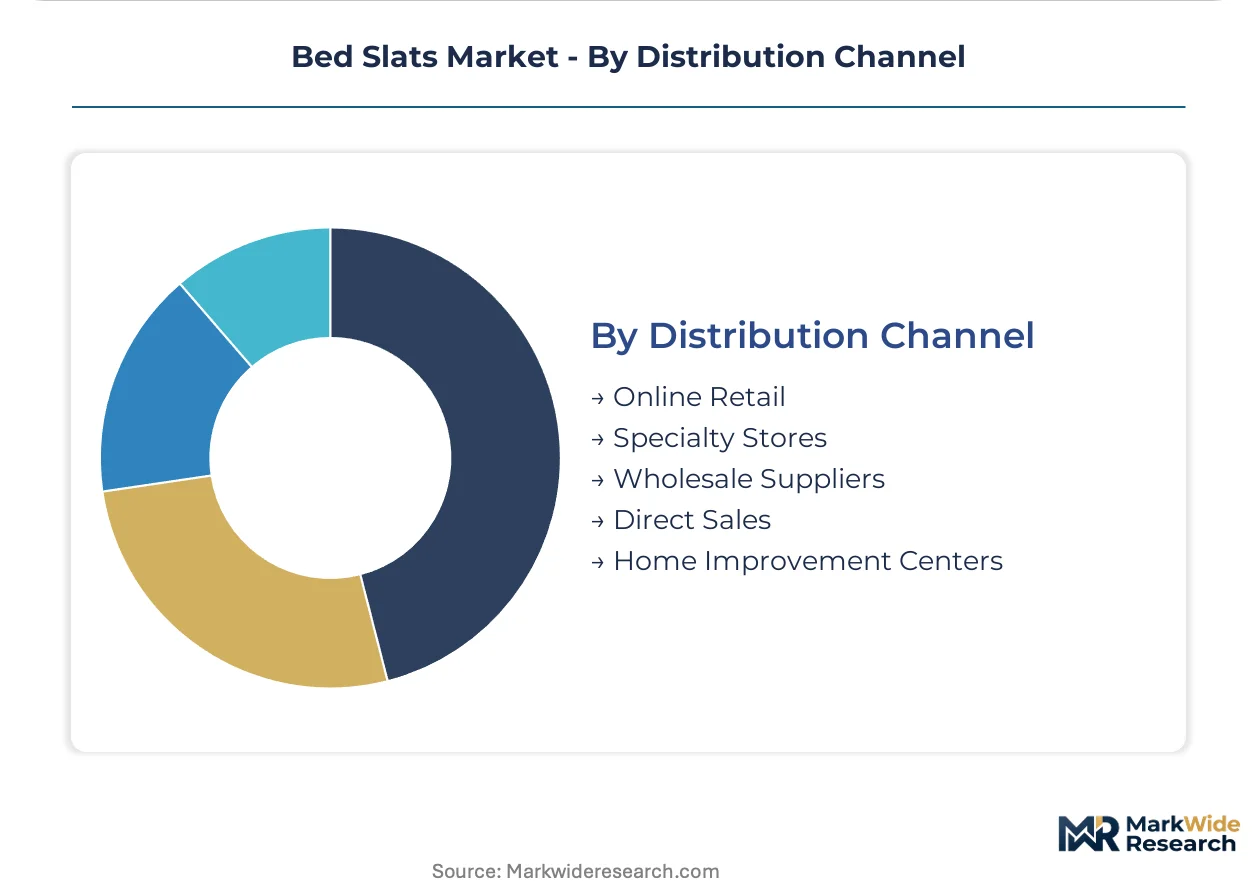
Volume concentration in wholesale and direct sales channels is displacing specialty store intermediaries for large-account hospitality contracts.
- Online Retail:Amazon and Wayfair platforms aggregate replacement slat demand from residential consumers seeking compatible dimensions for existing bed frames, with SKU proliferation matching legacy furniture specifications.
- Specialty Stores:Independent bedding retailers maintain slat accessory inventory for walk-in replacement demand, though foot traffic erosion compresses this channel's relevance.
- Wholesale Suppliers:Furniture OEM procurement through regional distributors persists for mid-tier manufacturers lacking direct import capabilities.
- Direct Sales:Corporate sourcing teams at major hospitality chains engage certified manufacturers directly, eliminating margin layers previously captured by specification consultants.
- Home Improvement Centers:Lowe's and Home Depot stock standardized slat sets for DIY bed repair and platform bed construction projects.
Direct sales channels are climbing the fastest as procurement digitization disintermediates traditional furniture distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium ergonomic slat engineering while China anchors mass-manufacturing scale, revealing divergent national specializations within the bed slats supply base.
United States
California's TB 117-2013 smolder resistance mandate compels hospitality chains across 50,000-plus hotel properties to replace wood slats with steel or intumescent-coated systems. The EPA coordinates with state fire marshals on evolving flammability protocols. Manufacturing concentrates in North Carolina furniture corridors and Midwest metal-stamping centers serving commercial lodging procurement.
Germany
Orthopedic mattress brands bundle differentiated support frames with flexible slat technology developed through biomechanical modeling capabilities. ECHA REACH Annex XVII restrictions on formaldehyde emissions redirect procurement toward certified birch and beech suppliers with third-party E1/E0 validation. Precision-engineered slat clusters in Bavaria and Baden-Württemberg supply calibrated moisture-content boards for European OEM assembly lines.
China
Dongguan mass-manufacturing hubs around Guangdong province concentrate 60-plus percent of Asian export capacity for flat-pack distribution. GB/T 3324 national standards establish minimum slat thickness and fastener pull-out strength for domestic retail and export certification. Qualified producers leverage this standard to bypass redundant testing for Japanese and Korean hospitality procurement.
Japan
Laminated bamboo strips target eco-positioned retail channels with JIS-certified sustainable sourcing claims. METI oversees national quality frameworks for wooden furniture components. Osaka-based bedding distributors specialize in replacement slat sets for compact residential spaces demanding space-efficient folding configurations.
India
Marriott and IHG expansion into tier-2 cities creates demand for fire-code metal slats as BIS certification requirements tighten for commercial lodging. The central bank's infrastructure lending priorities indirectly support hospitality construction financing. Maharashtra and Karnataka industrial zones attract slat fabricators serving domestic furniture OEMs and export channels to Middle Eastern markets.
Bed Slats Market Competitive Landscape
Top-tier vendors anchor premium ergonomic and clinical-grade segments, while mid-scale fabricators compete on flat-pack logistics and mass-manufacturing efficiency. The vendor base stratifies across three functional tiers: captive retail networks, hospitality-direct specialists, and healthcare-integrated manufacturers. Two dominant competitive moves reshape positioning: direct-to-facility procurement platforms disintermediating traditional distributors, and adhesive reformulation investments responding to REACH formaldehyde limits.
Among Swedish-origin retail conglomerates, IKEA exemplifies scale-driven flat-pack logistics dominance through captive distribution networks. Hill-Rom and Stryker occupy positions within the clinical-grade adjustable slat tier, representing healthcare-integrated manufacturing archetypes with in-house motorized support frame production. Brother Furniture anchors Asian export competitiveness, exemplifying laminated wood specialization for Japanese hospitality buyers seeking JIS-certified supply chains.
| Leading Market Players |
|---|
| Ashley Furniture |
| IKEA |
| Rooms To Go |
| Brother Furniture |
| Master & Zest |
| Qumei |
| Landbond |
| Hill-Rom |
| Stryker |
| Others |
Pricing and Supply Chain Analysis
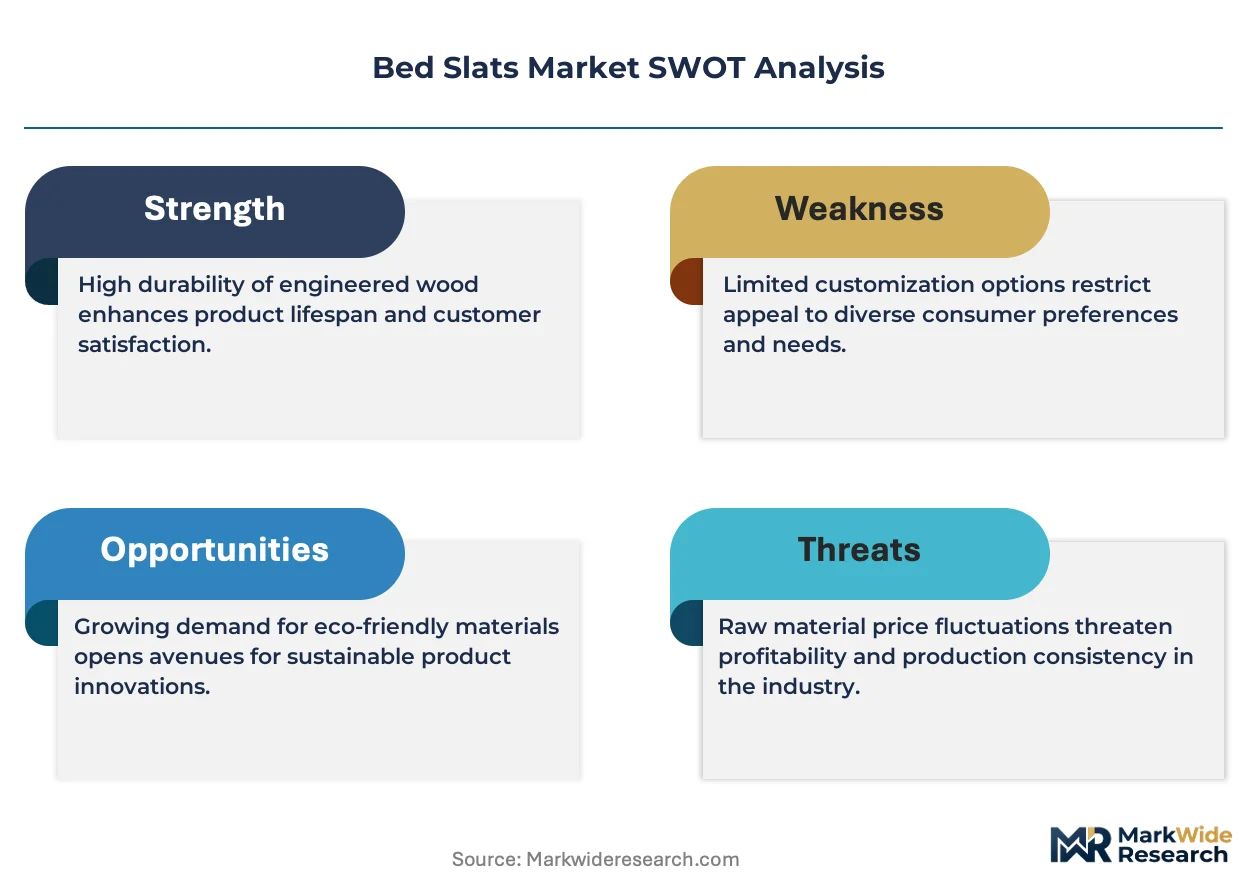
REACH Annex XVII formaldehyde restrictions gate qualified supply for European hospitality procurement while elevating E1-certified birch slats to premium-tier pricing access unavailable to uncertified Asian exporters. California's TB 117-2013 enforcement simultaneously compresses margins on conventional kiln-dried hardwood by mandating steel or intumescent-coated alternatives across commercial lodging properties.
Pricing Analysis
Capacity additions in Vietnam and Poland are reshaping price floors for fixed slat bundles, intensifying cost compression in the standard tier. Three-tier pricing structure across premium ergonomic, certified commercial, and economy flat-pack levels stratifies the market, with REACH E1 validation and TB 117-2013 compliance serving as the primary price differentiation drivers. Pricing pressure stems from US Section 301 lumber duties on Chinese birch cores, squeezing flat-wood assemblers dependent on imported inputs. Furniture OEMs exhibit highest price sensitivity in volume procurement, while hospitality chains prioritize certification compliance over unit cost.
Supply Chain Analysis
Freight cost volatility from Red Sea disruptions and transpacific rate spikes is compressing margins on Dongguan-exported flat-pack bundles destined for European retail channels. Supply concentrates in China's Guangdong province, Germany's Bavarian precision clusters, and Vietnam's emerging furniture corridors, with raw material dependencies spanning Baltic birch plywood, cold-rolled steel coil, and phenol-resorcinol adhesive formulations. Single-region concentration risk in Dongguan exposes buyers to logistics disruption from port congestion or regulatory inspection backlogs. Distribution runs through direct-to-facility procurement platforms for hospitality chains, bypassing traditional bedding distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant European precision manufacturing and scale-driven Asian export production, with formaldehyde certification costs in Germany running substantially above uncertified Chinese alternatives.
For Market Incumbents: Extend E0 adhesive reformulation investments to capture hospitality procurement contracts as French and Dutch buyers mandate emission certifications. Deepen backward integration into phenol-resorcinol resin production to offset volatile adhesive input costs from specialty chemical suppliers. Defend against direct-sourcing platform disintermediation by embedding specification consulting into slat system bundles. For New Entrants and Emerging Players: Hospitality procurement teams represent the most penetrable channel entry point, as IHG and Hilton corporate sourcing seeks secondary qualified suppliers beyond incumbent Dongguan and Bavarian producers. Target India's tier-2 city hospitality buildout where BIS certification requirements are tightening but qualified domestic capacity remains scarce. Pursue GB/T 3324 export certification to bypass redundant testing for Japanese and Korean procurement channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Vietnamese flat-pack fabricators lacking direct hospitality relationships but possessing dimensional tolerance capabilities for OEM assembly lines. Long-term viability over the projection horizon hinges on adhesive chemistry transition costs and coastal composite slat adoption curves. Monitor glass-reinforced polymer pultrusion capacity buildouts in Florida and Southeast Asia as inflection indicators for corrosion-resistant segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| REACH E0 Adhesive Reformulation | German precision slat clusters face 12-18 month requalification cycles for emission-compliant product lines. |
| Direct-to-Facility Procurement Platform | IHG and Hilton sourcing teams now engage certified Dongguan and Bavarian manufacturers directly. |
| Glass-Reinforced Polymer Capacity Buildout | Marriott's Caribbean properties specify pultruded slats for humidity-exposed exterior-facing guest rooms. |
| GB/T 3324 Export Certification | Qualified Chinese producers bypass redundant testing for Japanese and Korean hospitality procurement. |
| Backward Integration into Resin Production | Phenol-resorcinol adhesive captive supply offsets specialty chemical input volatility for European manufacturers. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's hospitality procurement hubs and furniture manufacturing corridors. The analysis combines structured interviews with hotel chain sourcing directors, bedding OEM procurement managers, German orthopedic mattress brand technical directors, and Chinese flat-pack export coordinators with secondary validation from customs trade databases, EPA and ECHA regulatory filings, and hospital procurement contract disclosures. Bottom-up volume estimates from slat system shipments triangulate against top-down furniture industry consumption models.
Rate-of-change decomposition separates volume growth from pricing dynamics across material substitution trends and regulatory compliance cost pass-through. Segmentation dimensions modeled include material type, product architecture, end-user category, and distribution channel structure alongside certification tier and regional regulatory cluster. CAGRs derive from installed base replacement cycles, hospitality construction pipelines, and healthcare facility upgrade spending patterns. Forecast inputs incorporate steel price cyclicality, lumber tariff trajectories, and REACH Annex XVII enforcement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to adhesive chemistry transition costs, composite material qualification timelines, and logistics route disruptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and hospitality construction financing availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Germany Mattress Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
Bunk Beds Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
Malaysia Mattress Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Australia Mattress Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Luxury Mattress Market
Bedroom Furniture
Latin America Mattress Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Global Cervical Pillows Market