
 North America Wall Bed Market | 2026-2036
North America Wall Bed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wall Bed Market Analytics
Canadian panel producers is rebalancing output toward engineered wood substrates suited to vertical bed frames. Wilding Wallbeds leverages captive hardwood sourcing to control material consistency across its Rocky Mountain manufacturing footprint. Resource Furniture sustains design-led positioning through Italian-engineered hardware systems adapted for North American ceiling heights. Murphy Wall-Bed Hardware Inc. anchors the upstream supply tier through proprietary piston-lift mechanisms distributed to regional assemblers.
A wall bed is a sleep system hinged at one end for vertical storage against a wall or within a cabinet enclosure, typically incorporating counterbalanced lift mechanisms rated for 1,000 to 3,000 cycle lifespans and requiring minimum 12-inch depth clearances. The product serves residential and commercial users seeking to reclaim floor area in spaces below 800 square feet. Murphy beds occupy the premium tier where solid wood construction and custom millwork command higher margin pools, while sofa beds expand fastest among urban renters prioritizing dual-function seating. Metal framing segments compete on price in institutional procurement channels where durability specifications override aesthetic considerations.
The Consumer Product Safety Commission governs tip-over stability requirements for freestanding and wall-mounted furniture, directly influencing bed frame anchoring hardware design and installation protocols. California's Department of Public Health maintains Section 01350 indoor air quality standards that limit VOC off-gassing from composite substrates used in cabinet enclosures. The EPA's TSCA Title VI formaldehyde rules further constrain particle board sourcing options for manufacturers serving health-conscious residential buyers. Stakeholders must weigh certification costs against channel access as building codes in major metropolitan areas tighten space-efficiency mandates for new construction.
Market Dynamics
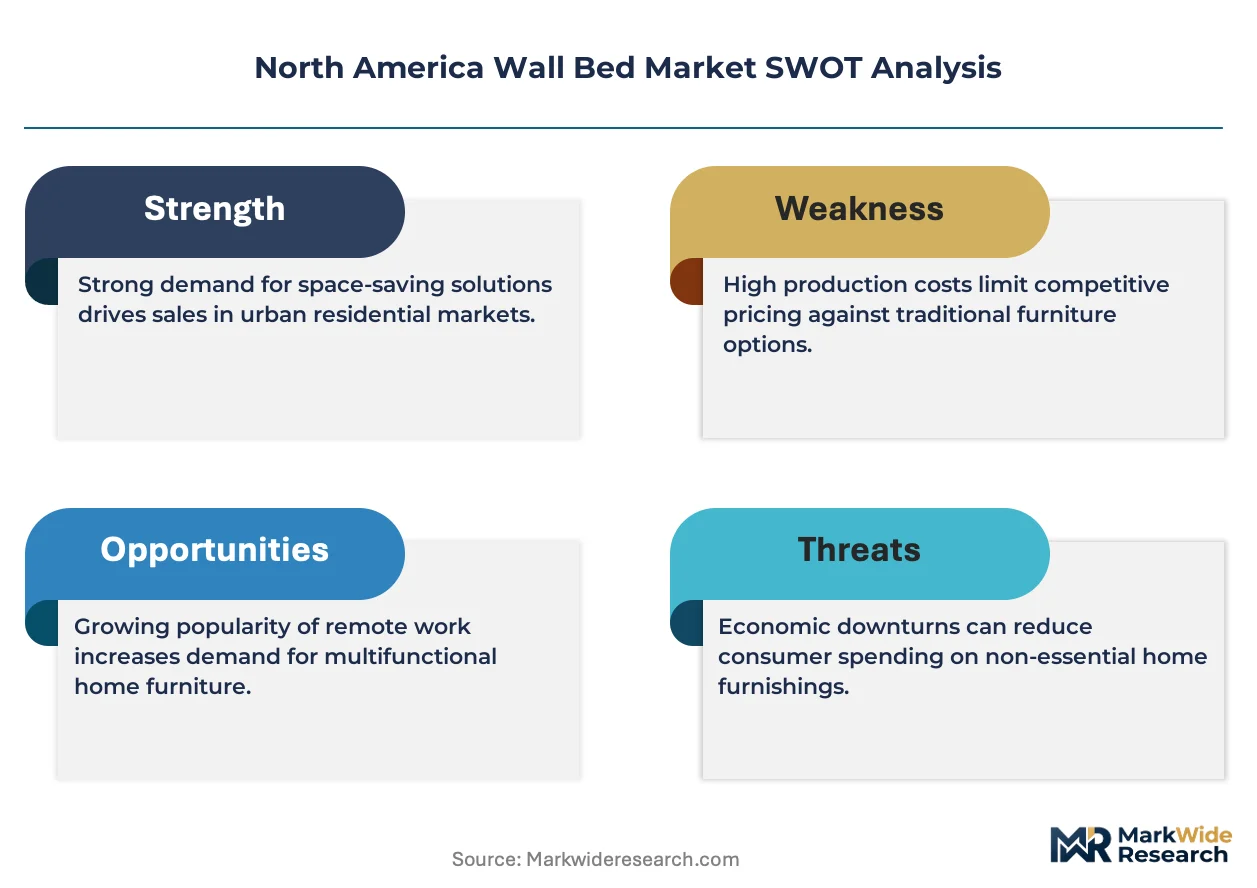
EPA's TSCA Title VI formaldehyde emission standards are forcing substrate substitutions across cabinet enclosures, while multifamily developers in California, Texas, and Florida accelerate space-efficient unit specifications. This regulatory-supply tension is compressing margins for particleboard-dependent assemblers and rewarding captive hardwood sourcing.
Growth Catalysts
- California Section 01350 indoor air quality mandates:Low-VOC certification requirements from the California Department of Public Health are pulling engineered wood demand toward compliant substrates, opening premium positioning for certified manufacturers.
- Urban residential densification:Toronto and Vancouver developers are expanding sub-600 square foot inventory, embedding wall bed specifications directly into architectural drawings rather than aftermarket installation.
- Piston-lift mechanism reliability:Hardware rated for 3,000-cycle lifespans is reducing replacement frequency and expanding commercial hospitality procurement in extended-stay properties.
Market Restraints
- Hardwood input cost volatility:Rocky Mountain lumber supply fluctuations are pressuring solid-wood premium tier margins, forcing price pass-through to residential buyers.
- Formaldehyde compliance friction:TSCA Title VI certification timelines extend particleboard sourcing cycles, constraining rapid SKU expansion for mid-market assemblers.
- Sofa bed substitution threat:Dual-function seating alternatives are capturing urban renter segments prioritizing immediate floor-space flexibility over dedicated sleep systems.
Strategic Opportunities
- Texas and Florida multifamily pipelines:Sun Belt metro construction permits are outpacing national averages, creating concentrated demand clusters for developer-direct procurement.
- Smart home convergence:Integration of motorized lift systems with IoT controls is unifying sleep furniture with connected home ecosystems, commanding specification in luxury residential.
- Institutional procurement channels:University housing and military barracks are formalizing durability specifications that favor metal-framed wall beds over traditional dormitory furniture.
Industry Challenges
- Installation skill scarcity:CPSC tip-over anchoring protocols require certified technician deployment, limiting scalable direct-to-consumer fulfillment.
- Cross-border substrate certification:Canadian panel producers must dual-certify under EPA TSCA Title VI and domestic standards, extending inventory holding periods.
- Hardware-software integration complexity:Motorized mechanisms with app-based controls are introducing firmware update liabilities unfamiliar to traditional furniture assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wall Bed Market |
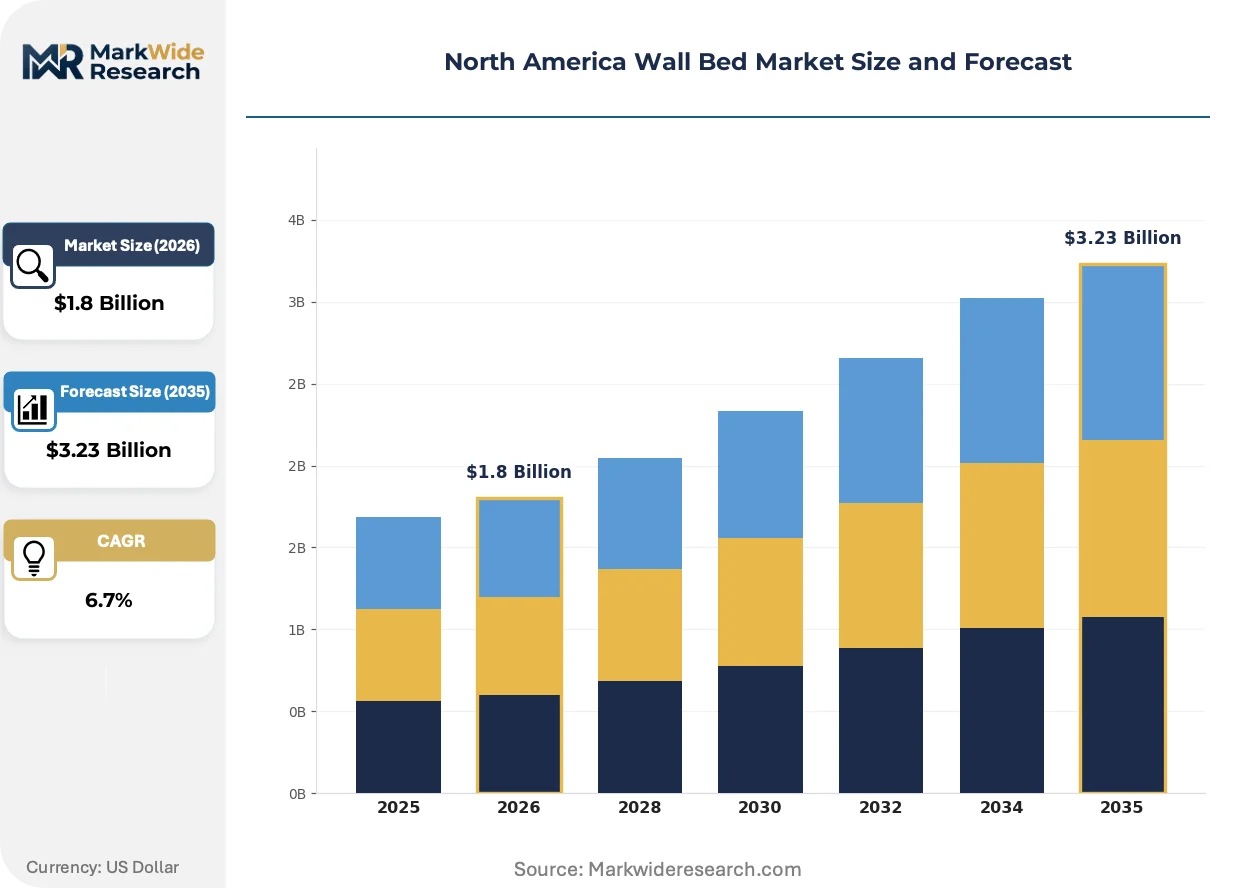
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Murphy Beds, Folding Beds, Sofa Beds, Convertible Beds Material: Wood, Metal, Upholstered, Particle Board End User: Residential, Commercial, Hospitality, Institutions Distribution Channel: Online Retail, Offline Retail, Showrooms, Direct Sales |
| Companies Covered | Wall Beds Manufacturing Inc., The Bedder Way Co., Wilding Wallbeds, Resource Furniture, Murphy Beds of San Diego, Murphy Wall-Bed Hardware Inc., Twin Cities Closet Co., Murphy Bed Depot, Monarch Murphy Beds, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wall Bed Market Evolving Landscape
Wall bed engineering is converging around three vectors: hardware durability standards, regulatory material compliance, and embedded smart functionality. These shifts are compressing the supplier base toward vertically integrated manufacturers.
Italian-engineered piston-lift systems adapted for North American ceiling heights are unifying premium residential specifications with commercial hospitality durability requirements. Extended-stay hotel operators in California and Texas are specifying these mechanisms for 10-year replacement cycles rather than traditional 5-year furniture refresh schedules. This unifying hardware standard is compressing regional supplier fragmentation toward hardware-agnostic assemblers.
The EPA's TSCA Title VI formaldehyde emission rules are constraining particleboard sourcing to certified mills in the US and Canada. Manufacturers serving health-conscious residential buyers are shifting specification sheets toward low-VOC engineered wood substrates. California's Department of Public Health Section 01350 standards are extending this pressure to cabinet enclosure adhesives and surface finishes.
Urban renters in Toronto and Vancouver are prioritizing dual-function furniture over dedicated sleep systems, compressing traditional wall bed demand into owner-occupied compact housing segments. This behavioral pivot is fragmenting distribution: big-box retail captures price-sensitive renters while direct-to-developer channels serve condominium pre-sales. The shift is most visible in Vancouver's Yaletown and Toronto's King West micro-condominium towers where developer-specified millwork now dominates.
North America Wall Bed Market Segmentation
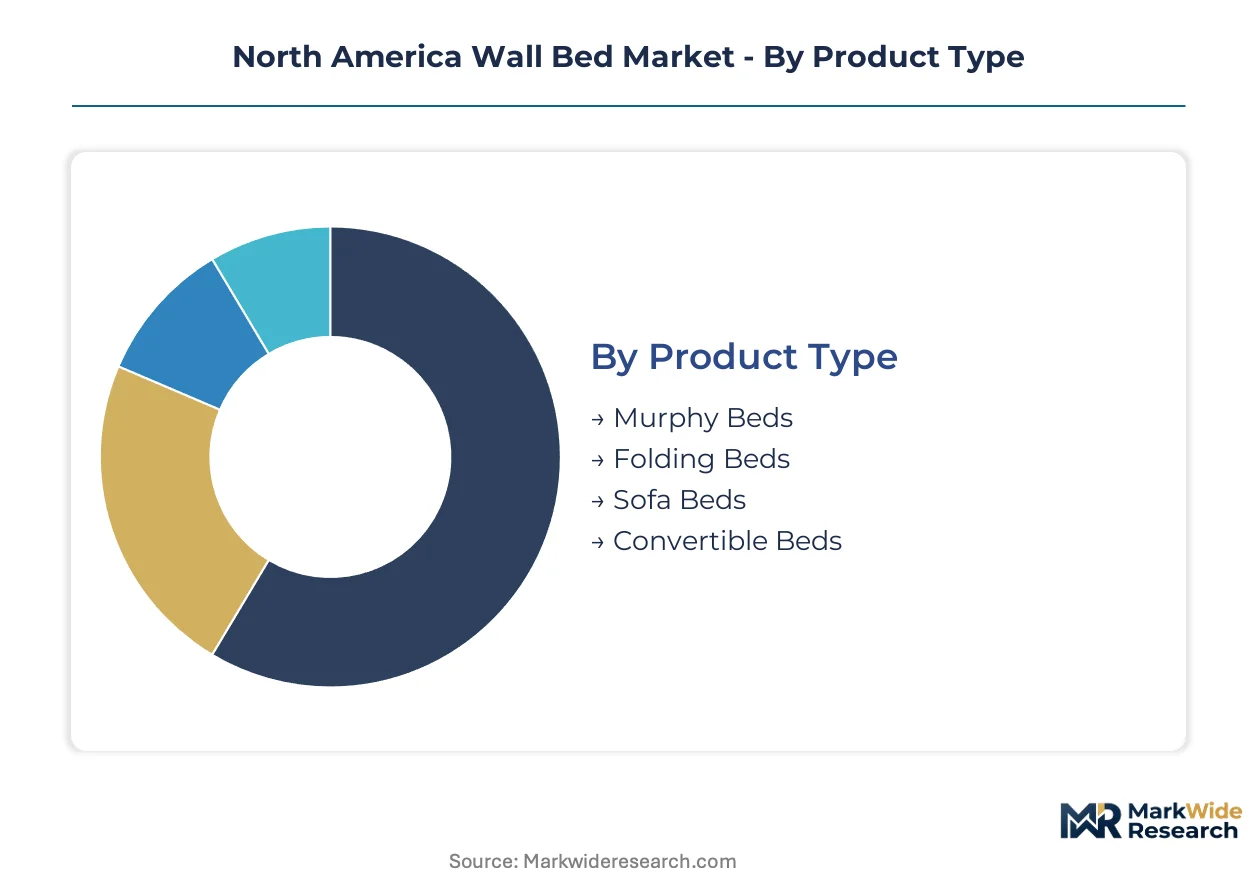
Wall bed demand fragments across construction methods, material substrates, and procurement channels. Each axis carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Piston-lift engineering and counterbalance mechanics define performance tiers across sleep system categories.
- Murphy Beds:Vertical-hinge systems with 1,000 to 3,000 cycle-rated hardware dominate owner-occupied compact housing in California and Texas. Custom millwork and solid wood construction command premium positioning where developer specifications embed beds directly into architectural drawings.
- Sofa Beds:Dual-function seating alternatives capture urban renter segments in Toronto and Vancouver micro-condominiums. Immediate floor-space flexibility displaces dedicated sleep systems among tenants prioritizing mobility over permanent installation.
- Folding Beds:Collapsible metal frames serve institutional procurement channels where durability specifications override aesthetic considerations.
- Convertible Beds:Multi-position mechanisms integrate with modular furniture systems for extended-stay hospitality properties.
Murphy beds lead on scale; sofa beds lead on momentum.
Material:
Substrate selection determines VOC compliance exposure and cycle durability in commercial specifications.
- Wood:Solid hardwood construction anchors premium residential tiers where Rocky Mountain captive sourcing controls material consistency. Wilding Wallbeds leverages vertical supply chain control to buffer against lumber input volatility.
- Metal:Steel and aluminum framing competes on price in university housing and military barracks where institutional durability standards favor 10-year replacement cycles over aesthetic millwork.
- Upholstered:Fabric-wrapped surfaces integrate with soft goods retail channels for hospitality procurement seeking brand-coordinated room packages.
- Particle Board:Composite substrates face EPA TSCA Title VI certification friction that extends sourcing cycles for mid-market assemblers dependent on rapid SKU expansion.
Wood commands margin concentration; metal captures volume scale in institutional channels.
End User:
Occupancy patterns and ownership duration reshape specification requirements across deployment contexts.
- Residential:Owner-occupied compact housing in California, Texas, and Florida drives developer-direct procurement where space-efficiency mandates tighten building codes.
- Commercial:Extended-stay hotel operators in Texas specify Italian-engineered piston-lift systems for unified 10-year replacement schedules.
- Hospitality:Luxury residential convergence with connected home ecosystems commands motorized lift integration with IoT controls.
- Institutions:University housing formalizes metal-framed durability specifications that displace traditional dormitory furniture.
Residential anchors revenue concentration; hospitality posts the steepest expansion trajectory.
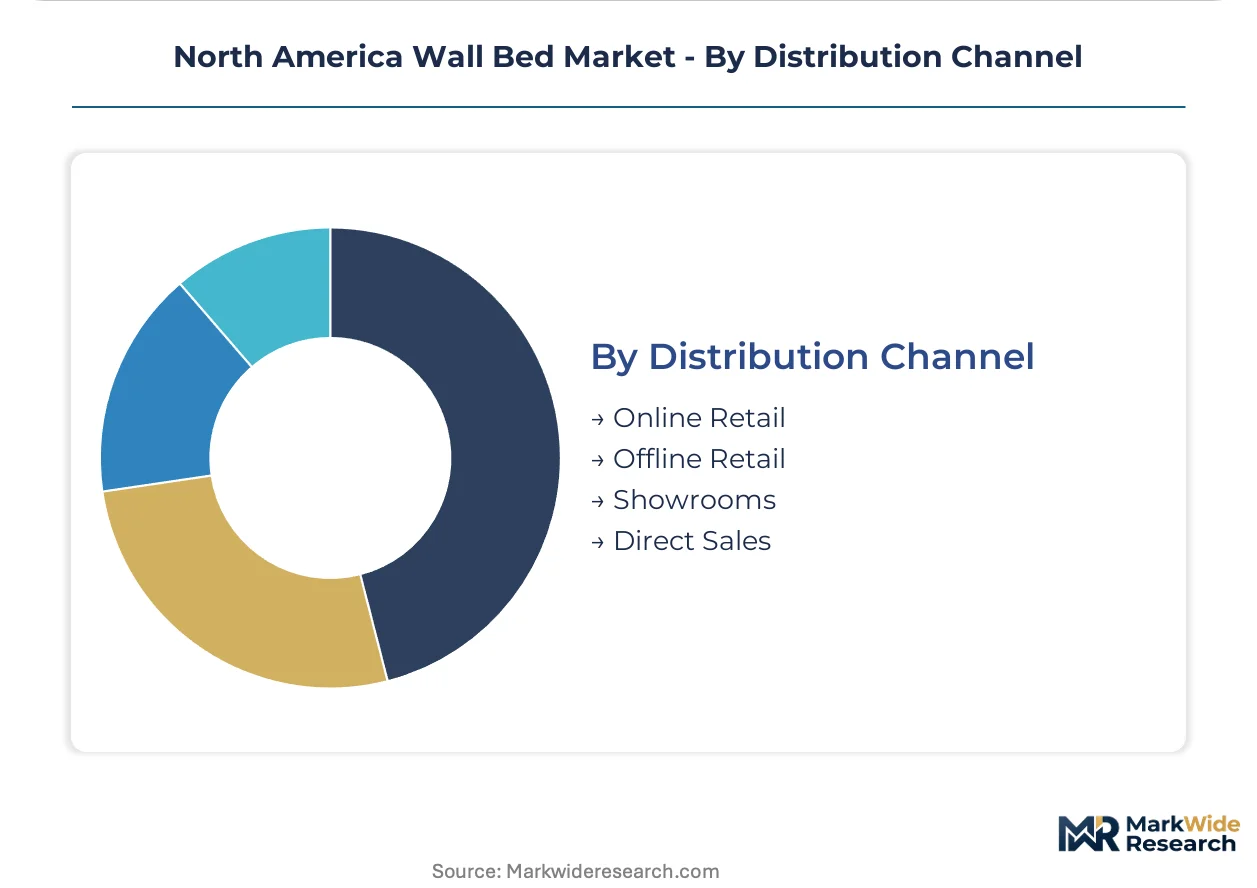
Distribution Channel:
Fulfillment complexity scales with installation certification requirements and customer touchpoint preferences.
- Online Retail:E-commerce penetration faces CPSC tip-over anchoring protocol constraints that limit scalable direct-to-consumer deployment without certified technician networks.
- Offline Retail:Big-box capture concentrates price-sensitive renter segments in Toronto and Vancouver where immediate purchase overrides custom specification.
- Showrooms:Design-led positioning through Italian-engineered hardware demonstrations sustains premium tier access for Resource Furniture and comparable specialists.
- Direct Sales:Developer-direct channels dominate Vancouver Yaletown and Toronto King West condominium pre-sales where architectural millwork integration precedes occupancy.
Direct sales lead on contract value; online retail faces installation friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are redistributing wall bed manufacturing capacity across North America. EPA TSCA Title VI certification timelines favor domestic panel producers over importers, while Canadian mills leverage dual-certification advantages to capture cross-border supply contracts.
United States
California's Department of Public Health Section 01350 standards are pulling engineered wood demand toward low-VOC substrates in the Los Angeles and San Francisco metropolitan corridors. The EPA's TSCA Title VI formaldehyde rules constrain particleboard sourcing to certified domestic mills. Texas multifamily construction in Houston and Dallas anchors Sun Belt demand for developer-direct procurement.
Canada
Toronto and Vancouver developers are embedding wall bed specifications directly into micro-condominium architectural drawings for sub-600 square foot inventory. Canadian panel producers must dual-certify under EPA TSCA Title VI and domestic standards, extending inventory cycles but securing cross-border market access. The Rocky Mountain manufacturing footprint around Calgary serves captive hardwood sourcing for premium residential tiers.
Mexico
Baja California and Chihuahua assembly operations are capturing contract manufacturing for US-branded wall bed distributors seeking tariff-advantaged production. Mexico's national standards body aligns composite wood certification with EPA thresholds to maintain export eligibility. Monterrey industrial parks are concentrating metal-framing capacity for institutional procurement channels serving university housing contracts.
North America Wall Bed Market Competitive Landscape
Rocky Mountain producers anchor the solid-wood premium tier; Great Lakes and Pacific specialists hold engineered substrate and hardware distribution positions. The supplier base concentrates around vertically integrated manufacturers with captive material sourcing and regional assemblers dependent on third-party lift mechanisms. Three archetypes dominate: hardwood-centric millwork houses, hardware-agnostic volume assemblers, and design-led import distributors. Competitive moves center on backward integration into substrate production and exclusive territory partnerships with multifamily developers.
Within the captive-sourcing archetype, Wilding Wallbeds exemplifies Rocky Mountain vertical control over material consistency. Resource Furniture occupies the design-import position through Italian-engineered hardware adaptation. Murphy Wall-Bed Hardware Inc. anchors the upstream supply tier through proprietary mechanism distribution to regional assemblers.
| Leading Market Players |
|---|
| Wall Beds Manufacturing Inc. |
| The Bedder Way Co. |
| Wilding Wallbeds |
| Resource Furniture |
| Murphy Beds of San Diego |
| Murphy Wall-Bed Hardware Inc. |
| Twin Cities Closet Co. |
| Murphy Bed Depot |
| Monarch Murphy Beds |
| Others |
Value Network & Pricing Analysis
Certified technician networks in the Rocky Mountain corridor anchor installation labor pools, and the wage differential between these specialized crews and general furniture assemblers in Mexico's Baja California industrial parks feeds a three-tier pricing spread across premium millwork, mid-market engineered substrates, and economy metal-framed units.
Pricing Analysis
Retailer markup layers absorb the CPSC certification burden for tip-over anchoring protocols, compressing margins for direct-to-consumer channels while rewarding developer-direct procurement with volume discounts. Price differentiation hinges on VOC certification grade under EPA TSCA Title VI and cycle-rated hardware tier. Cost compression in particleboard-dependent segments intensifies as dual-certification timelines extend inventory holding periods. Urban renters in Toronto and Vancouver exhibit the highest price sensitivity, whereas extended-stay hotel operators in Texas prioritize 10-year replacement cycle guarantees over upfront unit cost.
Supply Chain Analysis
Direct-to-developer channels handle hyperscale multifamily procurement in California, Texas, and Florida, bypassing traditional retail markups. Manufacturing concentrates in the United States, Canada, and Mexico, with Canadian panel producers dual-certifying under EPA and domestic standards. The supply chain draws from captive hardwood sourcing in the Rocky Mountains, Italian-engineered piston-lift mechanisms, and low-VOC engineered wood substrates. Single-source vulnerability around proprietary hardware distribution from Murphy Wall-Bed Hardware Inc. creates concentration risk for regional assemblers. Distribution runs through certified technician networks for installation-heavy residential contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Wall Bed Market functions as a geographic-arbitrage play where Canadian mills leverage dual-certification advantages to capture cross-border supply contracts while Mexican assembly operations absorb tariff-advantaged production for US-branded distributors.
For Market Incumbents: Deploy captive hardwood sourcing to buffer Rocky Mountain lumber volatility and insulate premium tier margins from particleboard-dependent competitors. Deepen backward integration into low-VOC engineered wood substrate production to compress TSCA Title VI certification cycles. Sofa bed substitution in urban renter segments demands defensive positioning through dual-function product line extensions. For New Entrants and Emerging Players: EPA TSCA Title VI formaldehyde rules in the United States open a window for certified Canadian panel producers to establish cross-border supply partnerships with mid-market assemblers facing sourcing friction. Target Texas and Florida multifamily developer-direct channels where construction permits outpace national averages. Pursue smart home convergence through IoT-enabled motorized lift system partnerships as the most penetrable premium positioning angle. For Investors and Strategic Acquirers: Multifamily real estate developers are the most active acquirer in this space, vertically integrating millwork capabilities to control pre-sale specification flows in Vancouver's Yaletown and Toronto's King West towers. The analysis frames five-to-ten year viability around regulatory compliance moats rather than hardware differentiation alone. Acquisition targets should demonstrate dual-certification infrastructure and developer-direct channel relationships. Monitor California Section 01350 indoor air quality mandate expansion as the inflection signal for engineered wood substrate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive low-VOC engineered wood supply compresses EPA TSCA Title VI certification timelines for mid-market assemblers. |
| Smart Home Convergence Partnership | Motorized lift integration with IoT controls commands specification in luxury residential and extended-stay hospitality segments. |
| Developer-Direct Channel Expansion | Architectural millwork embedding in Toronto and Vancouver micro-condominiums locks out aftermarket competitors. |
| Dual-Certification Infrastructure Investment | Canadian panel producers secure cross-border market access through simultaneous EPA and domestic standard compliance. |
| Institutional Procurement Specialization | Metal-framed durability specifications for university housing and military barracks displace traditional dormitory furniture suppliers. |
Research Methodology
Bottom-up residential and commercial procurement modeling reconciled against top-down substrate production and hardware distribution tracking forms the analytical core of this study. Primary interviews with multifamily developers, millwork contractors, furniture procurement officers at extended-stay hotel chains, and certified installation technicians were validated against secondary sources including EPA TSCA Title VI certification registries, California Department of Public Health Section 01350 compliance databases, and municipal building permit records in Toronto, Vancouver, Houston, and Dallas.
The input-output matrix framing connects piston-lift mechanism cycle ratings, engineered wood substrate VOC emission levels, and regional construction permit velocities to demand projections across the analysis window. Segmentation dimensions include product type, material substrate, end-user category, and distribution channel, with hardware durability tiers and certification grade status as industry-specific forecast inputs. CAGRs were derived from regression analysis of historical permit data against wall bed specification penetration rates.
Revisions become necessary when EPA formaldehyde emission thresholds tighten, Canadian-US trade terms shift, or smart home integration adoption accelerates beyond current hospitality and luxury residential clusters. Forecasts reflect assumptions around regulatory stability, lumber input cost trajectories, and technician network scalability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Bed Wedge Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Canopy Beds Market
Bedroom Furniture
China Mattress Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
United States Mattress Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
North America Mattress Market