
 Baby Cribs Market | 2026-2036
Baby Cribs Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Cribs Market Analysis
Aftermarket service revenue from mattress replacement and conversion kit sales is tilting margin pools away from initial hardware transactions. Delta Children leverages its vertical manufacturing footprint to control costs across wood sourcing and finished assembly. Storkcraft anchors its position through broad retail distribution partnerships with mass-market chains. Babyletto differentiates via design-forward aesthetics targeting premium urban consumers.
A baby crib is a framed sleeping enclosure for infants, typically constructed with slatted sides, fixed or adjustable mattress supports, and compliance-tested finishes to prevent entrapment or chemical exposure. Convertible cribs dominate unit economics as they extend product lifecycles from infancy through toddler years via rail removal and mattress repositioning. Wood material categories command premium positioning due to parental perceptions of durability and natural composition, while metal and plastic segments compete on portability and price accessibility.
The US Consumer Product Safety Commission mandates full-size and non-full-size crib standards under 16 CFR Part 1219, while the EU REACH regulation restricts phthalates and formaldehyde emissions in finishes and adhesives. ASTM International F1169 provides voluntary structural testing protocols that most major retailers require for shelf placement. Stakeholders must monitor evolving chemical disclosure rules and state-level extended producer responsibility frameworks that could reshape material sourcing and end-of-life collection obligations.
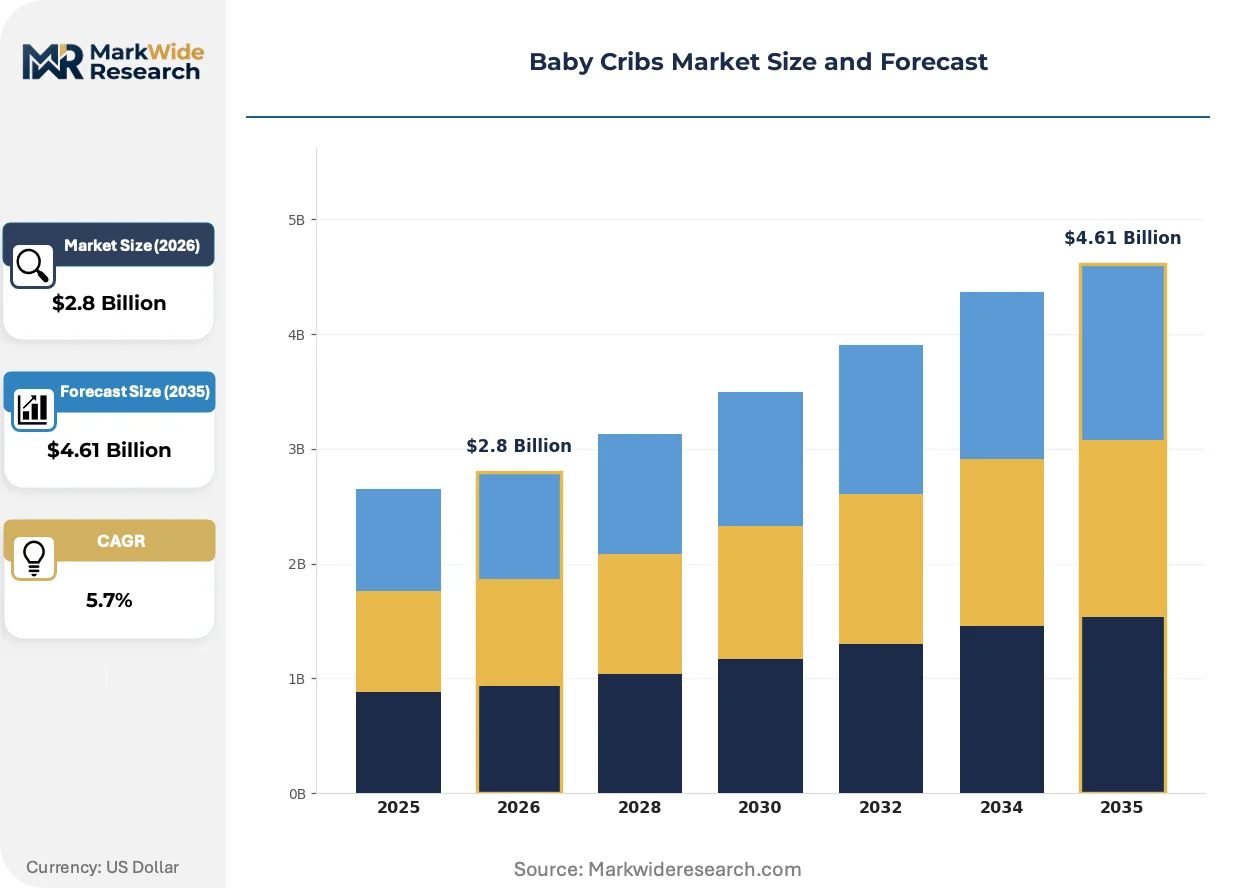
Market Dynamics
Convertible crib architectures are compressing replacement cycles and capturing mattress and conversion kit revenue streams that previously escaped to aftermarket suppliers, forcing manufacturers to restructure their hardware-plus-consumables economics around extended household tenure.
Growth Catalysts
- REACH chemical compliance:The EU's REACH framework mandates formaldehyde and phthalate restrictions in finishes and adhesives, creating certified-supplier premiums that reward early compliance investments with retail shelf access.
- Urban millennial household formation:Dense metropolitan housing in cities like New York, London, and Shanghai drives demand for space-efficient convertible designs that transition from bassinet to toddler bed without square footage expansion.
- Solid wood sourcing premiums:Parental perception of natural material safety is elevating certified sustainable hardwoods above engineered alternatives in premium positioning.
Market Restraints
- Volatile Baltic birch plywood costs:Input price swings for this primary crib substrate compress margin predictability for manufacturers without captive timber holdings or long-term supply contracts.
- Chinese component concentration:Hardware, fasteners, and adjustable mattress mechanisms cluster in Zhejiang and Guangdong provinces, exposing supply continuity to single-region logistics disruptions.
- 16 CFR Part 1219 testing timelines:US Consumer Product Safety Commission certification cycles extend product launch windows by 4-6 months, freezing working capital in pre-revenue inventory.
Strategic Opportunities
- Indian tier-two city penetration:E-commerce logistics expansion into cities like Pune, Ahmedabad, and Jaipur opens convertible crib access to first-time middle-class parents previously served only by informal local carpentry.
- Subscription-based conversion kit fulfillment:Automated mattress and rail replacement shipments timed to child development milestones capture recurring revenue from hardware-installed bases.
- EU Green Deal circular economy incentives:Member-state extended producer responsibility schemes for furniture end-of-life collection reward take-back program investments with regulatory preference and municipal procurement access.
Industry Challenges
- Furniture-grade finishing technician scarcity:Low-VOC waterborne coating application requires specialized spray booth expertise that vocational pipelines have not scaled to meet demand.
- ASTM F1169 structural testing backlog:Third-party laboratory capacity constraints delay voluntary certification required by major retail buyers, stalling channel entry for new entrants.
- ERP integration with legacy timber tracking:Chain-of-custody documentation for FSC-certified sourcing demands system upgrades that smaller manufacturers execute slowly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Cribs Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convertible Cribs, Portable Cribs, Mini Cribs, Traditional Cribs Material: Wood, Metal, Plastic, Fabric Design: Modern, Rustic, Vintage, Contemporary Feature: Foldable, Adjustable Mattress Height, Under-crib Storage, Safety Standards |
| Companies Covered | Newton Baby, Delta Children, Nestig, Graco, Storkcraft, Babyletto, Stokke, dadada, DaVinci, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Cribs Market Emerging Trajectories
Smart sensing integration and material transparency are redefining product differentiation beyond static safety compliance, with manufacturers competing on real-time environmental monitoring and chemical disclosure depth rather than structural durability alone.
Embedded air quality and breathing motion sensors are collapsing the boundary between passive sleep furniture and active infant monitoring systems. Premium urban buyers in Seoul, Toronto, and Sydney are specifying these integrated units at rates that compress standalone monitor sales. The technology is collapsing aftermarket device attach rates by bundling monitoring into the crib purchase itself.
California's Proposition 65 enforcement expansion now requires explicit warning labeling for formaldehyde emissions in juvenile furniture sold or shipped into the state. Retailers have responded by demanding batch-level chemical testing documentation from all suppliers regardless of origin. West Coast distribution now segregates compliant and non-compliant inventory, bifurcating fulfillment operations.
Direct-to-parent subscription models are displacing traditional retail buying cycles for conversion accessories. Urban millennial households in Amsterdam, Copenhagen, and Melbourne prefer automated mattress firmness and rail kit deliveries synchronized to pediatrician visit schedules. This pattern concentrates customer data ownership with manufacturers and erodes retailer aftermarket capture.
Baby Cribs Market Segmentation
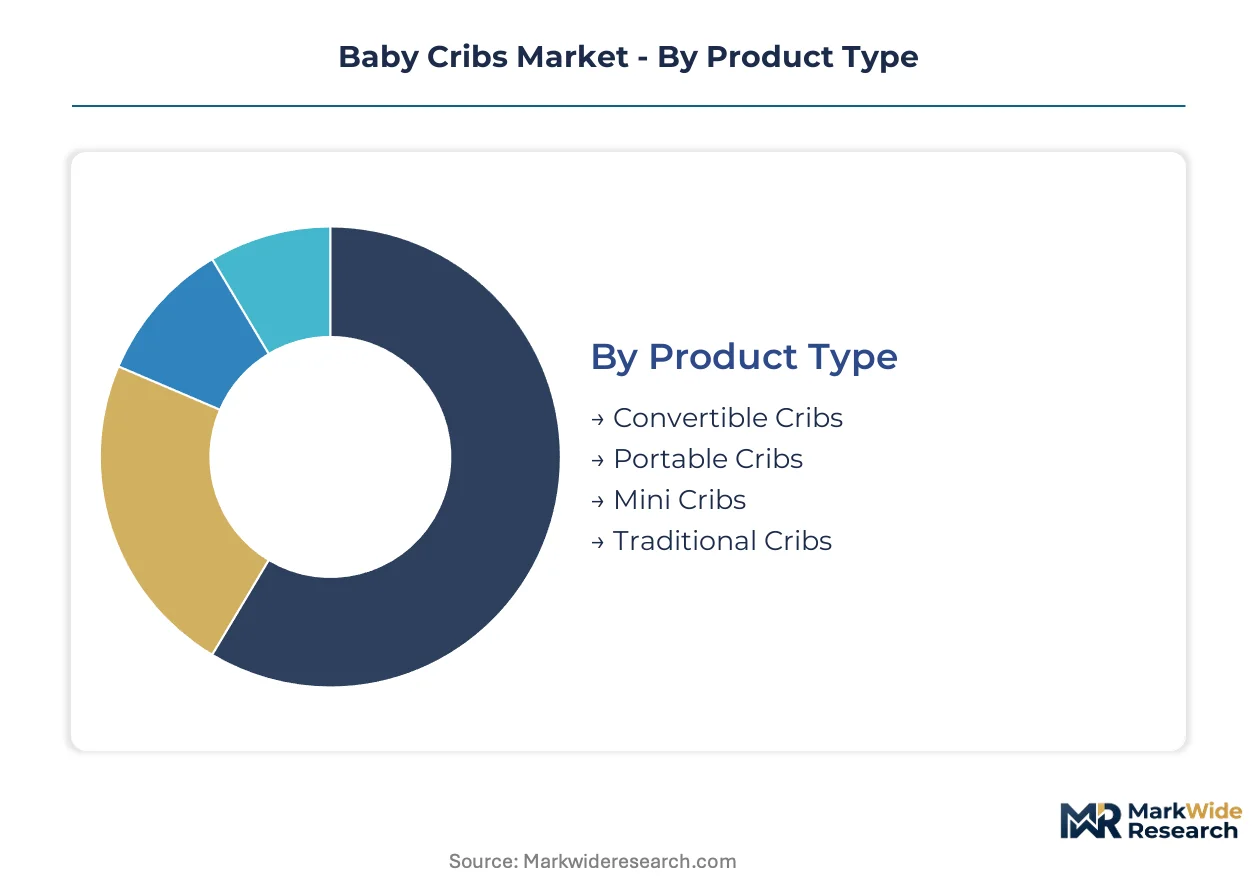
Product heterogeneity in the baby cribs market reflects divergent household tenure patterns and parental willingness to pay for lifecycle extension. Segment boundaries increasingly blur as manufacturers bundle hardware with consumable accessories to capture recurring revenue streams.
Product Type:
Convertible architectures compress household replacement cycles from three purchases to one, while portable and mini variants serve secondary locations with abbreviated usage windows.
- Convertible Cribs:Modular rail systems and mattress support repositioning extend functional lifespan from infancy through early childhood. Millennial parents in New York and London prioritize these units despite 40-60% price premiums over traditional alternatives.
- Portable Cribs:Collapsible aluminum or tubular steel frames target grandparents' homes and travel scenarios. Demand clusters among dual-income households in Seattle and Toronto seeking flexible sleep arrangements without dedicated nursery space.
- Mini Cribs:Compact footprints serve urban apartments where square footage commands premium valuations. Primary adoption occurs in studio and one-bedroom configurations.
- Traditional Cribs:Fixed-side constructions without conversion capability dominate price-sensitive procurement. Volume concentrates in mass-market retail channels.
Traditional cribs anchor the volume base while convertible designs gain share at the steepest rate.
Material:
Raw material selection dictates finishing complexity, supply chain geography, and parental perception of infant safety exposure.
- Wood:Solid hardwoods and furniture-grade plywood receive multi-coat low-VOC finishes meeting REACH and 16 CFR Part 1219 requirements. Certified sustainable sourcing from Baltic states and Appalachian regions commands supplier premiums.
- Metal:Tubular steel and aluminum alloys enable lightweight portable architectures. Powder-coat finishing eliminates solvent-based emission concerns.
- Plastic:Injection-molded polypropylene and ABS serve budget positioning and travel-focused use cases. Recycled content integration responds to EU Green Deal circular economy specifications.
- Fabric:Mesh and textile constructions appear in travel crib and bassinet attachments. Breathability certification drives material specification.
Wood materials dominate revenue contribution while plastic alternatives expand most quickly in emerging market penetration.
Design:
Aesthetic positioning separates premium urban boutiques from mass-market retail shelves, with design language signaling parental identity affiliation.
- Modern:Clean lines, neutral palettes, and minimal visible hardware align with Scandinavian-influenced interior trends. Urban consumers in Copenhagen and Amsterdam specify these units at elevated rates.
- Rustic:Distressed finishes and visible wood grain target farmhouse and cottage aesthetic preferences. Regional concentration appears in southeastern US and rural Canadian markets.
- Vintage:Spindle details and antique-inspired hardware serve heritage-themed nursery designs. Safety retrofit requirements limit true antique sourcing.
- Contemporary:Geometric forms and mixed material integration occupy middle-market positioning. Retailer private label programs favor this flexibility.
Contemporary styling anchors the volume base while modern designs gain share at the steepest rate.
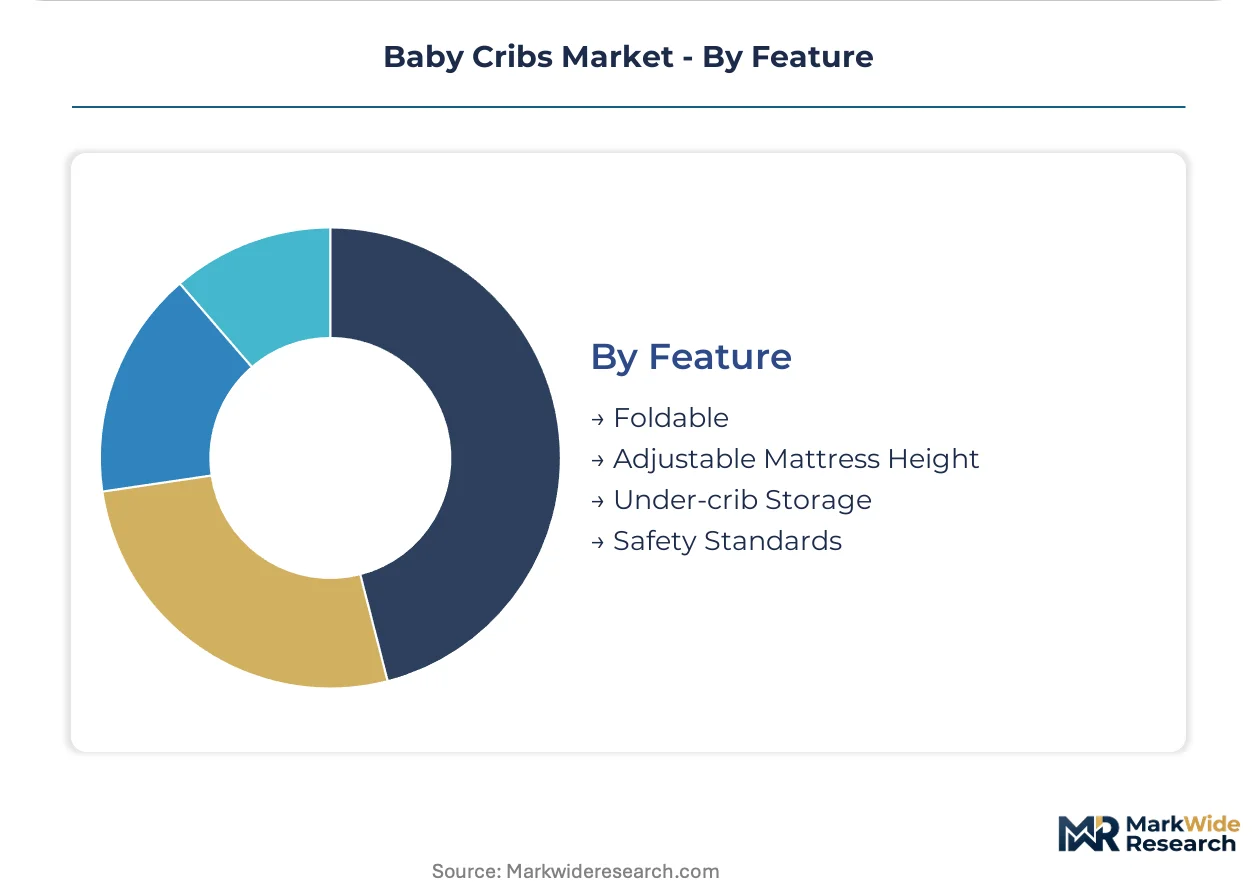
Feature:
Functional specifications determine compliance burden, manufacturing complexity, and aftermarket revenue attachment potential.
- Adjustable Mattress Height:Three-position support mechanisms accommodate infant growth stages and parental lifting ergonomics. This capability has become baseline for mid-tier and above positioning.
- Safety Standards:ASTM F1169 structural testing and CPSC certification documentation required by major retail buyers. Batch-level testing extends production timelines.
- Foldable:Hinge and locking mechanisms enable storage and transport scenarios. Engineering tolerance demands concentrate manufacturing in Zhejiang province.
- Under-crib Storage:Integrated drawers capture otherwise dead space in compact urban bedrooms. Drawer glide specification affects perceived quality.
Adjustable mattress height anchors the volume base while safety standards certification gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial household formation in dense metropolitan cores is compressing nursery footprints and elevating demand for convertible architectures, while regulatory divergence between REACH-compliant European markets and CPSC-governed North American procurement is fragmenting supplier certification requirements.
United States
Dual-income households in Seattle and New York prioritize space-efficient convertible designs that extend product lifecycles. The CPSC enforces 16 CFR Part 1219 standards with mandatory third-party testing, extending launch timelines for new entrants. Manufacturing concentration in North Carolina and Mississippi leverages Appalachian hardwood sourcing for premium solid-wood positioning.
Germany
Scandinavian-influenced interior preferences in Berlin and Hamburg drive specification of minimalist modern aesthetics with FSC-certified sustainable sourcing. ECHA REACH enforcement mandates formaldehyde emission limits below 0.1 ppm in finishes, creating certified-supplier premiums. The Bavarian furniture cluster around Rosenheim specializes in precision-engineered adjustable mattress mechanisms.
China
Middle-class expansion in Shanghai and Beijing is accelerating convertible crib penetration through e-commerce platforms with same-day fulfillment capabilities. The State Administration for Market Regulation enforces GB 28007-2011 structural safety standards alongside voluntary CCC certification. Zhejiang province hardware manufacturers in Wenzhou dominate adjustable mechanism and fastener supply.
India
First-time parents in Pune and Ahmedabad are bypassing informal carpentry for branded convertible units as logistics penetration deepens. The Bureau of Indian Standards operates voluntary IS 9873 certification for juvenile furniture without mandatory enforcement. The Delhi-NCR corridor is emerging as a distribution hub for premium imported and domestic assembled products.
United Kingdom
Urban density constraints in London and Manchester elevate mini crib and convertible demand among apartment-dwelling millennials. Trading Standards enforces EU-derived REACH chemical compliance post-Brexit with continued ECHA alignment. The Midlands manufacturing belt around Nottingham maintains specialty finishing capabilities for heritage-styled spindle designs.
Baby Cribs Market Vendor Landscape
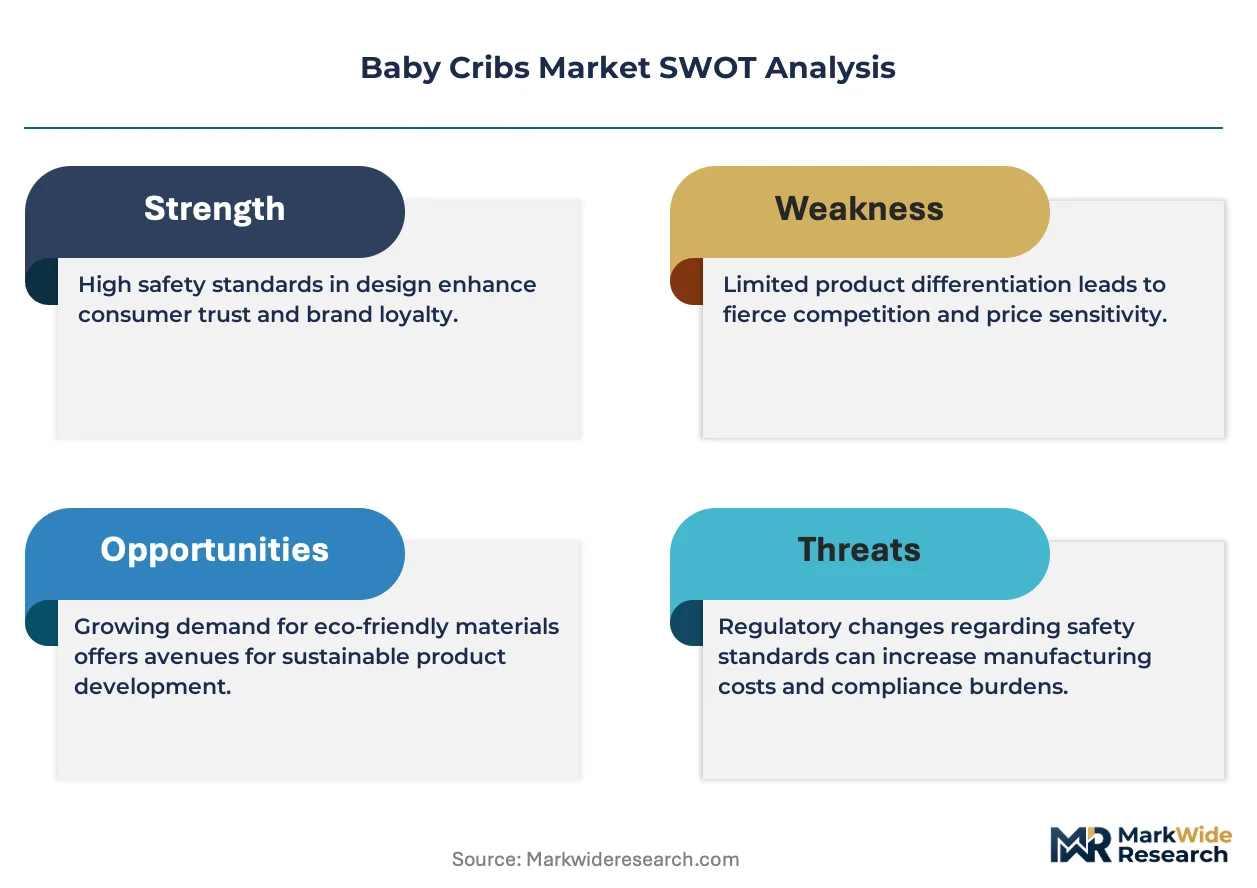
Capability concentration sits with design-forward specialists commanding premium positioning; scale advantage sits with mass-market fabricators with captive retail distribution. The vendor base stratifies across three tiers: vertically integrated hardwood specialists, broad-line juvenile furniture conglomerates, and direct-to-consumer digital natives. Dominant competitive moves include backward integration into Baltic timber sourcing and subscription-based conversion kit fulfillment models that capture recurring revenue from installed hardware bases.
Within the vertically integrated tier, Delta Children exemplifies cost control through captive wood sourcing and finished assembly operations. Storkcraft occupies a position representing broad retail distribution anchoring through mass-market chain partnerships. Babyletto sits within the design-forward archetype targeting premium urban consumers with Scandinavian-influenced aesthetics. These three anchors illustrate the strategic divergence between scale efficiency, channel breadth, and aesthetic differentiation.
| Leading Market Players |
|---|
| Newton Baby |
| Delta Children |
| Nestig |
| Graco |
| Storkcraft |
| Babyletto |
| Stokke |
| dadada |
| DaVinci |
| Others |
Supply Flow & Price Mechanics
Shanghai-Ningbo port freight corridors transmit Baltic birch plywood cost volatility directly into manufacturer margin structures, compressing pricing power for non-integrated producers while amplifying differentiation premiums for REACH-certified suppliers with captive timber holdings.
Pricing Analysis
Long-term offtake contracts for FSC-certified Appalachian and Baltic hardwoods anchor premium tier positioning, while spot-market Baltic birch procurement serves economy segments. Price differentiation rests on REACH compliance certification and adjustable mechanism engineering precision. Cost compression in mid-tier wood sourcing is intensifying because Zhejiang hardware suppliers face energy rationing. Mass-market retail buyers exhibit highest price sensitivity; design-forward urban boutiques show inelastic demand for certified sustainable sourcing.
Supply Chain Analysis
Hardwood feedstocks draw from Estonian and Latvian forest concessions, Appalachian timber holdings, and Guangdong engineered panel facilities. Metal hardware and adjustable mattress mechanisms hinge on Wenzhou and Dongguan manufacturing clusters. Single-source vulnerability concentrates in Zhejiang province fastener production. Distribution runs through mass-market retail chains, boutique nursery specialists, and direct-to-parent e-commerce platforms with same-day fulfillment in tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Convertible crib penetration in Indian tier-two cities signals early-cycle expansion, with e-commerce logistics deepening access beyond traditional carpentry-served households.
For Market Incumbents: Entrench through backward integration into Baltic timber concessions and captive low-VOC finishing capacity. Delta Children-style manufacturing footprints defend against Zhejiang supply disruptions. Certification investments in REACH and 16 CFR Part 1219 compliance lock in retail shelf access against emerging entrants.
For New Entrants and Emerging Players: Tier-two Indian cities with nascent e-commerce penetration represent the most penetrable entry point for branded convertible units. Subscription-based conversion kit fulfillment captures recurring revenue from hardware-installed bases. Direct-to-parent digital channels bypass established retail gatekeepers.
For Investors and Strategic Acquirers: Carve-out targets emerge from juvenile furniture conglomerates with underutilized finishing capacity and dormant FSC certification. Five-to-ten year viability favors design-forward specialists with data-rich subscription customer bases. Watch for REACH enforcement acceleration in additional member states as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Timber | Captive Baltic and Appalachian hardwood sourcing insulates margin from plywood price swings. |
| Subscription Conversion Kit Fulfillment | Automated mattress and rail shipments timed to pediatric milestones capture recurring revenue streams. |
| REACH Compliance Certification Investment | Formaldehyde and phthalate testing documentation unlocks EU retail shelf access and supplier premiums. |
| Direct-to-Consumer Digital Launch | Owned customer data from DTC channels erodes retailer aftermarket capture and enables personalized accessory marketing. |
| Smart Sensor Integration Partnership | Embedded air quality and breathing monitors collapse standalone device sales into premium hardware bundles. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade records, CPSC certification databases, and EU ECHA substance registrations. Interviews with juvenile furniture brand managers, retail category buyers, Baltic timber procurement leads, and Zhejiang hardware manufacturers inform demand and supply-side dynamics. Bottom-up unit shipment modeling triangulates against top-down household formation projections.
Forecast inputs incorporate product type segmentation by convertible, portable, mini, and traditional architectures; material tiers across solid wood, metal, plastic, and fabric; and design positioning from modern through vintage aesthetics. CAGRs derive from fitted growth curves across the projection horizon. Birth rate trajectories, urban household density indices, and e-commerce penetration curves inform regional demand allocation.
Macroeconomic conditions sit as an overlay; deviation in birth rates, Baltic plywood futures, or China-EU shipping rates would shift the trajectory. Cross-checking against national statistical office household formation data and timber trade association production volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Luxury Mattress Market
Bedroom Furniture
United States Mattress Market
Bedroom Furniture
Bed Wedge Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
Bed Head Panel Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
US Wall Beds Market