
 Home Bedding Market | 2026-2036
Home Bedding Market Size, Share, and Industry Trends Forecast 2026-2036
Home Bedding Market Intelligence
Customer concentration in the home bedding market is broadening beyond traditional department stores to encompass a fragmented landscape of direct-to-consumer (DTC) and specialized hospitality buyers. Casper Sleep Inc. leverages its digital-native brand and DTC model to reach younger demographics. In contrast, Tempur Sealy International sustains its market position through a vast network of physical retail partners and strong brand equity. WestPoint Home LLC competes by supplying major retailers and the hospitality industry with a wide portfolio of textile products.
Home bedding refers to the array of textile products used for covering mattresses, pillows, and inserts, including sheets, cases, and comforters. Technical specifications such as thread count, fiber staple length, and weave type (e.g., percale, sateen) are critical determinants of product performance, durability, and texture. The primary purpose is to provide comfort, hygiene, and aesthetic value in residential settings. While cotton remains the dominant material segment due to its breathability and cost-effectiveness, materials like linen and silk are gaining share in the premium category. Bedsheets and pillowcases form the highest volume product segment, driven by frequent replacement cycles.
Regulatory compliance shapes material sourcing and product claims. In the United States, the FTC enforces textile fiber content and care labeling rules, while the EU's REACH regulation restricts the use of certain chemicals in consumer goods. Certifications such as OEKO-TEX Standard 100 and the Global Organic Textile Standard (GOTS) are becoming essential for market access, verifying that products are free from harmful substances. Effectively communicating material traceability and adherence to sustainability standards is becoming a key factor for brand differentiation and consumer trust.
Market Dynamics
The home bedding market's central dynamic is the pressure from the hospitality sector for durable, premium textiles and the parallel consumer pursuit of wellness and sustainability. This dual demand influences everything from material sourcing to product certification standards.
Growth Catalysts
- Hospitality Sector Procurement:Hotels and resorts are increasingly investing in high-thread-count sheets and premium fills to enhance guest satisfaction and brand image, creating a significant B2B demand channel for luxury bedding products.
- Sustainable Material Frameworks:The adoption of standards like the Global Organic Textile Standard (GOTS) provides a clear pathway for producers to validate organic and socially responsible production, appealing to environmentally conscious consumers.
- Chinese Consumer Focus:A growing middle class in China is prioritizing home comfort and personal wellness, spurring domestic consumption of higher-quality bedding materials like long-staple cotton and silk.
Market Restraints
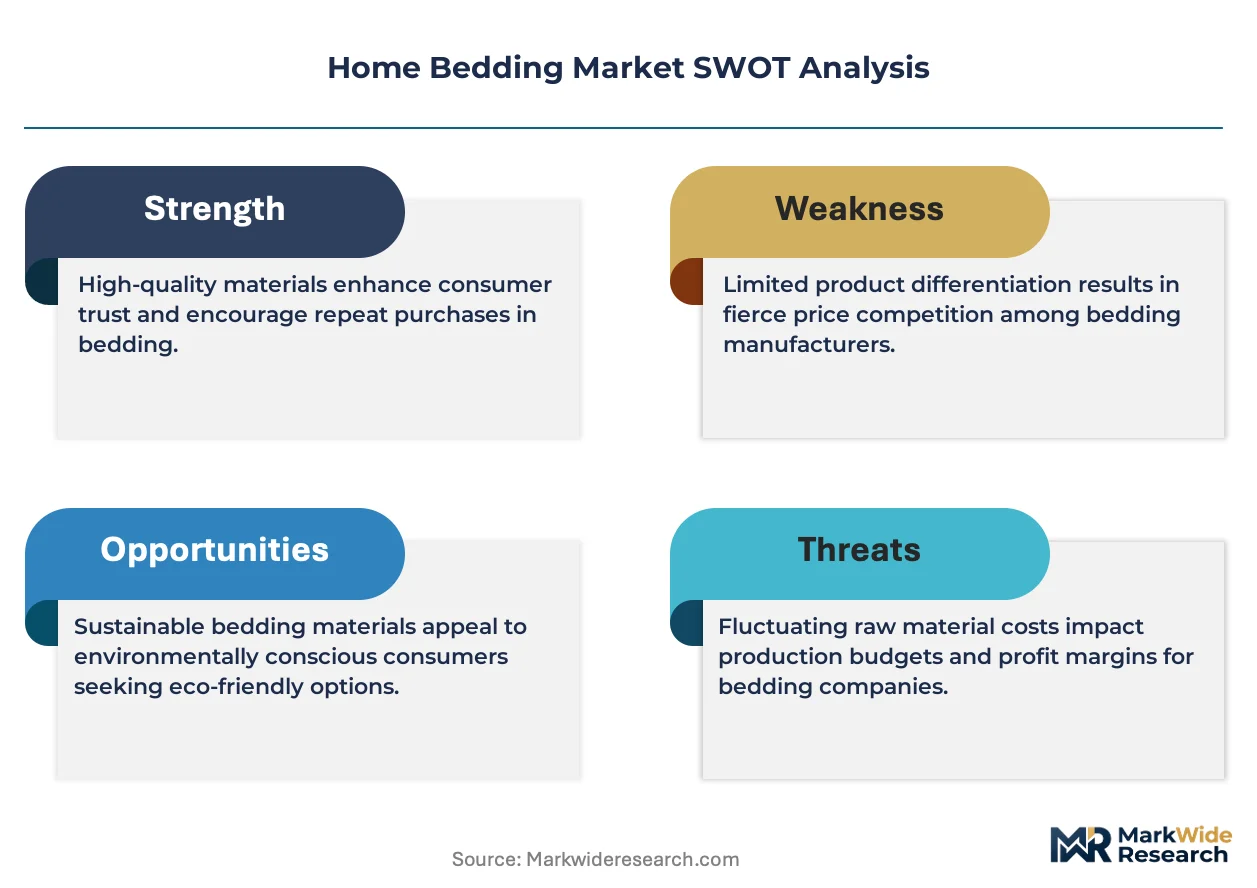
- Raw Material Volatility:The price and availability of high-quality natural fibers, particularly long-staple cotton, are subject to fluctuations from climate events and agricultural policies, creating input cost instability for manufacturers.
- Regulatory Fragmentation:Manufacturers face complexity in complying with disparate chemical safety regulations, such as the EU's REACH framework and the FTC's labeling rules in the United States, which increases compliance overhead.
- Synthetic Fiber Competition:Lower-cost synthetic alternatives like microfiber polyester present a significant substitution threat, competing aggressively on price point, particularly in the economy and mid-range market segments.
Strategic Opportunities
- Smart Textile Integration:There is an opportunity to embed sensor technology into bedding for sleep tracking and climate control, catering to the wellness and quantified-self movements and creating a new premium product category.
- Subscription-Based Models:Developing direct-to-consumer subscription services for products with frequent replacement cycles, such as bedsheets and pillowcases, can build recurring revenue and enhance customer loyalty.
- Southeast Asian Market Entry:Countries with rising disposable incomes, such as Vietnam and Indonesia, represent underpenetrated markets for branded and premium bedding products as consumer preferences evolve beyond basic utility.
Industry Challenges
- Certification Complexity:Obtaining and maintaining multiple third-party certifications like OEKO-TEX Standard 100 and GOTS is a resource-intensive process, creating barriers for smaller manufacturers and complicating supply chain management.
- Supply Chain Traceability:Ensuring and verifying the provenance of raw materials, such as ethically sourced down or organic cotton, throughout a multi-layered global supply chain remains a significant operational hurdle.
- Product Counterfeiting:The market faces persistent issues with counterfeit goods and fraudulent marketing claims regarding thread count, material composition, and certifications, which erodes consumer trust and brand equity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Bedding Market |
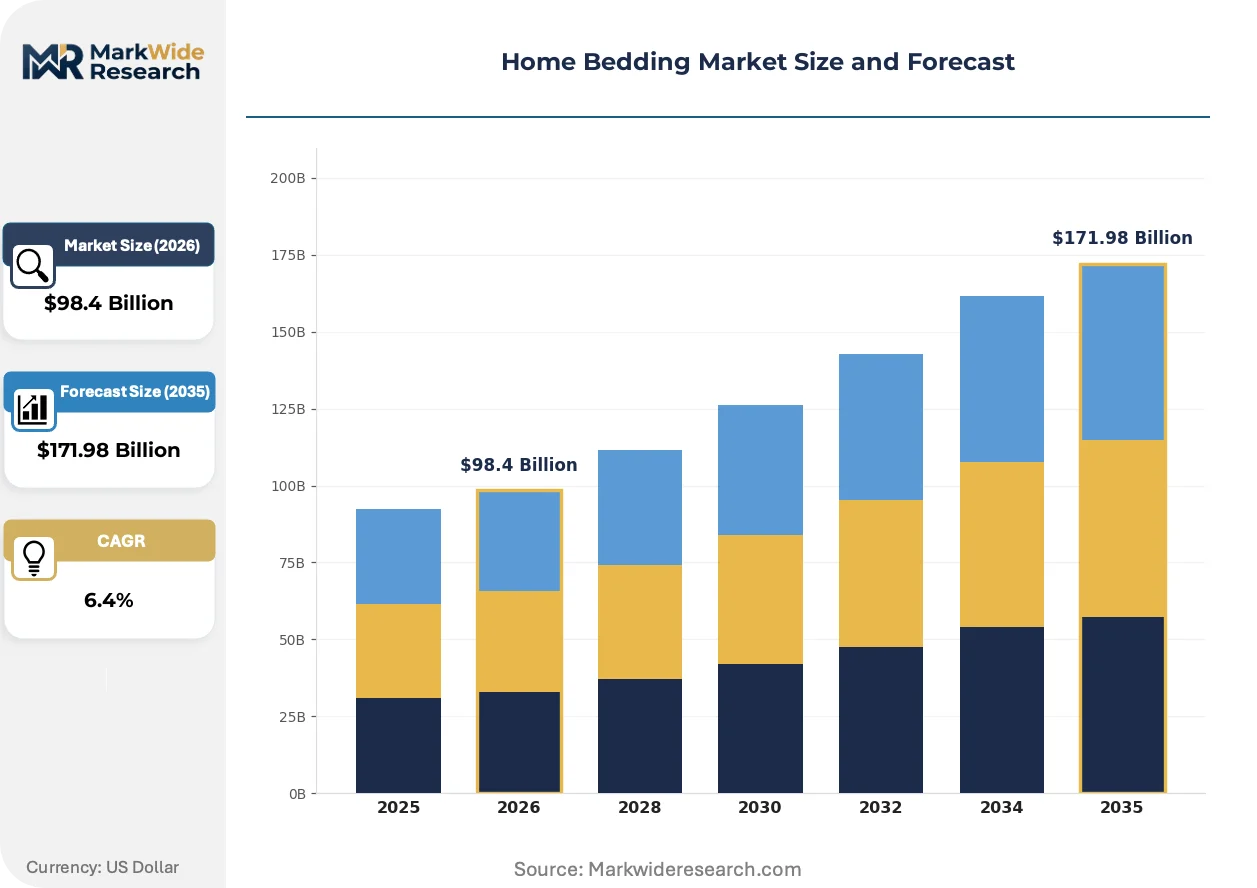
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $171.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedsheets, Comforters, Pillowcases, Duvets Material: Cotton, Polyester, Linen, Silk Size: Twin, Full, Queen, King Distribution Channel: Online, Offline, Retail Stores, Direct Sales |
| Companies Covered | Bombay Dyeing & Manufacturing Company Limited, Casper Sleep Inc., American Textile Company, Beaumont & Brown, Boll & Branch LLC, Sleep Number Corporation, Tempur Sealy International, Purple Innovation Inc., WestPoint Home LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Bedding Market Strategic Shifts & Innovations
Material science advancements and digital retail models are fundamentally altering product development and market access in the home bedding sector. Innovations focus on enhancing performance attributes like thermal comfort, while new channels change how consumers discover and purchase products.
Fibers engineered for thermoregulation, such as TENCEL™ Lyocell and those infused with phase-change materials, manage heat and moisture to improve sleep quality. Health-conscious consumers and buyers in the premium residential segment are driving adoption of these materials. This technology is expanding into performance-oriented product lines, creating a clear differentiation from conventional cotton-based bedding.
Regulations like the EU's Corporate Sustainability Reporting Directive (CSRD) are forcing greater transparency in textile supply chains. This directive requires large companies to disclose detailed environmental and social impact data. The bedding segment is highly affected, compelling manufacturers selling into Europe to invest in robust traceability systems for materials to substantiate sustainability claims.
Consumer purchasing behavior is shifting from incidental, in-store acquisitions to a research-intensive process heavily influenced by digital content and reviews. Direct-to-consumer (DTC) online brands are disrupting sales once dominated by department stores and big-box retailers. This trend is most visible in North America and Western Europe, where brand storytelling and digital marketing are critical for capturing market share.
Home Bedding Market Segmentation
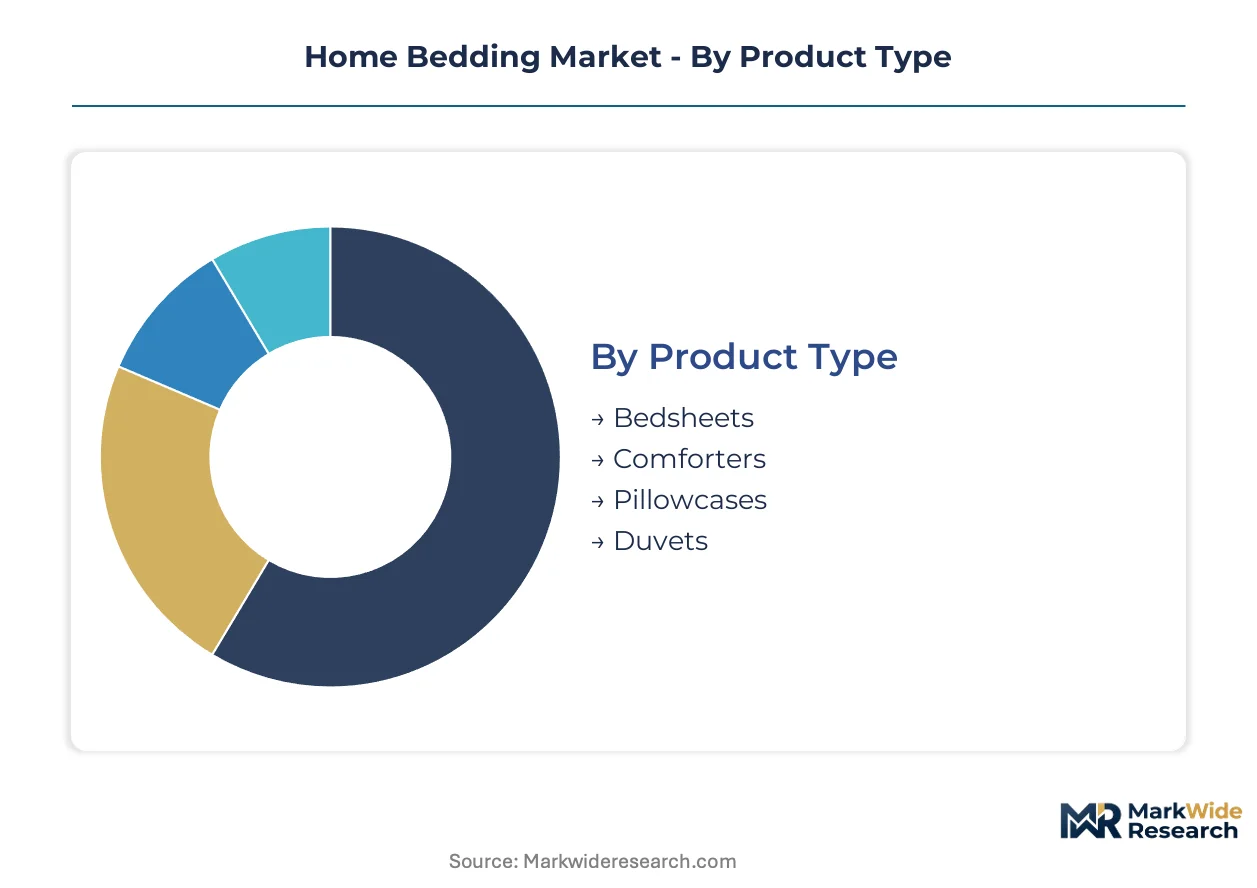
Analyzing the home bedding market through detailed segmentation reveals distinct consumer behaviors and operational requirements across product types, materials, sizes, and distribution channels. This granular view helps manufacturers and retailers tailor product development, marketing strategies, and supply chain logistics to specific market demands and regulatory landscapes.
Product Type:
Ensuring regulatory compliance for textile products often dictates the manufacturing processes and claims for various home bedding product types, particularly concerning fiber content and chemical safety standards like OEKO-TEX Standard 100.
- Bedsheets:These textile layers cover mattresses, primarily providing hygiene and comfort. Demand concentrates in residential settings globally, driven by frequent replacement cycles and the pursuit of specific thread counts and weave types like percale or sateen.
- Comforters:Thick, quilted blankets filled with natural or synthetic materials, comforters offer thermal insulation and aesthetic appeal. The hospitality sector increasingly procures premium comforters to enhance guest experiences, focusing on durability and hypoallergenic properties.
- Pillowcases:Fabric coverings for pillows, pillowcases contribute to hygiene and extend pillow lifespan.
- Duvets:Protective covers for duvets, often featuring decorative designs and requiring less frequent washing than the insert.
Leading the category by volume: Bedsheets. Growing fastest: Comforters.
Material:
Cost considerations heavily influence material selection, segmenting the market based on raw fiber expense and processing requirements for different home bedding materials.
- Cotton:A natural fiber known for breathability and softness, cotton remains the dominant material due to its versatility and cost-effectiveness. Demand is widespread across all market segments, from economy to luxury, particularly for long-staple varieties.
- Silk:Valued for its luxurious feel, natural sheen, and hypoallergenic properties, silk occupies the premium segment. Consumer demand in affluent markets, particularly in China, is spurring growth for silk bedding due to its perceived wellness benefits.
- Polyester:A synthetic fiber offering durability, wrinkle resistance, and affordability, polyester competes strongly in the economy and mid-range segments.
- Linen:A natural fiber derived from flax plants, linen provides durability and a distinct texture.
Cotton holds the largest market share by volume, while silk is gaining share due to premium positioning.
Size:
Consumer preferences and household demographics primarily define the market segmentation by bed size, reflecting the standard bed dimensions in various regions.
- Twin:Designed for single occupants, twin-sized bedding is common in children's rooms and smaller living spaces. Demand is consistent in urban apartments and student housing.
- Full:Providing more width than a twin, full-sized bedding accommodates single adults or small couples. This size is popular in guest rooms and mid-sized bedrooms across North America.
- Queen:The most popular bed size for couples globally, queen-sized bedding offers a balance of space and room fit.
- King:King-sized bedding caters to consumers seeking maximum sleeping space, often found in master bedrooms and luxury hospitality suites.
Queen size products command the largest sales, with King size expanding quickly in affluent markets.
Distribution Channel:
The evolution of consumer purchasing habits shapes the segmentation across various distribution channels, influencing market access and brand visibility for home bedding products.
- Online:E-commerce platforms, including brand-specific direct-to-consumer (DTC) websites and large online retailers, offer convenience and broad product selection. This channel is crucial for reaching younger demographics and consumers in North America and Western Europe who prioritize digital content and reviews.
- Offline:Traditional brick-and-mortar stores, encompassing department stores, specialty bedding shops, and mass merchandisers, allow consumers to physically inspect products before purchase. This channel remains significant for customers valuing tactile experience and immediate acquisition.
- Retail Stores:This category includes a wide array of physical outlets where bedding products are sold directly to consumers.
- Direct Sales:Manufacturers selling directly to consumers through their own channels, including proprietary stores or online platforms, bypass intermediaries.
Offline retail channels still capture significant volume, but online platforms exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for home bedding concentrates in specific global regions, driven by evolving consumer preferences and economic growth. Hospitality sector procurement of premium textiles shapes regional market dynamics. Regulatory frameworks further influence material sourcing and product claims across these diverse geographies.
China
China's growing middle class prioritizes home comfort and personal wellness, spurring consumption of higher-quality bedding materials. The Chinese government's dual carbon goals influence sustainable manufacturing for textile producers. Major textile hubs like Shanghai and Guangzhou are centers for production and distribution of premium bedding.
United States
Consumer pursuit of wellness and sustainability drives demand for organic and smart textile bedding in the United States. The FTC enforces textile fiber content and care labeling rules, ensuring product claim accuracy. New York City and Los Angeles serve as key design and retail centers, showcasing luxury and innovative bedding trends.
Germany
High disposable incomes and environmental consciousness drive demand for certified sustainable bedding in Germany. The EU's REACH regulation restricts certain chemicals in consumer goods, impacting material sourcing for manufacturers. Production clusters in Bavaria specialize in high-quality textile manufacturing and export across Europe.
India
Rising disposable incomes and evolving urban lifestyles increase consumption of branded and premium bedding products across India. The Bureau of Indian Standards (BIS) sets quality benchmarks for textile products, guiding local manufacturers. Textile manufacturing centers like Panipat and Tirupur are significant for domestic supply and international exports.
Vietnam
Southeast Asian market entry opportunities exist in Vietnam due to rising disposable incomes and a shift towards higher-quality home goods. Government policies support textile industry growth and export, attracting foreign investment. Ho Chi Minh City is emerging as a critical hub for textile production and distribution, serving regional and global markets.
Home Bedding Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized segments like sustainable materials or smart textile integration. The market structure exhibits a mix of large, diversified textile manufacturers and agile, digitally native brands. Strategic archetypes include traditional volume players, premium brand specialists, and direct-to-consumer innovators. Portfolio diversification and strategic partnerships are dominant competitive moves among market participants.
Direct-to-consumer (DTC) brands like Casper Sleep Inc. exemplify the digital-native approach, targeting younger demographics with online sales models. Tempur Sealy International, conversely, represents a market position sustained through extensive physical retail networks and strong brand equity. WestPoint Home LLC sits within the archetype of a diversified textile supplier, providing a wide product portfolio to major retailers and the hospitality industry.
| Leading Market Players |
|---|
| Bombay Dyeing & Manufacturing Company Limited |
| Casper Sleep Inc. |
| American Textile Company |
| Beaumont & Brown |
| Boll & Branch LLC |
| Sleep Number Corporation |
| Tempur Sealy International |
| Purple Innovation Inc. |
| WestPoint Home LLC |
| Others |
Cost & Logistics Intelligence
Hospitality sector procurement of premium textiles creates significant demand for specialized materials, compelling suppliers to invest in higher-grade production and influencing pricing across the home bedding market.
Pricing Analysis
The home bedding market exhibits a clear volume-versus-margin split, operating primarily on a tiered premium-mid-economy pricing differentiation. Price differentiation stems from the quality grade of natural fibers like long-staple cotton and specific certification levels such as GOTS. Pricing softness affects the economy and mid-range segments due to aggressive competition from synthetic alternatives. The economy segment remains most price-sensitive, while hospitality buyers and premium residential consumers show lower price sensitivity for certified, high-performance products.
Supply Chain Analysis
Dual-sourcing requirements for critical raw materials, driven by risk mitigation, shape the home bedding supply chain. Geographic supply concentration centers in China, India, and Vietnam for textile production. The industry relies heavily on raw material dependencies such as cotton, silk, and polyester fibers. Raw material volatility, exacerbated by climate events impacting agricultural yields, represents a significant structural supply chain risk. Distribution runs through a fragmented model encompassing direct-to-consumer online platforms and traditional offline retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home bedding market faces supply constraints, particularly for high-quality natural fibers like long-staple cotton, which props up pricing in premium segments. Limited availability of certified organic materials also restricts broader market access.
For Market Incumbents: Extend product lifecycle management by investing in circular economy initiatives and material recycling technologies. Deepen relationships with hospitality procurement teams through customized product development and service agreements. This strategy counters the threat of synthetic fiber competition by emphasizing durability and sustainability. Vertical integration into specialized fiber processing offers a lever to control input costs and quality.
For New Entrants and Emerging Players: Digital-first distribution channels provide a strategic entry point to target health-conscious, digitally-savvy consumers. Focus on white-space opportunities such as smart textile integration for sleep tracking or subscription models for frequent replacement items like bedsheets. Brand storytelling around wellness and sustainability offers a compelling go-to-market angle for differentiation.
For Investors and Strategic Acquirers: Re-rating potential sits with agile, digitally-native brands given their strong customer acquisition metrics and potential for rapid scaling. Long-term viability in this market depends on capturing growth in premium and sustainable segments over the next decade. Acquisition targets should possess unique material science intellectual property or robust direct-to-consumer infrastructure. Sustained growth in sustainable material certifications provides a clear signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Sourcing Investment | Ensures compliance with evolving regulations and appeals to environmentally conscious consumers. |
| DTC Channel Expansion | Reduces reliance on traditional retail and strengthens direct customer relationships. |
| Smart Bedding R&D | Captures new premium segments driven by wellness and technology integration. |
| Hospitality Partnership Programs | Secures high-volume B2B contracts and enhances brand reputation through premium placements. |
| Material Traceability Systems | Validates product claims and builds consumer trust in ethical and sustainable practices. |
Research Approach
Industry reports, company filings, and textile association publications formed the secondary backbone of this market analysis. Primary research involved interviews with brand managers, textile engineers, retail buyers, and sustainability officers across key geographies. This approach combined bottom-up data collection with top-down market validation, ensuring comprehensive coverage and accuracy.
Historical trendline analysis underpins the market size and forecast projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, material, size, distribution channel, and regional consumer preferences. Compound Annual Growth Rates (CAGRs) were derived from demand-side growth factors and supply-side capacity expansions throughout the forecast period. Raw material price forecasts and consumer disposable income growth served as key industry-specific forecast inputs.
The model holds under conditions of stable raw material supply and consistent regulatory enforcement. Deviation in global trade policies or major climate events impacting fiber production would shift the forecast. A model refresh is warranted upon material change in consumer sustainability preferences.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Bed Wedge Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Bunk Beds Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Heated Bedding Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Canopy Beds Market
Bedroom Furniture
Asia-Pacific Mattress Market