
 Germany Home Furniture Market | 2026-2036
Germany Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Home Furniture Market Foresight
The split between handcrafted solid-wood dining sets and flat-pack particleboard living room systems is realigning how German manufacturers allocate capital and factory capacity. Rauch Möbelwerke GmbH leverages its vertical sawmill-to-showroom pipeline to control oak and beech supply costs. Schmidt Küchen GmbH & Co. KG anchors its position through built-to-order kitchen cabinetry with 72-hour configuration turnaround. IKEA competes on scale, operating 53 stores across Germany that standardize bedroom and storage furniture at mass-market price points.
Germany home furniture encompasses movable residential fixtures constructed from wood, metal, glass, upholstery, plastic, or rattan, engineered for ergonomic support, storage, and spatial organization within domestic interiors. Solid wood dining tables typically employ 40mm-thick engineered tops with moisture-resistant lacquer finishes to withstand Central European humidity cycles. Sofas and upholstered beds dominate value generation due to higher per-unit margins and shorter replacement cycles driven by fabric wear. E-commerce channels for living room and bedroom furniture are expanding fastest as virtual room-planning tools reduce return rates, while offline retail sustains volume leadership through tactile material evaluation.
KBA vehicle certification standards indirectly shape logistics furniture demand by regulating last-mile delivery fleet specifications, while REACH and the EU Green Deal mandate formaldehyde emission limits below 0.1 ppm for wood-based panels sold to German households. The F-Gas Regulation affects polyurethane foam blowing agents used in mattress and upholstery production, pushing suppliers toward cyclopentane alternatives. Stakeholders must monitor how Berlin's building energy efficiency codes reshape room dimensions and storage requirements in new residential construction.
Market Dynamics
German furniture manufacturers face capital reallocation pressure as EU Green Deal mandates force simultaneous compliance with formaldehyde emission limits and F-Gas phase-downs while modular living room demand reshapes factory tooling priorities.
Growth Catalysts
- REACH formaldehyde standards:Wood panel certification requirements above 0.1 ppm emission thresholds are filtering out uncertified imports and consolidating demand among compliant domestic producers.
- Urban apartment densification:Berlin and Munich micro-living units are driving specification pull for wall-mounted storage systems and convertible sofa beds with sub-200cm footprints.
- Bavaria premium consumption:Higher disposable household incomes in southern Germany sustain demand for solid oak dining sets and built-to-order bedroom cabinetry.
Market Restraints
- Beech and oak supply concentration:Sawmill capacity constraints in Central Europe limit domestic solid wood availability, forcing manufacturers toward engineered alternatives or Baltic imports.
- Cyclopentane transition costs:F-Gas Regulation phase-down of HFC blowing agents requires polyurethane foam retooling for mattress and upholstery production.
- Last-mile logistics rigidity:KBA vehicle certification standards for urban delivery fleets restrict flat-pack shipment volumes per route, elevating distribution costs for particleboard living room systems.
Strategic Opportunities
- Virtual room-planning tools:Augmented reality configuration software is compressing return rates for e-commerce bedroom and living room purchases, enabling channel expansion beyond tactile retail.
- Rhine-Ruhr retrofit construction:Berlin building energy efficiency codes are reshaping room dimensions in residential renovation, creating specification windows for custom storage and built-in cabinetry.
- Circular material recovery:EU Green Deal extended producer responsibility frameworks are opening revenue streams for furniture take-back and certified recycled wood sourcing.
Industry Challenges
- Master craftsperson pipeline:Vocational training gaps in traditional joinery and veneer application are constraining solid wood dining set production capacity.
- Dual certification timelines:Simultaneous FSC chain-of-custody and Blue Angel ecolabel approvals extend product launch cycles by 8-14 months for premium bedroom lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Home Furniture Market |
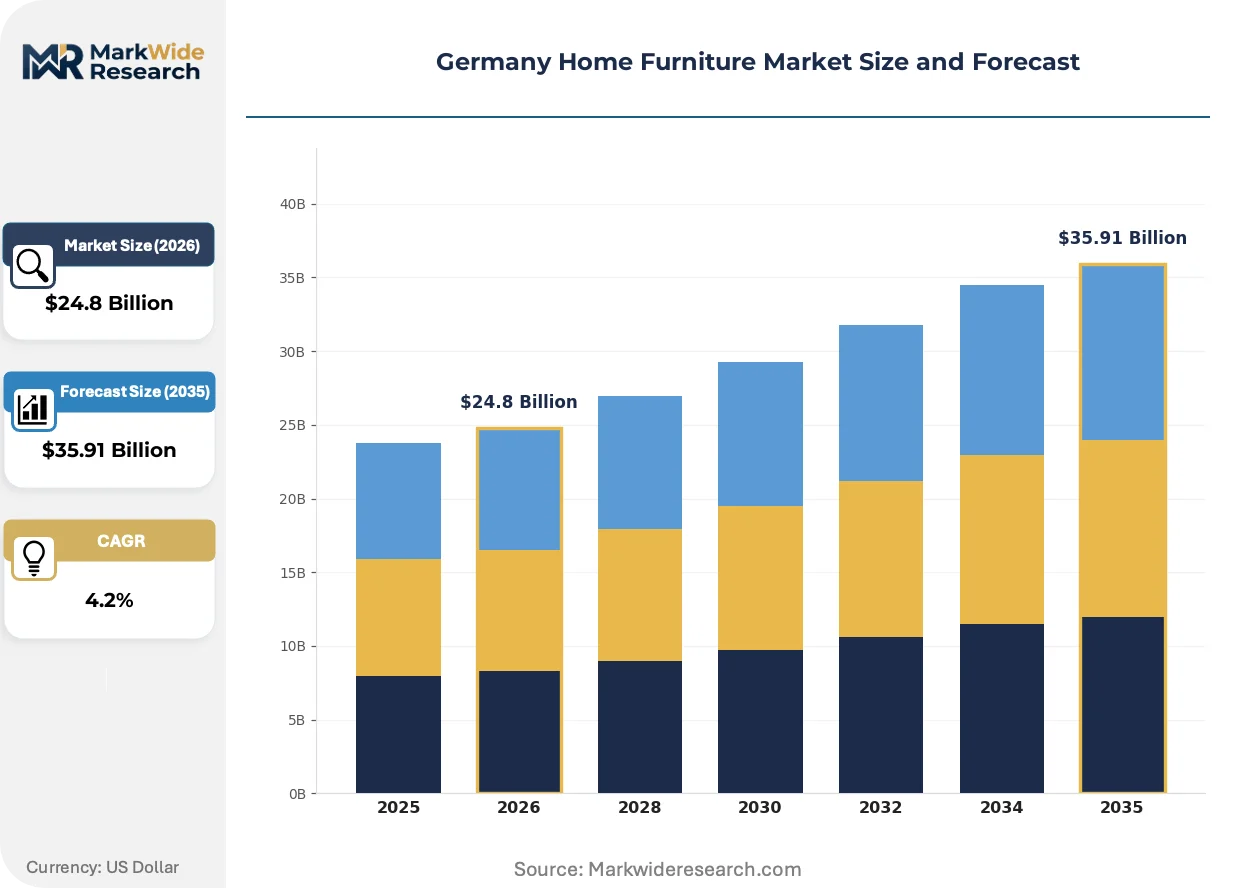
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $35.91 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Dining Sets, Beds, Cabinets, Tables, Chairs Material: Wood, Metal, Glass, Upholstery, Plastic, Rattan Application: Living Room, Bedroom, Dining Room, Home Office, Outdoor, Nursery Sales Channel: Offline Retail, E-commerce, Specialty Stores, Direct-to-Consumer, Wholesale |
| Companies Covered | Rauch Möbelwerke GmbH, Schmidt Küchen GmbH & Co. KG, IKEA, SieMatic, Rolf Benz AG & Co. KG, XXXLutz KG, Segmüller Polstermöbelfabrik GmbH & Co. KG, Welle Holding AG & Co. KG, Nobilia AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Home Furniture Market Shifts & Advancements
Digital configuration tools and sustainable material substitution are compressing traditional retail cycles while regulatory chemistry mandates force polyurethane and coating reformulation across upholstery and case goods production.
Parametric design software is expanding into German furniture manufacturing as a core production planning layer. Mid-market living room specialists adopt cloud-based customization engines that generate CNC-ready cutting patterns from consumer room dimensions. This capability is expanding into mass-market flat-pack segments previously constrained by standardized SKU economics.
EU Green Deal sustainability mandates are tightening formaldehyde emission thresholds and wood sourcing traceability requirements for panels sold to German households. Manufacturers must now maintain FSC or PEFC chain-of-custody documentation across tier-two suppliers. Bedroom and children's furniture categories face the steepest compliance burden given prolonged skin-contact exposure scenarios.
Berlin apartment dwellers are compressing replacement cycles for upholstered seating as rental turnover accelerates fabric wear and style obsolescence. Virtual showrooms with AR placement tools are displacing tactile material evaluation for younger demographics. Southern Germany retains showroom dependency for premium dining set purchases where grain matching and finish depth require physical assessment.
Germany Home Furniture Market Segmentation
Segmentation in the Germany home furniture market reveals divergent margin structures and regulatory exposure across material categories and sales channels. Manufacturers allocate factory capacity differently when serving Bavaria's solid-wood dining purchasers versus Berlin's flat-pack apartment furnishers.
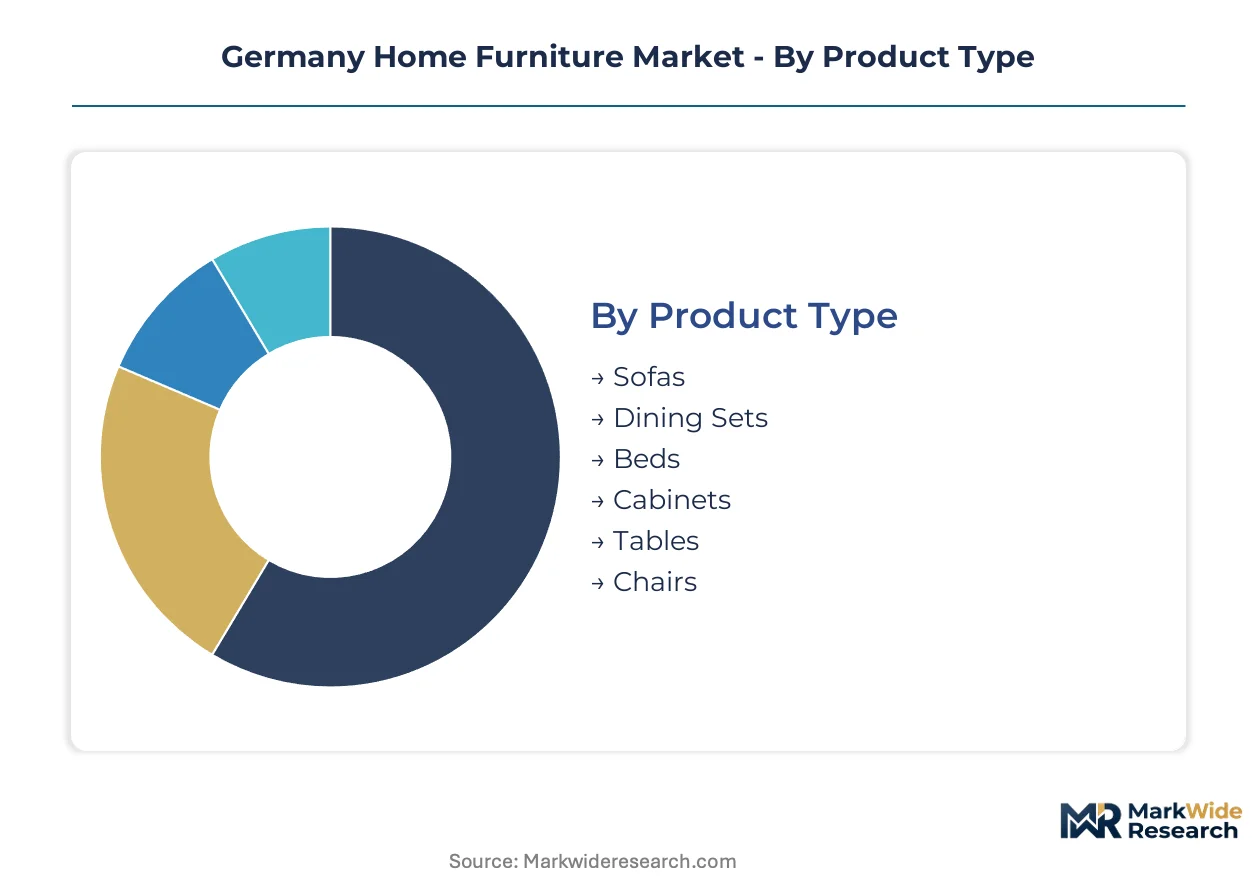
Product Type:
Volume concentration clusters in upholstered seating and bedroom systems, while premium pricing power concentrates in handcrafted dining and storage solutions.
- Sofas:Engineered with pocket-spring cores and high-resilience polyurethane foam cushioning, upholstered in fabric or leather covers. Demand concentrates in Berlin and Munich rental markets where tenant turnover accelerates replacement cycles driven by fabric wear and style obsolescence.
- Dining Sets:Solid oak and beech constructions employ 40mm-thick engineered tops with moisture-resistant lacquer finishes calibrated for Central European humidity cycles. Bavaria's higher disposable household incomes sustain demand for grain-matched premium sets requiring physical showroom evaluation.
- Beds:Upholstered frames and storage-integrated designs dominate value generation through shorter replacement cycles.
- Cabinets:Wall-mounted systems gain traction in micro-living units with sub-200cm footprint constraints.
- Tables:Multi-functional designs with extendable mechanisms address space efficiency requirements.
- Chairs:Ergonomic dining and accent seating complete coordinated room sets.
Mature deployment sits with sofas and beds. Newer deployment is concentrated in space-optimized cabinets and modular table systems.
Material:
REACH formaldehyde standards and FSC chain-of-custody requirements are reshaping procurement priorities across panel and solid-wood categories.
- Wood:Oak and beech supply faces sawmill capacity constraints in Central Europe, forcing manufacturers toward engineered alternatives or Baltic imports while maintaining Blue Angel ecolabel compliance.
- Upholstery:Fabric and leather coverings generate higher per-unit margins through shorter replacement cycles. F-Gas Regulation phase-downs of HFC blowing agents require polyurethane foam retooling for mattress and seating production.
- Metal:Steel and aluminum framing supports outdoor and home office furniture durability requirements.
- Glass:Tempered surfaces accent contemporary dining and accent table designs.
- Plastic:Polypropylene and polycarbonate enable lightweight, cost-competitive seating for mass-market channels.
- Rattan:Natural and synthetic weaves serve outdoor and conservatory applications with moisture resistance priorities.
Certified wood sourcing commands procurement attention. Upholstery materials face the steepest chemistry reformulation pressure.
Application:
Room-specific demand patterns align with housing typology—urban apartments versus suburban single-family residences—and corresponding storage density requirements.
- Living Room:Modular, space-efficient systems dominate Berlin and Munich micro-living specifications. Wall-mounted storage and convertible sofa beds with sub-200cm footprints address densification pressures.
- Bedroom:Built-to-order cabinetry with rapid configuration turnaround anchors premium positioning. Dual certification timelines for FSC and Blue Angel approvals extend product launch cycles.
- Dining Room:Solid-wood sets retain showroom dependency in southern Germany where grain matching requires tactile evaluation.
- Home Office:Ergonomic desk and storage configurations expand with remote work normalization.
- Outdoor:Weather-resistant materials face seasonal demand concentration.
- Nursery:Formaldehyde emission limits below 0.1 ppm impose strictest compliance burden given prolonged skin-contact exposure scenarios.
Living room and bedroom applications are expanding most quickly through e-commerce channels. Dining room retains offline retail dominance.
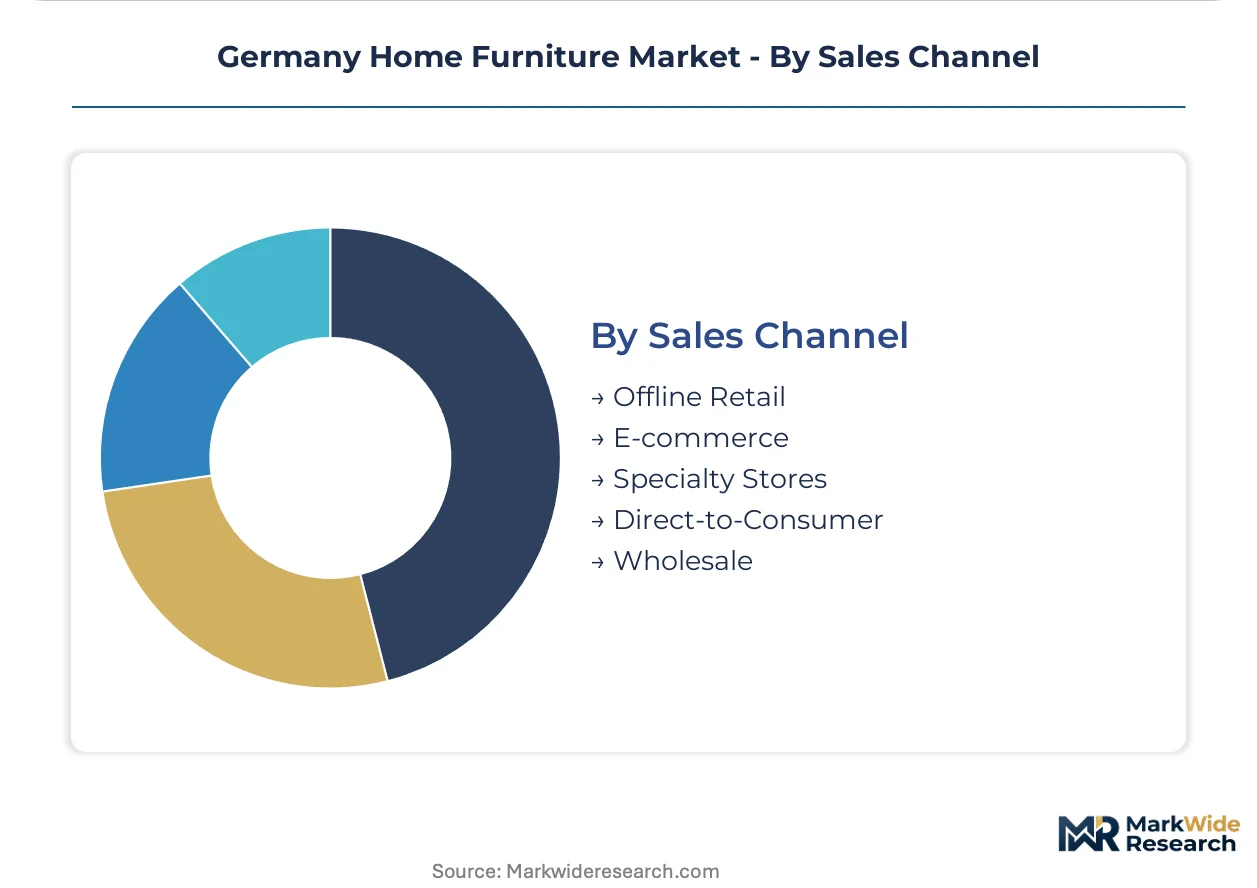
Sales Channel:
Channel economics diverge sharply between tactile material evaluation requirements and virtual configuration capabilities.
- Offline Retail:Physical showrooms sustain volume leadership through grain assessment for solid-wood dining sets and fabric texture evaluation for upholstered seating. Southern Germany retains highest showroom dependency.
- E-commerce:Augmented reality placement tools compress return rates for living room and bedroom purchases, enabling channel expansion beyond tactile evaluation constraints among younger demographics.
- Specialty Stores:Curated assortments serve premium bedroom and kitchen cabinetry segments.
- Direct-to-Consumer:Built-to-order models with rapid configuration turnaround bypass traditional retail markups.
- Wholesale:Bulk procurement serves multi-unit residential developers and hospitality furnishers.
Established volume flows through offline retail. Channel investment is concentrating in e-commerce configuration platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors furniture specification pull for micro-living units, while Bavaria's higher disposable incomes sustain premium demand for solid-wood dining and bedroom systems across southern Germany.
Bavaria
Solid oak dining sets and built-to-order bedroom cabinetry dominate Bavarian household purchases. The EU Green Deal's FSC chain-of-custody requirements filter procurement toward certified domestic sawmills. Munich's showroom concentration sustains tactile evaluation dependency for grain-matched premium furniture.
North Rhine-Westphalia
Rhine-Ruhr retrofit construction reshapes room dimensions and storage requirements in residential renovation. REACH formaldehyde emission limits below 0.1 ppm constrain panel sourcing for nursery and children's furniture. Cologne-Düsseldorf corridor manufacturers specialize in rapid-configuration kitchen cabinetry.
Baden-Württemberg
Ergonomic home office furniture demand accelerates with remote work normalization in Stuttgart and Karlsruhe. KBA vehicle certification standards regulate last-mile delivery fleet specifications, elevating distribution costs for flat-pack systems. Black Forest woodworking clusters maintain traditional joinery capacity for handcrafted dining sets.
Berlin-Brandenburg
Urban apartment densification drives specification pull for wall-mounted storage and convertible sofa beds with sub-200cm footprints. Berlin building energy efficiency codes reshape storage requirements in new residential construction. E-commerce channels expand fastest here as virtual room-planning tools reduce return rates among younger demographics.
Lower Saxony
Engineered wood panel production concentrates near sawmill corridors supplying Baltic import alternatives. F-Gas Regulation phase-downs of HFC blowing agents require polyurethane foam retooling for regional mattress manufacturers. Hanover-Braunschweig logistics hubs face last-mile rigidity constraints under KBA urban delivery standards.
Germany Home Furniture Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification compliance and configuration speed dimensions. The vendor base clusters around three strategic archetypes: vertically integrated sawmill-to-showroom operators, built-to-order rapid configurators, and mass-market scale retailers. Consolidation pressure intensifies as dual certification timelines for FSC and Blue Angel approvals extend product launch cycles. Capacity reallocation toward modular living room systems and circular material recovery capabilities represents the dominant competitive move set.
Within the integrated manufacturing tier, Rauch Möbelwerke GmbH and Welle Holding AG & Co. KG occupy positions anchored by captive wood supply control. Schmidt Küchen GmbH & Co. KG exemplifies the rapid-configuration archetype with built-to-order kitchen cabinetry specialization. At the scale-driven end, IKEA represents mass-market standardization across bedroom and storage categories.
| Leading Market Players |
|---|
| Rauch Möbelwerke GmbH |
| Schmidt Küchen GmbH & Co. KG |
| IKEA |
| SieMatic |
| Rolf Benz AG & Co. KG |
| XXXLutz KG |
| Segmüller Polstermöbelfabrik GmbH & Co. KG |
| Welle Holding AG & Co. KG |
| Nobilia AB |
| Others |
Supply & Pricing Matrix
Family-owned mid-caps with generational sawmill holdings anchor supply discipline across Bavaria and Baden-Württemberg, translating captive oak and beech access into pricing power that resists Baltic import undercutting. Their ownership structure insulates long-term procurement contracts from quarterly margin pressure, reinforcing stability in premium solid-wood dining segments where grain-matched certification commands persistent premiums.
Pricing Analysis
Value-based pricing anchored to FSC chain-of-custody certification and Blue Angel ecolabel compliance stratifies German home furniture across premium, standard, and economy tiers. Price differentiation separates certified solid-wood dining sets with documented provenance from particleboard alternatives facing REACH formaldehyde scrutiny. Cost compression in mass-market flat-pack living room systems is intensifying because KBA vehicle certification standards restrict last-mile delivery volumes, elevating per-unit distribution overhead. Berlin apartment renters exhibit highest price sensitivity for upholstered seating with accelerated replacement cycles, while Bavarian households show lowest sensitivity for handcrafted bedroom cabinetry requiring physical showroom evaluation.
Supply Chain Analysis
Single-source vulnerability sits with Central European sawmill capacity for oak and beech, forcing manufacturers toward Baltic imports from Estonia, Latvia, and Poland when domestic log supply tightens. Raw material dependencies center on engineered wood panels, high-resilience polyurethane foam cushioning, and moisture-resistant lacquer finishes calibrated for humidity cycles. Regulatory restriction risk concentrates in simultaneous FSC and Blue Angel certification timelines that extend product launch cycles. Distribution runs through 53-store mass-market networks for standardized bedroom systems alongside direct-to-consumer rapid-configuration platforms for built-to-order kitchen cabinetry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
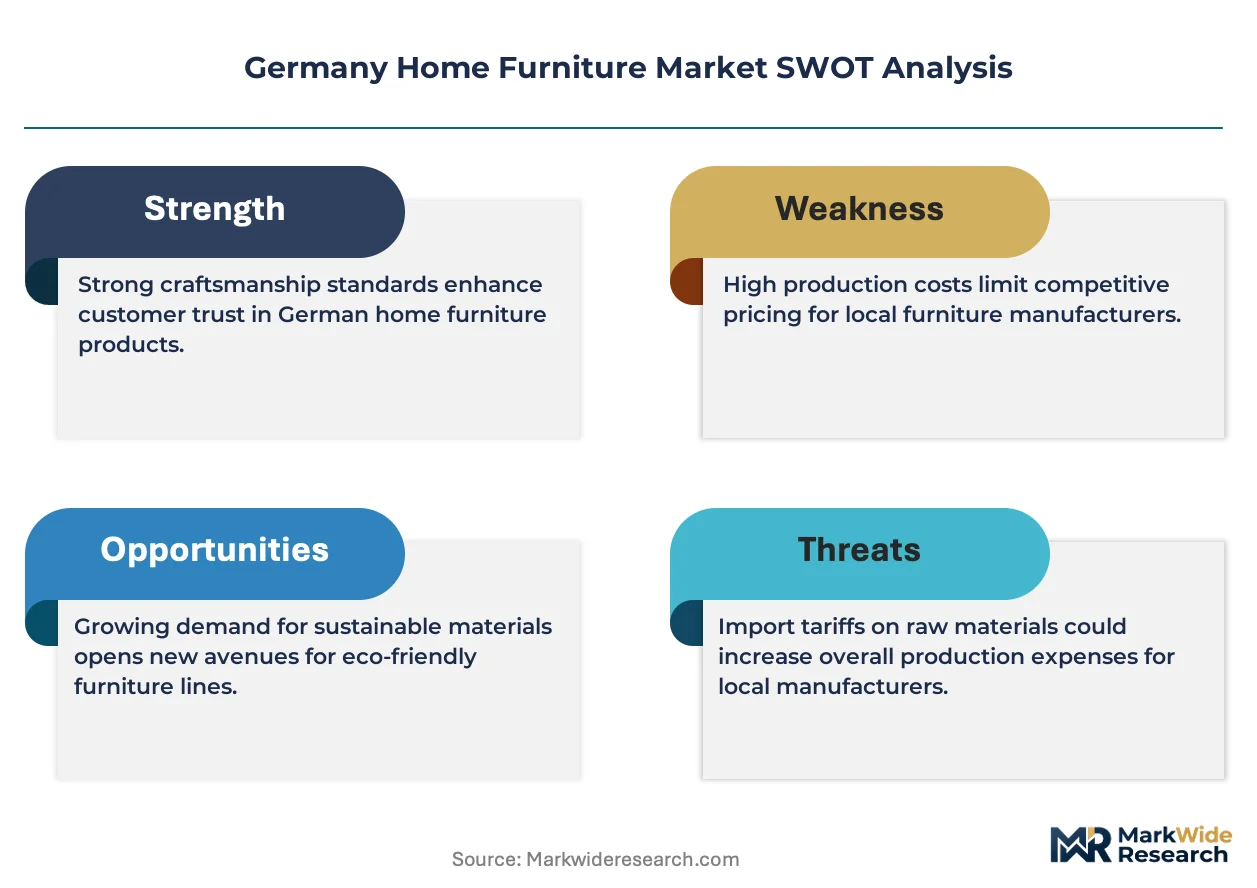
The Germany home furniture market reads as a cost-of-compliance story where EU Green Deal extended producer responsibility frameworks erect barrier-to-entry moats favoring incumbents with certified supply chain documentation and established ecolabel portfolios.
For Market Incumbents: Acquire distressed Baltic sawmill assets to secure oak and beech supply independence amid Central European capacity constraints. Consolidate regional craftsperson training pipelines to defend against vocational gaps threatening solid-wood dining production. Dual certification investment in FSC chain-of-custody and Blue Angel approvals represents the critical lever for premium bedroom positioning, while modular living room tooling expansion captures Berlin and Munich micro-living specification pull. For New Entrants and Emerging Players: EU Green Deal circular material recovery mandates in Germany open a window for furniture take-back service models targeting Berlin-Brandenburg rental markets with accelerated tenant turnover. White-space concentration sits in virtual room-planning tools with AR placement capabilities compressing e-commerce return rates for living room and bedroom purchases. Go-to-market execution should anchor in direct-to-consumer platforms bypassing traditional showroom markups, leveraging rapid-configuration software for built-to-order storage systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with captive sawmill assets and established FSC documentation in southern Germany over asset-light trading operations exposed to Baltic import volatility. Long-term viability across the analysis window hinges on backward integration into certified wood sourcing and circular recovery infrastructure. Watch cyclopentane transition completion rates among polyurethane foam suppliers as inflection indicator for upholstery margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Sawmills | FSC chain-of-custody control secures oak supply against Baltic import price volatility. |
| Circular Material Recovery Program | EU Green Deal extended producer responsibility creates revenue streams from furniture take-back. |
| Virtual Room-Planning Platform Launch | AR configuration tools compress return rates for e-commerce bedroom purchases in Berlin. |
| Rapid-Configuration Software Deployment | Cloud-based customization engines generate CNC-ready patterns for built-to-order cabinetry. |
| Cyclopentane Foam Retooling | F-Gas Regulation compliance transitions polyurethane blowing agents for upholstery production. |
Research Methodology
Independent corroboration across sawmill procurement directors, furniture manufacturing executives, and retail category buyers underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with production planners at solid-wood dining specialists, sustainability officers navigating dual certification timelines, and e-commerce operations heads deploying AR configuration tools. Secondary validation drew from KBA vehicle certification filings, EU Green Deal regulatory impact assessments, and FSC chain-of-custody audit records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the German residential construction and household consumption datasets.
Comparable-period anchoring employed historical reference spans of equivalent duration to the projection horizon, ensuring model calibration against full economic cycles including energy price shocks and regulatory implementation phases. Segmentation dimensions spanned product type, material certification tier, application room category, and sales channel format, with regional splits across Bavaria, North Rhine-Westphalia, Baden-Württemberg, Berlin-Brandenburg, and Lower Saxony. CAGRs were derived from fitted trend extrapolation adjusted for saturation effects in mature upholstered seating categories and acceleration factors in micro-living storage systems. Forecast inputs incorporated REACH formaldehyde threshold enforcement timelines and F-Gas phase-down schedules affecting polyurethane chemistry.
The model assumes a particular technology adoption path; alternative pathways for augmented reality room-planning penetration would alter the outlook for e-commerce channel share trajectories. Forecasts reflect assumptions regarding regulatory enforcement consistency, sawmill capacity expansion rates, and vocational training pipeline recovery. Specific risks that could revise projections include accelerated EU Green Deal timeline compression, Baltic import tariff restructuring, and cyclopentane supply constraints disrupting upholstery production. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
HORECA Furniture Market
Furniture
Children's Home Study Desks Market
Furniture
Brazil Furniture Market
Furniture
Exam Tables Market
Furniture
Pedicure Chair Market
Furniture
Japan Home Furniture Market
Furniture
Laminated Door Market
Furniture
Wooden Furniture Market
Furniture
North America Smart Furniture Market
Furniture
Cabinet Market
Furniture
Entryway Furniture Market
Furniture
Europe Furniture Market
Furniture
Asia-Pacific Contract Furniture Market
Furniture
Europe Multifunctional Furniture Market
Furniture
Europe Outdoor Furniture Market
Furniture
Global Smart Furniture Market