
 Collapsible Wardrobe Market | 2026-2036
Collapsible Wardrobe Market Size, Share, and Industry Trends Forecast 2026-2036
Collapsible Wardrobe Market Outlook
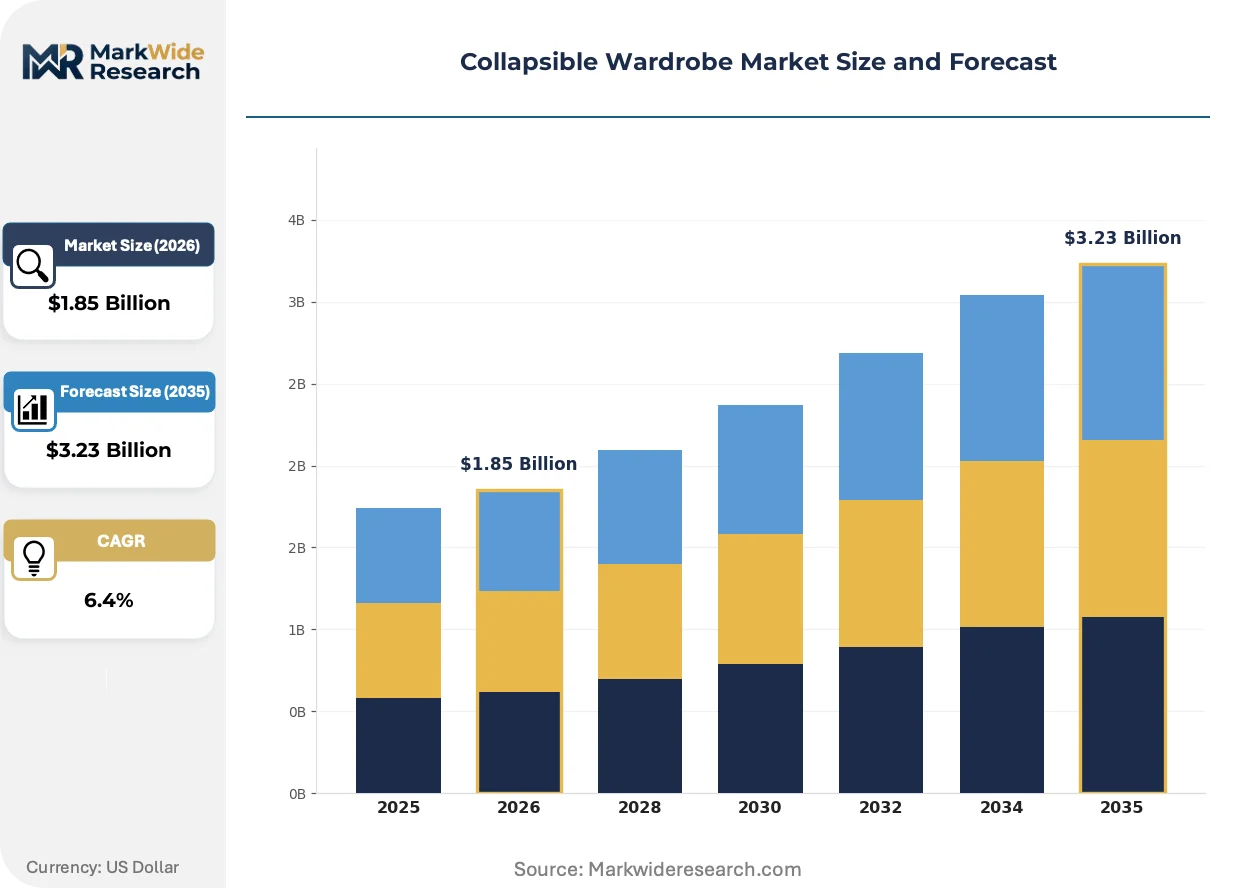
Subscription-based furniture rental services is repositioning how collapsible wardrobes reach end consumers, shifting ownership models from outright purchase to recurring revenue arrangements. IKEA Systems B.V. leverages its global logistics network to dominate flat-pack delivery and self-assembly positioning. Dorel Industries anchors its presence through multi-channel distribution across mass retail and e-commerce platforms. Sauder Woodworking Company specializes in engineered wood variants that balance cost compression with structural stability for frequent relocation cycles.
A collapsible wardrobe constitutes a demountable garment storage unit employing foldable frames, tension rods, and detachable fabric or rigid panel enclosures designed for rapid assembly, disassembly, and transport without permanent installation. Fabric variants typically utilize non-woven polypropylene or polyester canvas with powder-coated steel tube skeletons rated for 15-25 kilogram load capacity per hanging tier, serving residential, academic, and temporary commercial environments where spatial flexibility outweighs built-in permanence. Fabric wardrobes lead volume shipments due to minimal shipping cube and price accessibility, while metal wardrobes command margin pools in institutional procurement channels demanding extended duty cycles. Distribution through online retail accelerates fastest as direct-to-consumer brands bypass traditional furniture showroom economics, though specialty stores retain influence in tactile purchase decisions for premium design styles.
EPA formaldehyde emission standards under TSCA Title VI and California Air Resources Board certification constrain composite wood inputs across North American supply chains, while REACH and RoHS directives in Europe govern chemical content in metal finishes and plastic components. ISO 19833 furniture stability testing provides voluntary benchmarks that procurement officers in student housing and corporate relocation services increasingly embed as contractual requirements. Stakeholders must monitor how extended producer responsibility frameworks for furniture waste alter material recovery obligations and reshape end-of-life cost structures.
Market Dynamics
Subscription-based furniture rental services are fundamentally restructuring ownership models in the collapsible wardrobe market, converting one-time purchases into recurring revenue streams while embedding these units as standard furnishings in managed rental housing portfolios.
Growth Catalysts
- Rental Housing Platform Specifications:Furnished apartment operators now mandate collapsible wardrobes as baseline inventory, creating institutional procurement pipelines that bypass traditional retail channels entirely.
- REACH Compliance Pressures:European chemical safety directives restrict formaldehyde emissions in pressed-wood components, accelerating manufacturer migration toward low-emission adhesives and certified fabric liners that command premium positioning.
- Student Migration Patterns:Nuclear family formations and educational mobility toward tier-2 Indian cities expand addressable demand for portable storage solutions in academic and temporary residential settings.
Market Restraints
- Steel Tube Price Volatility:Powder-coated steel skeletons face input cost swings tied to global metallurgical commodity markets, compressing margin stability for fabric-variant producers.
- Concentrated Fabric Supply:Non-woven polypropylene liner production clusters in select East Asian manufacturing zones, exposing brands to single-source disruption risks.
- California Proposition 65 Liability:Warning label requirements for formaldehyde exposure create litigation exposure and inventory segregation costs for cross-border sellers.
Strategic Opportunities
- Southeast Asian Urbanization:Co-living operator expansion in Vietnam and Indonesia presents untapped demand for standardized, rapid-deploy furnishing solutions.
- ISO 19833 Certification Embedding:Voluntary furniture stability benchmarks are becoming contractual requirements in student housing procurement, creating differentiation pathways for tested products.
- Direct-to-Consumer Logistics Innovation:Flat-pack optimization and last-mile delivery partnerships enable brands to bypass showroom economics and capture margin pools previously allocated to retail intermediaries.
Industry Challenges
- Extended Producer Responsibility Compliance:Emerging furniture waste recovery frameworks in European jurisdictions impose end-of-life material sorting obligations that reshape cost structures and reverse logistics design.
- Load Capacity Certification Timelines:Third-party validation of 15-25 kilogram per-tier ratings requires extended laboratory testing cycles that delay product launches and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collapsible Wardrobe Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabric Wardrobe, Metal Wardrobe, Plastic Wardrobe, Wooden Wardrobe End User: Households, Students, Offices, Retailers Design Style: Modern, Vintage, Minimalist, Rustic Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | IKEA Systems B.V., Dorel Industries, Sauder Woodworking Company, Oppein Home Group, Suofeiya Home Collection Co., Ltd., Shenzhen Central Tide Industry & Trade Co. Ltd., Lifetime Products, Haworth, BBMG Tiantan Furniture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collapsible Wardrobe Market Strategic Shifts
Material science advances and regulatory tightening are converging to redefine product architecture and go-to-market economics across collapsible wardrobe manufacturing.
Modular tension-rod systems with tool-free assembly mechanisms are rewriting the user experience standard for frequent relocation cycles. Corporate relocation services and academic housing operators are adopting these configurations at accelerating rates. The technology is compressing installation labor costs and enabling same-day deployment that built-in alternatives cannot match.
EPA formaldehyde emission standards under TSCA Title VI and California Air Resources Board certification now constrain composite wood inputs across North American supply chains. Manufacturers are reformulating adhesive chemistries and substituting engineered wood with aluminum framing to maintain market access. Fabric-enclosed metal variants are capturing preference share in institutional channels where documentation requirements are most stringent.
Buyer concentration among platform-mediated rental housing operators is consolidating procurement decisions into centralized specification committees. Traditional furniture showrooms are losing influence as these operators negotiate direct supply agreements with manufacturers. This pattern is most visible in German and Dutch urban markets where co-living penetration rates lead continental adoption curves.
Collapsible Wardrobe Market Segmentation
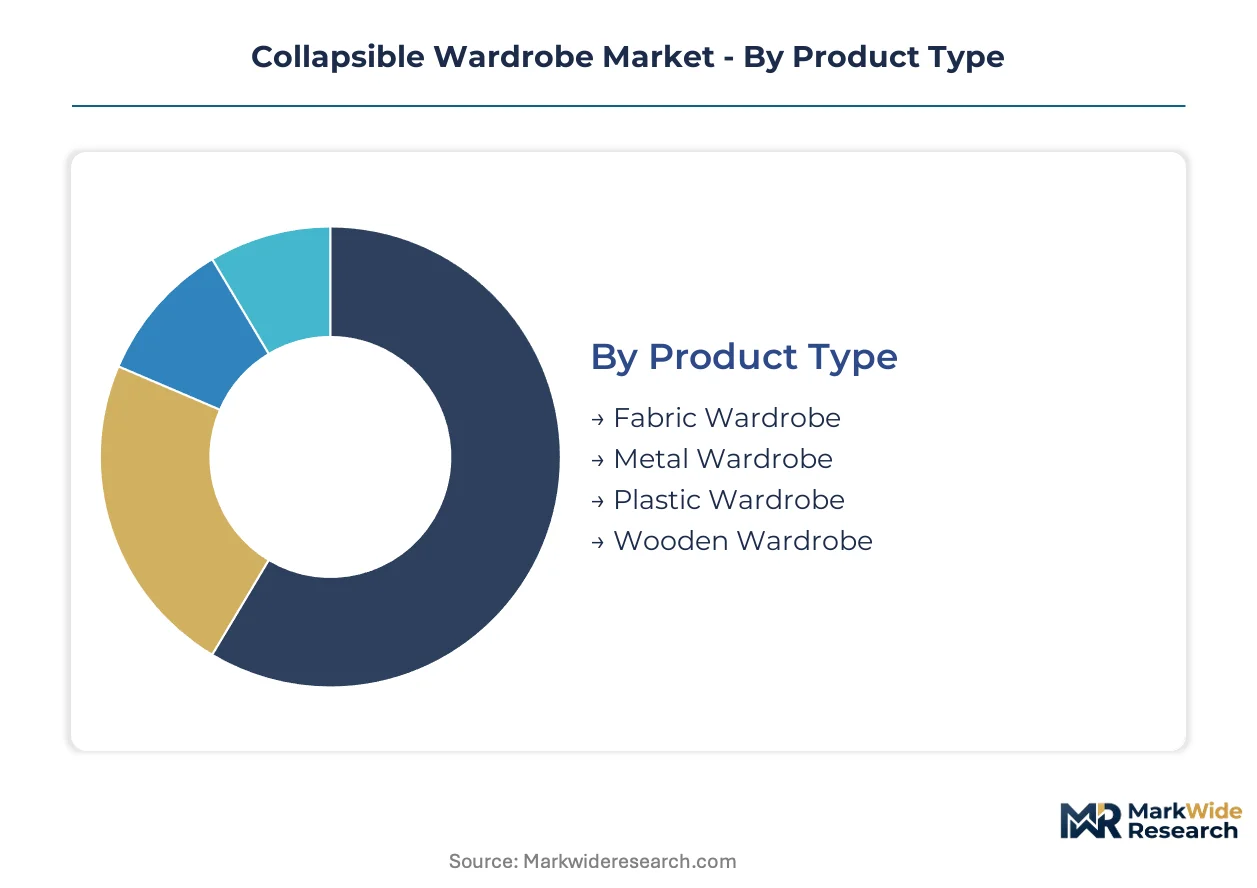
Collapsible wardrobe procurement patterns diverge sharply across use cases, with rental housing operators, academic institutions, and individual consumers each imposing distinct performance specifications and price tolerances. Understanding these segment boundaries clarifies where manufacturers must adapt product architecture versus where standardized platforms suffice.
Product Type:
Upgrade and replacement cycles vary dramatically by material composition, with fabric units refreshing every 2-3 years versus metal frames enduring 8-10 year service intervals.
- Fabric Wardrobe:Non-woven polypropylene or polyester canvas enclosures stretched over powder-coated steel tube skeletons rated for 15-25 kilogram loads per tier. Demand clusters in student housing and co-living deployments across India and Vietnam where frequent relocation cycles prioritize portability over longevity.
- Metal Wardrobe:Aluminum or steel framing with rigid panel enclosures, engineered for institutional procurement channels demanding ISO 19833 stability certification and extended duty cycles. Corporate relocation services and furnished apartment operators in Germany and the Netherlands specify these for standardized inventory.
- Plastic Wardrobe:Injection-molded polypropylene assemblies targeting budget-conscious household segments in Southeast Asian urban markets.
- Wooden Wardrobe:Engineered wood or bamboo variants constrained by REACH formaldehyde limits and California Proposition 65 labeling requirements, capturing niche premium positioning.
Volume placements concentrate in fabric variants; the faster expansion belongs to metal configurations as institutional procurement specifications tighten.
End User:
Cost tier stratification separates mass-market household purchases from contract-negotiated institutional volumes.
- Households:Individual consumers purchasing through online retail or specialty stores, with decisions driven by spatial constraints in urban rental units and price accessibility.
- Students:Academic housing operators and platform-mediated rental services specifying standardized units for furnished dormitories and off-campus housing, creating concentrated procurement pipelines that bypass traditional retail.
- Offices:Corporate facilities managers sourcing temporary storage for hot-desking environments and relocation staging, with stability documentation requirements rising.
- Retailers:Commercial display and back-of-house inventory management applications, typically sourcing through direct manufacturer relationships.
Households generate the highest unit volumes; student housing procurement is climbing the fastest as migration to tier-2 Indian cities accelerates.
Design Style:
Application context dictates aesthetic requirements, with co-living operators favoring neutral palettes that photograph uniformly across property listings.
- Modern:Clean lines and neutral colorways dominating platform-mediated rental housing specifications, particularly in German and Dutch urban markets where co-living penetration leads continental curves.
- Minimalist:Reduced visual footprint designs capturing preference in Japanese compact living environments and Scandinavian-influenced European segments.
- Vintage:Retro-styled metal frames and canvas treatments appealing to boutique hospitality and themed accommodation operators.
- Rustic:Wood-grain finishes and natural material aesthetics targeting rural vacation rental markets and heritage property conversions.
Modern styling commands the largest placement base; minimalist variants are gaining share fastest as space-constrained urbanization intensifies.
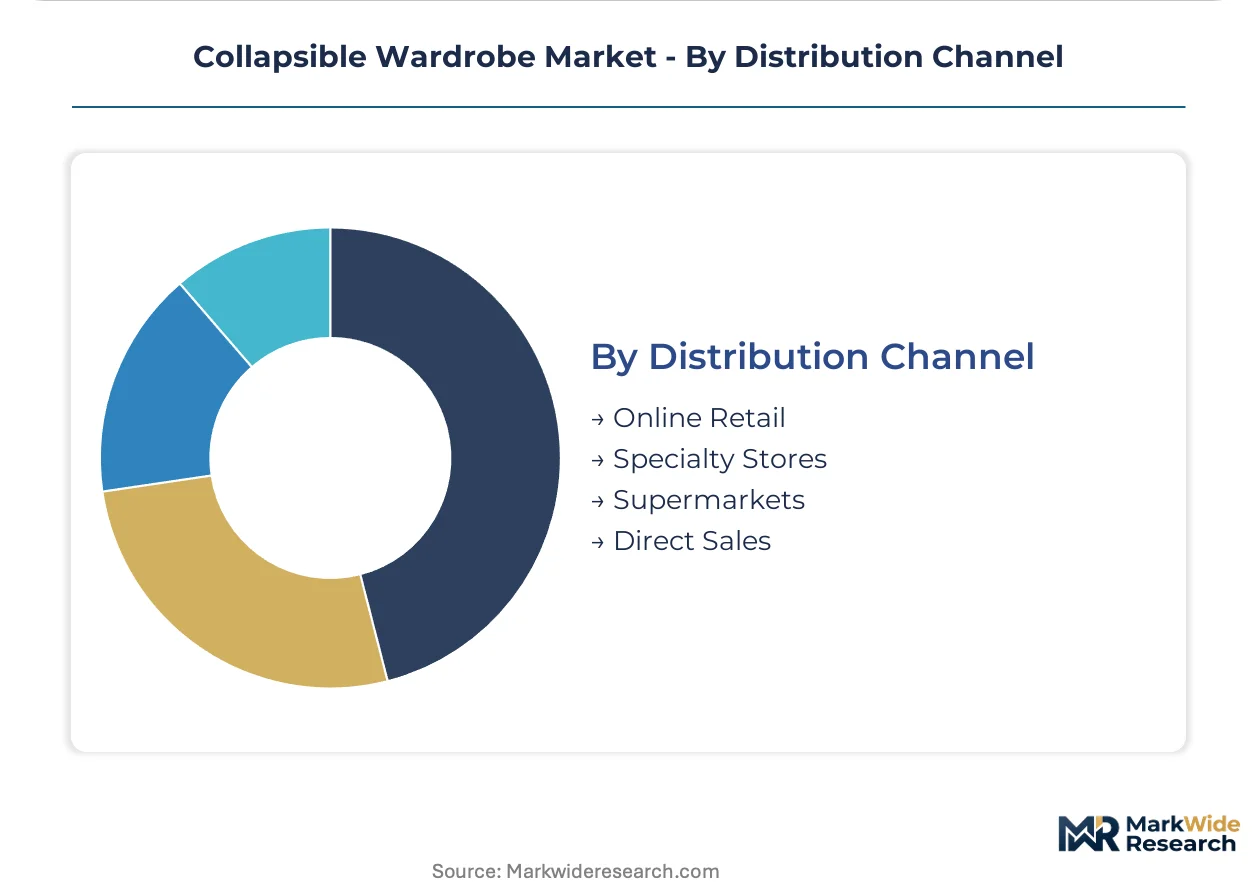
Distribution Channel:
Supply concentration in East Asian manufacturing clusters shapes channel economics, with direct-to-consumer brands capturing margin pools previously allocated to retail intermediaries.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling flat-pack optimization and last-mile delivery partnerships, accelerating fastest as showroom economics erode.
- Specialty Stores:Tactile purchase environments retaining influence in premium design segments where material quality assessment precedes commitment.
- Supermarkets:Mass-market fabric variants positioned as impulse or seasonal purchases, with limited SKU depth and compressed margins.
- Direct Sales:Manufacturer-to-operator contracts with rental housing platforms and co-living chains, consolidating procurement decisions into centralized specification committees.
Online retail captures the steepest expansion trajectory; direct sales channels secure the highest contract values per placement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters dominate collapsible wardrobe production, while consumption concentrates in urbanizing markets across India, Southeast Asia, and European co-living corridors. This geographic split shapes logistics networks and regulatory compliance requirements across supply chains.
India
Student migration to tier-2 cities including Pune, Jaipur, and Lucknow is expanding demand for portable storage solutions in academic housing and co-living developments. BIS certification requirements for furniture safety are tightening procurement specifications for institutional buyers. Manufacturing activity clusters in Gujarat and Maharashtra, where fabric enclosure suppliers serve both domestic consumption and export markets.
Germany
Co-living operator penetration in Berlin, Hamburg, and Munich is consolidating procurement decisions into centralized specification committees that mandate ISO 19833 stability certification. REACH compliance for formaldehyde emissions and metal finish chemistries constrains supplier qualification. The North Rhine-Westphalia industrial corridor hosts distribution hubs serving Dutch and Belgian cross-border demand.
Vietnam
Urban co-living expansion in Ho Chi Minh City and Hanoi is generating institutional demand for rapid-deploy furnishing solutions compatible with frequent relocation cycles. The country's national standards body is aligning furniture safety regulations with ASEAN harmonization frameworks. Manufacturing concentration in Binh Duong Province supplies fabric-variant components to regional assembly operations.
United States
Rental housing platform specifications in Texas, Florida, and California are embedding collapsible wardrobes as standard furnished apartment inventory. EPA formaldehyde emission standards under TSCA Title VI and California Air Resources Board certification constrain composite wood inputs across supply chains. Distribution logistics optimize through Southern California and Dallas-Fort Worth last-mile nodes.
Netherlands
Platform-mediated rental housing operators in Amsterdam, Rotterdam, and Utrecht are negotiating direct supply agreements that bypass traditional furniture retail channels. ECHA enforcement of REACH chemical safety directives governs metal finishes and fabric liner content. The Randstad logistics network enables rapid replenishment cycles for co-living property managers.
Collapsible Wardrobe Market Competitive Environment
Top-tier vendors anchor flat-pack logistics and global retail networks, while mid-tier fabricators compete on regional customization and institutional procurement responsiveness. The market structure reflects a bifurcation between scale-driven players with captive supply chains and specialized operators serving niche certification requirements. Strategic archetypes include global flat-pack retailers, engineered wood specialists, and direct-to-consumer logistics innovators. Competitive moves center on backward integration into fabric and steel tube production, plus certification pre-positioning for REACH and ISO 19833 compliance.
Among flat-pack retail specialists, IKEA Systems B.V. exemplifies the global logistics archetype through standardized self-assembly positioning. Dorel Industries and Sauder Woodworking Company represent North American-engineered wood and multi-channel distribution approaches. Chinese fabricators including Oppein Home Group, Suofeiya Home Collection Co., Ltd., and Shenzhen Central Tide Industry & Trade Co. Ltd. occupy positions serving both domestic consumption and export assembly relationships.
| Leading Market Players |
|---|
| IKEA Systems B.V. |
| Dorel Industries |
| Sauder Woodworking Company |
| Oppein Home Group |
| Suofeiya Home Collection Co., Ltd. |
| Shenzhen Central Tide Industry & Trade Co. Ltd. |
| Lifetime Products |
| Haworth |
| BBMG Tiantan Furniture |
| Others |
Value Chain & Pricing Dynamics
REACH formaldehyde emission limits and California Proposition 65 warning requirements gate qualified supply access and premium-tier pricing power, bifurcating manufacturers between certified fabric-liner producers commanding institutional premiums and uncertified competitors confined to mass-market economy positioning.
Pricing Analysis
Margin tightening in economy-tier fabric variants reflects steel tube input volatility and concentrated polypropylene supply from East Asian manufacturing zones. Three-tier pricing structure across premium ISO 19833-certified metal frames, mid-tier REACH-compliant fabric units, and economy-grade uncertified alternatives separates institutional procurement from household impulse purchases. Cost-down pressure on fabric wardrobes accelerates as rental housing operators consolidate volume negotiations. Students and co-living residents exhibit highest price sensitivity; corporate relocation services show lowest sensitivity due to stability documentation requirements.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia, Dallas-Fort Worth, and Randstad optimize hub-and-spoke patterns for flat-pack inventory replenishment. Manufacturing concentrates in China, Vietnam, and India, with fabric enclosure production clustering in Binh Duong Province and Gujarat. Raw material dependencies span powder-coated steel tubes, non-woven polypropylene, and low-emission adhesive chemistries. Single-source vulnerability in East Asian polypropylene supply exposes brands to disruption. Distribution runs through direct-to-consumer platforms, manufacturer-direct contracts with rental operators, and residual specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 19833 certification capacity constraints prop pricing premiums as institutional procurement pipelines expand faster than qualified supplier validation timelines.
For Market Incumbents: Anticipate margin compression from direct-to-consumer entrants by embedding backward integration into steel tube and fabric liner production. Defend institutional channel position through preemptive REACH and Proposition 65 certification renewal cycles. Capacity expansion in Gujarat and Binh Duong Province secures supply continuity against East Asian concentration risk. For New Entrants and Emerging Players: Tool-free modular tension-rod systems offer technology-first wedge into student housing procurement in tier-2 Indian cities. White-space targets include Vietnam co-living operator direct contracts and Japanese minimalist design segments. Go-to-market angle centers on same-day deployment capability and ISO 19833 pre-certification. For Investors and Strategic Acquirers: Consolidation of rental housing platform procurement committees into centralized specification bodies is the leading indicator that institutional channel access is narrowing to certified incumbents. Long-term viability favors manufacturers with captive REACH-compliant supply chains and established direct sales relationships with co-living operators. Acquisition target archetype: regional fabricators with latent ISO 19833 certification progress and underutilized capacity in India or Vietnam. Signal to monitor: BIS safety standard harmonization triggering import qualification barriers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 19833 Certification Pre-Positioning | Institutional procurement committees in Germany and the Netherlands mandate stability documentation for contract eligibility. |
| Backward Integration into Steel Tube Production | Captive supply of powder-coated skeletons insulates margin from metallurgical commodity volatility. |
| Direct-to-Consumer Logistics Partnership | Last-mile flat-pack optimization captures margin pools previously allocated to furniture showroom intermediaries. |
| REACH-Compliant Adhesive Reformulation | Low-emission chemistry substitution maintains European market access against formaldehyde restriction tightening. |
| Co-Living Operator Direct Supply Agreement | Centralized procurement consolidation in Amsterdam and Berlin bypasses traditional retail channel economics. |
Study Parameters
Trade databases, customs filings, and furniture industry association reports formed the secondary backbone, supplemented by primary interviews with co-living property managers, student housing procurement officers, flat-pack logistics coordinators, and REACH compliance consultants. Bottom-up triangulation across product-type shipment estimates and top-down validation against end-user expenditure patterns anchored volume and value outputs.
Bottom-up modeling segmented the market by material composition, end-user category, design aesthetic, and distribution channel across the projection horizon. CAGRs derived from fitted trend lines applied to historical shipment data, adjusted for regulatory phase-in schedules and urbanization migration patterns. Forecast inputs incorporated BIS certification timeline assumptions and co-living operator expansion trajectories in Vietnam and Indonesia.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel price spike scenarios or single-source polypropylene disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Cabinet & Furniture Drawer Slides Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Hong Kong Self-Storage Market