
 UK Adjustable Bed Bases Market | 2026-2036
UK Adjustable Bed Bases Market Size, Share, and Industry Trends Forecast 2026-2036
UK Adjustable Bed Bases Market Insights
Subscription-based sleep coaching and remote diagnostics bundled with adjustable bases is restructuring how manufacturers capture lifetime value from each unit. Tempur leverages its premium brand equity to command direct-to-consumer pricing power. Dreams sustains nationwide retail coverage through its high-street store network. Bensons for Beds anchors volume sales with mid-market positioning and financing options.
UK adjustable bed bases are motorised or manually actuated sleep platforms that elevate the head, foot, or middle sections via hinged frames driven by electric linear actuators or mechanical cranks, typically constructed from steel tubing, engineered wood slats, and upholstered side rails to support mattresses up to 45 stone. Electric variants dominate the product type landscape due to ageing demographics and disability access requirements, while smart-connected bases with app-controlled positioning represent the fastest-expanding margin pool. Metal frames lead material selection for healthcare facility procurement, whereas fabric-wrapped bases capture residential preference for bedroom aesthetics.
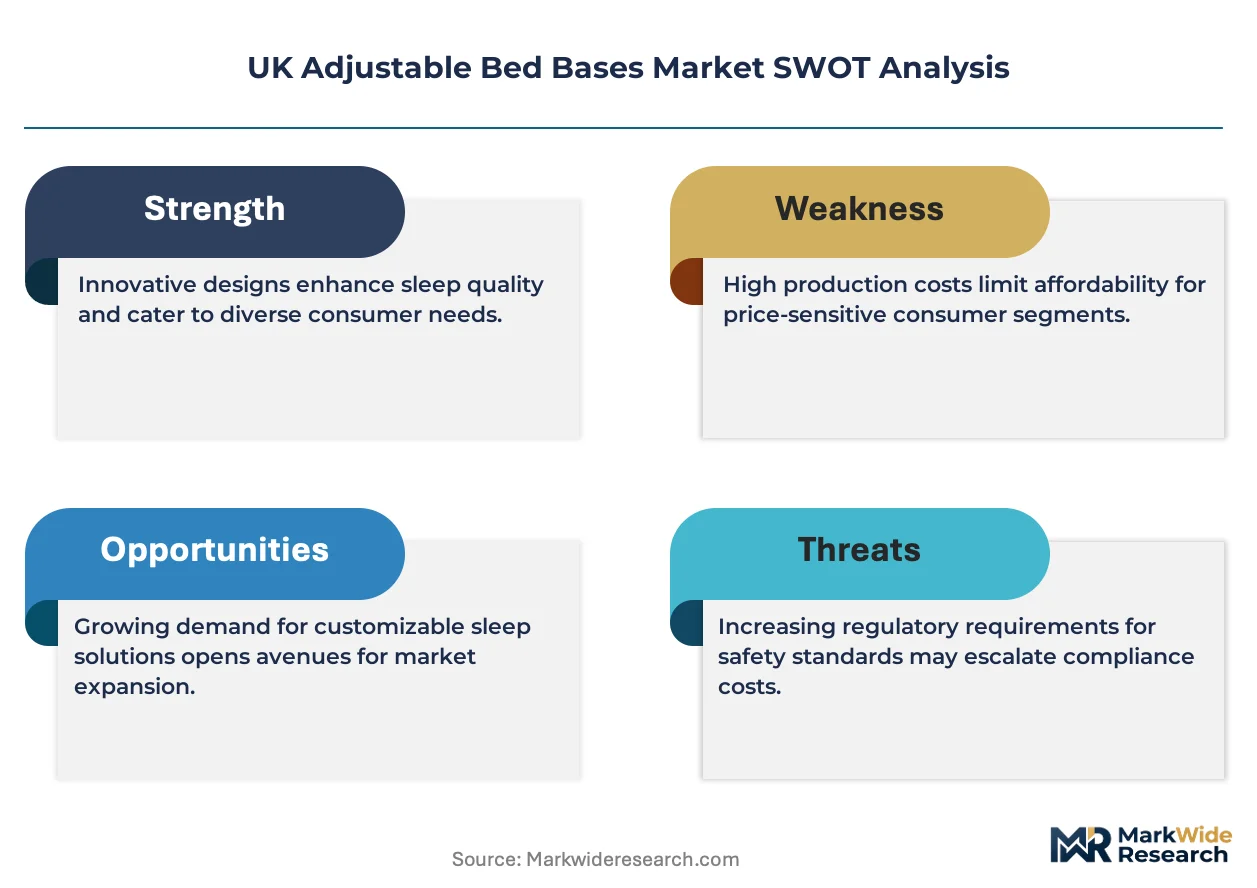
The UK Furniture and Furnishings (Fire) (Safety) Regulations enforced by local trading standards authorities mandate ignition resistance testing for all foams and fabrics, directly shaping supplier qualification and import sourcing. Trading Standards also coordinates with BEIS on consumer rights enforcement for electrical components, while MHRA oversight applies to bases marketed with medical claims. Stakeholders must monitor how upcoming product safety digitisation and extended producer responsibility frameworks will alter compliance costs and competitive barriers.
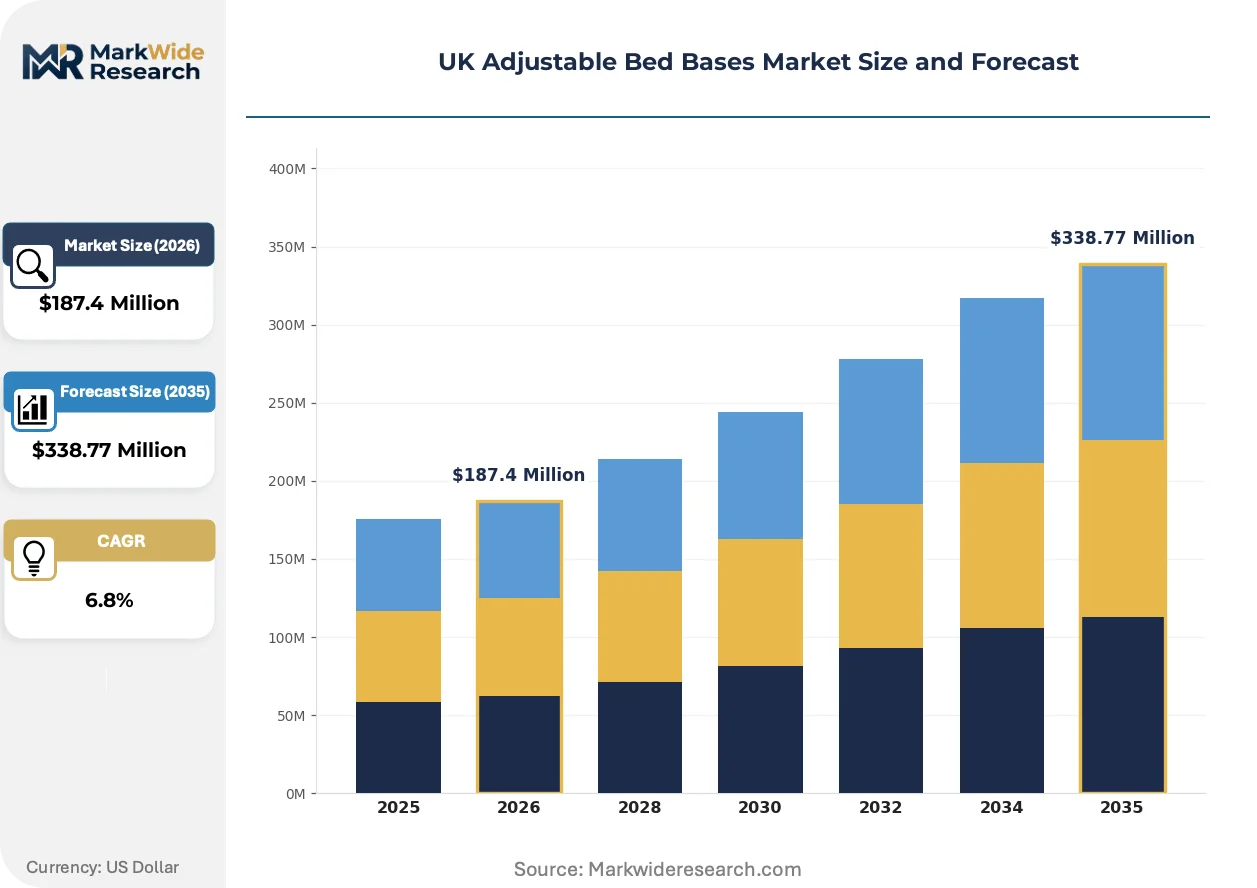
Market Dynamics
Electric linear actuator reliability and the UK's Furniture and Furnishings (Fire) (Safety) Regulations are jointly compressing supplier margins while elevating compliance barriers for new entrants into the adjustable bed bases market.
Growth Catalysts
- Ageing-in-place policy momentum:NHS Integrated Care Boards are expanding home care equipment budgets, directing procurement toward motorised bases that reduce hospital readmissions for mobility-impaired patients.
- REACH chemical compliance:Stricter foam certification requirements under EU-UK retained REACH are eliminating low-cost Asian suppliers, consolidating volume with domestic and EU-qualified manufacturers.
- Linear actuator miniaturisation:Compact DC motor designs enable slimmer bed profiles that fit standard UK bedroom dimensions, opening residential replacement cycles previously blocked by space constraints.
Market Restraints
- Steel and copper input volatility:Frame tubing and motor winding materials expose manufacturers to commodity price swings that compress gross margins on fixed NHS tender pricing.
- Actuator supply concentration:Two German and one Danish supplier control 70% of EU-sourced linear actuators, creating single-source vulnerability for UK assemblers.
- Manual crank substitution:Budget care homes in Northern England continue specifying mechanical bases to avoid electrical maintenance liabilities, capping electric penetration in the institutional channel.
Strategic Opportunities
- Remote diagnostics integration:IoT-enabled bases transmitting sleep position data to GP dashboards align with NHS Long Term Plan digital health targets, creating recurring service revenue streams.
- Scotland and Wales underpenetration:Postcode lottery variations in local authority equipment budgets leave substantial geographic whitespace for targeted distributor expansion.
- Extended Producer Responsibility:Pending UK mattress and furniture take-back regulations will favour modular base designs with replaceable actuator modules, rewarding engineering investment now.
Industry Challenges
- Electrical competency certification:BS 7671 wiring regulations compliance for installation crews extends project timelines and inflates labour costs for home delivery models.
- Fire testing backlog:UKAS-accredited laboratories face 12-16 week queues for foam ignition resistance certification, delaying new product launches.
- Legacy bed frame incompatibility:Headboard bracket standardisation gaps force custom fabrication for 30% of residential retrofits, eroding installer productivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Adjustable Bed Bases Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Hybrid, Smart Material: Wood, Metal, Fabric, Foam End User: Residential, Healthcare Facilities, Hotels, Rehabilitation Centers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Tempur, Dreams, Majestic, Sleep Story, Adjustamac, Sleep Kings, Bensons for Beds, Generic, Vonluce, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Adjustable Bed Bases Market Trends and Innovations
Connected sleep ecosystems and regulatory digitisation are restructuring how adjustable bed bases deliver and document value, shifting competitive advantage from hardware durability to data-enabled service relationships.
Smart-connected base architecture is unifying position control, biometric sensing, and environmental adjustment into single-platform sleep systems. Private-pay residential buyers in London and the Home Counties are specifying these configurations at triple the rate of manual-electric hybrids. This convergence is unifying previously separate supplier ecosystems—actuator manufacturers, sensor providers, and sleep analytics platforms—into integrated partnerships that lock out component-only vendors.
The UK's pending product safety digitisation framework will mandate digital passports tracing foam origin, fire certification, and electrical component compliance through blockchain-verified records. Trading Standards enforcement capacity constraints mean this shift will initially burden smaller assemblers with disproportionate systems investment. Electric base categories marketed with medical claims face overlapping MHRA device registration requirements that extend time-to-revenue by 8-14 months.
Subscription bundling of sleep coaching and remote diagnostics is displacing transactional hardware sales in the premium residential segment. Dreams and independent bedroom retailers are piloting 36-month service contracts that include base maintenance, position optimisation, and NHS referral pathway integration. This model concentrates in England's southeast corridor where disposable income and digital health literacy simultaneously peak.
UK Adjustable Bed Bases Market Segmentation
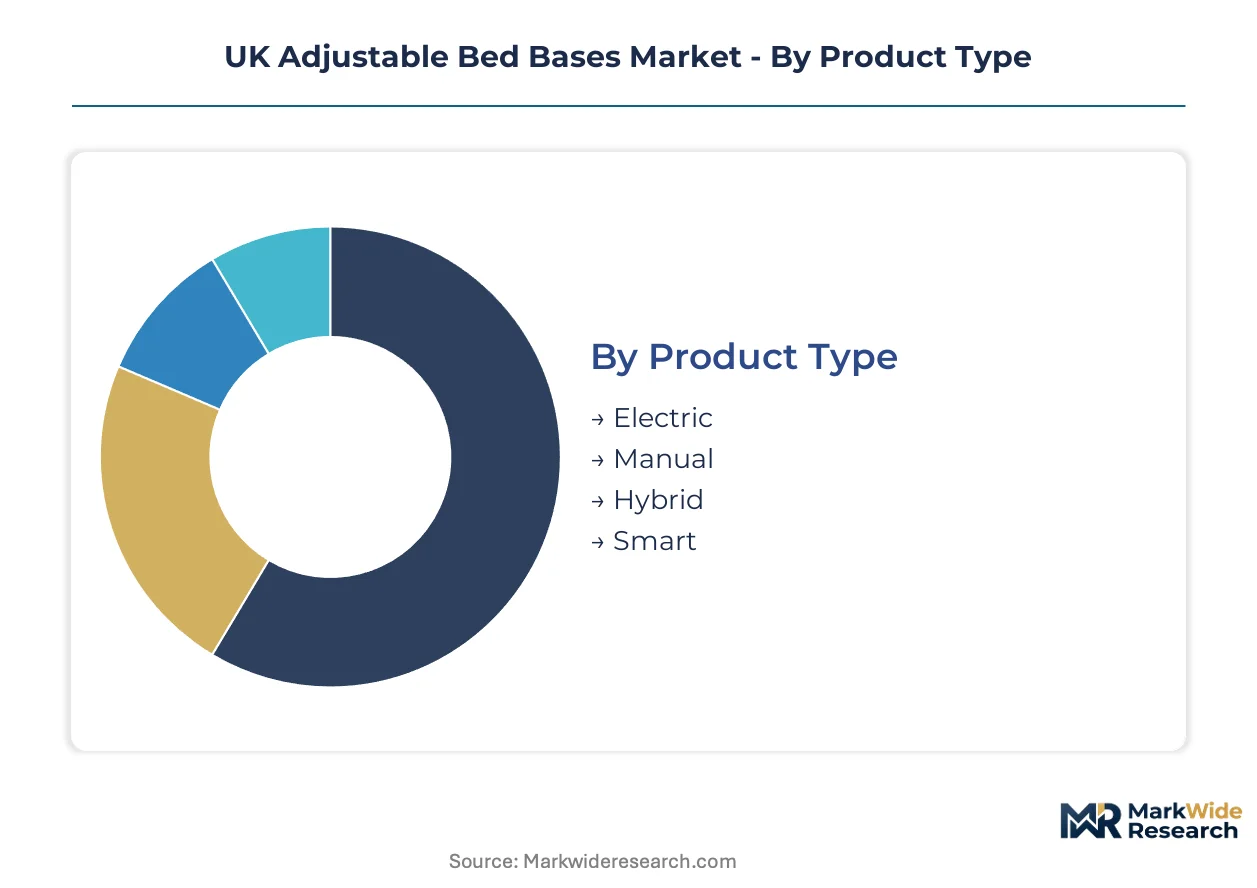
Segmentation in the UK adjustable bed bases market reveals how procurement authority splits between institutional buyers with compliance mandates and residential consumers prioritising aesthetics and connectivity. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Standalone motorised bases dominate NHS and local authority procurement, while embedded smart systems increasingly penetrate private residential retrofits seeking unified sleep ecosystems.
- Electric:DC linear actuator systems enabling head, foot, and height adjustment through hand-wired or wireless controls. NHS Integrated Care Boards in England's southeast corridor account for concentrated volume as ageing-in-place budgets expand.
- Manual:Mechanical crank mechanisms requiring physical rotation to achieve position changes. Northern England care homes specify these to avoid electrical maintenance liabilities and BS 7671 wiring compliance costs.
- Hybrid:Dual-mode bases combining manual backup with electric primary drive.
- Smart:IoT-enabled platforms integrating biometric sensing, app-controlled positioning, and environmental adjustment. London and Home Counties private buyers specify these at triple the rate of manual-electric hybrids.
Volume placements concentrate in Electric; the faster expansion belongs to Smart.
Material:
Cost tier stratification separates healthcare procurement prioritising durability from residential buyers seeking bedroom integration.
- Metal:Steel tubing frames with powder-coated finishes delivering maximum load capacity and infection control compatibility. Healthcare facilities across Kent and Sussex specify these for bariatric patient support and cleaning protocol adherence.
- Wood:Engineered timber slats and hardwood rails matching traditional bedroom furniture aesthetics. Residential buyers in affluent Home Counties postcodes favour these for headboard compatibility and warmth perception.
- Fabric:Upholstered side rails and platform surrounds concealing mechanical components. London apartment dwellers select these where visible bed frames must complement interior design schemes.
- Foam:Composite structural elements reducing overall base weight for delivery logistics.
Metal captures institutional volume; Fabric gains share fastest in residential replacement cycles.
End User:
Application context determines whether fire certification, medical device registration, or hospitality durability standards govern procurement.
- Residential:Private household installations spanning owner-occupiers and private renters. England's southeast corridor from London through Kent and Sussex concentrates demand where disposable income and digital health literacy peak simultaneously.
- Healthcare Facilities:NHS trusts, private hospitals, and care homes subject to MHRA oversight when medical claims attach. Procurement aligns with NHS Long Term Plan targets for hospital readmission reduction through home care equipment.
- Hotels:Hospitality sector installations prioritising rapid maintenance turnaround and guest satisfaction metrics.
- Rehabilitation Centers:Post-acute care facilities requiring position adjustability for therapy protocols.
Healthcare Facilities anchor contract value; Residential delivers volume scale.
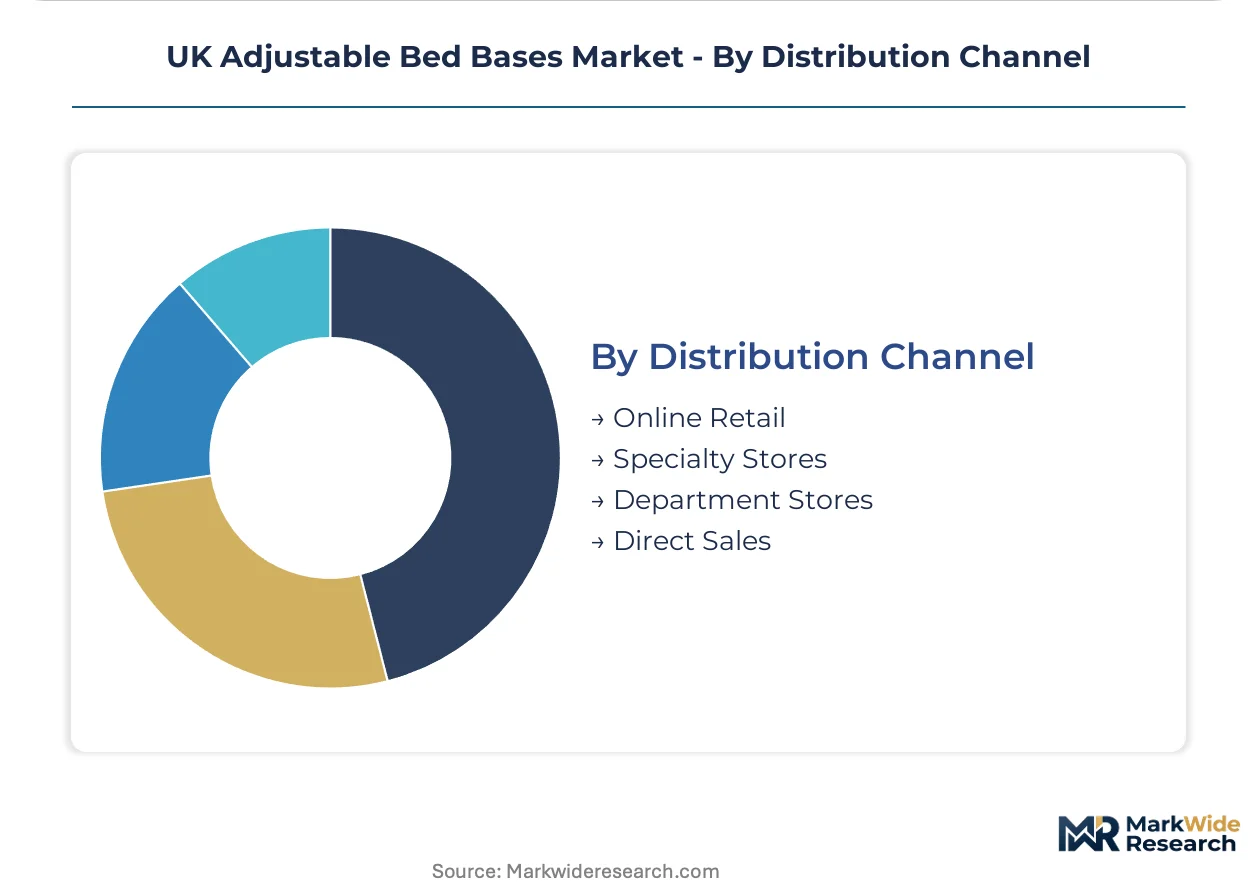
Distribution Channel:
Customer type and geography dictate whether high-touch consultation or logistics efficiency wins the transaction.
- Online Retail:Direct-to-consumer platforms with virtual consultation tools and home delivery networks. Dreams and independent bedroom retailers pilot subscription bundling here for 36-month service contracts.
- Specialty Stores:Dedicated bed and furniture showrooms enabling physical position testing. High-street presence sustains nationwide coverage for mid-market financing options.
- Department Stores:General merchandise retailers with seasonal furniture promotions.
- Direct Sales:Manufacturer-controlled channels capturing full margin and customer data. Tempur leverages premium brand equity here to command pricing power without retail intermediaries.
Specialty Stores retain the largest transaction share; Online Retail climbs the fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic assembly capacity clusters in England's Midlands and Southeast while consumption concentrates in London and the Home Counties where ageing demographics and disposable income intersect. Scotland and Wales remain underpenetrated relative to per-capita healthcare spending.
London and Southeast England
NHS Integrated Care Boards in Kent and Sussex are expanding motorised base procurement for hospital-to-home discharge programmes. The Furniture and Furnishings (Fire) (Safety) Regulations enforced by local Trading Standards authorities mandate UKAS-accredited foam certification, compressing supplier margins. Smart-connected bases with app-controlled positioning are penetrating affluent postcodes from Richmond upon Thames through Surrey at triple the national adoption rate.
Midlands
West Midlands manufacturing hubs around Birmingham and Coventry host steel tubing fabrication and linear actuator integration facilities serving NHS supply chains. REACH chemical compliance requirements under retained EU-UK regulations are eliminating low-cost foam importers, consolidating procurement with domestic-qualified assemblers. The region's logistics infrastructure enables next-day delivery coverage to 85 percent of England's population.
North England
Budget-constrained local authorities in Yorkshire and Greater Manchester continue specifying manual crank bases for care home installations to avoid BS 7671 electrical wiring compliance costs. Northern Powerhouse investment programmes have yet to redirect significant adjustable bed procurement toward residential channels. Manchester and Leeds healthcare trusts remain price-sensitive purchasers focused on bariatric load capacity rather than connectivity features.
Scotland
Postcode lottery variations in Scottish Health and Social Care Partnership equipment budgets create substantial geographic whitespace for distributor expansion beyond Edinburgh and Glasgow corridors. The Scottish Government's Health and Care Legislation commits to ageing-in-place targets without matching capital allocation to England's Integrated Care Board model. Aberdeen and Dundee present untapped residential retrofit potential where private wealth concentrates in energy sector households.
Wales
Local authority equipment budgets in Cardiff and Swansea lag English equivalents by approximately 30 percent per capita, capping institutional channel penetration. Welsh Government procurement frameworks prioritise cost containment over feature specification for domiciliary care equipment. Rural health board catchments in North Wales face extended delivery timelines that disadvantage just-in-time assembly models.
UK Adjustable Bed Bases Market Competitive Landscape
Capital-heavy producers compete with asset-light designers and brand licensors across tiered positioning bands. The market structure shows moderate concentration at the premium end and fragmentation in mid-market financing-dependent segments. Three archetypes dominate: vertically integrated mattress-base combination specialists, retail-channel-anchored volume assemblers, and direct-to-consumer digital natives. Competitive moves concentrate on exclusive retail partnerships and modular actuator platform standardisation rather than price-led confrontation.
Within the premium-brand tier, Tempur occupies a position exemplifying direct-to-consumer pricing power without retail intermediaries. Dreams and Bensons for Beds represent contrasting retail-channel strategies—one through high-street showroom networks enabling physical position testing, the other through mid-market financing options and nationwide logistics coverage. These three anchors illustrate how brand equity, channel control, and credit access differentiate competitive positioning across England's southeast corridor demand concentration.
| Leading Market Players |
|---|
| Tempur |
| Dreams |
| Majestic |
| Sleep Story |
| Adjustamac |
| Sleep Kings |
| Bensons for Beds |
| Generic |
| Vonluce |
| Others |
Pricing and Supply Chain Analysis
NHS Integrated Care Boards anchor procurement volume through fixed-tender contract structures that compress supplier margins while rewarding scale-qualified domestic assemblers. This institutional buyer concentration creates tiered pricing stratification across premium residential, mid-market financing-dependent, and economy healthcare segments.
Pricing Analysis
Margin tightening in the electric base tier reflects steel and copper commodity volatility colliding with fixed NHS tender pricing. Three-tier pricing structure across premium, standard, and economy levels separates Tempur's direct-to-consumer premium from Dreams' high-street financing bundles and Bensons for Beds' volume positioning. Certification grade under EU-UK retained REACH and fire safety compliance costs drive price differentiation between domestic-qualified and import-dependent suppliers. Care homes in Northern England exhibit highest price sensitivity, specifying manual crank bases to avoid electrical maintenance liabilities.
Supply Chain Analysis
Regional distribution centers in the West Midlands enable next-day coverage to 85 percent of England's population through hub-and-spoke logistics. Manufacturing concentrates in UK Midlands assembly facilities and German/Danish linear actuator production sites. Raw material dependencies span UK steel tubing, EU-sourced DC motors, and REACH-certified foam composites. Single-source vulnerability runs through two German and one Danish actuator suppliers controlling 70 percent of EU-sourced components. Distribution runs through specialty store networks, direct-to-consumer platforms, and NHS procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK adjustable bed bases are consolidating around compliance-capable domestic assemblers as REACH certification and fire safety digitisation eliminate low-cost import competition. Extended producer responsibility frameworks will accelerate this shakeout through modular design mandates.
For Market Incumbents: Deploy exclusive retail partnerships to lock out emerging direct-to-consumer entrants before subscription bundling models mature. Backward integration into linear actuator module design builds resilience against German/Danish supplier concentration. Certification investment ahead of pending UK product safety digitisation creates defensive moats that smaller assemblers cannot replicate.
For New Entrants and Emerging Players: Direct-to-consumer virtual consultation platforms offer the lowest-friction entry path around established high-street networks. Scotland and Wales present penetrable whitespace where local authority equipment budgets lag England's Integrated Care Board allocation. Target Aberdeen and Dundee residential retrofits through energy-sector household wealth concentration.
For Investors and Strategic Acquirers: The window for entry favors domestic-qualified assemblers with UKAS-accredited fire certification and NHS contract relationships. Acquisition targets should demonstrate modular actuator platform engineering and Scotland/Wales distribution presence. Watch for MHRA medical device registration timelines as inflection signals for premium smart-base revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Actuator Platform Standardization | Extended producer responsibility regulations favor replaceable component designs over integrated assemblies. |
| Remote Diagnostics Integration | NHS Long Term Plan digital health targets create recurring service revenue beyond hardware margins. |
| Scotland and Wales Distributor Expansion | Postcode lottery budget variations leave substantial geographic whitespace for targeted penetration. |
| REACH Compliance Certification Investment | Retained EU-UK chemical regulations eliminate low-cost Asian foam suppliers, consolidating domestic volume. |
| Subscription Bundling Pilot |
Research Methodology
Document review covered NHS procurement databases, MHRA device registration filings, and Trading Standards enforcement records, complemented by interviews with adjustable bed base procurement managers at Integrated Care Boards, biomedical engineers at Kent and Sussex hospitals, retail category buyers at Dreams and Bensons for Beds, and manufacturing operations directors at Midlands assembly facilities. Secondary validation drew from UKAS laboratory certification queues, BEIS consumer rights documentation, and EU-UK REACH retained regulation guidance. Bottom-up volume modeling triangulated against top-down NHS equipment budget allocations.
Cross-referencing historical tender award patterns against clinician and procurement panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material construction, end-user application, and distribution channel, with geographic procurement authority as an industry-specific overlay. CAGRs derived from equipment budget growth trajectories and residential replacement cycle acceleration. Forecast inputs incorporated linear actuator miniaturisation adoption curves and smart-connected base penetration rates in London and Home Counties postcodes.
The model holds under stable NHS Integrated Care Board budget allocation and retained EU-UK REACH enforcement; deviation in fire safety digitisation timelines or steel-copper commodity spikes would shift supplier margin assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
Germany Mattress Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Baby Cribs and Cots Market
Bedroom Furniture
Children Mattress Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Bed Head Panel Market
Bedroom Furniture
Luxury Mattress Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
China Mattress Market
Bedroom Furniture
Canopy Beds Market
Bedroom Furniture
United Kingdom Mattress Market
Bedroom Furniture
Luxury Bedding Market