
 Comforter Market | 2026-2036
Comforter Market Size, Share, and Industry Trends Forecast 2026-2036
Comforter Market Analysis
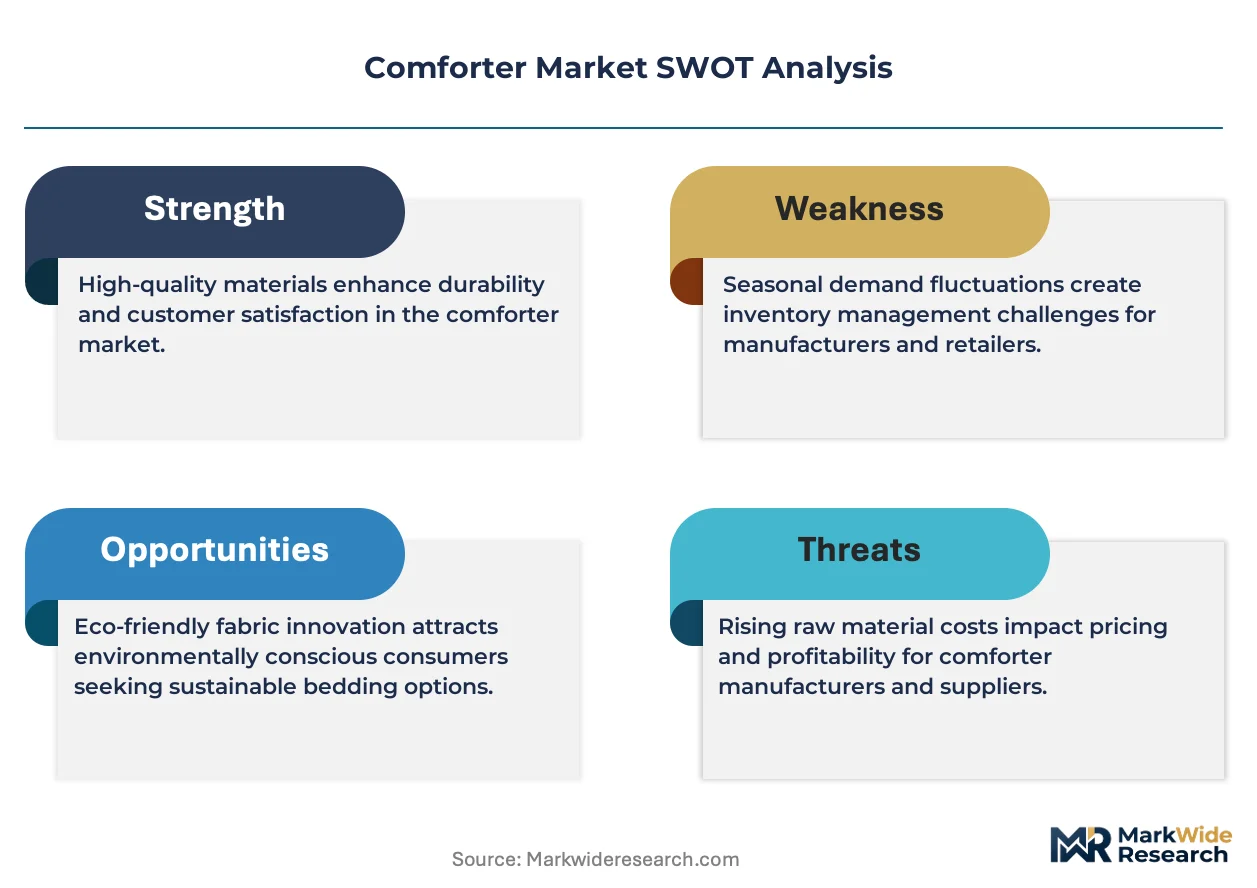
China is tilting toward large-scale textile manufacturing clusters for comforter production, drawing capacity from traditional European centers. Brooklinen leverages direct-to-consumer channels to sustain margin control across North American markets. Tempur Sealy International anchors its comforter strategy through integrated sleep-system bundling with mattress lines. Serta Simmons Bedding LLC dominates mass-market retail distribution through big-box partnerships.
A comforter is a thick, quilted bed covering consisting of an outer shell—typically cotton, polyester, or blended fabric—encasing an insulating fill layer measured in grams per square meter for thermal performance, designed primarily to provide adjustable warmth during sleep. Cotton and down fills command premium positioning due to breathability and loft retention, while synthetic fills compete on hypoallergenic properties and washability at lower price points. Queen and king sizes generate disproportionate revenue share as master-bedroom renovations drive replacement cycles, though twin sizes sustain volume through institutional hospitality contracts.
The US Consumer Product Safety Commission governs flammability standards for bedding products, while the OEKO-TEX Standard 100 restricts harmful substance thresholds in textiles sold across European markets. China's GB standards and evolving green manufacturing directives from the Ministry of Ecology and Environment are tightening chemical discharge requirements for dyeing and finishing operations. Stakeholders must monitor how diverging sustainability certifications between regions reshape sourcing decisions and factory compliance investments.
Market Dynamics
China's textile manufacturing clusters are consolidating comforter production capacity, while OEKO-TEX Standard 100 certification requirements in Europe and flammability mandates from the US Consumer Product Safety Commission force parallel compliance investments across export-oriented suppliers.
Growth Catalysts
- Residential renovation waves:China's tier-one cities are driving replacement cycles for queen and king-size bedding as master-bedroom upgrades accelerate, pulling premium fill volumes through retail channels.
- Hospitality procurement expansion:US hotel chains are compressing refresh cycles for premium bedding, creating sustained institutional demand for hypoallergenic synthetic fills at volume scale.
- REACH chemical restrictions:The European regulation is disqualifying legacy dyeing operations, shifting sourcing toward certified suppliers with verified discharge controls.
Market Restraints
- Down fill cost volatility:Feather and down insulation faces price pressure from avian influenza disruptions and restricted trade flows from Eastern European suppliers.
- Single-region supply concentration:China's Yangtze River Delta and Pearl River Delta clusters now control the majority of cut-and-sew capacity, creating vulnerability to localized energy rationing or logistics interruptions.
- Flammability testing bottlenecks:US Consumer Product Safety Commission compliance timelines stretch 8-14 weeks for new product introductions, delaying seasonal launches.
Strategic Opportunities
- Direct-to-consumer channel maturation:North American sleep brands are bypassing wholesale markups through owned e-commerce, capturing margin equivalent to 35-40% of retail price.
- Integrated sleep-system bundling:Mattress manufacturers are expanding comforter attach rates through point-of-sale packaging, converting mattress buyers into bedding purchasers at 60% higher average order values.
- India's organized retail penetration:Urban households in Mumbai, Delhi, and Bangalore are shifting from unbranded local quilts to packaged comforters as modern trade formats expand.
Industry Challenges
- Certification timeline compression:OEKO-TEX Standard 100 renewal cycles now require annual testing, forcing smaller mills to absorb $15,000-$40,000 recurring compliance costs or exit European export markets.
- Fill power testing standard divergence:IDFB, ASTM, and JIS methodologies produce non-comparable loft measurements, creating disputes between buyers and suppliers over thermal performance specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Comforter Market |
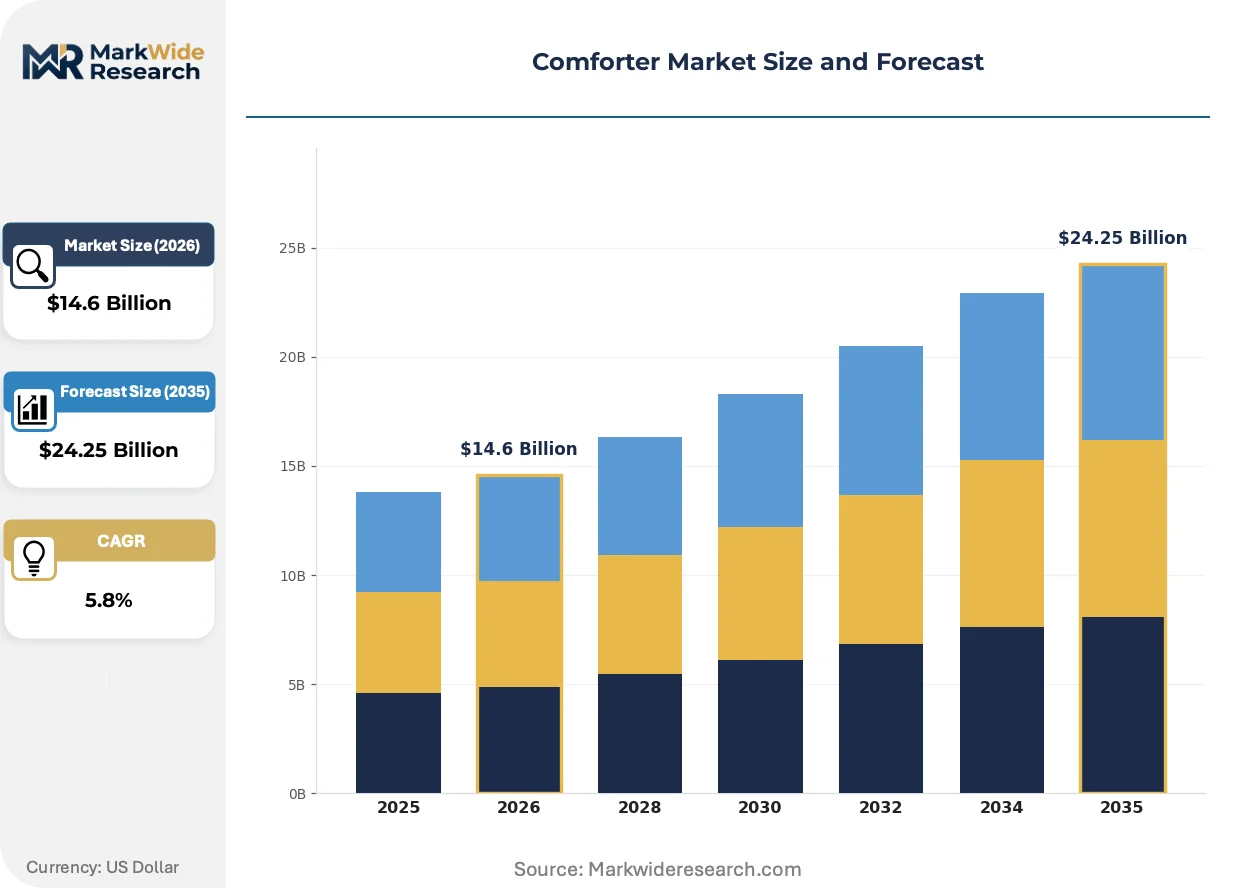
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $24.25 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Cotton, Polyester, Wool, Down Size: Twin, Full, Queen, King Pattern: Solid, Floral, Striped, Geometric Fill Type: Synthetic, Natural, Blended, Eco-Friendly |
| Companies Covered | SFERRA, Brooklinen, Tempur Sealy International, Saatva, Boll & Branch, Serta Simmons Bedding LLC, The Fine Bedding Company Ltd., Cozy Earth, Frette, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Comforter Market Emerging Trajectories
Sustainability verification and thermal performance engineering are converging to reshape product architecture, with certification regimes now functioning as market access gates rather than optional premiums.
Phase-change material microencapsulation is migrating from athletic apparel into bedding insulation, absorbing and releasing latent heat to stabilize sleep microclimates. High-end hospitality chains in Germany and Switzerland are piloting these fills for guest rooms with variable occupancy patterns. The technology is migrating from niche wellness positioning toward mainstream premium tiers as manufacturing costs decline 12-15% annually.
China's Ministry of Ecology and Environment is tightening GB standard enforcement for textile dyeing effluent, requiring zero-liquid-discharge systems at mills above 5,000-ton annual capacity. Zhejiang and Jiangsu provincial authorities are withholding operating licenses from non-compliant facilities. European brands sourcing from these clusters are accelerating supplier audits to preempt disruption.
Consumer preference is hardening around verified supply chain transparency, with QR-code traceability for down and feather fills becoming a non-negotiable purchase criterion in French and German retail. Mass-market retailers are responding by delisting untraceable white-label products. This shift is most visible in Benelux and Nordic markets where animal welfare legislation has preconditioned buyer expectations.
Comforter Market Segmentation
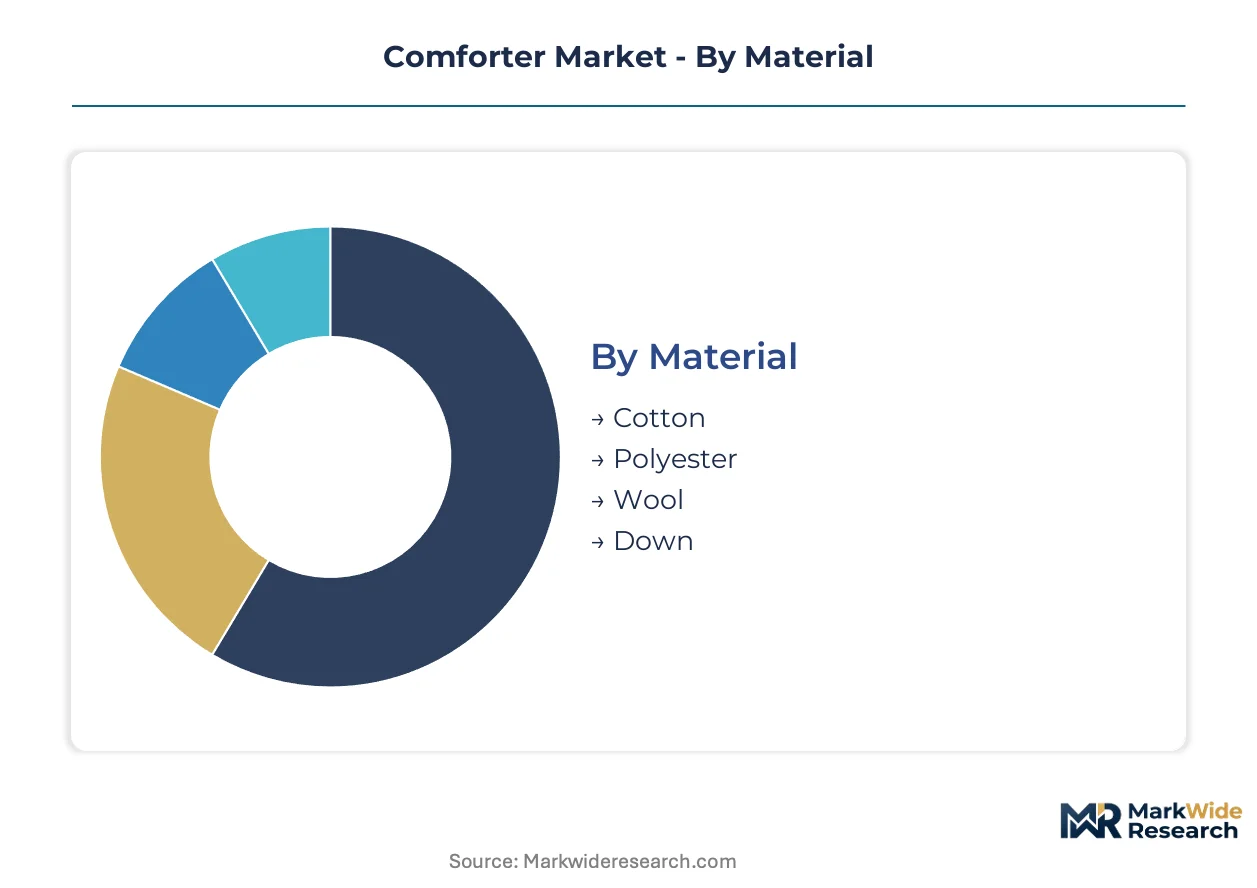
Comforter purchasing decisions cascade through material performance, dimensional fit, aesthetic preference, and thermal engineering specifications. Each segmentation axis carries distinct margin profiles and supply chain requirements that shape manufacturer portfolio strategy.
Material:
Mature natural fibers compete with engineered synthetics across price-performance tradeoffs.
- Cotton:Breathable cellulosic fibers with moisture-wicking properties dominate premium residential channels. Master-bedroom renovations in China's tier-one cities are pulling long-staple Egyptian and Pima cotton volumes through certified retail networks.
- Polyester:Thermoplastic polymer fills deliver hypoallergenic performance at mass-market price points. US hospitality procurement teams specify recycled PET content for ESG compliance in premium property refreshes.
- Wool:Crimped protein fibers provide natural temperature regulation and flame resistance without chemical treatment.
- Down:Clustered waterfowl plumage delivers unmatched loft retention measured in fill power, though avian influenza disruptions constrain Eastern European supply.
Cotton retains volume leadership; down holds the steepest expansion curve among natural materials.
Size:
Residential replacement cycles and institutional contract specifications create divergent demand patterns across dimensional tiers.
- Queen:Mid-market standard for North American master bedrooms with 60x80 inch mattress coverage. German and French retail channels report accelerating replacement frequency as renovation activity concentrates in urban centers.
- King:Oversized dimensions serve luxury hospitality suites and spacious residential primary bedrooms. California king variants gain traction in Western US markets where residential square footage exceeds national averages.
- Twin:Narrow 38x75 inch format sustains institutional volume through US hotel chain procurement and university housing contracts.
- Full:Transitional size captures adolescent bedroom upgrades and compact urban apartments with space constraints.
Queen dimensions command revenue concentration; king sizes are climbing the fastest among premium tiers.
Pattern:
Aesthetic differentiation separates commodity white-label supply from branded positioning at retail.
- Solid:Unpatterned dyeing minimizes production complexity and inventory risk for mass-market replenishment.
- Floral:Botanical motifs concentrate demand in Southern European and Southeast Asian markets with traditional decorative preferences.
- Striped:Linear patterns align with minimalist Scandinavian interior trends and hospitality neutral palettes.
- Geometric:Angular and tessellated designs target younger demographics through direct-to-consumer channels with seasonal rotation.
Solid patterns dominate hospitality procurement; geometric designs are gaining share fastest among digitally native brands.
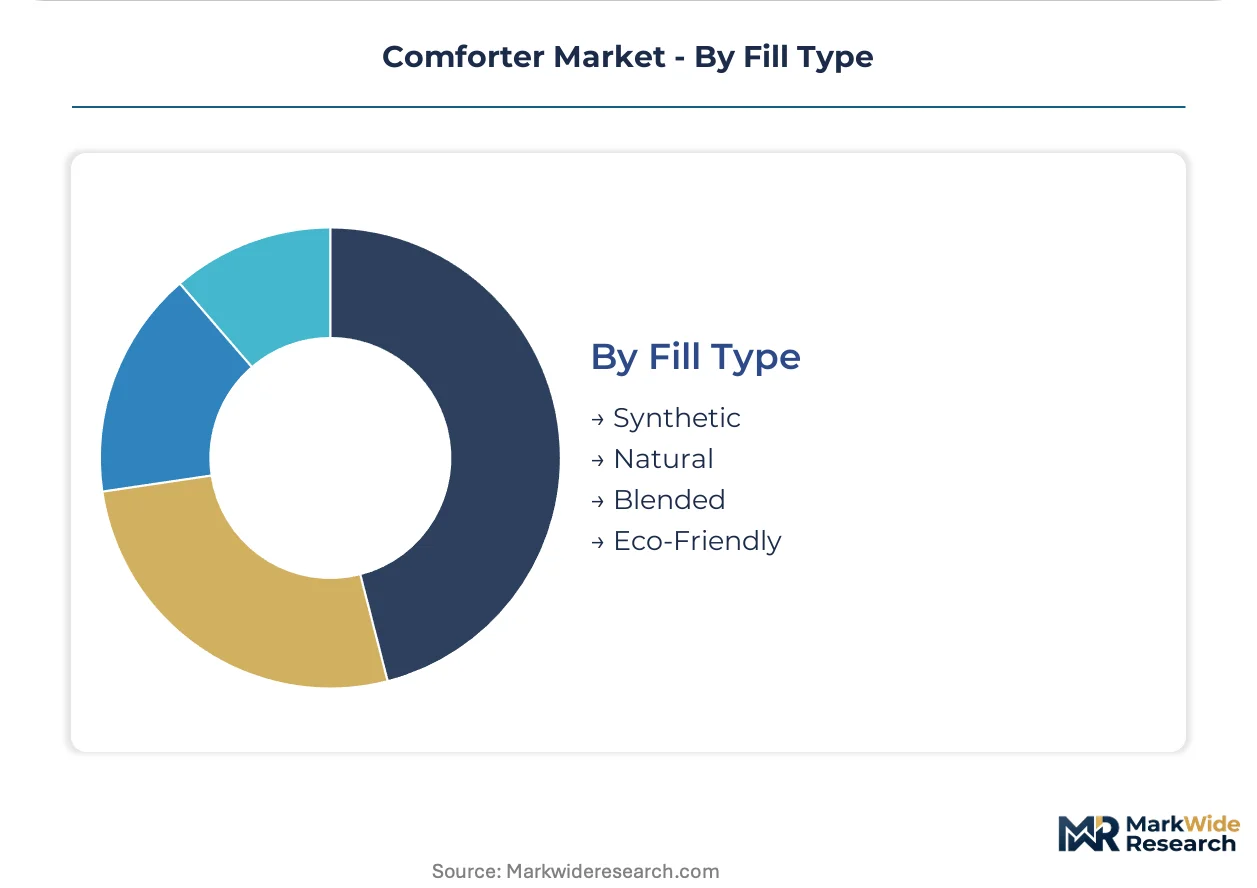
Fill Type:
Thermal engineering and sustainability verification now determine supplier qualification across export markets.
- Synthetic:Polyester and microfiber fills deliver machine-washable durability with consistent loft performance. REACH chemical restrictions are disqualifying legacy dyeing operations, shifting European sourcing toward certified suppliers.
- Natural:Down and feather insulation command price premiums contingent on traceability verification. QR-code tracking for Eastern European plumage has become mandatory for French and German retail placement.
- Blended:Hybrid constructions combine natural loft with synthetic washability for mid-market positioning.
- Eco-Friendly:Recycled fills and organic cotton casings target sustainability-motivated segments with third-party certification requirements.
Synthetic fills retain institutional volume leadership; eco-friendly alternatives are expanding most quickly among premium residential purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Comforter manufacturing capacity clusters heavily in China's Yangtze River Delta and Pearl River Delta, with secondary weaving and finishing operations concentrated in India and Vietnam. European brands source certified fills from Eastern European plumage processors while US hospitality procurement draws from domestic cut-and-sew facilities and Mexican nearshoring operations.
United States
Hotel chains including Marriott and Hilton compress bedding refresh cycles to 18-24 months, pulling synthetic fill volumes through institutional procurement channels. The US Consumer Product Safety Commission enforces 16 CFR Part 1633 flammability standards, stretching compliance timelines 8-14 weeks for seasonal product launches. Cut-and-sew operations concentrate in North Carolina's Catawba Valley and El Paso border maquiladoras.
China
Tier-one cities Beijing, Shanghai, and Shenzhen drive queen and king-size replacement cycles as residential renovation activity accelerates. The Ministry of Ecology and Environment enforces GB standards for textile dyeing effluent, requiring zero-liquid-discharge systems at mills above 5,000-ton annual capacity. Zhejiang and Jiangsu provincial authorities are withholding operating licenses from non-compliant facilities in Shaoxing and Changzhou clusters.
Germany
Benelux and Nordic retail channels demand QR-code traceability for down and feather fills as animal welfare legislation hardens buyer expectations. ECHA administers REACH chemical restrictions that disqualify legacy dyeing operations without verified discharge controls. Hamburg and Bremen harbor logistics hubs coordinate supplier audits for brands sourcing from Yangtze River Delta mills.
India
Urban households in Mumbai, Delhi, and Bangalore shift from unbranded local quilts to packaged comforters as modern trade formats expand organized retail penetration. BIS certification requirements for textile safety labels are tightening import substitution pressures on Chinese suppliers. Tiruppur and Surat textile clusters are adding cut-and-sew capacity for export-oriented bedding production.
Switzerland
High-end hospitality chains in Zurich and Geneva pilot phase-change material microencapsulation fills for guest rooms with variable occupancy patterns. Swissmedic coordinates with EU regulators on textile safety convergence, though OEKO-TEX Standard 100 certification remains the operative market access gate. Basel chemical engineering firms supply microencapsulation technology migrating from athletic apparel into bedding insulation.
Comforter Market Vendor Landscape
Direct-to-consumer specialists and integrated sleep-system manufacturers split the market between margin-capture and attach-rate strategies. The vendor base concentrates around three archetypes: digitally native brands bypassing wholesale markups, mattress manufacturers bundling bedding at point-of-sale, and legacy textile houses defending European heritage positioning. M&A activity targets traceable supply chain assets, while capacity expansion focuses on certified dyeing and finishing operations in Zhejiang and Jiangsu provinces.
Within the direct-to-consumer tier, Brooklinen exemplifies margin-control architecture through owned e-commerce channels. Tempur Sealy International and Serta Simmons Bedding LLC anchor the integrated sleep-system vector, converting mattress purchasers into bedding buyers through point-of-sale packaging. SFERRA occupies a position representing European heritage textile craftsmanship in premium hospitality and residential channels.
| Leading Market Players |
|---|
| SFERRA |
| Brooklinen |
| Tempur Sealy International |
| Saatva |
| Boll & Branch |
| Serta Simmons Bedding LLC |
| The Fine Bedding Company Ltd. |
| Cozy Earth |
| Frette |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion cycles transmit cost volatility through comforter supply chains, compressing margins for European brands while amplifying price differentiation between certified and uncertified supplier tiers. This freight corridor's reliability directly determines whether OEKO-TEX Standard 100 compliance costs flow through to retail premiums or get absorbed by intermediaries.
Pricing Analysis
OEKO-TEX Standard 100 dictates the pricing tier structure across European export markets, separating certified suppliers commanding retail premiums from uncertified competitors relegated to discount channels. Three-tier pricing structure across premium, standard, and economy levels tracks fill power verification and traceability documentation depth. Cost compression in synthetic fill tiers is intensifying because recycled PET feedstock competition from beverage packaging diverts supply. Hospitality procurement teams exhibit lowest price sensitivity due to bundled sleep-system contracts, while mass-market retailers face acute margin pressure from private-label substitution.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for North American brands, accelerating nearshoring trials to Mexican cut-and-sew operations. Manufacturing gravity centers on China's Zhejiang and Jiangsu provinces, with secondary weaving capacity in India and Vietnam. Raw material flows draw from Eastern European down processors, recycled PET suppliers in Southeast Asia, and long-staple cotton traders in Egypt and the United States. Single-region concentration in Yangtze River Delta dyeing facilities creates vulnerability to energy rationing directives. Distribution runs through hospitality procurement consortiums, direct-to-consumer fulfillment centers, and big-box retail replenishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Comforter market economics are shifting toward platform-mediated sleep ecosystems where mattress-comforter bundling and subscription-based refresh cycles restructure traditional transactional purchasing into recurring revenue architectures.
For Market Incumbents: Entrench certification advantages by accelerating zero-liquid-discharge investments at Zhejiang dyeing partners before MEE license withholding spreads beyond Shaoxing and Changzhou clusters. Deepen backward integration into traceable down supply through Eastern European plumage processor partnerships, preempting QR-code transparency mandates that threaten to delist untraceable inventory from German and French retail.
For New Entrants and Emerging Players: India's organized retail penetration in Mumbai, Delhi, and Bangalore offers the most penetrable white-space opportunity as modern trade formats displace unbranded local quilts. Target mid-market eco-friendly positioning with BIS-certified recycled fills, leveraging import substitution pressures on Chinese suppliers. Deploy direct-to-consumer channels with seasonal geometric pattern rotation to capture digitally native household formation.
For Investors and Strategic Acquirers: OEKO-TEX Standard 100 annual renewal requirements reshape the acquisition landscape toward certified dyeing assets with verified discharge controls, as smaller mills face $15,000-$40,000 recurring compliance costs or European market exit. Long-term viability favors suppliers with captive traceability infrastructure spanning plumage sourcing through retail QR-code integration. Watch for REACH chemical restriction expansion into additional dye classes as the inflection signal for accelerated supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Liquid-Discharge System Installation | MEE license compliance in Zhejiang and Jiangsu provinces secures European export access for certified suppliers. |
| Direct-to-Consumer Channel Launch | Owned e-commerce bypasses wholesale markups equivalent to 35-40% of retail price for North American brands. |
| Integrated Sleep-System Bundling | Mattress manufacturers convert purchasers at 60% higher average order values through point-of-sale packaging. |
| QR-Code Traceability Implementation | French and German retail placement now mandates verified down and feather supply chain transparency. |
| Phase-Change Material Integration | Swiss hospitality chains pilot microencapsulation fills as manufacturing costs decline 12-15% annually. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with bedding procurement managers, sustainability compliance officers, and textile mill operations directors across China, India, Germany, and the United States; and secondary validation against customs records, OEKO-TEX certification databases, and hospitality industry procurement disclosures. Bottom-up volume modeling triangulated against top-down category spend estimates derived from retail audit data and institutional contract filings.
Forecast inputs span material segmentation by fill type and casing composition, dimensional tier analysis across queen, king, and twin specifications, and regional regulatory cluster differentiation between REACH-governed European markets, CPSC-regulated US channels, and GB-standard Chinese domestic demand. CAGRs were derived from elasticity-adjusted replacement cycle projections and hospitality procurement expansion trajectories, with phase-change material adoption curves and recycled fill penetration rates as industry-specific modifiers.
Practitioners should monitor avian influenza disruptions to Eastern European down supply, MEE enforcement intensity in Zhejiang province, and REACH chemical restriction expansion for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
China Mattress Market
Bedroom Furniture
Bed Wedge Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
Baby Cribs and Cots Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
United States Mattress Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
United Kingdom Mattress Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
Malaysia Pillow Market