
 India Mattress Market | 2026-2036
India Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
India Mattress Market Outlook
Modular mattress-in-a-box delivery is decoupling purchase decisions from traditional showroom visits across Indian metros. Wakefit Innovations leverages direct-to-consumer logistics to sustain price competitiveness against legacy channels. Sleepwell (Sheela Foam Ltd) anchors its position through backward integration into polyurethane foam production. Kurlon Enterprises competes via extensive rural distribution networks that dominate tier-3 and tier-4 towns.
A mattress is a textile-based sleep support system comprising polyurethane foam, coir, spring assemblies, or latex layers engineered to distribute body weight and maintain spinal alignment during rest. Indian manufacturers typically fabricate these products through hot-melt adhesion, quilting, and tape-edging processes calibrated to BIS density and resilience specifications. Foam and hybrid categories lead volume due to lighter weight and lower freight costs suited to e-commerce fulfillment. Memory foam and pocket spring technologies are gaining fastest among urban consumers seeking pressure relief and motion isolation. The hospitality end-user segment commands premium margin pools as hotel chains standardize on branded sleep surfaces for guest satisfaction metrics.
BIS mandates density labeling and fire-resistance testing for domestic mattress production, while the PLI scheme for textiles indirectly subsidizes foam and fabric input costs for certified manufacturers. State-level municipal corporations in Maharashtra and Karnataka enforce building code standards that specify mattress dimensions for worker dormitories and healthcare facilities. Stakeholders must monitor how BIS expands scope to imported sleep products and whether e-commerce disclosure rules reshape comparison shopping behavior.
Market Dynamics
Direct-to-consumer logistics is compressing traditional mattress distribution layers across Indian metros, forcing legacy retailers to absorb showroom cost structures while competing against asset-light digital entrants.
Growth Catalysts
- PLI scheme for textiles:The production-linked incentive subsidizes foam and fabric input costs for certified domestic manufacturers, narrowing the landed cost gap against imports.
- Hospitality procurement standardization:Tier-2 hotel chains are mandating branded sleep surfaces for guest satisfaction metrics, creating pull-through demand for premium foam and hybrid categories.
- Maharashtra real estate pipeline:Mumbai-Pune corridor development is driving bulk mattress procurement for worker dormitories and residential projects under municipal building codes.
Market Restraints
- Polyol price volatility:Foam manufacturers face margin compression when crude-derived polyol feedstock costs spike, with limited pass-through power in price-sensitive segments.
- Coir belt supply concentration:Kerala and Karnataka account for the majority of domestic coir fiber output, exposing spring mattress producers to monsoon-dependent supply disruptions.
- BIS testing timelines:Density certification and fire-resistance validation create 6-8 week product launch delays that disadvantage smaller manufacturers against stocked incumbents.
Strategic Opportunities
- Tier-3 and tier-4 town penetration:Gujarat and Tamil Nadu districts show rising branded mattress adoption as rural incomes climb and organized retail expands beyond district headquarters.
- Healthcare facility specifications:State-level municipal corporations in Karnataka are drafting mattress dimension and hygiene standards for hospital and eldercare procurement that favor certified domestic suppliers.
- Hybrid channel models:Phygrometry—showroom experience with warehouse-direct fulfillment—is emerging as a middle path between pure digital and full-retail distribution economics.
Industry Challenges
- Skilled quilting technician scarcity:Tape-edging and hot-melt adhesion specialists are concentrated in legacy manufacturing clusters, constraining capacity expansion in newer facilities.
- E-commerce disclosure compliance:Draft rules under consumer protection frameworks may mandate density and firmness index labeling on digital platforms, requiring backend system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Mattress Market |
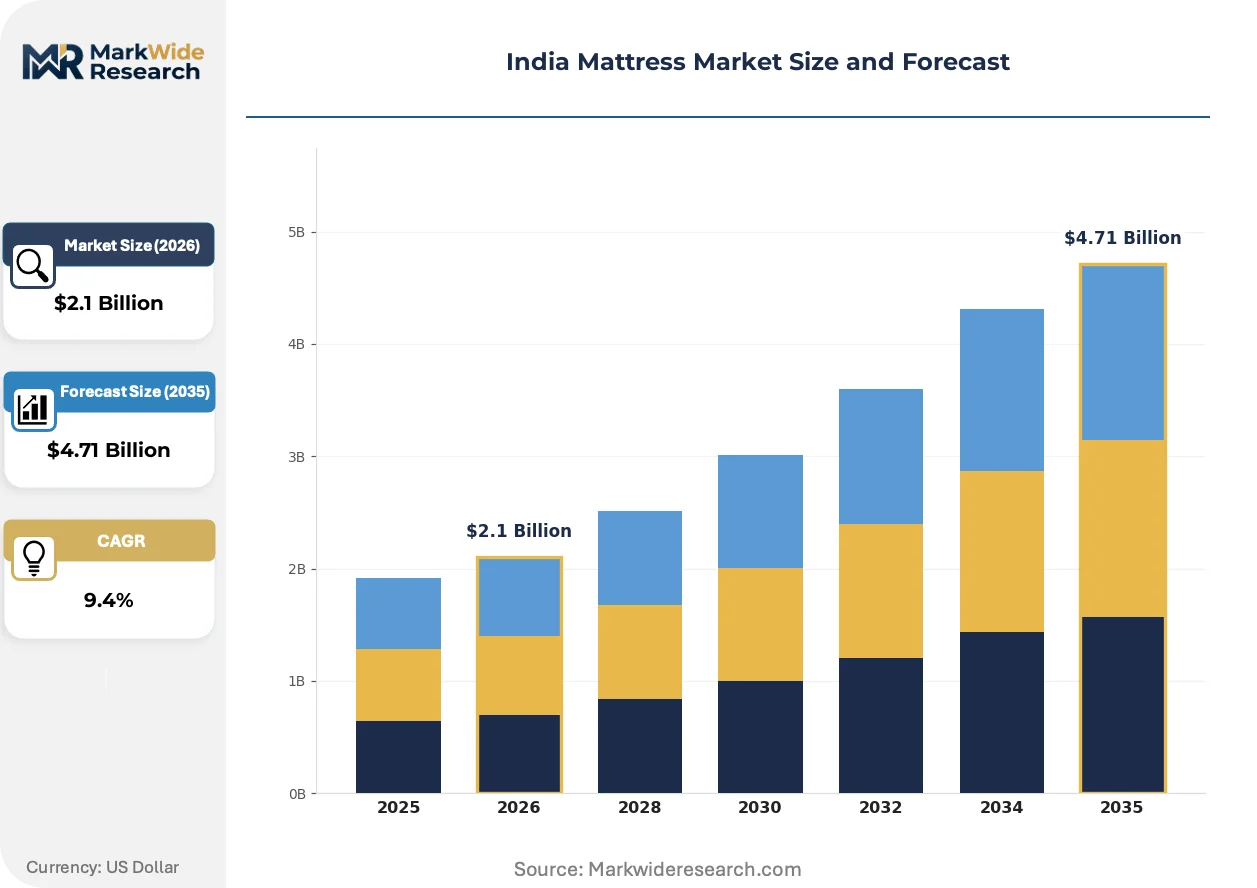
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring, Foam, Latex, Hybrid Technology: Memory Foam, Gel-Infused, Bonnell Spring, Pocket Spring Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale End User: Residential, Commercial, Hospitality, Healthcare |
| Companies Covered | Peps Industries, The Sleep Company, Sleepwell (Sheela Foam Ltd), Springfit Mattress, Centuary Foam, Kurlon Enterprises, Wakefit Innovations, Godrej Interio, Duroflex Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Mattress Market Strategic Shifts
Memory foam and pocket spring technologies are converging with logistics innovations to redefine how Indian consumers evaluate and receive sleep products, compressing the traditional purchase cycle from weeks to days.
Pocket spring assemblies are unifying pressure relief and motion isolation in a single sleep surface architecture. Urban consumers seeking hotel-grade rest quality are adopting these configurations fastest. The technology is unifying premium positioning with e-commerce viability, as rolled-pack compatibility reduces freight costs versus traditional bonnell spring units.
BIS certification scope expansion is tightening quality benchmarks for imported sleep products. The regulator is evaluating fire-resistance and density labeling parity between domestic and foreign manufacturers. Premium hospitality procurement teams are responding by pre-qualifying only BIS-compliant suppliers for chain-wide standardization mandates.
Consumer research behavior is fragmenting across touchpoints before purchase commitment. Buyers now compare firmness indices and trial-period policies online before confirming tactile preference in limited showroom visits. This pattern is most visible in Bengaluru and Hyderabad, where digital-native demographics dominate residential furnishing decisions.
India Mattress Market Segmentation
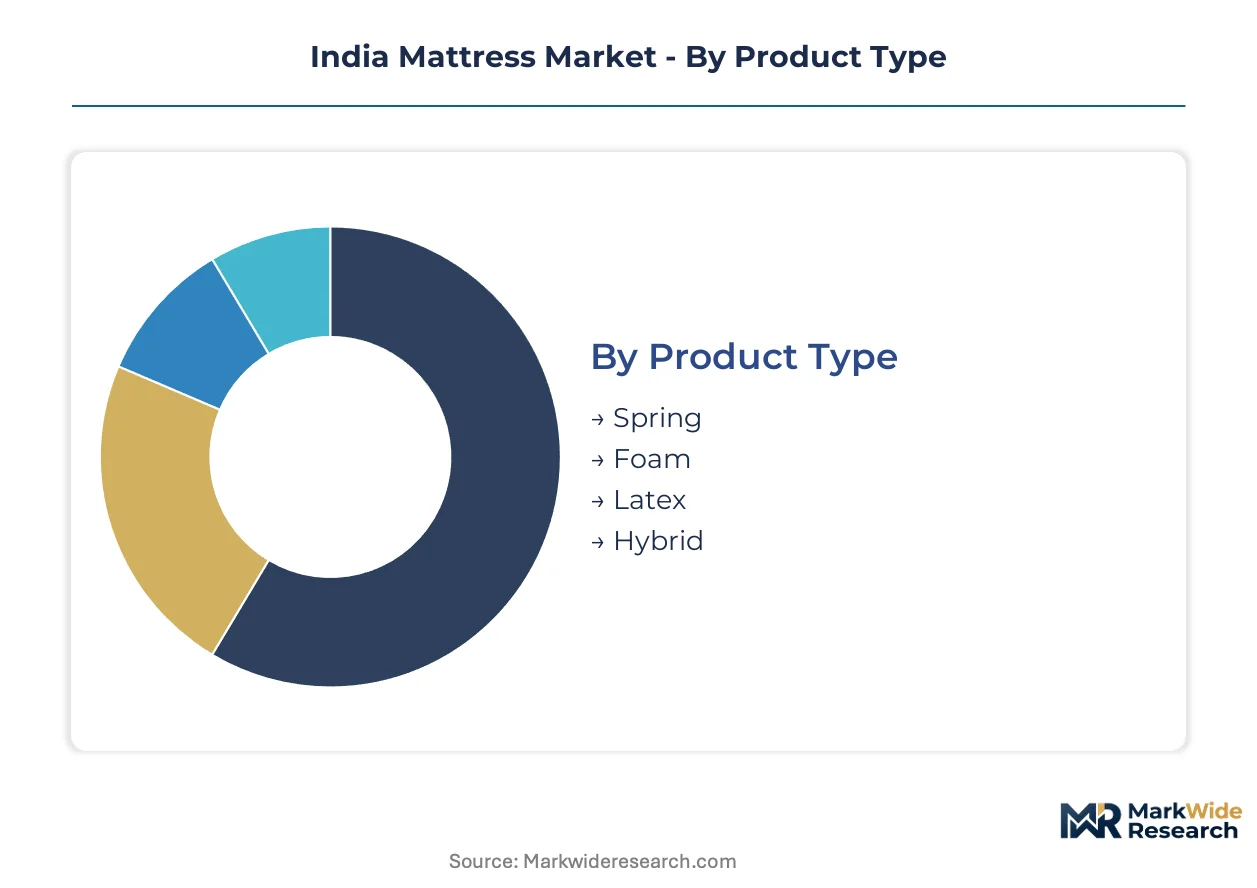
Segmentation in the India mattress market reveals how material science, channel economics, and end-use specifications create distinct competitive arenas. Manufacturers must align production configurations with the density, durability, and delivery requirements of each category to capture margin pools effectively.
Product Type:
Customization intensity varies sharply across this category, from standardized foam blocks to bespoke spring assemblies engineered for specific load-bearing profiles.
- Foam:Polyurethane and bonded foam cores dominate volume production due to lower material costs and compression-roll compatibility for e-commerce fulfillment. Maharashtra and Gujarat residential projects specify foam mattresses for worker dormitories under municipal building codes, with BIS density mandates driving supplier certification.
- Hybrid:Layered constructions combining foam comfort zones with spring support cores command premium positioning in urban markets. Bengaluru and Hyderabad hospitality procurement teams specify hybrid configurations for motion isolation and pressure relief metrics in guest satisfaction systems.
- Spring:Bonnell and pocket spring units retain stronghold in tier-3 and tier-4 towns where tactile showroom evaluation dominates purchase decisions. Coir belt supply concentration in Kerala constrains cost competitiveness during monsoon disruptions.
- Latex:Natural rubber latex cores serve niche allergen-sensitive and eco-positioned segments with limited domestic production scale. Import dependency for raw latex maintains price premiums above mass-market categories.
Most installed capacity flows through Foam. Expansion is steepest in Hybrid.
Technology:
Cost tier stratification in this category separates commodity spring systems from precision-engineered foam formulations with proprietary chemistry.
- Memory Foam:Viscoelastic polyurethane formulations respond to body heat and weight distribution for pressure point relief. Urban residential buyers in Karnataka and Maharashtra prioritize memory foam for spinal alignment claims, with trial-period policies accelerating online conversion rates.
- Pocket Spring:Individually wrapped coil arrays isolate motion transfer between sleep partners. Tier-2 hotel chains mandate pocket spring specifications for guest satisfaction standardization, creating pull-through demand from hospitality procurement.
- Gel-Infused:Thermally conductive gel beads dispersed in foam matrices address heat retention complaints in tropical climates. Limited domestic formulation expertise constrains supplier base.
- Bonnell Spring:Interconnected hourglass coil systems remain the lowest-cost spring technology for price-sensitive segments. Rural distribution networks in Gujarat and Tamil Nadu move significant Bonnell volume through offline retail.
Technology adoption concentrates in Memory Foam for residential channels. Pocket Spring gains share fastest in hospitality procurement.
Distribution Channel:
Customer type in this category spans digitally native urban millennials to rural buyers requiring tactile validation before commitment.
- Online Retail:Direct-to-consumer platforms compress delivery timelines through warehouse-direct logistics and compressed-roll packaging. Metro consumers in Bengaluru and Hyderabad complete purchase cycles without showroom visits.
- Offline Retail:Branded experience centers and multi-brand furniture stores dominate tier-2 and tier-3 town penetration. Kerala and Karnataka coir belt proximity influences regional showroom inventory mix.
- Direct Sales:Manufacturer-owned outlets and institutional contract teams serve bulk hospitality and healthcare procurement. BIS certification documentation requirements favor established players in direct bidding.
- Wholesale:Unorganized channel serving budget segments through district-level distributors with limited brand affiliation. Price transparency gaps persist versus organized retail.
Volume throughput remains highest in Offline Retail. Channel shift is most pronounced in Online Retail.
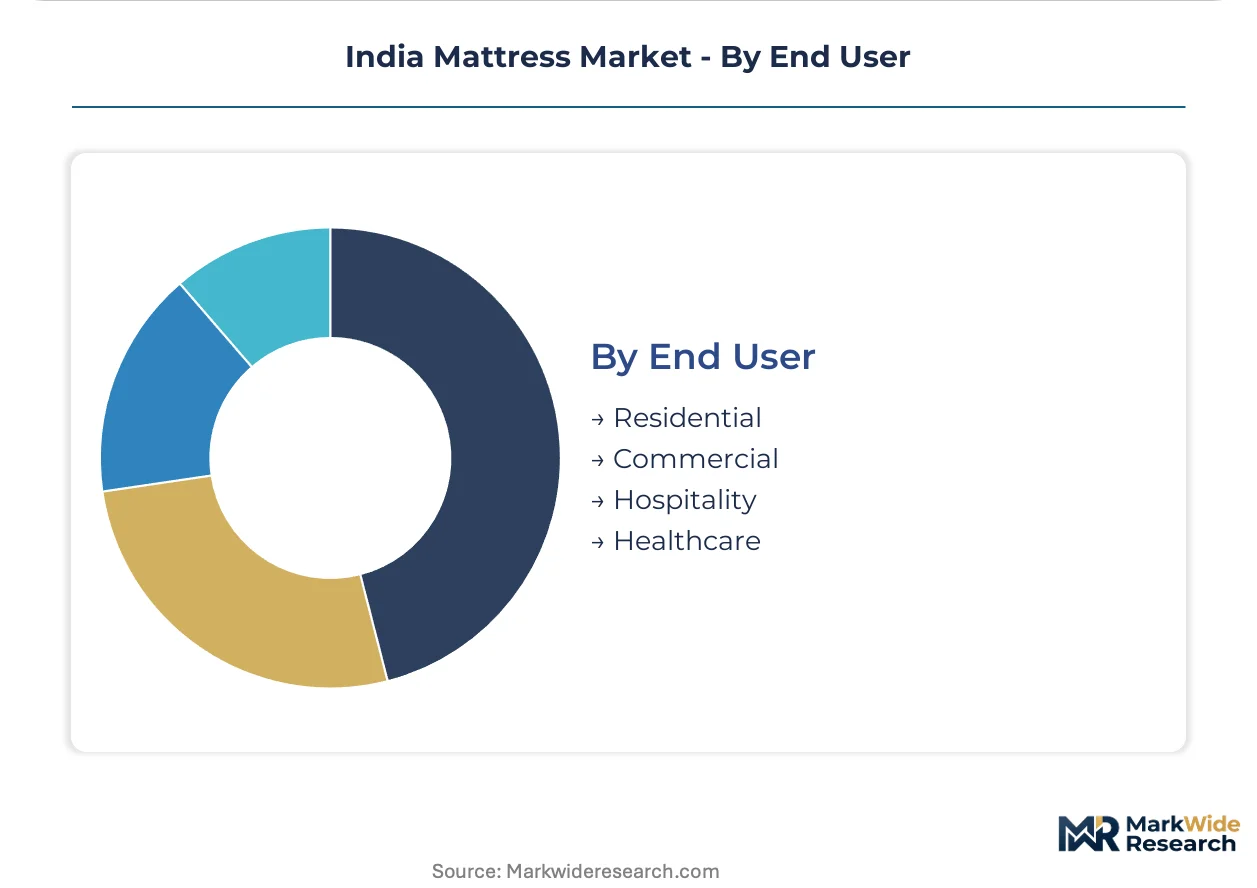
End User:
Application requirements in this category range from individual comfort preferences to institutional durability and hygiene mandates.
- Residential:Individual and family purchase decisions prioritize comfort trials, warranty terms, and delivery logistics. Maharashtra and Karnataka urban corridors drive premium category adoption.
- Hospitality:Hotel chains standardize on branded sleep surfaces with defined firmness indices and replacement cycles. Tier-2 city expansion is concentrating procurement volume.
- Commercial:Corporate housing, student hostels, and rental furnished apartments specify cost-optimized durability. Bulk procurement contracts favor foam categories for freight efficiency.
- Healthcare:Hospitals and eldercare facilities draft mattress dimension and hygiene standards under municipal corporation oversight. Karnataka state-level specifications favor certified domestic suppliers.
Revenue concentration sits with Residential. Procurement formalization is advancing fastest in Hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Indian mattress industry traces its organized roots to the 1960s coir belt industrialization in Kerala, where mechanized coir processing first enabled standardized spring mattress production for domestic distribution.
Maharashtra
Mumbai-Pune corridor real estate development drives bulk procurement for worker dormitories and residential projects. Municipal building codes specify mattress dimensions for compliance, tightening supplier certification requirements. Thane and Nashik industrial zones host foam fabrication clusters serving western India logistics networks.
Karnataka
Bengaluru's digital-native demographics accelerate online mattress adoption without showroom visits. State-level municipal corporations draft hospital and eldercare mattress specifications favoring certified domestic suppliers. Mysuru and Mangalore anchor coir processing and latex sourcing for southern distribution.
Gujarat
Surat and Ahmedabad districts show rising branded mattress penetration as rural incomes climb beyond district headquarters. PLI scheme textile subsidies narrow input cost gaps for certified foam manufacturers. Vadodara industrial belt concentrates polyurethane chemical processing for captive supply.
Tamil Nadu
Chennai hospitality procurement standardization creates pull-through demand for premium hybrid configurations. Coimbatore and Tiruppur textile machinery clusters support quilting and tape-edging equipment maintenance. State industrial policy targets mattress component manufacturing under textile sector incentives.
Delhi-NCR
Gurgaon and Noida corporate housing developments specify cost-optimized durability for bulk furnished apartment procurement. BIS density labeling enforcement tightest in national capital region retail channels. Ghaziabad foam conversion plants serve northern India e-commerce fulfillment networks.
India Mattress Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification and channel sophistication tiers. The vendor base organizes into three strategic archetypes: foam chemical integrators controlling upstream polyol supply, direct-to-consumer logistics specialists compressing delivery timelines, and rural distribution incumbents dominating tier-3 and tier-4 offline penetration. Dominant competitive moves include backward integration into polyurethane foam production and hybrid channel models blending showroom experience with warehouse-direct fulfillment.
Among established fabricators, Sleepwell (Sheela Foam Ltd) exemplifies the chemical-integrated archetype through captive foam production, while Wakefit Innovations occupies the direct-to-consumer logistics tier with compressed-roll fulfillment. Kurlon Enterprises represents the rural distribution anchor, leveraging extensive tier-3 and tier-4 network penetration. These three players illustrate how certification compliance, supply chain control, and channel economics define competitive positioning.
| Leading Market Players |
|---|
| Peps Industries |
| The Sleep Company |
| Sleepwell (Sheela Foam Ltd) |
| Springfit Mattress |
| Centuary Foam |
| Kurlon Enterprises |
| Wakefit Innovations |
| Godrej Interio |
| Duroflex Pvt Ltd |
| Others |
Value Chain & Pricing Dynamics
BIS fire-resistance and density certification mandates gate qualified supplier pools and premium-tier pricing access, compressing margins for uncertified manufacturers while rewarding compliant incumbents with hospitality procurement eligibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification grade and channel sophistication. Premium tiers command hospitality procurement premiums through BIS-compliant documentation, while economy segments face acute price sensitivity in tier-3 and tier-4 wholesale channels. Cost compression in the foam category intensifies because polyol feedstock volatility limits pass-through power. Direct-to-consumer entrants are least price-sensitive due to trial-period policy differentiation, whereas institutional bulk buyers in commercial housing negotiate hardest on per-unit landed costs.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for textiles reshape sourcing toward certified Indian foam and fabric producers, reducing import dependency for polyurethane inputs. Raw material supply concentrates in Maharashtra, Gujarat, and Karnataka, where petrochemical corridors feed polyurethane production and coir belt proximity serves spring mattress assembly. The chain draws from crude-derived polyol, coir fiber from Kerala, and natural latex imports. Single-source vulnerability in coir fiber during monsoon disruptions poses structural risk. Distribution runs through hybrid channel models blending showroom experience with warehouse-direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on backward integration into polyurethane foam production and premium hospitality procurement formalization, compressing input cost volatility while capturing standardized replacement cycles.
For Market Incumbents: Anchor market position through captive foam production investments in Thane and Vadodara industrial corridors, insulating against polyol price spikes. Deepen BIS certification portfolios to preempt regulatory scope expansion on imported sleep products. Defend against direct-to-consumer logistics specialists by deploying phygrometry showrooms in Bengaluru and Hyderabad, merging tactile validation with compressed-roll fulfillment economics.
For New Entrants and Emerging Players: Tier-3 and tier-4 towns in Gujarat and Tamil Nadu districts present underserved buyer archetypes with rising branded adoption and limited organized retail penetration. White-space exists in healthcare facility procurement as Karnataka municipal corporations draft mattress hygiene specifications favoring certified domestic suppliers. Launch through district-level distributor partnerships with BIS documentation support, avoiding legacy showroom cost structures.
For Investors and Strategic Acquirers: Roll-up economics work for foam-chemical integrators because PLI scheme subsidies and BIS compliance barriers create durable moats against asset-light entrants. Target mid-cap manufacturers with captive polyurethane supply and existing hospitality contract relationships. Watch for inflection in e-commerce disclosure rule finalization, which would mandate density labeling on digital platforms and favor backend-system-ready acquirers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Production | Captive polyurethane supply in Thane and Vadodara insulates Sheela Foam Ltd from polyol volatility. |
| Direct-to-Consumer Logistics Buildout | Compressed-roll fulfillment enables Wakefit Innovations to bypass legacy showroom economics in metros. |
| BIS Certification Portfolio Expansion | Fire-resistance documentation opens hospitality procurement pipelines for tier-2 hotel chain standardization. |
| Phygrometry Showroom Deployment | Hybrid channel models in Bengaluru merge tactile trials with warehouse-direct delivery timelines. |
| Healthcare Facility Specification Targeting | Karnataka municipal drafting of hospital mattress standards favors certified domestic suppliers. |
Study Parameters
Coverage spans Maharashtra, Karnataka, Gujarat, Tamil Nadu, and Delhi-NCR, with primary inputs from each region's manufacturing clusters and procurement centers. Primary interviews engaged foam fabrication plant managers, hospitality procurement directors at tier-2 hotel chains, retail channel partners in tier-3 towns, and BIS certification compliance officers. Secondary validation drew from BIS regulatory filings, PLI scheme textile subsidy disclosures, municipal building code specifications, and organized retail penetration databases. Bottom-up production capacity estimates triangulated against top-down end-use demand segmentation.
Rate-of-change decomposition across the analysis window modeled volume and value trajectories through product type, technology tier, distribution channel, and end-user segmentation dimensions. CAGRs derived from historical shipment data, replacement cycle analysis, and real estate pipeline correlation. Industry-specific forecast inputs incorporated hospitality procurement standardization timelines and PLI scheme subsidy phase-in assumptions for certified manufacturers.
Underlying measurement precision varies by segment; online retail and hospitality procurement carry tighter precision than wholesale channel estimates due to disclosure requirements. Forecasts reflect assumptions on BIS regulatory scope expansion, polyol price trajectory, and tier-2 city real estate completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
Germany Mattress Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Bed Wedge Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
United States Mattress Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
United Kingdom Mattress Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Bed Slats Market