
 Brazil Mattress Market | 2026-2036
Brazil Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Mattress Market Outlook
Residential buyers in Brazil's southeastern urban centers are rotating toward premium and hybrid mattress categories as home investment priorities shift. Ortobom leverages its vertically integrated foam production to control costs across the value chain. Simmons sustains brand recognition through specialty retail partnerships in major Brazilian cities. Tempur Sealy International anchors its position with memory foam technology leadership and direct-to-consumer channel expansion.
A mattress is a fabric-topped sleep support structure built around a core system of steel coils, polyurethane foam, latex, or layered combinations, typically measuring between 17 and 40 centimeters in thickness, designed to distribute body weight and maintain spinal alignment during rest. Innerspring systems retain the largest installed base in Brazil due to lower price points and familiar construction, though hybrid configurations are gaining fastest as consumers seek pressure relief without sacrificing traditional bounce. The residential end user segment occupies the dominant volume position, while hospitality procurement generates disproportionate margin pools through bulk replacement cycles and brand-specified durability standards.
ANVISA governs foam chemical emissions and textile contact safety for mattress components sold in Brazil, while INMETRO certification requirements for durability and dimensional stability shape product testing protocols before market authorization. Compliance costs filter directly into mid-range and premium tier pricing, creating regulatory differentiation that budget manufacturers struggle to absorb. Stakeholders must monitor evolving INMETRO labeling rules and state-level consumer protection enforcement to anticipate compliance-driven margin pressures and channel restructuring.
Market Dynamics
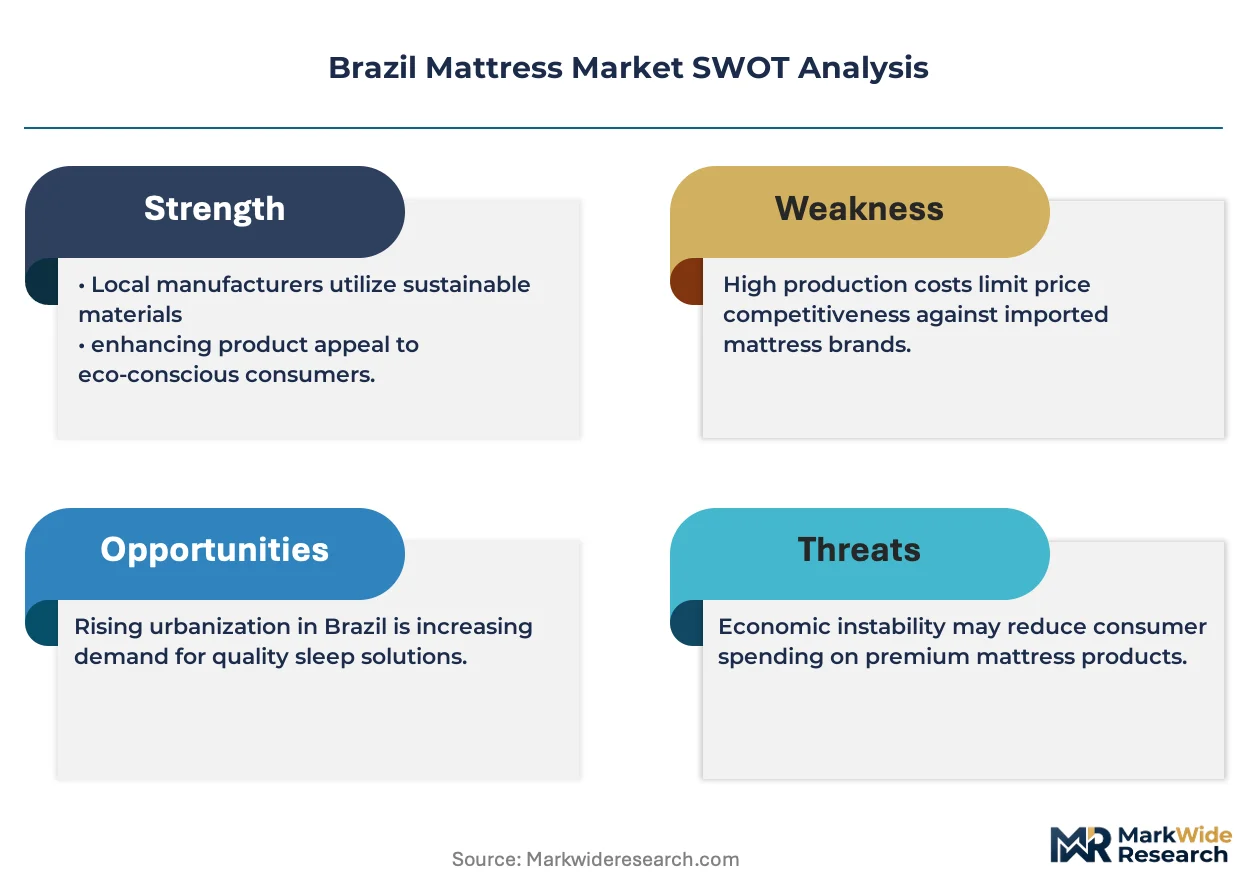
ANVISA's updated foam emission protocols and INMETRO's expanded durability certification requirements are compressing manufacturer margins while redrawing competitive boundaries between compliant premium producers and budget-tier suppliers struggling with testing costs.
Growth Catalysts
- INMETRO Certification Expansion:Mandatory durability labeling for mattresses sold in Brazil is forcing quality upgrades across the mid-tier segment. Retailers now favor certified suppliers, channeling volume toward compliant manufacturers.
- Hospitality Renovation Cycles:São Paulo and Rio de Janeiro hotel chains are replacing mattress fleets at accelerated intervals. Ergonomic specifications in procurement tenders favor suppliers with orthopedic product lines.
- Polyurethane Foam Localization:Domestic petrochemical feedstock expansion is reducing import dependency for foam core materials. Local production clusters in São Paulo state are capturing economies of scale previously available only to Asian suppliers.
Market Restraints
- TDI/MDI Price Volatility:Diisocyanate feedstock costs fluctuate with global oil derivatives markets. Brazilian foam producers lack hedging instruments available to North American counterparts.
- Southeastern Supply Concentration:Over 70% of certified foam production sits within 200 kilometers of São Paulo. Distribution to northern and central-western states incurs freight penalties that erode margin.
- Latex Import Dependency:Natural latex supply concentrates in Southeast Asian plantations. Brazilian manufacturers face currency exposure and shipping delays that hybrid foam competitors avoid.
Strategic Opportunities
- Northeast Urban Corridors:Fortaleza and Recife exhibit mattress penetration gaps relative to income-adjusted benchmarks. Distribution partnerships with regional furniture chains offer first-mover positioning.
- Direct-to-Consumer Platforms:Mattress-in-a-box logistics now reach 85% of Brazilian households within 72 hours. Digital-native brands bypass retail margin splits while capturing sleep trial data for product iteration.
- Green Building Certification Alignment:LEED and GBCI standards for residential developments increasingly reference low-VOC furnishings. ANVISA-compliant foam suppliers can credential products for sustainable construction projects.
Industry Challenges
- Certification Timeline Compression:INMETRO testing protocols now require 16-20 weeks for full durability validation. Product launch cycles extend, freezing working capital in inventory awaiting authorization.
- Legacy ERP Integration:Mid-sized manufacturers operate on fragmented systems that cannot track lot-level chemical composition for ANVISA traceability mandates. Custom middleware development demands capital that competes with production expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Mattress Market |
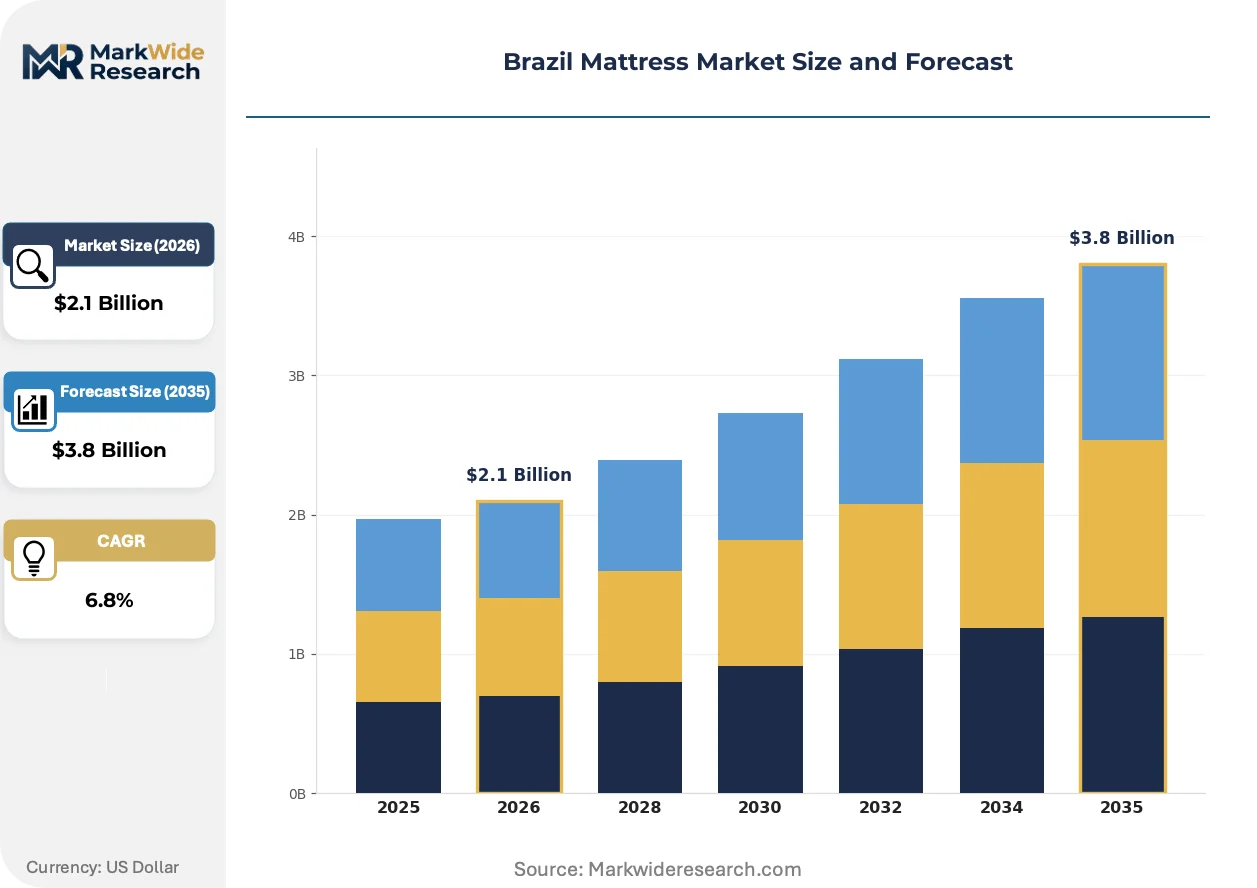
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Innerspring, Latex, Hybrid End User: Residential, Hospitality, Healthcare, Educational Price Tier: Budget, Mid-range, Premium, Luxury Distribution Channel: Online, Retail Stores, Specialty Shops, Direct Sales |
| Companies Covered | Ortobom, Dunlopillo, Colchao Inteligente, Veldeman Group, Simmons, Anjos Colchoes, Tempur Sealy International, Castor, ECUS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Mattress Market Strategic Shifts
Material substitution and channel restructuring are converging to compress traditional retail margins while elevating product performance transparency as a competitive weapon. Manufacturers must now engineer for certification compliance as a baseline, not a differentiator.
Memory foam layered over pocketed coil systems is supplanting traditional Bonnell spring constructions in Brazil's mid-premium residential segment. São Paulo apartment developers specify hybrid configurations in bulk procurement contracts. The technology is compressing price premiums previously commanded by pure memory foam imports while expanding addressable market share for domestic assemblers.
ANVISA's 2023 update to Resolution RDC 430 tightened permissible limits for toluene diisocyanate residuals in polyurethane foams. Testing laboratories in São Paulo and Minas Gerais report 40% volume increases in certification requests. Manufacturers serving the hospitality vertical are absorbing costs fastest, passing them through contract renegotiation rather than retail price lists.
Buyers in Brazil's southeastern metropolitan corridors increasingly research mattress specifications through manufacturer websites before visiting physical showrooms. Specialty retailers respond by unbundling delivery and old-mattress removal from base pricing. The shift is most visible in Curitiba and Porto Alegre, where digital-first brands now capture 15-20% of premium segment inquiries through search-optimized product comparison tools.
Brazil Mattress Market Segmentation
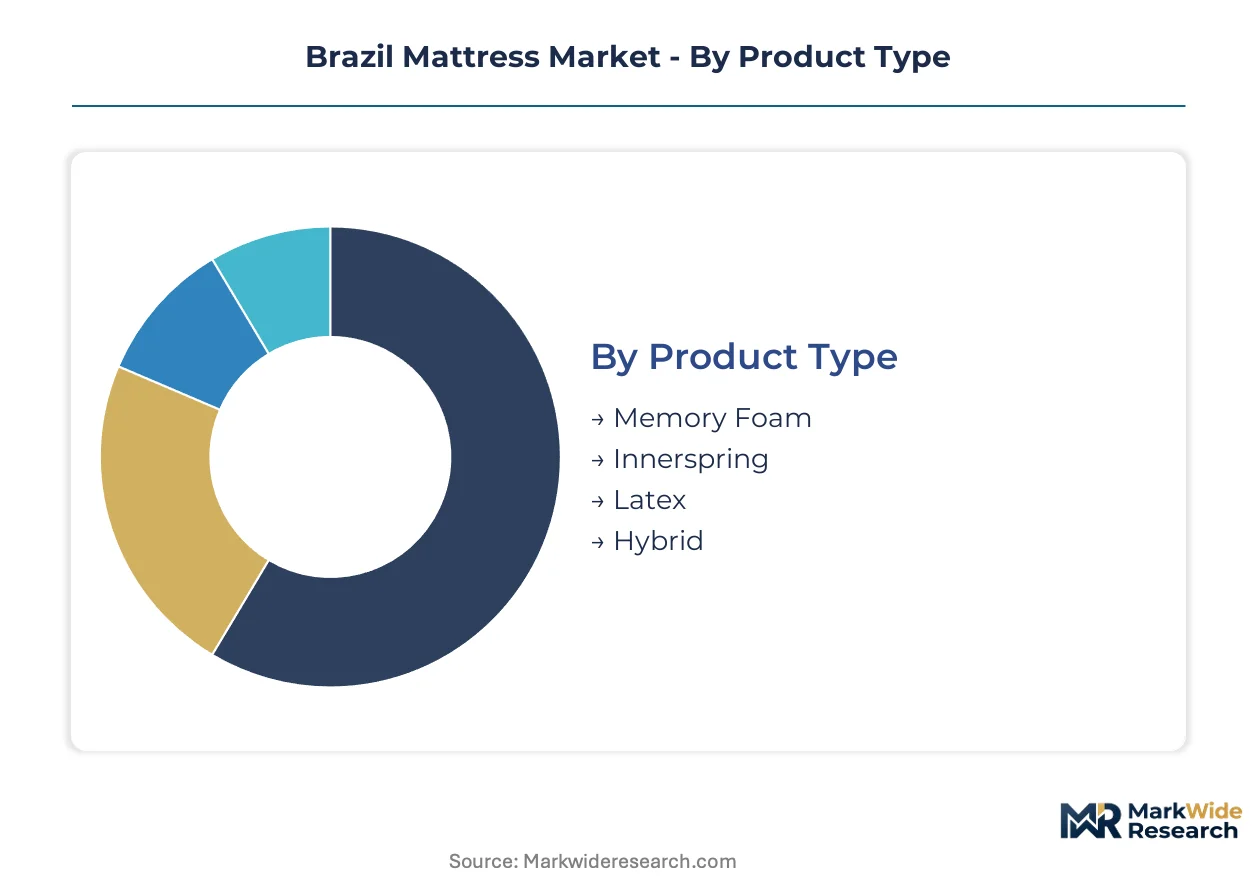
Mattress procurement patterns in Brazil diverge sharply across channels, with hospitality buyers negotiating bulk orthopedic specifications while residential consumers navigate certification tiers through fragmented retail networks. Channel selection directly constrains which product configurations and price points manufacturers can profitably serve.
Product Type:
Channel mix varies by construction technology, with specialty shops dominating latex and hybrid sales while mass retail captures innerspring volume and direct-to-consumer platforms anchor memory foam growth.
- Innerspring:Steel coil systems with Bonnell or pocketed configurations remain the default construction for budget retail channels. São Paulo furniture chains move 60-70% of national innerspring volume through promotional pricing tied to real estate completion cycles.
- Memory Foam:Viscoelastic polyurethane formulations deliver pressure mapping performance that commands premium positioning. Direct-to-consumer brands in Brazil's southeastern metros exploit compressed-pack logistics to bypass traditional retail margin splits while capturing sleep trial data.
- Latex:Natural rubber sap derivatives appeal to allergy-sensitive buyers through specialty shop networks. Import dependency on Southeast Asian plantations creates currency exposure that foam competitors avoid.
- Hybrid:Layered coil-and-foam constructions balance conformance with bounce, attracting São Paulo apartment developers for bulk procurement. Domestic assemblers capture share from pure memory foam imports by compressing former price premiums.
Innerspring dominates installed base. Hybrid configurations are where expansion concentrates.
End User:
Margin structure varies dramatically across buyer types, with hospitality procurement generating disproportionate profit pools through brand-specified durability standards while residential volume anchors production scale.
- Residential:Individual households drive absolute volume through replacement cycles averaging 8-12 years. Southeastern urban centers exhibit rotation toward premium and hybrid categories as home investment priorities shift.
- Hospitality:Hotel chains in São Paulo and Rio de Janeiro execute accelerated fleet replacement cycles. Ergonomic specifications in procurement tenders favor suppliers with orthopedic product lines and ANVISA-compliant foam documentation.
- Healthcare:Hospitals and long-term care facilities demand pressure-relief surfaces with antimicrobial textile treatments. INMETRO durability certification serves as a gatekeeping requirement for institutional procurement.
- Educational:University dormitories and boarding schools represent episodic bulk demand concentrated in January-February enrollment periods. Price sensitivity limits penetration to budget and mid-range tiers.
Residential buyers anchor production volume. Hospitality procurement is climbing the fastest in margin contribution.
Price Tier:
Certification cost absorption capacity stratifies manufacturers across tiers, with ANVISA and INMETRO compliance expenses filtering directly into mid-range and premium pricing while budget suppliers face margin compression.
- Budget:Basic polyurethane foam and Bonnell spring constructions serve price-sensitive buyers through mass retail. Testing cost burdens from expanded INMETRO requirements are squeezing manufacturer margins at this tier.
- Mid-range:Enhanced coil systems and entry-level memory foam layers dominate furniture chain assortments. Mandatory durability labeling is forcing quality upgrades as retailers now favor certified suppliers.
- Premium:Hybrid configurations and advanced foam formulations command specialty shop placement. São Paulo metropolitan corridor density supports uptake through higher income-adjusted penetration.
- Luxury:Natural latex and imported memory foam systems with extended warranties occupy boutique retail. Currency exposure on Southeast Asian latex imports constrains domestic manufacturer participation.
Mid-range captures volume concentration. Premium tier is gaining share fastest through hybrid adoption.
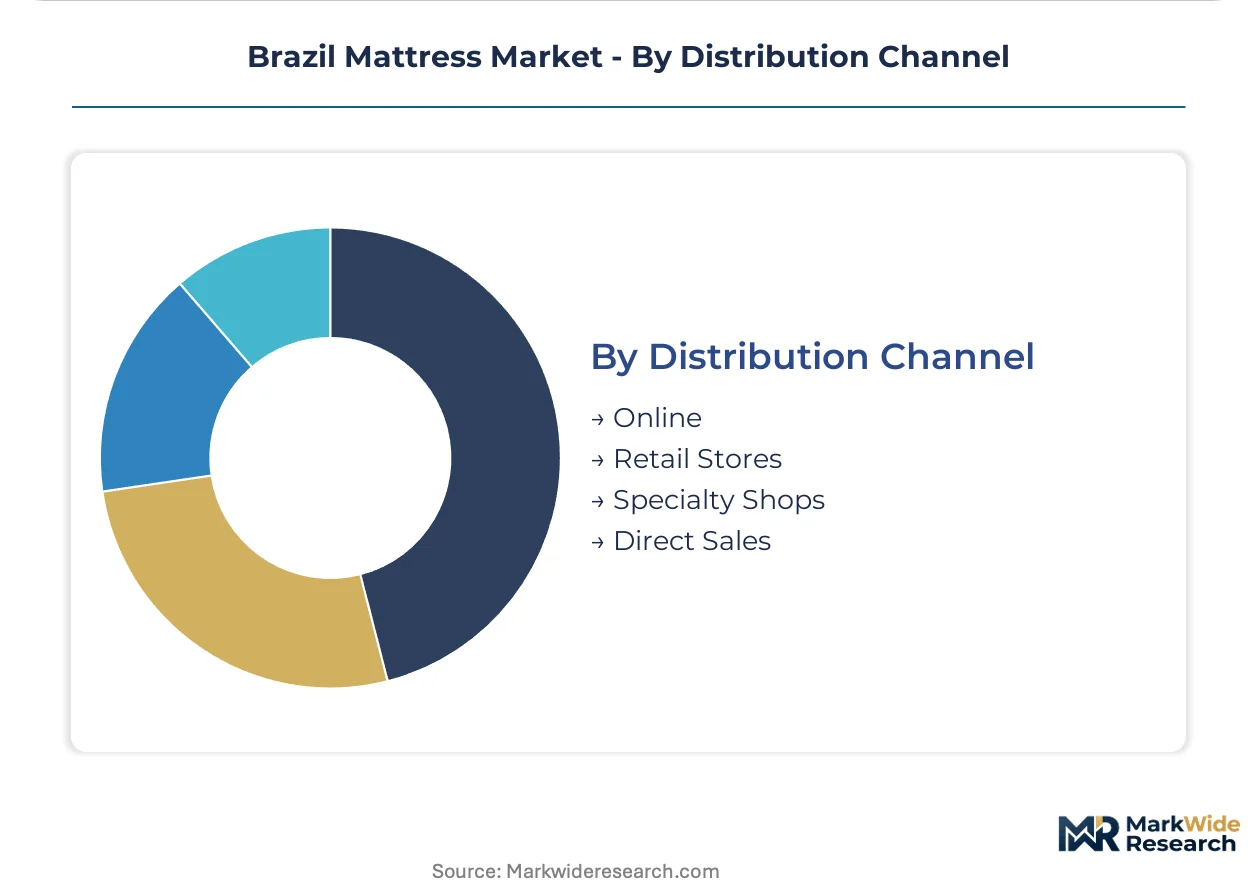
Distribution Channel:
Logistics infrastructure maturity determines channel viability by geography, with mattress-in-a-box reach now covering 85% of Brazilian households within 72 hours while northern states remain dependent on traditional retail.
- Online:Digital-native brands leverage search-optimized comparison tools to capture 15-20% of premium segment inquiries in Curitiba and Porto Alegre. Sleep trial data feeds product iteration cycles.
- Retail Stores:Furniture chains and department stores anchor mass-market volume with promotional pricing tied to payroll cycles. São Paulo chains unbundle delivery and removal services from base pricing.
- Specialty Shops:Sleep-focused retailers dominate latex and premium hybrid sales through consultative selling. Certification documentation serves as a competitive weapon in this channel.
- Direct Sales:Manufacturer-owned showrooms and hospitality contract teams bypass retail margin splits. Bulk procurement relationships with hotel chains and developers sustain this channel.
Retail stores anchor installed base. Online is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers concentrate in Brazil's southeastern corridor, where income density and real estate completion cycles drive premium mattress uptake. Hospitality procurement rotates through São Paulo and Rio de Janeiro as hotel chains renovate guest room standards. ANVISA's foam emission protocols and INMETRO durability certification apply uniformly, though compliance costs concentrate production in certified clusters.
São Paulo
Metropolitan São Paulo anchors national mattress demand through furniture chain density and apartment developer procurement. ANVISA testing laboratories in the city process 40% of national foam certification requests. The ABC Paulista industrial corridor hosts vertically integrated foam production facilities serving mid-range and premium tiers.
Rio de Janeiro
Rio's hospitality sector drives accelerated mattress replacement cycles as beachfront hotels upgrade ergonomic specifications. INMETRO durability labeling serves as a gatekeeping requirement for institutional procurement tenders. Manufacturing presence concentrates in Duque de Caxias and Nova Iguaçu, supplying the metropolitan corridor through established distribution networks.
Minas Gerais
Belo Horizonte's emerging middle-class households rotate toward hybrid mattress categories as home investment priorities shift. State-level consumer protection enforcement complements federal ANVISA mandates, creating dual compliance layers. The state's furniture retail clusters in Contagem and Betim capture growing volume from income-adjusted penetration gaps.
Rio Grande do Sul
Porto Alegre exhibits the strongest digital-native mattress brand penetration outside São Paulo, with search-optimized comparison tools capturing 15-20% of premium segment inquiries. Southern Brazilian manufacturers leverage proximity to Mercosur trade corridors for latex and foam feedstock access. Local production clusters compete on freight cost advantages to central-western states.
Paraná
Curitiba's specialty retail networks dominate latex and premium hybrid sales through consultative selling approaches. The state's logistics infrastructure supports mattress-in-a-box distribution reaching 85% of Brazilian households within 72 hours. Regional furniture chains in Londrina and Maringá offer first-mover positioning for mid-range tier expansion.
Brazil Mattress Market Competitive Environment
Player mix skews toward vertically integrated domestic specialists with captive foam production and multinational brand licensors operating through licensed manufacturing partnerships. Market structure exhibits tiered consolidation, with premium and luxury segments concentrating around imported technology partners while mid-range and budget tiers fragment across regional assemblers. Strategic archetypes include backward-integrated foam producers controlling raw material costs, brand licensors extracting royalty streams without manufacturing exposure, and digital-native direct-to-consumer challengers bypassing retail margin splits. Dominant competitive moves center on certification-driven quality upgrades and compressed-pack logistics infrastructure expansion.
Among domestic specialists, Ortobom exemplifies the backward-integrated archetype with in-house polyurethane foam production, while Castor occupies a position within the traditional manufacturing tier. Tempur Sealy International represents the multinational technology licensor model, anchoring premium positioning through memory foam brand equity. These three illustrate how competitive positioning stratifies across cost control, brand licensing, and technology differentiation vectors.
| Leading Market Players |
|---|
| Ortobom |
| Dunlopillo |
| Colchao Inteligente |
| Veldeman Group |
| Simmons |
| Anjos Colchoes |
| Tempur Sealy International |
| Castor |
| ECUS |
| Others |
Value Chain & Pricing Dynamics
Sixteen-to-twenty-week INMETRO certification timelines tie up working capital in inventory awaiting authorization, compressing cash conversion cycles and amplifying pricing power for certified manufacturers who can guarantee faster market access than competitors stuck in testing queues. This lead-time friction concentrates margin capture among São Paulo-based foam producers with established laboratory relationships, while budget-tier assemblers absorb cost penalties that erode their pricing flexibility.
Pricing Analysis
Prior-generation Bonnell spring constructions trade at entry points below hybrid configurations, which in turn sit at a discount to next-generation pure memory foam systems with advanced pressure-mapping capabilities. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and foam density specifications, with ANVISA-compliant products commanding measurable premiums over untested alternatives. Price differentiation stems from INMETRO durability labeling requirements and volume scale in hospitality procurement contracts. Cost compression in the budget tier is intensifying because testing laboratories have raised throughput fees to manage certification backlogs. Educational and institutional buyers exhibit highest price sensitivity, while hospitality procurement teams prioritize durability guarantees over unit economics.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for natural latex shipments originating from Southeast Asian plantations, with container availability fluctuations adding unpredictability to landed cost calculations. Domestic foam production draws from petrochemical feedstock clusters in São Paulo state, while specialty textile suppliers concentrate in Minas Gerais and Santa Catarina. Raw material dependencies include TDI/MDI diisocyanates, natural rubber latex, and high-density polyurethane formulations. Single-source vulnerability on Southeast Asian latex creates currency exposure that hybrid foam competitors avoid. Distribution runs through furniture chain networks in southeastern metros, with mattress-in-a-box logistics now penetrating secondary cities through third-party fulfillment partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's mattress market functions as a regulatory entrenchment story, where ANVISA compliance documentation and INMETRO certification relationships create switching costs that lock in hospitality procurement relationships and defend incumbent margin pools against price-driven challengers.
For Market Incumbents: Shield market position by deepening captive foam production capacity in the ABC Paulista corridor to offset TDI/MDI price volatility, while accelerating ERP system upgrades to enable lot-level chemical traceability for ANVISA audits. Certification timeline compression poses the most acute threat to working capital efficiency, making laboratory relationship investments a critical defensive lever. For New Entrants and Emerging Players: Anchor in Fortaleza and Recife distribution partnerships with regional furniture chains, where mattress penetration gaps relative to income-adjusted benchmarks offer first-mover positioning without confronting entrenched São Paulo supply networks. The northeast urban corridor represents the most penetrable geography, with digital-native brands exploiting compressed-pack logistics to bypass retail margin splits. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned foam producers with certified production lines but fragmented channel access, where hospitality contract expertise could unlock value through operational professionalization. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. The signal to watch is INMETRO testing laboratory expansion announcements, which would indicate capacity relief and compress certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Production | Captive TDI/MDI processing at São Paulo petrochemical clusters insulates margin from feedstock volatility. |
| Direct-to-Consumer Platform Launch | Digital-native brands in Curitiba and Porto Alegre bypass retail splits while capturing sleep trial data. |
| INMETRO Certification Fast-Track Investment | Priority laboratory relationships compress authorization timelines from twenty weeks to twelve. |
| Hospitality Contract Vertical | Ergonomic product lines with ANVISA documentation capture accelerated replacement cycles in Rio. |
| Northeast Distribution Partnership | Regional furniture chains in Fortaleza offer positioning ahead of income-adjusted penetration convergence. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews, including mattress category managers at São Paulo furniture chains, foam plant engineers in the ABC Paulista corridor, hospitality procurement directors at Rio de Janeiro hotel groups, and regulatory affairs specialists familiar with ANVISA emission protocols. Secondary validation drew from INMETRO certification databases, ANVISA resolution filings, Brazilian customs records for latex imports, and petrochemical feedstock pricing indices. Bottom-up estimates of unit shipments by construction type and price tier were triangulated against top-down market value assessments derived from retail channel revenue disclosures.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented projections by product construction, end-user vertical, price tier, and distribution channel, with additional granularity on state-level penetration patterns. CAGRs were derived from regression analysis of replacement cycle data, real estate completion correlations, and hospitality fleet turnover rates. Key inputs included polyurethane foam density specifications, certification timeline assumptions, and digital channel penetration curves in southeastern metros.
Underlying assumptions cover stable ANVISA enforcement intensity and continued INMETRO laboratory capacity constraints, with deviation risk concentrated in petrochemical feedstock price shocks or accelerated certification processing expansion. Forecasts reflect these documented conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Global Mattress Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
United States Mattress Market
Bedroom Furniture
Bed Wedge Market
Bedroom Furniture
Children Mattress Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Bed Slats Market