
 Smart Bed Market | 2026-2036
Smart Bed Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bed Market Intelligence
The divergence between premium, sensor-laden smart beds and lower-cost, basic adjustable models is shifting the market's value proposition. Sleep Number Corporation leverages its direct-to-consumer channel and strong brand recognition in the consumer segment. Tempur Sealy International Inc. competes through its extensive retail network and material science innovations. Meanwhile, Hill-Rom Holdings Inc. specializes in the clinical needs of healthcare facilities, integrating medical-grade features into its products.
A smart bed is a mattress and frame system integrated with sensors and network connectivity to monitor physiological data and adjust its physical characteristics. These beds utilize sleep monitoring sensors to track metrics like heart rate, respiration, and movement for automated position adjustment. While adjustable beds represent a foundational product type, models featuring AI sleep analysis and IoT integration are seeing the most rapid adoption. The healthcare facilities application commands the highest value, but the home care segment drives overall sales volume.
Product design and market access are governed by medical device regulations. In the United States, the FDA oversees beds intended for clinical use, while Europe requires compliance with CE marking and the Medical Device Regulation (MDR). These frameworks mandate stringent safety, data security, and performance standards. Consequently, manufacturers must decide whether to pursue a consumer wellness path or invest in the rigorous compliance required for the medical device market.
Market Dynamics
The market's primary dynamic is the bifurcation between consumer-grade wellness products and regulated medical devices. This split is forcing manufacturers to choose distinct pathways for product development, marketing, and regulatory compliance, defined by frameworks like the FDA's oversight in the US and the MDR in Europe.
Growth Catalysts
- AI and IoT Integration:The incorporation of artificial intelligence for sleep pattern analysis and Internet of Things connectivity for integration with smart home ecosystems creates new value propositions for consumers and healthcare providers, driving adoption of higher-end models.
- Demographic Shifts:Aging populations in developed nations, particularly in Germany and Japan, are expanding the need for advanced patient monitoring and pressure ulcer prevention in both clinical and home care settings, directly benefiting the healthcare segment.
- Preventative Healthcare Focus:A policy emphasis on remote patient monitoring and preventative care encourages the use of smart beds in home settings to track chronic conditions, reducing hospital readmissions and overall healthcare system costs.
Market Restraints
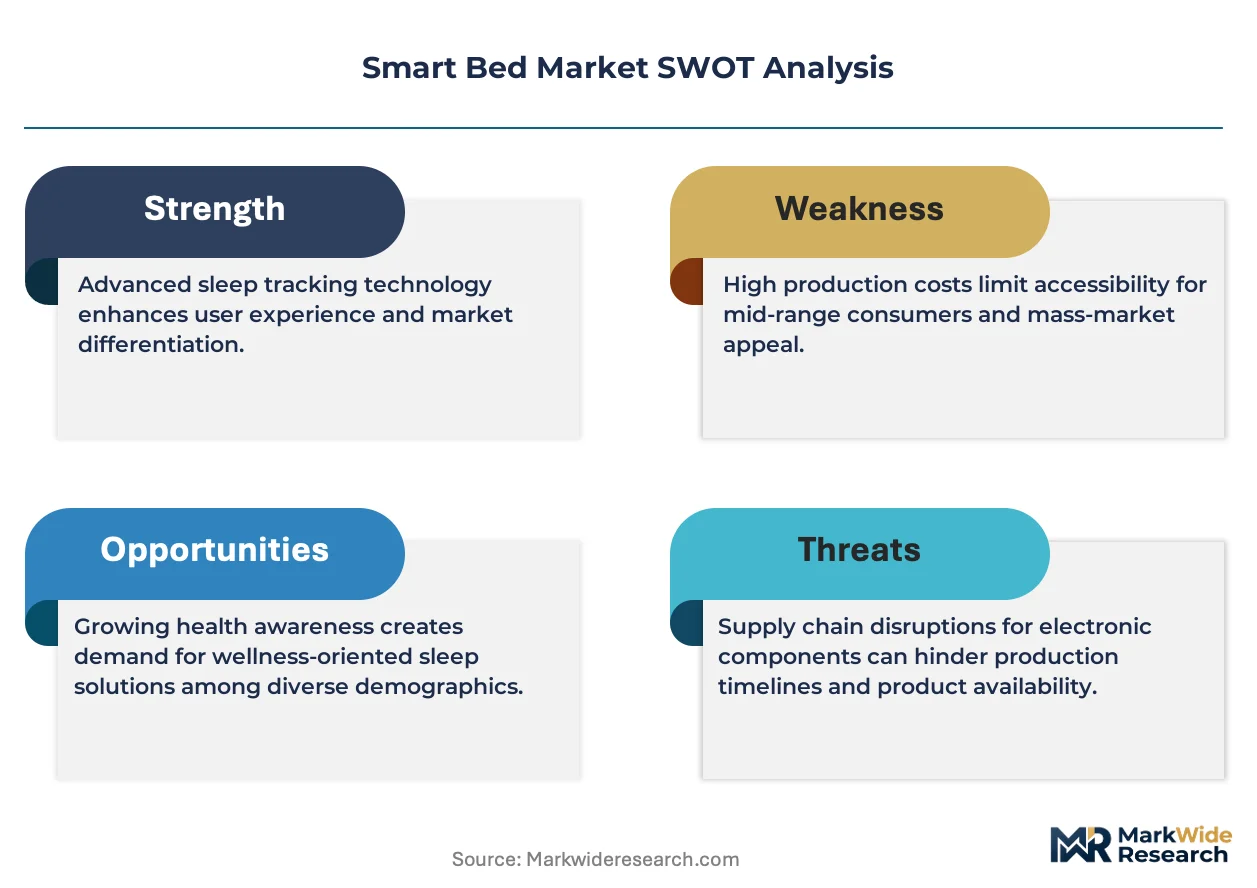
- High Product Cost:The significant price premium for smart beds equipped with advanced sensors and automation features, compared to traditional or basic adjustable beds, remains a primary barrier to widespread adoption in the mass consumer market.
- Regulatory Compliance Burden:Navigating the complex and expensive requirements for medical device classification, such as the European Union's Medical Device Regulation (MDR), deters some manufacturers and slows market entry for new clinical-grade products.
- Data Privacy Concerns:Hesitancy among consumers and healthcare institutions regarding the security and privacy of sensitive personal health data collected by smart beds can slow adoption, requiring robust cybersecurity measures and transparent data policies.
Strategic Opportunities
- Expansion in Emerging Economies:There is significant potential in markets with rising disposable incomes and modernizing healthcare infrastructure, such as South Korea and the United Arab Emirates, for both consumer and clinical applications.
- Digital Health Ecosystem Integration:Developing partnerships to integrate smart bed data with third-party digital health platforms, electronic health records (EHRs), and wearable devices offers a path to creating more holistic health monitoring solutions.
- Subscription-Based Service Models:Offering ongoing services like personalized sleep coaching, advanced data analytics, and software updates on a subscription basis can create recurring revenue streams beyond the initial hardware sale.
Industry Challenges
- Interoperability with Health IT Systems:Ensuring seamless data exchange between smart beds and diverse hospital Electronic Medical Record (EMR) systems presents a significant technical and standardization challenge, limiting efficiency in clinical workflows.
- Data Standardization Deficit:The absence of universal communication protocols and data formats across different smart bed manufacturers complicates the integration of devices into a single, cohesive platform for large-scale healthcare providers or smart home users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bed Market |
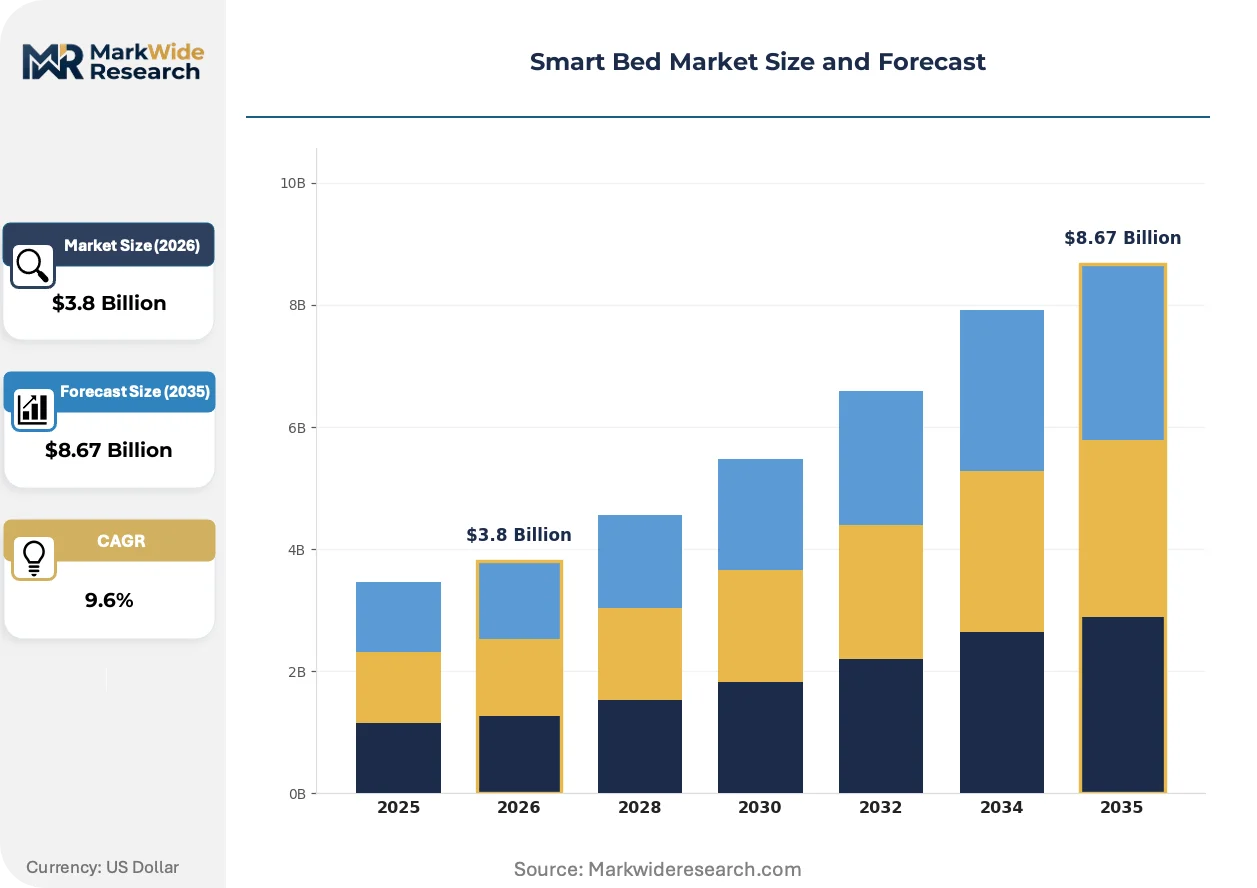
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Beds, Sleep Tracking Beds, Massage Beds, Cooling & Heating Beds, Anti-Snore Beds, Zero Gravity Beds Technology: IoT Integration, Wireless Connectivity, Voice Control, Sleep Monitoring Sensors, AI Sleep Analysis, Automated Position Adjustment Application: Healthcare Facilities, Assisted Living Centers, Hospitality Sector, Home Care, Rehabilitation Centers, Wellness Clinics End User: Hospitals, Senior Care Providers, Hotels, Individual Consumers, Physical Therapy Clinics, Specialty Clinics |
| Companies Covered | Hill-Rom Holdings Inc, Invacare Corporation, Sleep Number Corporation, Tempur Sealy International Inc, Eight Sleep Inc, Paramount Bed Co Ltd, Arjo AB, Joerns Healthcare LLC, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bed Market Strategic Shifts & Innovations
The evolution from passive furniture to active health-monitoring platforms is reshaping product development. This transition centers on embedding non-intrusive sensing technology and analytical software directly into the sleep environment, creating a source of continuous physiological data for personal and clinical use.
Ambient sensing technology allows for the collection of vital signs like heart rate and respiration without direct skin contact. This capability is being rapidly adopted by the premium consumer segment and long-term care facilities seeking less intrusive patient monitoring. This technology is converging with AI-powered predictive algorithms to identify potential health deterioration or sleep disorders before they become critical events.
Heightened regulatory scrutiny over data security is a defining trend. Mandates such as the EU's GDPR and the US's HIPAA govern the handling of personal health information collected by smart beds. This is forcing manufacturers to invest heavily in end-to-end encryption and secure cloud architecture. The healthcare facilities segment is most affected, as hospital procurement now heavily weighs data compliance in purchasing decisions.
A behavioral shift from one-time hardware purchases toward service-oriented models is altering revenue streams. This disrupts the traditional mattress retail channel by layering recurring software and coaching subscriptions on top of the physical product. This model is most prominent within the direct-to-consumer (DTC) segment, particularly in the United States, where brands build long-term customer relationships through ongoing digital engagement.
Smart Bed Market Segmentation
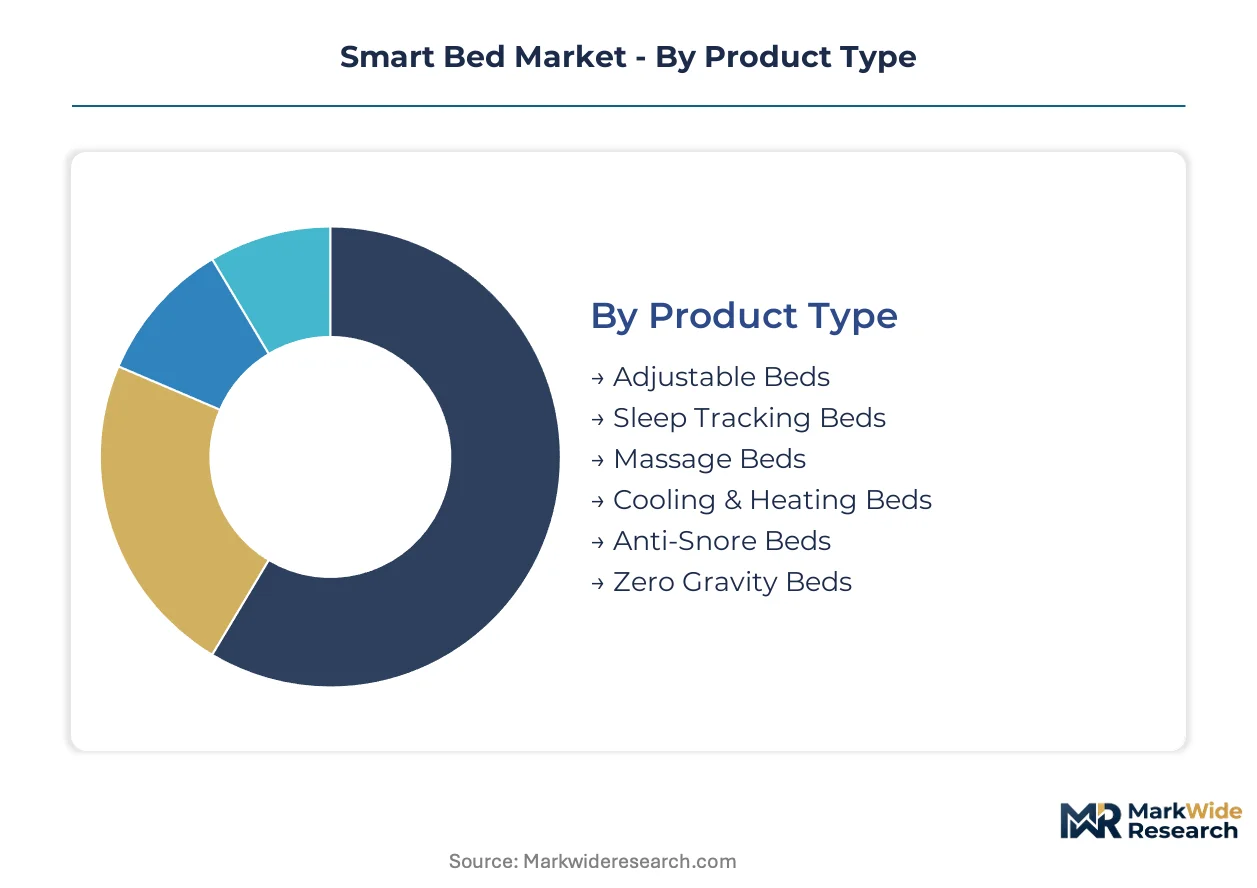
The Smart Bed Market exhibits distinct segments, reflecting diverse user needs and technological sophistication. Understanding these segmentations clarifies where innovation drives premium value and where market volume concentrates. This analysis reveals the evolving landscape of smart bed adoption across various functional requirements and user environments.
Product Type:
The product type segmentation reveals a clear division between foundational adjustable models and advanced, sensor-rich smart beds. This distinction influences both pricing structures and target consumer demographics.
- Adjustable Beds:These foundational products offer mechanical articulation for head and foot elevation, enhancing comfort and basic support. Demand remains consistent across home and clinical settings, driven by ergonomic benefits for users.
- Sleep Tracking Beds:Integrating advanced sensors, these beds monitor physiological data such as heart rate, respiration, and sleep cycles. Adoption is accelerating in the premium consumer market, where users prioritize detailed health insights.
- Massage Beds:These beds incorporate massage functions directly into the mattress or frame for relaxation.
- Cooling & Heating Beds:Featuring integrated temperature regulation systems, these models offer personalized thermal comfort.
- Anti-Snore Beds:Designed to detect and mitigate snoring through automatic position adjustments.
- Zero Gravity Beds:These beds position the body to simulate weightlessness, reducing pressure on the spine.
Mature deployment sits with Adjustable Beds. Newer deployment is concentrated in Sleep Tracking Beds.
Technology:
Technology segmentation highlights the core innovations enabling smart bed functionality, with advanced analytics and connectivity driving significant value. These advancements directly impact device capabilities and user experience.
- AI Sleep Analysis:This technology employs artificial intelligence algorithms to interpret complex sleep data, providing personalized insights and predictive health alerts. Its integration is critical for clinical applications in identifying early signs of sleep disorders.
- IoT Integration:Internet of Things connectivity allows smart beds to link with broader smart home ecosystems and healthcare platforms, facilitating seamless data exchange. This feature is highly valued in home care and healthcare facilities for comprehensive monitoring.
- Wireless Connectivity:This enables data transmission and remote control of smart bed features.
- Voice Control:Users can operate bed functions hands-free, enhancing convenience.
- Sleep Monitoring Sensors:These embedded sensors gather vital physiological data, forming the basis for advanced sleep tracking.
- Automated Position Adjustment:This feature allows beds to independently alter their configuration based on user needs or detected changes.
The adoption of AI Sleep Analysis is gaining share fastest. Wireless Connectivity represents a foundational technological element.
Application:
The application segmentation illustrates where smart beds are deployed, ranging from clinical environments to individual homes. Each application demands specific features and regulatory compliance levels.
- Healthcare Facilities:Hospitals and clinics utilize smart beds for advanced patient monitoring, pressure ulcer prevention, and remote care management. This segment commands the highest value due to stringent medical device requirements.
- Home Care:Smart beds in home settings support independent living, track chronic conditions, and provide comfort for aging populations. This application drives the largest sales volume, reflecting consumer demand for wellness.
- Assisted Living Centers:These facilities deploy smart beds for resident safety, fall detection, and continuous health oversight.
- Rehabilitation Centers:Smart beds assist in patient recovery by providing adjustable support and monitoring progress.
- Hospitality Sector:Hotels and resorts integrate smart beds to offer enhanced guest comfort.
- Wellness Clinics:These specialized clinics use smart beds for sleep studies, therapy, and personalized health interventions.
Healthcare Facilities demonstrate a high maturity level in specialized smart bed usage. The Home Care segment is expanding most quickly.
End User:
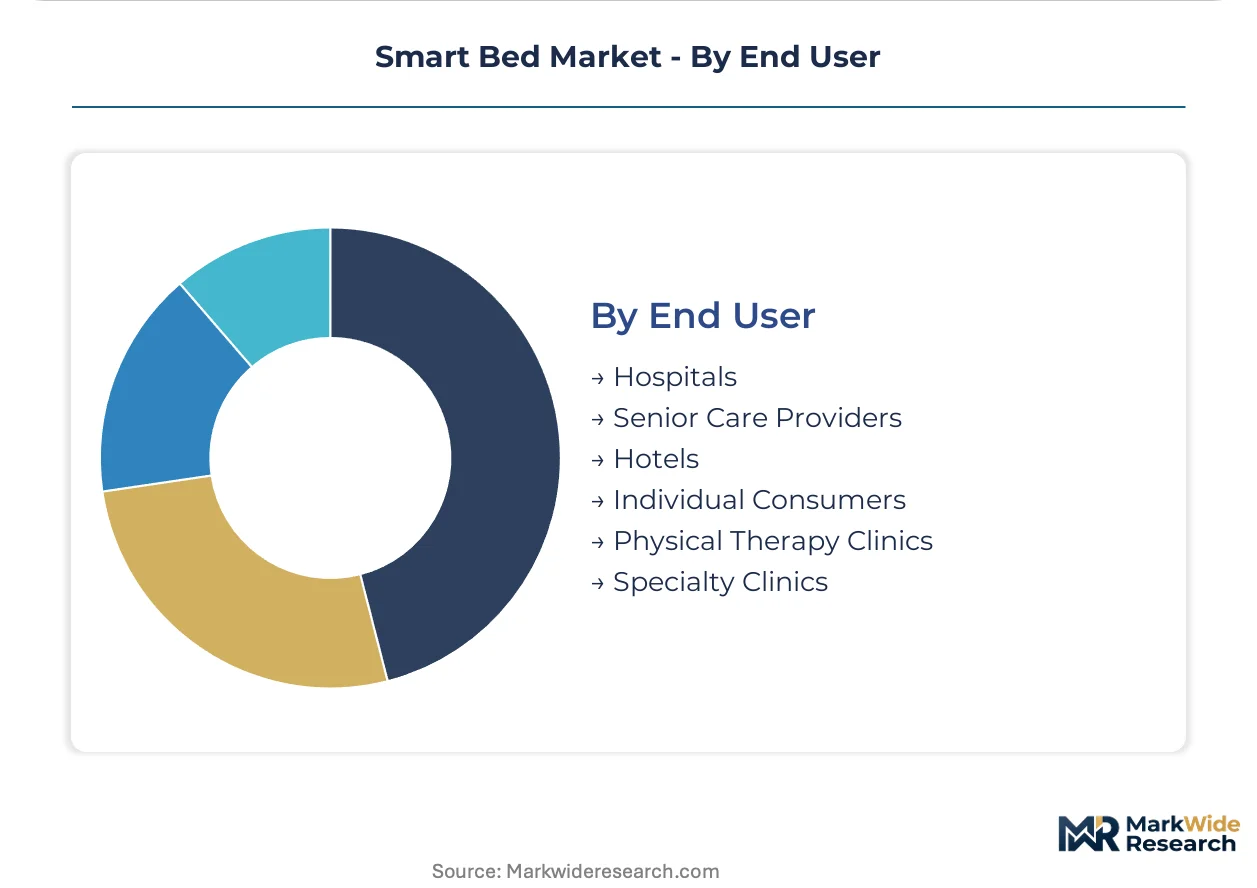
End user segmentation categorizes the primary purchasers and beneficiaries of smart bed technologies. This distinction influences product design, marketing strategies, and distribution channels.
- Individual Consumers:This group purchases smart beds for personal wellness, sleep improvement, and home health monitoring. Demand from individual consumers is concentrated in developed markets like the United States.
- Hospitals:Hospitals procure clinical-grade smart beds for patient care, critical monitoring, and operational efficiency within medical environments. Procurement decisions are heavily influenced by regulatory compliance and IT system interoperability.
- Senior Care Providers:These organizations acquire smart beds to enhance the safety and comfort of elderly residents.
- Hotels:The hospitality sector invests in smart beds to differentiate guest experiences.
- Physical Therapy Clinics:These clinics use smart beds to support patient rehabilitation and recovery.
- Specialty Clinics:Focused medical centers, such as sleep clinics, utilize advanced smart beds for diagnostic purposes.
The Individual Consumers segment is climbing the fastest in volume. Hospitals represent a stable, high-value end-user base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston area, with its robust medical technology and academic research ecosystem, drives innovation in smart bed development. This concentration of expertise fosters advancements in AI sleep analysis and IoT integration for clinical applications. Such regional strengths are influencing market dynamics across developed economies.
United States
Demand for smart beds in the United States stems from strong consumer wellness interest and extensive clinical adoption. FDA oversight ensures product safety for medical-grade devices, influencing manufacturer investment. Silicon Valley and Boston are hubs for health tech startups, developing advanced sensor and AI solutions.
Germany
Germany's aging population and preventative care emphasis fuel significant demand for smart beds in home and healthcare settings. Compliance with CE marking and MDR is critical for market access, impacting product design. Munich and Berlin attract R&D in AI-powered patient monitoring solutions.
Japan
Japan presents substantial demand for smart beds due to its rapidly aging demographic and advanced healthcare infrastructure. The PMDA regulates clinical-grade products, ensuring stringent quality standards for patient care. The Tokyo metropolitan area leads in geriatric care technology, integrating smart beds into elderly support systems.
South Korea
South Korea's modernizing healthcare system and rising disposable incomes drive smart bed adoption for wellness and clinical uses. The MFDS oversees medical device approvals, promoting innovation in connected health solutions. The Seoul Capital Area is a key region for digital health startups, specializing in IoT integration.
United Kingdom
The United Kingdom's focus on remote patient monitoring and preventative healthcare supports growing smart bed demand. The MHRA provides regulatory oversight for medical devices, impacting market entry strategies. London's health tech cluster is a focal point for AI research and digital health platform development.
Smart Bed Market Key Industry Players
Capital-heavy producers of traditional bed systems compete with asset-light technology firms specializing in sensor and software development. The market structure bifurcates between established medical device manufacturers and consumer-focused wellness brands. Strategic archetypes include specialized clinical solution providers, direct-to-consumer innovators, and broad retail network operators. Strategic partnerships between hardware manufacturers and AI/IoT developers define competitive moves.
Within the clinical solutions archetype, Hill-Rom Holdings Inc. exemplifies a focus on medical-grade features and healthcare facility integration. Sleep Number Corporation represents the direct-to-consumer segment, leveraging brand recognition for personalized sleep experiences. Tempur Sealy International Inc. occupies a position among broad retail network operators, emphasizing material science innovations and extensive distribution. These players collectively illustrate the diverse pathways for market engagement, from specialized medical applications to mass consumer wellness.
| Leading Market Players |
|---|
| Hill-Rom Holdings Inc |
| Invacare Corporation |
| Sleep Number Corporation |
| Tempur Sealy International Inc |
| Eight Sleep Inc |
| Paramount Bed Co Ltd |
| Arjo AB |
| Joerns Healthcare LLC |
| Stryker Corporation |
| Others |
Cost & Logistics Intelligence
Hospitals and healthcare facilities procurement, driven by stringent medical device regulations, anchors a value-based pricing model for clinical-grade smart beds. This concentration of demand ensures premium pricing for specialized features and compliance.
Pricing Analysis
Value-based pricing for smart beds ties directly to patient outcomes, such as reduced pressure ulcers and improved sleep quality in clinical settings. The dominant pricing structure is a hybrid model, combining an upfront hardware purchase with recurring software and service subscriptions. Price differentiation stems from medical device certification levels, like FDA oversight, and the integration of advanced AI sleep analysis features. Pricing softness in the consumer segment reflects the high initial product cost, while hospitals exhibit lower price sensitivity for medical-grade devices that enhance operational efficiency.
Supply Chain Analysis
Direct-to-consumer (DTC) channels and extensive retail networks dominate smart bed distribution for the home care segment, while clinical-grade products move through specialized medical equipment distributors. Component manufacturing concentrates in East Asia, particularly South Korea and China, for sensors and IoT modules; final assembly often occurs in the United States and Germany. The supply chain relies on specialized sleep monitoring sensors, AI processors, and advanced foam materials. Single-source vulnerability for proprietary sensor technology poses a structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart bed market operates as a supply-constrained story, particularly for medical-grade devices, where specialized component availability and regulatory compliance expertise limit production. This bottleneck for advanced sensor integration props up premium pricing in the healthcare segment.
For Market Incumbents: Lock in long-term supply agreements for advanced AI processors and specialized sleep monitoring sensors to secure critical component access. Invest heavily in FDA and MDR compliance certifications to raise barriers for new entrants, countering the threat from asset-light technology firms. Expand direct-to-consumer channels, leveraging brand recognition to mitigate retail network erosion.
For New Entrants and Emerging Players: The EU's Medical Device Regulation (MDR) in Europe opens a window for specialized software-as-a-medical-device (SaMD) solutions that integrate with existing bed hardware. Target the assisted living centers segment in Germany, which is highly penetrable due to aging populations and preventative care mandates. Partner with established medical device distributors for rapid market access.
For Investors and Strategic Acquirers: The window for entry favors specialized technology firms with proven AI sleep analysis algorithms and robust data security protocols. Long-term viability over the next decade hinges on integrating smart bed data into holistic digital health ecosystems. Watch for increased hospital procurement budgets specifically allocated to remote patient monitoring solutions as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Pursue FDA 510(k) Clearance for AI Software | Securing FDA clearance validates AI algorithms for clinical use, unlocking market access in the United States healthcare sector. |
| Develop Subscription-Based Sleep Coaching Services | This initiative creates recurring revenue streams and fosters long-term customer relationships in the consumer wellness segment. |
| Form Partnerships with EHR Providers | Integrating smart bed data with Electronic Health Records enhances clinical workflow efficiency for hospitals and care facilities. |
| Expand Manufacturing Capacity in Germany | Localized production addresses European MDR compliance and caters to the strong demand from Germany's aging population. |
| Invest in Ambient Sensing Technology R&D | Non-intrusive monitoring capabilities enhance user comfort and expand application into sensitive long-term care environments. |
Research Approach
Independent corroboration across medical device filings, healthcare expenditure reports, and consumer wellness surveys underwrites the qualitative findings of this analysis. Primary interviews with hospital procurement managers, biomedical engineers, sleep specialists, and direct-to-consumer brand managers provided critical insights. Secondary validation utilized FDA submissions, CE marking documentation, and national health statistics from Germany and Japan. This approach employed both bottom-up and top-down triangulation for robust data synthesis.
The forecast window was anchored to historical performance data from the past five years, establishing a comparable period for trend analysis. The analytical framework modeled segmentation dimensions including product type, technology, application, and end-user, alongside regional regulatory adherence. Compound Annual Growth Rates were derived from a regression analysis of historical and projected market drivers. Key forecast inputs included aging population demographics and healthcare IT investment trends.
The model assumes a particular technology adoption path for AI sleep analysis and IoT integration; alternative pathways for ambient sensing technology would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and consumer acceptance of health data sharing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Bed Wedge Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
Canopy Beds Market
Bedroom Furniture
Malaysia Pillow Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
United Kingdom Mattress Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
Baby Cribs and Cots Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
China Mattress Market
Bedroom Furniture
Luxury Mattress Market