
 Global Mattress Market | 2026-2036
Global Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mattress Market Outlook
The mattress industry is consolidating around a sharp split between premium sleep systems and commodity bedding. Tempur Sealy International leverages its proprietary pressure-relieving foam formulations to dominate the premium segment across North American and European retail channels. Serta Simmons Bedding anchors the mid-market through extensive wholesale partnerships with furniture chains and hospitality procurement programs.
A mattress is a sleep support system engineered from layered foam, spring coils, latex, or hybrid assemblies designed to distribute body weight, regulate thermal comfort, and maintain spinal alignment over sustained use cycles. Memory foam formulations with open-cell gel infusions now compete directly against innerspring platforms for pressure relief performance. The residential application segment sustains the largest volume base, while the hospitality channel generates superior margin pools through bulk replacement contracts with international hotel operators. Online distribution channels are capturing share from retail stores by offering compressed-roll delivery and extended trial periods.
The US Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1633, while the EU's REACH regulation restricts certain chemical flame retardants in polyurethane foams. California's Bureau of Household Goods and Services maintains additional labeling requirements that de facto shape national product specifications for brands selling across state lines. Stakeholders must monitor evolving chemical disclosure mandates and circular economy requirements that will determine which material platforms retain market access.
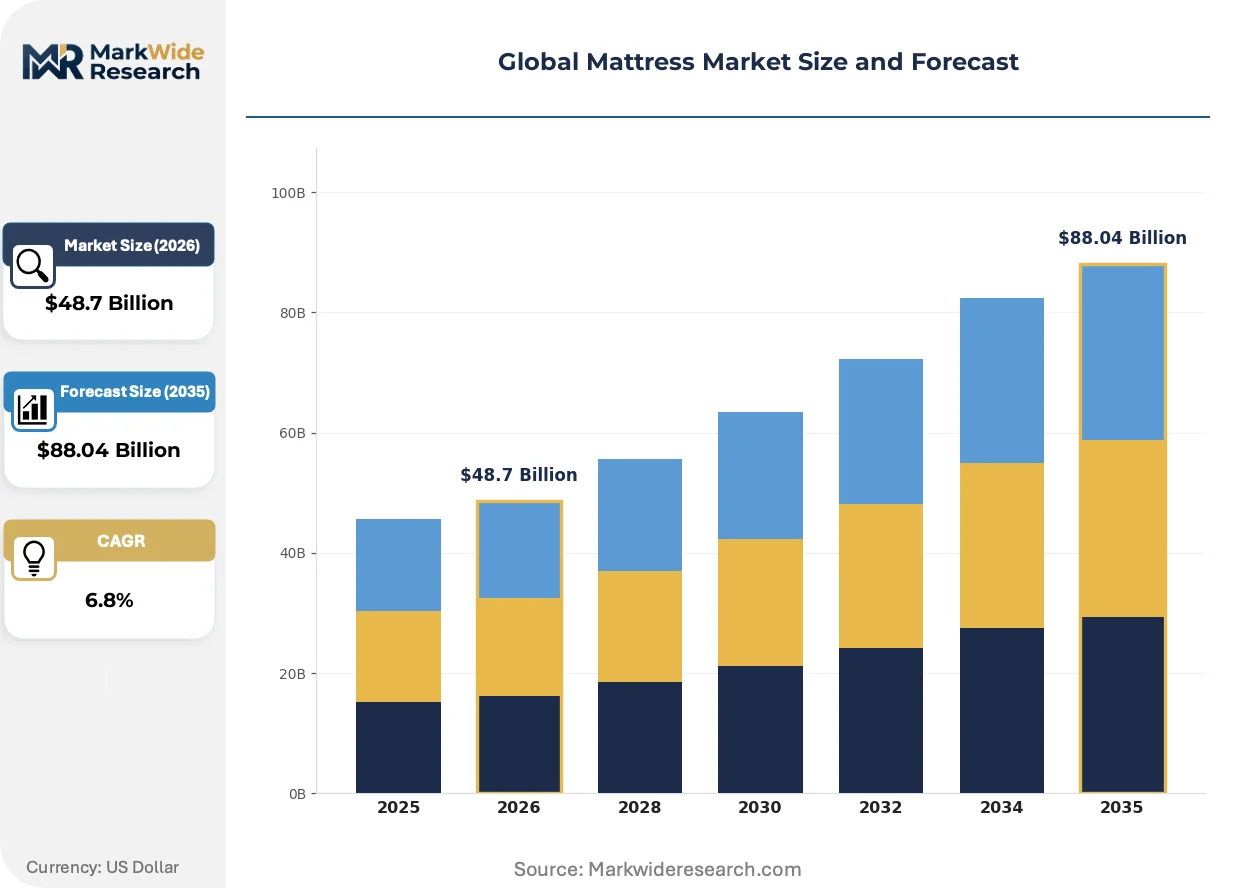
Market Dynamics
The EU's Ecodesign for Sustainable Products Regulation is forcing foam chemistry reformulation across manufacturing footprints, while hospitality procurement consolidation compresses replacement cycles and concentrates supplier negotiation leverage.
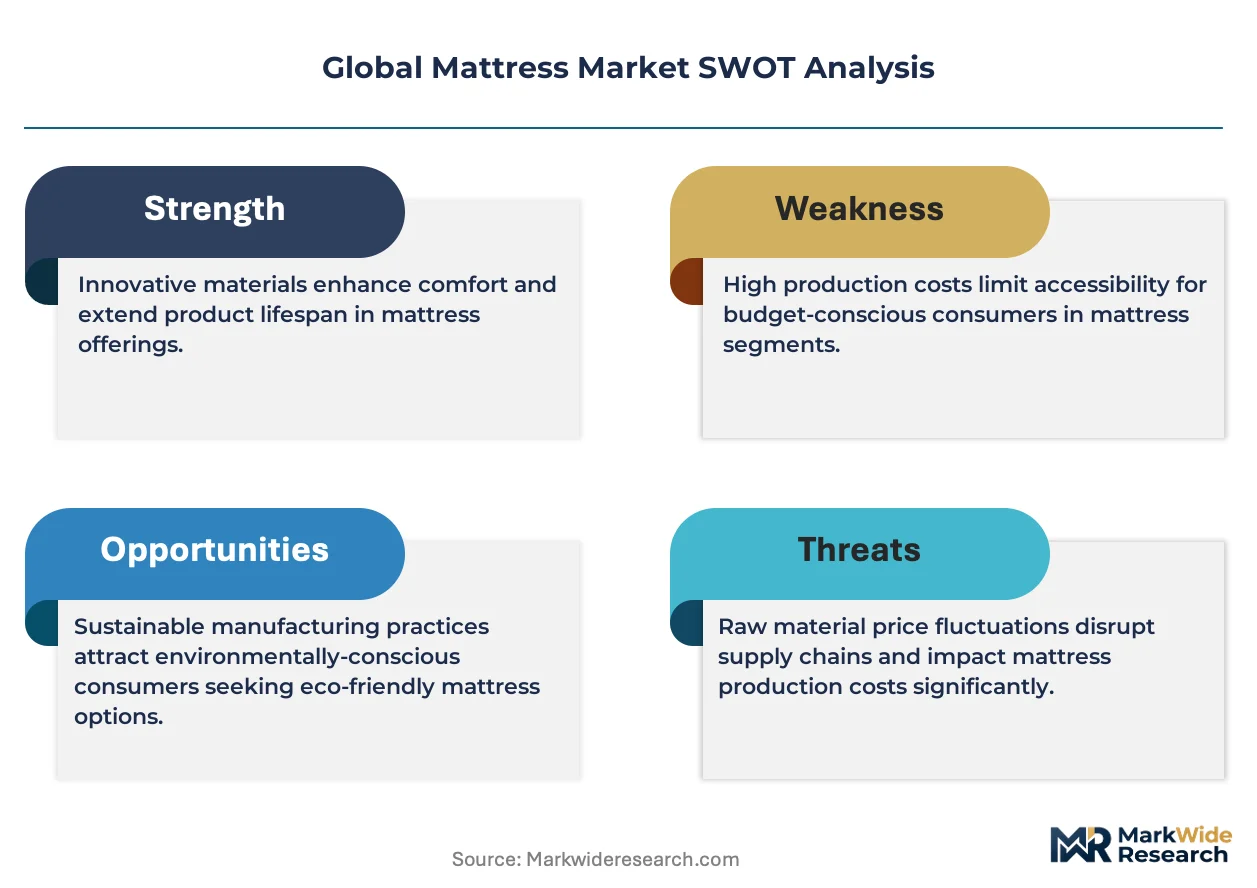
Growth Catalysts
- REACH chemical disclosure mandates:European manufacturers accelerating material transparency investments are capturing premium positioning in regulated retail channels.
- China tier-one city retail expansion:Flagship store networks in Shanghai, Beijing, and Shenzhen are building direct consumer relationships outside wholesale dependency.
- Open-cell gel infusion technology:Thermal regulation performance gains are converting innerspring loyalists in warm-climate residential markets.
Market Restraints
- Petrochemical input volatility:Polyether polyol and TDI price swings compress foam producer margins without immediate pass-through mechanisms.
- US-China tariff exposure:Cross-border component sourcing faces duty uncertainty that disrupts just-in-time assembly schedules.
- Latex substitution pressure:Natural rubber mattress cores from Southeast Asian processors compete on biodegradability claims in EU eco-conscious segments.
Strategic Opportunities
- India urban middle-class penetration:Organized retail and e-commerce logistics maturity in Mumbai, Delhi, and Bangalore unlock first-time branded mattress adoption.
- Circular economy remanufacturing:EU Extended Producer Responsibility frameworks create closed-loop foam recovery revenue streams.
- AI-driven sleep personalization:Sensor-integrated adjustable bases converging with biometric apps are opening subscription-based wellness revenue models.
Industry Challenges
- 16 CFR Part 1633 compliance certification:US flammability testing timelines add 8-12 weeks to product launch schedules.
- Multi-material disassembly expertise:Hybrid mattress construction complicates end-of-life sorting and recycling workforce training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mattress Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Innerspring, Memory Foam, Latex, Hybrid Application: Residential, Commercial, Hospitality, Healthcare Size: Single, Double, Queen, King Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Tempur Sealy International, Serta Simmons Bedding, Sleep Number Corporation, Kingsdown, Purple Innovation, Paramount Bed Holdings, Grupo Pikolin, Sheela Foam, Casper Sleep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mattress Market Strategic Shifts
Compressed-roll packaging and direct-to-consumer logistics are compressing traditional retail intermediation, while material science advances and regulatory transparency mandates reshape competitive differentiation.
Copper-infused memory foam is decentralizing thermal conductivity and antimicrobial claims from niche medical applications into mainstream residential positioning. Sleep clinics and athletic recovery facilities in Germany and Australia are specifying copper-layer constructions for patient temperature management. This formulation shift is decentralizing premium feature ownership from gel-foam patent holders toward additive-agnostic producers.
California's Bureau of Household Goods and Services labeling requirements are de facto nationalizing disclosure standards for brands selling across US state lines. The regulation mandates detailed component percentages and origin documentation that smaller manufacturers struggle to compile. Upholstery suppliers serving California, Texas, and Florida distribution hubs are consolidating compliance documentation to avoid shipment holds.
Extended in-home trial periods are displacing showroom-dependent purchase confidence models in North American and European markets. Digital-native brands offering 100-night return guarantees are capturing urban millennial households previously loyal to furniture chain financing programs. This behavioral shift concentrates fulfillment infrastructure investment in regional distribution nodes outside traditional retail corridors.
Global Mattress Market Segmentation
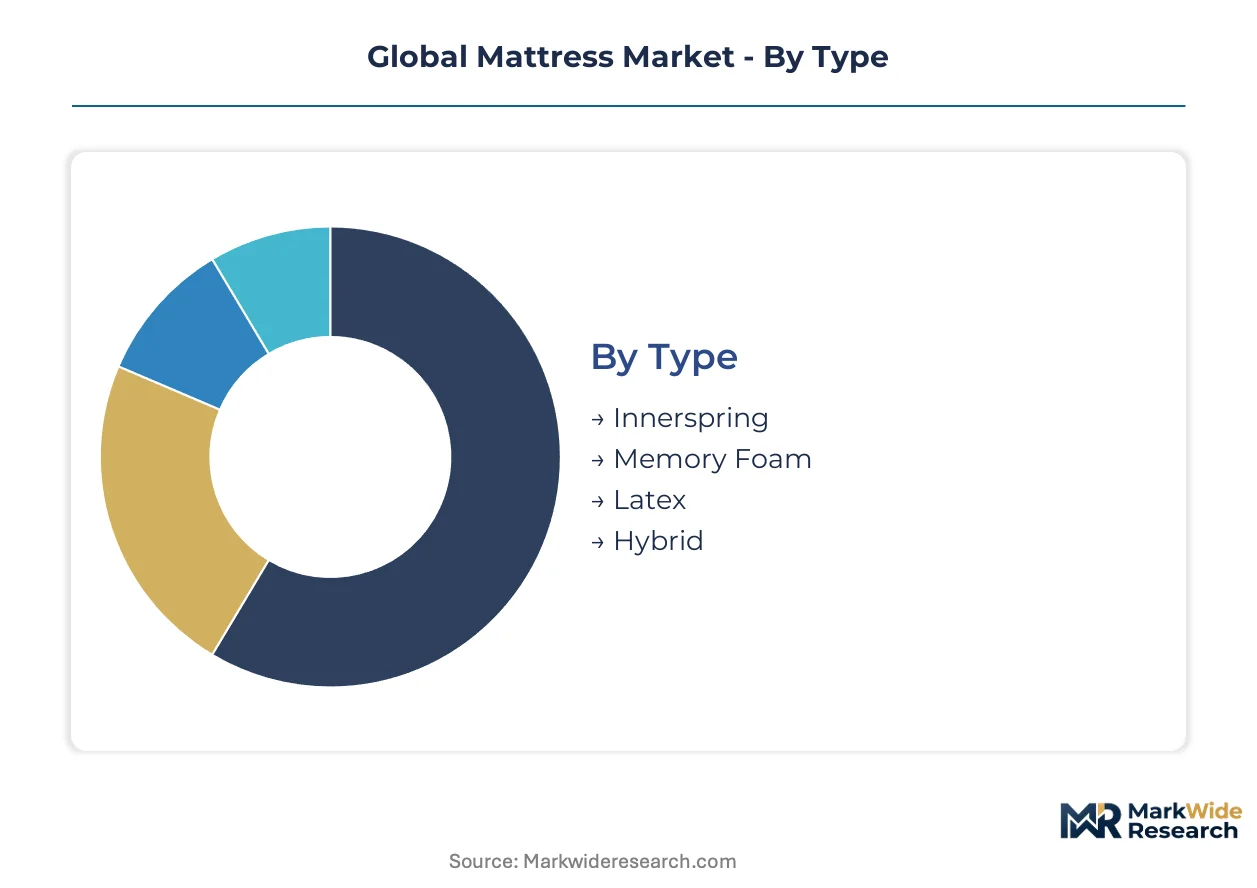
Mattress segmentation determines manufacturing footprint allocation and margin capture strategy. Material platform selection locks in foam chemistry investments and regulatory compliance pathways for multi-year production cycles.
Type:
Memory foam and innerspring platforms concentrate production capacity across polyurethane chemical clusters in China, the US, and Germany.
- Innerspring:Steel coil assemblies with fabric-encased pocket springs deliver responsive support through zoned compression. Hospitality procurement programs in the United States and Germany specify innerspring platforms for durability under high-occupancy cycling, though coil corrosion risk in humid climates limits tropical market penetration.
- Memory Foam:Viscoelastic polyurethane formulations with open-cell gel infusions conform to body contours while dissipating heat. China's tier-one cities—Shanghai, Beijing, Shenzhen—drive premium memory foam adoption as consumers upgrade from traditional cotton futon systems, pressured by REACH-compliant European imports raising transparency expectations.
- Latex:Natural rubber or synthetic polymer cores offer biodegradability advantages under EU Extended Producer Responsibility frameworks.
- Hybrid:Combined spring and foam layers balance pressure relief with structural support for premium residential positioning.
Today's leader: Memory Foam. Tomorrow's challenger: Hybrid.
Application:
Residential volume sustains manufacturing scale while hospitality and healthcare channels extract premium pricing through specification contracts.
- Residential:Individual household purchases through retail and online channels constitute the foundational demand base. India's urban middle-class in Mumbai, Delhi, and Bangalore is driving first-time branded mattress adoption as organized retail and e-commerce logistics mature.
- Hospitality:Bulk replacement contracts with international hotel operators generate superior margin pools through compressed procurement cycles. Marriott and Hilton procurement consolidation in the United States and Germany is concentrating supplier negotiation leverage toward multi-year framework agreements.
- Commercial:Office nap pods, co-living spaces, and institutional dormitories in Japan and South Korea specify standardized durability ratings.
- Healthcare:Pressure ulcer prevention and patient temperature management requirements in German and Australian sleep clinics drive copper-infused foam specifications.
Residential commands volume. Hospitality commands margin.
Size:
Dimensional standardization enables compressed-roll logistics while regional preferences dictate SKU allocation across distribution nodes.
- Queen:North American residential standard balancing space efficiency with couple accommodation. US e-commerce brands targeting urban millennial households prioritize queen dimensions for apartment delivery compatibility.
- King:Premium master bedroom positioning in suburban US and Australian markets with sufficient floor space. California king variants address height-differentiated couple needs in Western US states.
- Double:Compact couple accommodation standard in European and Japanese urban apartments where space constraints dominate.
- Single:Children's rooms, guest accommodations, and institutional dormitory specifications across India and Southeast Asia.
Queen anchors North American logistics. King defines premium aspiration.
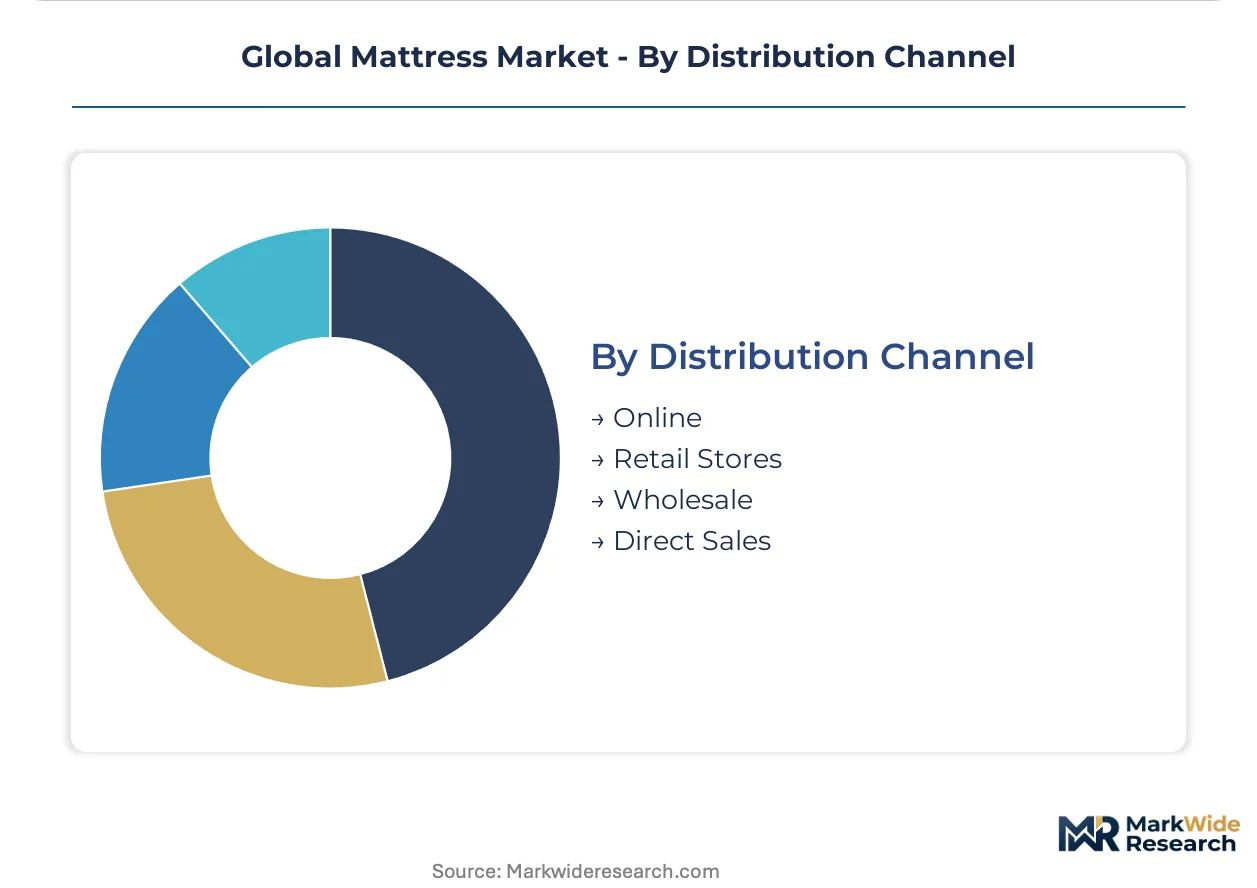
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition cost structure across geographic markets.
- Online:Compressed-roll delivery and extended trial periods displace showroom dependency. Digital-native brands offering 100-night return guarantees capture urban millennial households in the United States, United Kingdom, and Germany previously loyal to furniture chain financing.
- Retail Stores:Touch-and-feel purchase confidence sustains furniture chain partnerships in suburban US markets and European small-town networks where delivery infrastructure remains underdeveloped.
- Wholesale:Furniture retailer and hospitality procurement bulk purchasing concentrates volume through Serta Simmons Bedding partnerships in North America.
- Direct Sales:Flagship store networks in Shanghai, Beijing, and Shenzhen build direct consumer relationships for premium brands outside wholesale dependency.
Online gains fastest in logistics-mature markets. Retail defends where touch matters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled foam chemists and textile engineers cluster in Germany's industrial corridor, China's coastal manufacturing zones, and the US Southeast furniture belt, anchoring three distinct production ecosystems with diverging regulatory exposures and demand profiles.
United States
Urban millennial households in Atlanta and Charlotte drive compressed-roll e-commerce adoption, while hospitality procurement teams in Dallas and Chicago negotiate multi-year framework agreements with premium suppliers. The US Consumer Product Safety Commission enforces 16 CFR Part 1633 flammability standards that add certification delays to product launches. North Carolina's furniture manufacturing corridor around High Point concentrates innerspring assembly and upholstery finishing operations for domestic distribution.
Germany
Sleep clinics in Munich and Stuttgart specify copper-infused foam constructions for patient temperature management, creating premium specification channels distinct from mass retail. The EU's Ecodesign for Sustainable Products Regulation pressures manufacturers in Bavaria and Baden-Württemberg to reformulate polyurethane chemistries and disclose material contents. The Rhine-Main chemical cluster near Frankfurt supplies specialized polyols and isocyanates to foam producers serving regulated European markets.
China
First-time branded mattress buyers in Shanghai, Beijing, and Shenzhen upgrade from traditional cotton futon systems, attracted by flagship retail networks and domestic memory foam production. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions standards for polyurethane foam plants in Jiangsu and Zhejiang provinces. The Yangtze River Delta manufacturing belt around Suzhou and Nantong hosts integrated foam-chemical-to-mattress production complexes serving both domestic and export demand.
India
Organized retail penetration in Mumbai, Delhi, and Bangalore unlocks first-time branded mattress adoption among urban middle-class households transitioning from unorganized sector purchases. The Bureau of Indian Standards maintains labeling and quality certification requirements that formalize product specifications for multi-brand retailers. Gujarat's chemical processing corridor near Vadodara supplies polyether polyols to foam producers serving western and northern Indian distribution networks.
Japan
Commercial sleep pod operators and co-living space developers in Tokyo and Osaka specify standardized durability ratings for institutional procurement cycles. The Ministry of Economy, Trade and Industry oversees JIS standards that govern mattress performance claims in domestic retail channels. The Kansai industrial region around Osaka maintains specialized textile and foam processing capabilities for premium residential and healthcare applications.
Global Mattress Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated chemical-to-mattress manufacturers face pressure from direct-to-consumer brands outsourcing fabrication. The vendor base separates into three archetypes: proprietary foam formulators defending patent positions, wholesale-dependent assemblers anchoring furniture chain relationships, and digital-native marketers capturing trial-period loyalty. Consolidation pressures concentrate around hospitality procurement leverage and EU regulatory compliance costs that favor scaled operators with dedicated sustainability teams.
Within the premium foam formulation tier, Tempur Sealy International and Sleep Number Corporation occupy positions defined by proprietary material science and adjustable base integration. Serta Simmons Bedding exemplifies the wholesale-anchored archetype through furniture chain and hospitality procurement dominance. Purple Innovation represents the additive-technology challenger model, leveraging gel-grid constructions to differentiate from conventional memory foam positioning. These three anchors illustrate how competitive advantage separates across chemical innovation, channel control, and construction novelty.
| Leading Market Players |
|---|
| Tempur Sealy International |
| Serta Simmons Bedding |
| Sleep Number Corporation |
| Kingsdown |
| Purple Innovation |
| Paramount Bed Holdings |
| Grupo Pikolin |
| Sheela Foam |
| Casper Sleep |
| Others |
Value Chain & Pricing Dynamics
Polyether polyol and TDI feedstock costs cascade through polyurethane foam production tiers, with petrochemical volatility in the US Gulf Coast and Rotterdam refining clusters compressing margins at mid-market assemblers while premium formulators pass through formula premiums to hospitality procurement teams.
Pricing Analysis
White-glove delivery and old mattress removal services separate bundled premium offerings from stripped-down direct-to-consumer pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by foam density certification and trial period length, with California king and adjustable base configurations commanding widest spreads. Cost compression in the standard tier intensifies because wholesale furniture chains demand volume rebates without brand marketing support. Urban millennial households purchasing through compressed-roll channels exhibit highest price sensitivity, while hospitality procurement teams negotiating multi-year framework agreements prioritize durability specifications over per-unit cost.
Supply Chain Analysis
Steel coil supply rests on German automotive-grade wire producers and Chinese hot-rolled steel mills serving the Yangtze River Delta foam-to-mattress corridor. Polyurethane chemical production draws from the US Gulf Coast petrochemical cluster, Rotterdam refining hubs, and Jiangsu province specialty chemical plants. Single-source vulnerability concentrates in TDI isocyanate supply where three producers control European and North American volume. Distribution runs through regional compression-and-roll fulfillment nodes outside traditional furniture retail corridors, with last-mile logistics partnerships determining urban penetration speed.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EU REACH compliance investments raising European production costs and India's underpenetrated branded mattress sector where organized retail infrastructure now supports premium positioning.
For Market Incumbents: Deploy backward integration into captive polyol production to defend margin position against petrochemical input volatility threatening mid-market assemblers. Consolidate hospitality procurement relationships through multi-year framework agreements before procurement team consolidation at Marriott and Hilton concentrates supplier negotiation leverage further. Accelerate copper-infusion and gel-grid R&D to preempt additive-agnostic challengers from decentralizing thermal regulation claims. For New Entrants and Emerging Players: Direct-to-consumer subscription models for sensor-integrated adjustable bases offer lowest customer acquisition cost entry into North American and German urban markets. Target India's Mumbai-Delhi-Bangalore corridor where first-time branded mattress adoption among urban middle-class households outpaces organized retail supply. Lead with 100-night trial guarantees and biometric app integration to differentiate from furniture chain financing programs. For Investors and Strategic Acquirers: Consolidation pressure builds where EU Extended Producer Responsibility compliance costs and Ecodesign disclosure mandates favor scaled operators with dedicated sustainability teams over fragmented regional assemblers. Over a five-to-ten year horizon, vertically integrated foam-to-mattress manufacturers with REACH-compliant chemistry platforms and hospitality procurement relationships represent highest viability acquisition targets. Monitor copper-infused foam specification rates in German sleep clinics and Australian athletic recovery facilities as inflection indicator for premium material platform shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Captive TDI supply from US Gulf Coast petrochemical clusters insulates margins from volatility. |
| REACH-Compliant Chemistry Reformulation | EU Ecodesign disclosure mandates determine market access for European retail channels. |
| Direct-to-Consumer Subscription Launch | Biometric app integration with adjustable bases opens recurring revenue in urban millennial households. |
| Hospitality Procurement Framework Expansion | Multi-year agreements with Marriott and Hilton procurement teams lock in superior margin pools. |
| Circular Economy Remanufacturing Infrastructure | EU Extended Producer Responsibility frameworks create closed-loop foam recovery revenue streams. |
Study Parameters
Coverage spans North America, Europe, Asia-Pacific, and India, with primary inputs from each combining executive interviews with foam plant managers, hospitality procurement directors, furniture chain category buyers, and polyurethane chemical R&D leads with secondary validation through customs trade data, SEC 10-K filings, and Cefic chemical production reports. Bottom-up shipment data from regional compression-and-roll fulfillment nodes triangulates against top-down petrochemical feedstock consumption estimates.
Rate-of-change decomposition separates volume growth from mix-shift and pricing dynamics across the analysis window, with segmentation modeling across material platform, application channel, size specification, and distribution method. CAGRs derive from historical elasticity estimates applied to projected household formation rates, hospitality occupancy recovery patterns, and e-commerce logistics penetration curves. Forecast inputs incorporate REACH chemical disclosure implementation timelines and India's organized retail infrastructure buildout assumptions.
The model assumes a particular technology adoption path; alternative pathways for AI-driven sleep personalization and sensor-integrated adjustable bases would alter the outlook if biometric app integration stalls or wellness subscription fatigue emerges. Forecasts reflect assumptions about EU regulatory enforcement intensity, US-China tariff stability, and petrochemical price normalization. A small set of named triggers—copper-infusion specification rates, hospitality procurement consolidation announcements, and India e-commerce logistics maturity metrics—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Australia Mattress Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
China Mattress Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Latin America Mattress Market
Bedroom Furniture
Canopy Beds Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
US Wall Beds Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
Malaysia Pillow Market