
 Cloud PBX Market | 2026-2036
Cloud PBX Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud PBX Market Intelligence
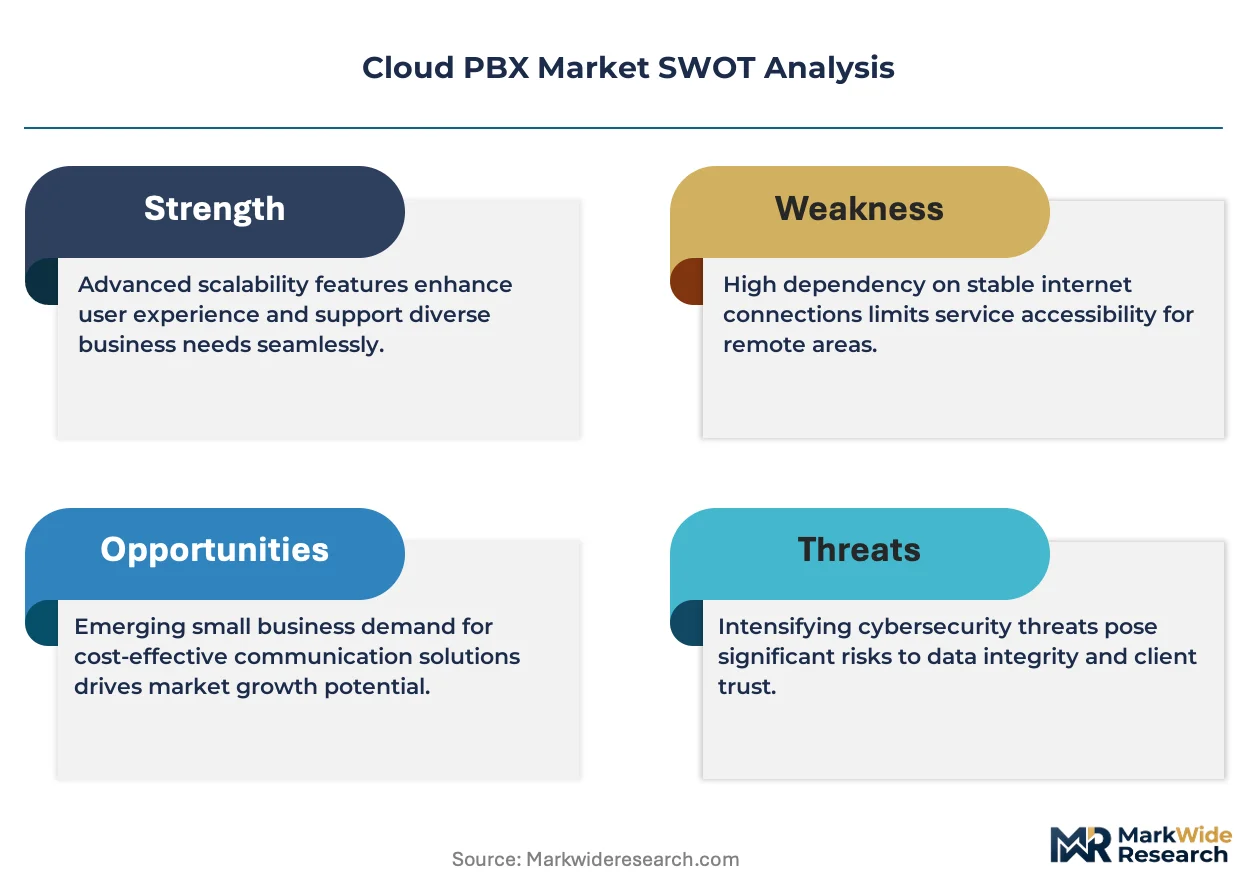
A shortage of certified VoIP network engineers is redrawing competitive dynamics across the Cloud PBX landscape. RingCentral leverages its channel partner density to capture mid-market accounts that competitors struggle to serve. 8x8 sustains R&D intensity in contact-center integration, while Vonage anchors its position through API-first programmable voice infrastructure.
Cloud PBX denotes a telephone exchange system hosted on remote servers and delivered via internet protocol, typically supporting SIP trunking, automatic call distribution, and least-cost routing across geographically distributed endpoints. Its primary commercial purpose is to eliminate capital expenditure on private branch exchange hardware while enabling real-time scalability for fluctuating call volumes. Public cloud deployments lead in new customer acquisition due to minimal upfront commitment, whereas hybrid cloud configurations capture margin pools from financial services firms requiring on-premise session border controllers for compliance. Unified communications as a service type is expanding fastest as vendors bundle messaging, video, and telephony into single subscriptions.
The FCC enforces network reliability standards and rural broadband deployment mandates that directly shape carrier infrastructure investments and Cloud PBX service availability. GDPR in Europe and HIPAA in the United States impose encryption, data residency, and access-log requirements that vendors must architect into multi-tenant platforms. ISO 27001 certification has become a de facto gate for enterprise procurement evaluations. Stakeholders must monitor how AI-powered call analytics features trigger emerging algorithmic accountability rules across multiple jurisdictions.
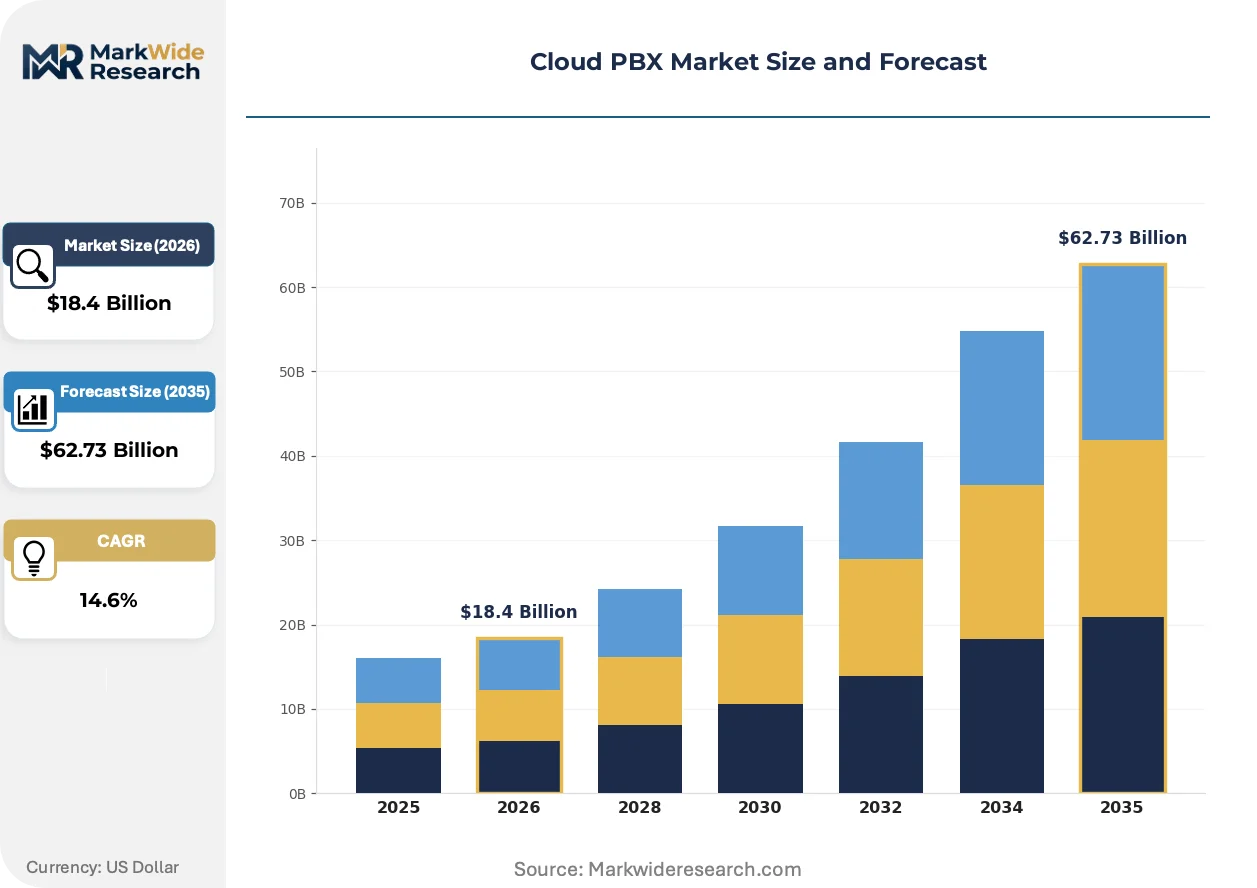
Market Dynamics
The migration from circuit-switched PSTN to packet-based IP infrastructure is compressing carrier revenue models while redistributing margin toward software-centric platform providers. This structural shift forces legacy equipment vendors to pivot subscription architectures or exit voice markets entirely.
Growth Catalysts
- FCC Rural Broadband Initiatives:Federal deployment mandates expand IP network reach into underserved territories, unlocking addressable subscriber bases previously constrained by copper loop limitations.
- Healthcare Vertical Expansion:HIPAA-compliant cloud voice architectures replace aging hospital PBX systems as providers consolidate communications onto unified clinical platforms.
- SIP Trunking Standardization:Session initiation protocol normalization reduces interconnection friction between carrier networks and enterprise edge devices, accelerating multi-site deployment velocity.
Market Restraints
- Certified Engineer Scarcity:Shortage of VoIP network specialists constrains implementation capacity and elongates deployment timelines for complex multi-tenant configurations.
- Last-Mile Infrastructure Gaps:Rural copper retirement outpaces fiber overbuild in certain census tracts, creating service availability dead zones that limit addressable market expansion.
- Legacy Equipment Stranding:Sunk capital in on-premise TDM systems creates organizational inertia among price-sensitive mid-market segments delaying cloud migration decisions.
Strategic Opportunities
- AI-Enabled Call Analytics:Convergence of natural language processing with real-time transcription creates premium service tiers for compliance-heavy financial and legal verticals.
- Hybrid Cloud Architectures:Financial services firms seeking session border controller retention on-premise represent untapped margin pools for vendors with flexible deployment models.
- API-First Programmability:Developer-centric voice infrastructure enables embedded communications within vertical SaaS applications, opening indirect channel revenue streams.
Industry Challenges
- Multi-Jurisdictional Compliance:GDPR data residency requirements in Europe and state-level privacy laws in the United States force architectural complexity into multi-tenant platform design.
- Interoperability Certification Delays:Protracted testing cycles for emergency services (E911) compliance and carrier-grade reliability standards slow product release velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud PBX Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Service Type: VoIP Services, Unified Communications, Disaster Recovery, Call Routing End User: SMBs, Large Enterprises, Government Agencies, Nonprofits Feature: Auto Attendant, Voicemail to Email, Call Analytics, Integrations |
| Companies Covered | 8x8, Dialpad, 3CX, Zadarma, Ringover, Nextiva, RingCentral, XO Communications, Vonage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud PBX Market Strategic Shifts & Innovations
Artificial intelligence integration is fundamentally altering how voice infrastructure delivers value, shifting competitive differentiation from connectivity quality toward intelligence layer capabilities. Platform vendors now embed machine learning throughout the call lifecycle.
Conversational AI is supplanting traditional interactive voice response systems across enterprise contact centers. Healthcare providers and financial institutions deploy natural language understanding engines to automate appointment scheduling and payment processing. This technology compression is collapsing the distinction between telephony infrastructure and customer experience software, forcing pure-play carriers to acquire or partner for AI competency.
The FCC's STIR/SHAKEN authentication mandate requires originating carriers to certify caller identity through digital signature protocols. This regulatory intervention elevates capital requirements for smaller competitive local exchange carriers lacking certificate infrastructure. Tier-one operators leverage compliance investment as competitive moat, while rural telcos face consolidation pressure from authentication cost burdens.
Enterprise buyers increasingly unbundle voice services from traditional managed service contracts, preferring direct platform relationships with consumption-based pricing. Channel partners respond by repositioning around integration and change management rather than resale margin. This disintermediation is most pronounced in the United States, where mid-market enterprises consolidate vendor relationships onto unified communications suites.
Cloud PBX Market Segmentation
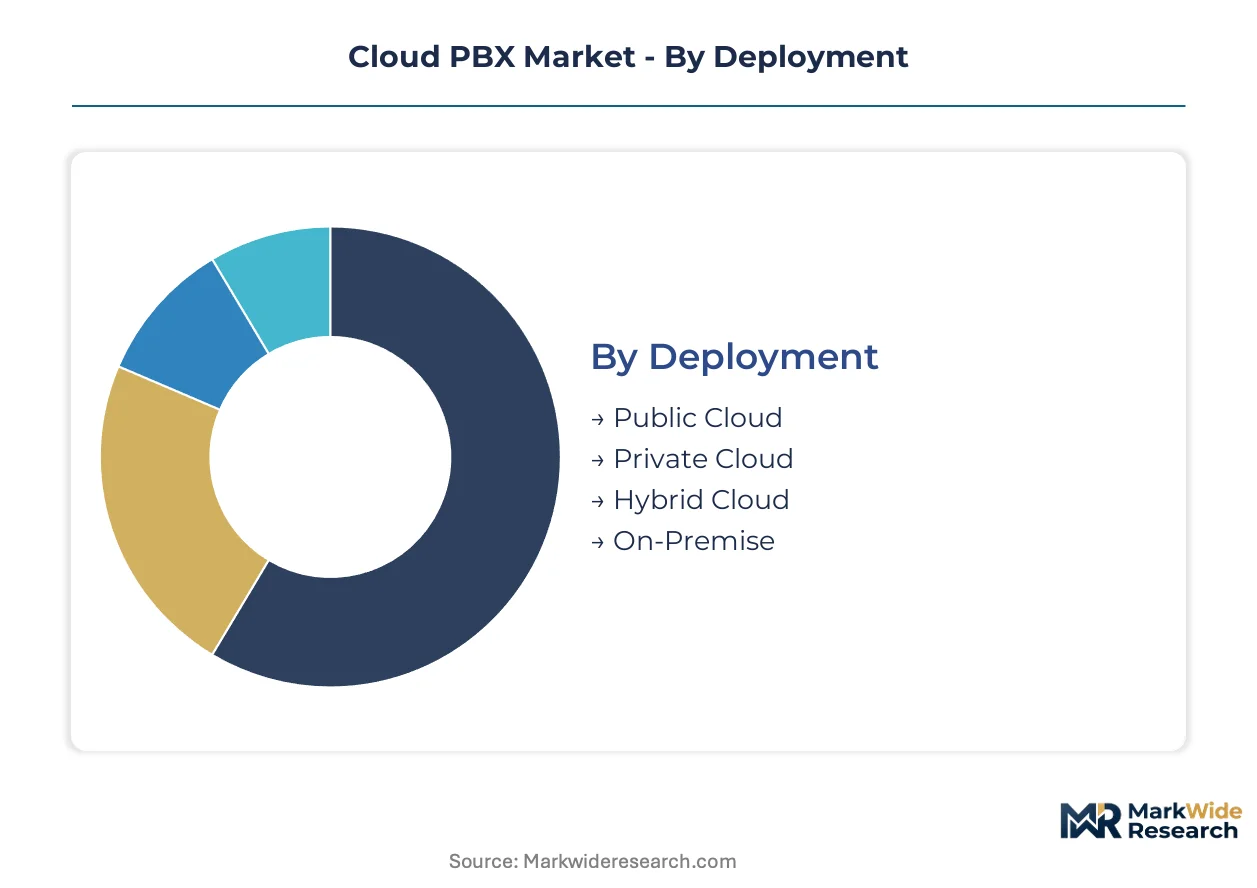
Cloud PBX segmentation reveals how deployment architecture, service bundling, and feature depth create distinct margin pools across customer tiers. Buyers sort themselves by compliance tolerance, IT staff capacity, and integration complexity requirements.
Deployment:
Substitution pressure runs highest where capital constraints meet minimal compliance burden, forcing architectural trade-offs between agility and control.
- Public Cloud:Multi-tenant infrastructure delivers SIP trunking and automatic call distribution via shared data centers with zero hardware commitment. United States mid-market enterprises concentrate demand here as they consolidate legacy telecom spending onto consumption-priced platforms.
- Private Cloud:Single-tenant environments dedicate compute and storage to one organization, supporting custom session border controller configurations. Financial services firms in Germany and Switzerland anchor demand due to GDPR data residency mandates and national banking regulator expectations.
- Hybrid Cloud:Split architectures retain sensitive call control on-premise while bursting overflow capacity to public infrastructure. Healthcare providers in the United States select this model to satisfy HIPAA audit requirements without sacrificing elasticity during seasonal patient volume spikes.
- On-Premise:Self-managed PBX hardware persists in defense contracting and classified government facilities where air-gapped networks are mandatory.
Public cloud anchors the volume base while hybrid cloud gains share at the steepest rate.
Service Type:
Cost tier differentiation separates commodity voice transport from premium collaboration suites with embedded compliance tooling.
- VoIP Services:Packet-switched voice transport replaces circuit-switched PSTN connectivity through SIP trunking standardization. United States rural broadband expansion unlocks subscriber bases previously stranded on copper loop limitations.
- Unified Communications:Bundled messaging, video conferencing, and telephony subscriptions collapse vendor relationships onto single platforms. Large enterprises in the United States drive consolidation as they eliminate redundant point solutions.
- Disaster Recovery:Geographically redundant call routing ensures business continuity during regional network failures. Healthcare systems and financial institutions mandate this capability for operational resilience certification.
- Call Routing:Intelligent distribution algorithms direct inbound traffic based on agent skill, queue depth, and customer priority. Contact centers embed these services within customer experience software stacks.
VoIP services still generate the largest revenue pool while unified communications expands most quickly.
End User:
Customer type determines procurement channel, with direct platform relationships displacing traditional managed service contracts at opposite ends of the size spectrum.
- SMBs:Sub-500-employee organizations prioritize rapid deployment and predictable monthly expenditure over customization depth. United States channel partners capture this segment through integration and change management services rather than hardware resale margin.
- Large Enterprises:Multi-site organizations require least-cost routing across geographically distributed endpoints and centralized administration portals. These buyers negotiate enterprise licensing agreements with API access for CRM and ERP embedding.
- Government Agencies:Federal, state, and municipal entities impose FedRAMP or state-equivalent security certifications that filter vendor eligibility. Procurement runs through approved contractor lists with multi-year contract vehicles.
- Nonprofits:Mission-driven organizations leverage donated or discounted licensing programs from major platform vendors, accepting reduced feature depth for cost elimination.
Large enterprises anchor the volume base while SMBs gain share at the steepest rate.
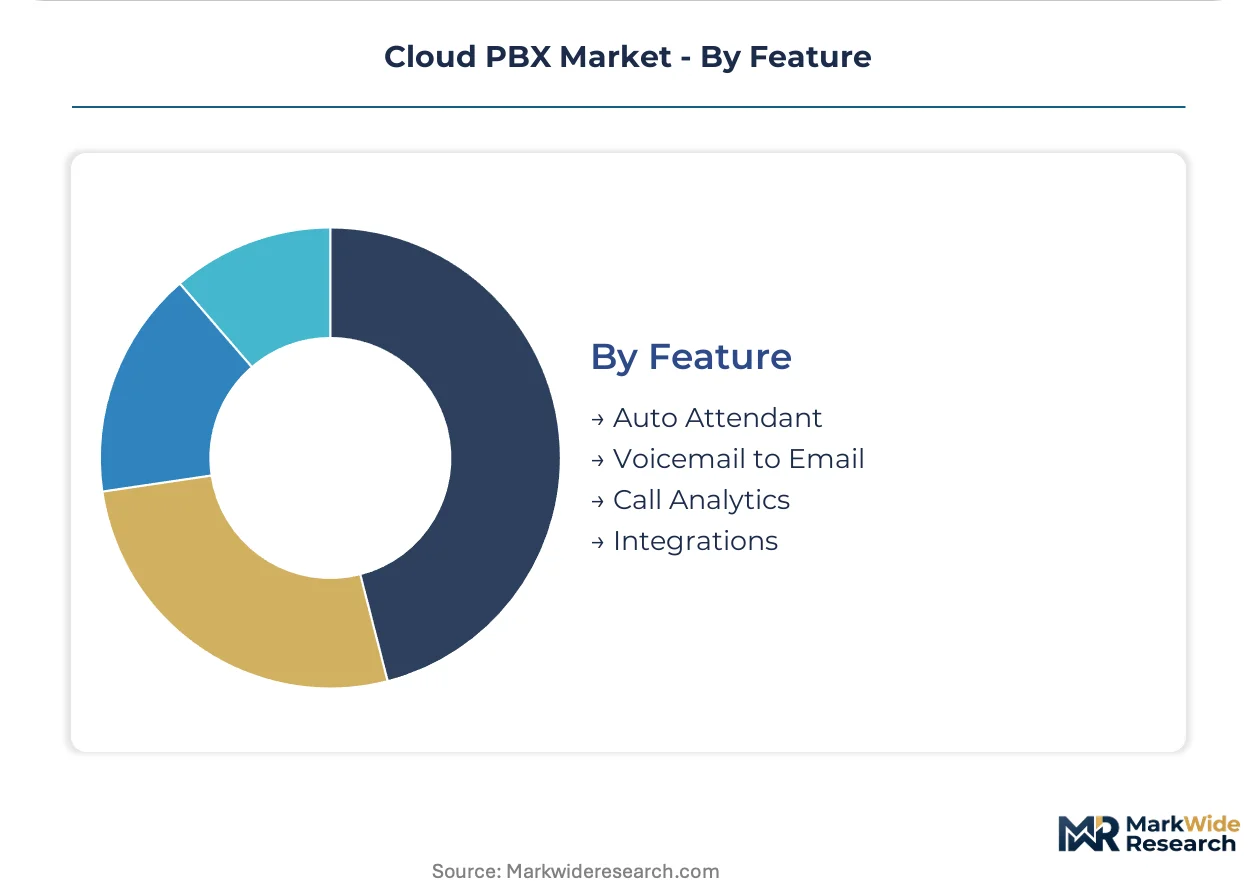
Feature:
Application maturity separates baseline telephony from AI-augmented intelligence layers that command pricing premiums.
- Auto Attendant:Automated menu systems route callers through touch-tone or voice command inputs without human operator intervention. Standard inclusion in base subscriptions limits differentiation value.
- Voicemail to Email:Audio file transcription and delivery to inbox archives creates searchable communication records. Healthcare and legal verticals treat this as compliance infrastructure for audit trails.
- Call Analytics:Real-time transcription and natural language processing extract sentiment, intent, and compliance risk from voice conversations. Financial services firms in the United States and United Kingdom pay premiums for algorithmic supervision of trader and advisor communications.
- Integrations:Pre-built connectors to Salesforce, Microsoft Teams, and vertical SaaS applications embed telephony within workflow software. Developer-centric buyers prioritize API breadth over out-of-box compatibility.
Auto attendant anchors the volume base while call analytics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States enterprises prioritize unified communications consolidation, while European buyers emphasize GDPR-compliant data residency and German financial institutions demand on-premise session border controllers.
United States
Mid-market enterprises drive demand as they consolidate legacy telecom spending onto consumption-priced platforms. The FCC's rural broadband deployment mandates expand IP network reach into previously underserved territories. Healthcare systems in Texas and Florida accelerate replacement of aging hospital PBX systems with HIPAA-compliant cloud voice architectures.
Germany
Financial services firms anchor private cloud demand due to national banking regulator expectations and strict data residency requirements. GDPR enforcement through CNIL-aligned state data protection authorities shapes multi-tenant platform procurement. Frankfurt's banking cluster sustains investment in single-tenant environments with custom session border controller configurations.
United Kingdom
Legal and financial verticals pay premiums for AI-powered call analytics with algorithmic supervision capabilities. The Financial Conduct Authority's operational resilience requirements mandate geographically redundant call routing for trading operations. London's insurance district drives adoption of real-time transcription and natural language processing for compliance documentation.
Japan
Large manufacturers consolidate multi-site voice infrastructure onto centralized administration portals with least-cost routing across distributed endpoints. METI's digital transformation incentives accelerate migration from legacy TDM systems. Osaka's industrial corridor exhibits particular concentration of hybrid cloud deployments balancing elasticity with on-premise control retention.
India
Technology services firms embed programmable voice infrastructure within client-facing SaaS applications through API-first architectures. TRAI's net neutrality frameworks shape interconnection agreements between cloud PBX providers and domestic carriers. Bangalore's software export cluster generates outsized demand for developer-centric telephony platforms with CRM embedding capabilities.
Cloud PBX Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the Cloud PBX market structure. Tier-one operators leverage compliance investment as competitive moat while smaller competitive local exchange carriers face consolidation pressure from authentication cost burdens. Two strategic archetypes dominate: unified communications bundlers and API-first programmable voice specialists. Competitive moves concentrate on M&A for AI competency acquisition and strategic partnerships for vertical SaaS embedding.
Within the unified communications tier, RingCentral and 8x8 exemplify platform consolidation strategies. Vonage occupies a position representing API-first programmable voice infrastructure. These three entities anchor the competitive spectrum from bundled collaboration suites to developer-centric embedding capabilities.
| Leading Market Players |
|---|
| 8x8 |
| Dialpad |
| 3CX |
| Zadarma |
| Ringover |
| Nextiva |
| RingCentral |
| XO Communications |
| Vonage |
| Others |
Cost & Logistics Intelligence
SIP trunking standardization replacing circuit-switched PSTN infrastructure simultaneously redistributes supply geography toward software-centric platform providers and compresses pricing power for legacy hardware vendors dependent on copper loop deployments. This substitution dynamic forces carrier revenue models toward consumption-based SaaS architectures while elevating margin capture for cloud-native orchestration layers.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, with annual or multi-year SaaS agreements anchoring revenue predictability for platform vendors. Pricing stratifies across premium compliance tiers, standard unified communications bundles, and economy VoIP-only configurations, with ISO 27001 certification and HIPAA attestation commanding substantial premiums. Cost compression in mid-market segments intensifies as channel partners disintermediate traditional managed service markups. SMB buyers exhibit highest price sensitivity, while financial services firms accepting private cloud deployments demonstrate lowest elasticity due to regulatory entrenchment.
Supply Chain Analysis
Certified VoIP engineer availability acts as a chokepoint constraining implementation velocity for complex multi-tenant configurations across the United States, Germany, and United Kingdom. Platform infrastructure draws from hyperscale data center providers, specialized session border controller manufacturers, and natural language processing API vendors. Single-source vulnerability in AI model supply creates concentration risk as conversational intelligence becomes table stakes. Distribution runs through channel partner networks repositioning around integration services rather than hardware resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud PBX market structure favors incumbents through regulatory entrenchment, where HIPAA, GDPR, and FedRAMP certifications create switching costs that compound over multi-year contract renewals.
For Market Incumbents: Fortify competitive moats by deepening API-first programmability investments and acquiring conversational AI specialists before capability scarcity escalates. Channel partner density in mid-market segments represents a defensible lever against emerging platform entrants. Prioritize backward integration into session border controller technology to capture hybrid cloud margin pools.
For New Entrants and Emerging Players: Anchor in rural broadband expansion zones where FCC deployment mandates outpace incumbent service coverage, creating white-space in previously copper-constrained territories. Developer-centric vertical SaaS embedding offers the most penetrable entry path against unified communications bundlers. Lead with consumption-priced offerings to bypass enterprise procurement committee inertia.
For Investors and Strategic Acquirers: Capital is best deployed toward API-first programmable voice specialists with established carrier interconnection agreements and embedded communications revenue streams. Long-term viability hinges on AI competency integration rather than connectivity quality differentiation. Watch STIR/SHAKEN compliance investment burdens as consolidation trigger for smaller competitive local exchange carriers lacking certificate infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Capability Acquisition | Conversational AI integration collapses distinction between telephony infrastructure and customer experience software layers. |
| Hybrid Cloud Architecture Development | Financial services demand for on-premise session border controllers unlocks untapped margin pools in regulated verticals. |
| Channel Partner Ecosystem Expansion | Mid-market enterprise consolidation onto unified platforms concentrates demand through integration-specialized intermediaries. |
| API-First Platform Integration | Developer-centric embedding within vertical SaaS applications opens indirect revenue streams beyond direct enterprise sales. |
| Regulatory Certification Investment | FedRAMP, HIPAA, and ISO 27001 attestations filter vendor eligibility for government and healthcare procurement vehicles. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FCC deployment filings, carrier interconnection agreements, and hyperscaler infrastructure disclosures. Interviews with cloud platform engineering directors, channel partner program managers, healthcare IT procurement officers, and financial services compliance officers inform demand-side validation. SEC 10-K filings, TRAI regulatory notices, and EMA data residency guidance provide supply-side triangulation against bottom-up deployment estimates.
Segmentation dimensions modeled span deployment architecture, service bundling configuration, organization size tier, and vertical regulatory intensity across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves calibrated against rural broadband penetration rates and legacy TDM replacement cycles. Forecast inputs incorporate SIP trunking standardization velocity and AI feature penetration assumptions without year-specific anchoring.
Material uncertainties — rural fiber overbuild timing, algorithmic accountability rule emergence, and carrier consolidation patterns — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and interconnection cost trajectories. Practitioners should keep alternative scenarios live as FCC mandate implementation pace and GDPR enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Egypt Telecom Tower Market
Telecommunications
5G MVNO Market
Telecommunications
Indonesia Volte Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
Bahrain Telecom Market
Telecommunications
Finland Telecom Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Voip Phone Market
Telecommunications
Turkey Telecom Market
Telecommunications
Spain ICT Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
Transport Stream Switching Market
Telecommunications
Colombia Telecom Market