
 France Telecom Market | 2026-2036
France Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
France Telecom Market Analysis
Enterprise buyer concentration is shifting toward integrated cloud-communications bundles as midsize firms consolidate vendor relationships. Orange S.A. anchors its position through nationwide fiber backbone ownership. Bouygues Telecom differentiates via aggressive pricing in the residential mobile segment. SFR (Altice France) competes through media-content bundling that extends average revenue per user.
France Telecom encompasses fixed-line, mobile, and data services delivered over terrestrial and wireless infrastructure, with fiber optics achieving symmetrical 1 Gbps throughput in urban deployments and 5G NR operating in 3.5 GHz mid-band spectrum for low-latency enterprise applications. The technology dimension shows fiber optics commanding the largest capital commitment while 5G network slicing creates new margin pools for enterprise verticals. Subscription pricing dominates revenue structure, though pay-as-you-go models gain traction among SMBs seeking operational flexibility.
ARCEP imposes wholesale access obligations on incumbent infrastructure, while France's national cybersecurity agency ANSSI mandates encryption standards for critical communication networks. The EU AI Act and GDPR frameworks shape data-processing requirements for cloud-hosted telecom services. Stakeholders must monitor spectrum auction timing and fiber co-investment rules to calibrate infrastructure deployment priorities.
Market Dynamics
ARCEP's infrastructure-sharing mandates are redistributing capital efficiency across the French telecom landscape by forcing incumbent fiber owners to open networks to wholesale competitors, compressing proprietary advantage timelines and accelerating competitive parity in dense urban corridors.
Growth Catalysts
- Fiber co-investment frameworks:ARCEP's regulatory mechanisms lower barrier-to-entry for regional operators seeking Île-de-France backbone access, expanding serviceable addressable market for alternative providers without full capex burden.
- Enterprise cloud migration:Midsize French firms consolidating vendor relationships are pulling integrated cloud-communications bundles into core procurement, lifting ARPU for operators with vertical software capabilities.
- 5G network slicing:Low-latency enterprise applications in manufacturing and logistics are creating margin pools distinct from commoditized consumer mobile, rewarding operators with industrial vertical expertise.
Market Restraints
- Spectrum auction timing uncertainty:ARCEP's irregular release of 26 GHz and other mid-band frequencies forces multi-year capital planning blindspots, stranding deployment commitments.
- Fiber deployment cost concentration:Civil works and right-of-way negotiations in dense Parisian arrondissements consume disproportionate project budgets, limiting rural extension economics.
- Wholesale margin compression:Mandatory access pricing floors set by the national regulator constrain infrastructure owners from capturing full value of sunk fiber investments.
Strategic Opportunities
- Network-as-a-Service models:Pay-as-you-go connectivity frameworks are gaining traction among French SMBs seeking operational flexibility without long-term subscription lock-in.
- Critical infrastructure cybersecurity:ANSSI encryption mandates for communication networks create certified service tiers that command pricing premiums from defense and energy verticals.
- Media-content bundling:SFR's proven ARPU extension through content integration demonstrates replicable playbook for operators with studio or streaming partnerships.
Industry Challenges
- Legacy PSTN interconnection:Maintaining circuit-switched compatibility during all-IP transition strains engineering resources and extends service migration timelines for rural subscriber bases.
- GDPR-compliant data localization:Cloud-hosted telecom services face architectural complexity satisfying French and EU data-processing requirements across multi-tenant infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Telecom Market |
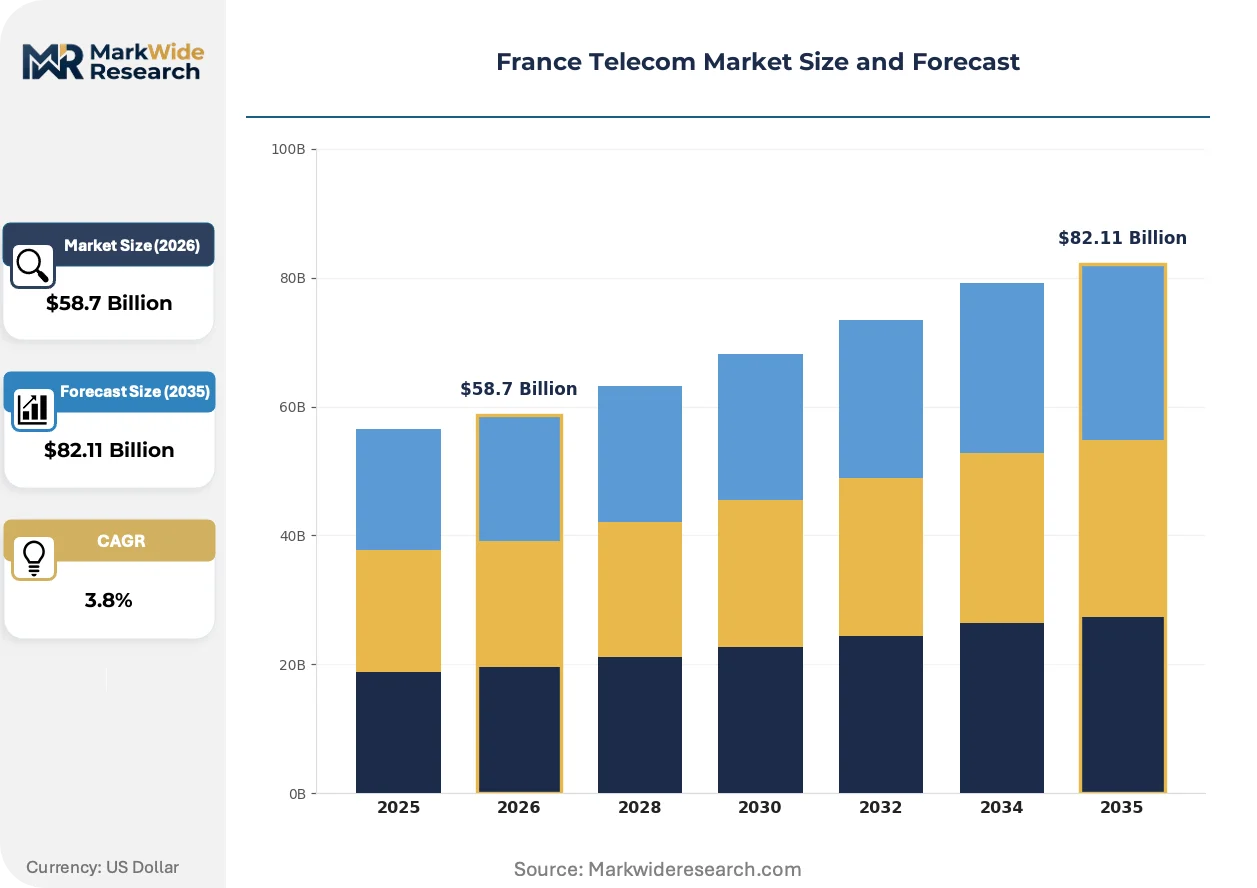
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $82.11 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Broadband, VoIP, Cloud Services Customer Type: Residential, SMBs, Enterprises, Public Sector Technology: 5G, Fiber Optics, LTE, Satellite Pricing Model: Subscription, Pay-As-You-Go, Bundled, Prepaid |
| Companies Covered | Free Mobile (Iliad), Weaccess Group, Orange S.A., Sequans Communications, La Poste Telecom, SFR (Altice France), BD Multimedia SA, Revox, Bouygues Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Telecom Market Emerging Trajectories
Software-defined networking principles are penetrating French telecom infrastructure, collapsing hardware dependency and enabling programmable service delivery that responds to enterprise demand fluctuations in real-time.
Open RAN architectures are converging with containerized network functions to displace proprietary baseband hardware. Bouygues Telecom and regional challengers are piloting multi-vendor radio access networks in secondary cities, compressing equipment supplier concentration and accelerating feature deployment cycles previously gated by single-vendor roadmaps.
The EU AI Act and GDPR frameworks are reshaping data-processing architectures for cloud-hosted telecom services. ANSSI mandates encryption standards for critical communication networks, forcing operators to segment infrastructure between general enterprise and certified national security tiers. Defense and energy verticals are responding by procuring only ANSSI-certified service tiers, bifurcating pricing structures.
Enterprise buyer concentration toward integrated cloud-communications bundles is displacing point-solution procurement. French midsize firms are consolidating vendor relationships under single-platform contracts that bundle fixed-line, mobile, and collaboration software. This pattern is most visible in the Île-de-France manufacturing corridor, where procurement teams prioritize operational simplicity over best-of-breed feature differentiation.
France Telecom Market Segmentation
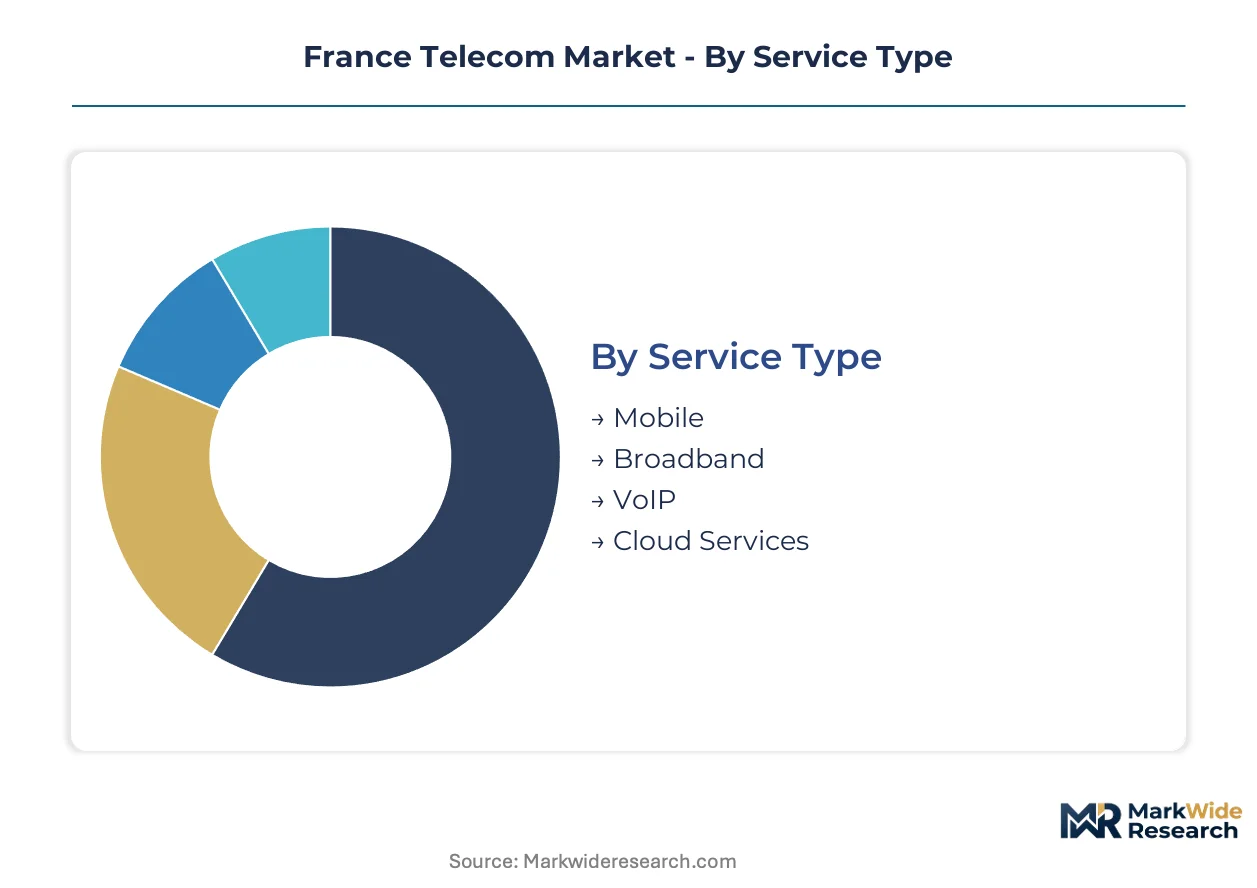
Segmentation in the France Telecom Market reveals how ARCEP's infrastructure-sharing mandates redistribute capital across service tiers and customer categories. Distinct technology and pricing boundaries determine competitive positioning for operators navigating wholesale access obligations.
Service Type:
Supply concentration in fiber backbones and 5G spectrum holdings shapes competitive intensity across service categories, with infrastructure ownership determining margin capture.
- Mobile:5G NR deployments in 3.5 GHz mid-band spectrum deliver low-latency connectivity for enterprise applications. Manufacturing and logistics verticals in the Île-de-France corridor are pulling dedicated network slices, creating margin pools beyond commoditized consumer plans.
- Broadband:Fiber-to-the-home infrastructure achieves symmetrical 1 Gbps throughput in urban deployments. ARCEP's wholesale access mandates compress proprietary advantage timelines for incumbent fiber owners in dense Parisian arrondissements.
- VoIP:All-IP transition services replace legacy PSTN circuits, straining engineering resources during interconnection maintenance.
- Cloud Services:Integrated cloud-communications bundles consolidate vendor relationships for midsize French firms seeking operational simplicity.
Broadband absorbs the bulk of installed capacity; Cloud Services is expanding most quickly.
Customer Type:
Enterprise procurement patterns concentrate demand toward integrated platforms, while residential segments fragment across price-sensitive and premium tiers.
- Enterprises:Consolidated vendor relationships under single-platform contracts bundle fixed-line, mobile, and collaboration software. Procurement teams in the Île-de-France manufacturing corridor prioritize operational simplicity over best-of-breed differentiation.
- SMBs:Pay-as-you-go connectivity frameworks gain traction among French small and midsize businesses seeking flexibility without long-term subscription lock-in.
- Residential:Aggressive pricing in mobile segments drives volume, with media-content bundling extending average revenue per user.
- Public Sector:ANSSI encryption mandates for critical communication networks create certified service tiers commanding pricing premiums from defense and energy verticals.
Enterprises absorb the bulk of installed capacity; SMBs are gaining share fastest.
Technology:
Capital deployment intensity varies sharply by infrastructure generation, with fiber and 5G commanding disproportionate project budgets against legacy platforms.
- Fiber Optics:Civil works and right-of-way negotiations in dense urban corridors consume disproportionate budgets, limiting rural extension economics despite symmetrical throughput advantages.
- 5G:Network slicing capabilities enable low-latency enterprise applications distinct from consumer mobile, rewarding operators with industrial vertical expertise in manufacturing and logistics.
- LTE:Remains the coverage backbone for rural and secondary city deployments where 5G capital intensity proves uneconomical.
- Satellite:Addresses connectivity gaps in remote geographies where terrestrial infrastructure deployment faces prohibitive civil works costs.
Fiber Optics absorbs the bulk of installed capacity; 5G shows the steepest expansion trajectory.
Pricing Model:
Subscription lock-in faces displacement from flexible consumption frameworks as SMB procurement teams prioritize operational adaptability.
- Subscription:Dominant revenue structure across residential and enterprise segments, though long-term contracts face pressure from pay-as-you-go alternatives.
- Pay-As-You-Go:Gaining traction among French SMBs seeking operational flexibility without capital commitment to multi-year service agreements.
- Bundled:Media-content and multi-service integration extends customer lifetime value, with SFR's playbook demonstrating ARPU extension through studio partnerships.
- Prepaid:Concentrated in price-sensitive residential mobile segments with minimal switching costs and high churn exposure.
Subscription absorbs the bulk of installed capacity; Pay-As-You-Go is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper wire and optical fiber manufacturing clusters in the Île-de-France region anchor French telecom infrastructure deployment. Dense urban civil works demand concentrates capital allocation in Parisian arrondissements while ARCEP regulatory frameworks reshape competitive access across metropolitan zones.
Île-de-France
Enterprise cloud-communications bundles concentrate procurement from midsize manufacturing firms in the Paris-Saclay corridor. ARCEP's infrastructure-sharing mandates force incumbent fiber owners to open backbone access to wholesale competitors. The La Défense financial district drives low-latency connectivity requirements for trading infrastructure.
Auvergne-Rhône-Alpes
Industrial automation in Lyon and Grenoble manufacturing zones pulls dedicated 5G network slices for logistics applications. ANSSI encryption standards apply to critical communication networks serving defense suppliers in the Isère valley. Saint-Étienne's precision engineering cluster contracts certified secure connectivity tiers.
Provence-Alpes-Côte d'Azur
Maritime logistics operators in Marseille-Fos port complex demand resilient mobile broadband for container tracking systems. The regional prefecture enforces GDPR-compliant data localization for cloud-hosted services processing customs documentation. Sophia Antipolis technology park hosts pilot Open RAN deployments by alternative operators.
Hauts-de-France
Agricultural cooperatives in the Picardy grain belt adopt satellite-backup connectivity where fiber extension proves uneconomical. The national rural digital inclusion program subsidizes civil works costs for last-mile deployment. Lille's logistics hub concentrates pay-as-you-go connectivity demand from third-party warehouse operators.
Nouvelle-Aquitaine
Aerospace subcontractors in Bordeaux-Mérignac require ANSSI-certified service tiers for defense contract compliance. The regional fiber co-investment framework lowers barrier-to-entry for alternative providers seeking backbone access. Bayonne's cross-border logistics corridor drives roaming-optimized mobile procurement from Basque Country enterprises.
France Telecom Market Vendor Landscape
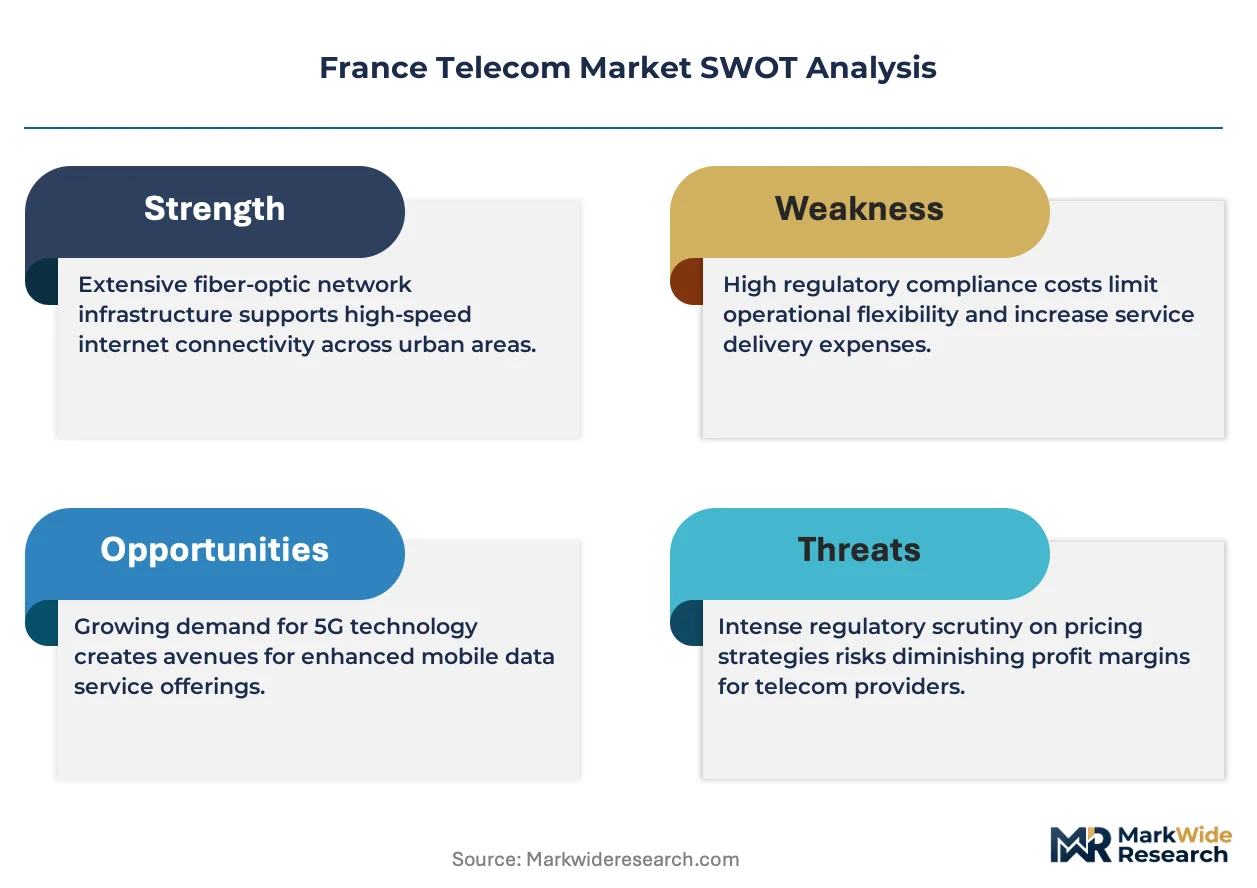
Established producers occupy the standard tier; emerging entrants pursue specialized vertical applications and regional wholesale access. The French telecom market presents a three-tier structure anchored by infrastructure-owning incumbents, mobile-focused challengers, and niche enterprise specialists. Strategic archetypes include nationwide fiber backbone operators, aggressive residential pricers, and vertical-software integrators. Dominant competitive moves center on media-content bundling for ARPU extension and fiber co-investment partnerships to share civil works burdens.
Within the infrastructure-owner tier, Orange S.A. and SFR (Altice France) exemplify divergent bundling strategies, while Bouygues Telecom occupies a position as the aggressive pricing challenger in residential mobile. Free Mobile (Iliad) represents the disruptive low-cost archetype that forced structural repricing across consumer segments. Sequans Communications sits within the specialized equipment supplier category serving industrial IoT connectivity requirements.
| Leading Market Players |
|---|
| Free Mobile (Iliad) |
| Weaccess Group |
| Orange S.A. |
| Sequans Communications |
| La Poste Telecom |
| SFR (Altice France) |
| BD Multimedia SA |
| Revox |
| Bouygues Telecom |
| Others |
Supply Flow & Price Mechanics
Civil works costs in dense Parisian arrondissements cascade through wholesale access pricing tiers, compressing margins for infrastructure owners while ARCEP-mandated floor prices prevent full value recovery from sunk fiber investments.
Pricing Analysis
Warranty and service-level guarantees separate premium enterprise tiers from stripped-down residential offerings in the French telecom landscape. Three-tier pricing structure across premium, standard, and economy levels reflects ANSSI certification status and fiber proximity to enterprise demand clusters. Cost compression in residential mobile stems from Free Mobile's disruptive low-cost positioning. SMB procurement teams exhibit highest price sensitivity, while defense and energy verticals accept certified service premiums.
Supply Chain Analysis
Reverse-logistics flows for decommissioned baseband hardware and fiber optic cable recovery remain underdeveloped across French operator procurement frameworks. Equipment sourcing draws from China, Finland, and Sweden for radio access network components and core switching infrastructure. Optical fiber production concentrates in Germany and the Netherlands. Single-source vulnerability in 5G baseband chipsets creates procurement risk. Distribution runs through direct operator procurement with limited distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiber deployment capacity constraints in Île-de-France civil works prop pricing power for incumbent infrastructure owners, creating supply-scarcity rents that alternative operators must navigate through co-investment frameworks.
For Market Incumbents: To counter wholesale margin compression from ARCEP access mandates, Orange S.A. and SFR should deepen fiber co-investment partnerships to distribute civil works burdens while securing exclusive enterprise service tiers through ANSSI certification investment.
For New Entrants and Emerging Players: Open RAN multi-vendor architectures offer entry pathways into secondary French cities where incumbent equipment lock-in proves weakest. Regional operators should target Auvergne-Rhône-Alpes manufacturing zones with 5G network slicing for industrial automation, leveraging pay-as-you-go commercial models to bypass subscription-heavy procurement committees.
For Investors and Strategic Acquirers: ARCEP spectrum auction announcements are the leading indicator that capital deployment windows are opening for infrastructure-light challengers. Long-term viability favors operators with vertical software capabilities in enterprise cloud-communications integration. Acquisition targets should display industrial IoT expertise and established fiber co-investment relationships. Monitor ANSSI certification queue lengths for demand signal inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Co-Investment Partnership | ARCEP frameworks enable alternative operators to access incumbent backbone without full capex burden. |
| ANSSI Certification Investment | Defense and energy verticals procure only certified tiers, bifurcating pricing structures. |
| Open RAN Multi-Vendor Deployment | Bouygues Telecom pilots displace proprietary hardware and compress supplier concentration. |
| 5G Network Slicing for Manufacturing | Industrial automation in Île-de-France corridor creates margin pools beyond consumer mobile. |
| Cloud-Communications Bundle Integration | Midsize firms consolidate vendor relationships under single-platform contracts. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this France Telecom Market analysis. Primary interviews with network engineering directors, ARCEP policy officers, enterprise procurement managers, and fiber infrastructure planners combined with ARCEP wholesale pricing decisions, ANSSI certification databases, and operator capex disclosures. Bottom-up service adoption modeling and top-down infrastructure deployment tracking provided triangulation.
Data-stream reconciliation across mobile subscriber metrics, fiber port activation rates, and enterprise cloud service attach rates shaped the analytical framework. Segmentation dimensions modeled include service type, customer category, technology generation, and pricing model across the projection horizon. CAGRs derived from infrastructure deployment curves and enterprise migration patterns. Forecast inputs incorporated spectrum auction timing scenarios and fiber co-investment participation rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under spectrum auction delays or civil works cost inflation. Forecasts reflect documented assumptions regarding ARCEP regulatory continuity and enterprise cloud migration velocity. Practitioners should monitor ARCEP wholesale pricing reviews and ANSSI certification backlog lengths for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Smart SIM Market
Telecommunications
Medical 5G Market
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
Cellular Modem Market
Telecommunications
Angola Telecom Market
Telecommunications
5G System Integration Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Brazil Telecom Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
Global Premium A2P and P2A Messaging Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Nigeria Satellite Communications Market