
 Voice Over Internet Protocol (Voip) Market | 2026-2036
Voice Over Internet Protocol (Voip) Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Over Internet Protocol (Voip) Market Analysis
Healthcare and education end-use verticals is rebalancing demand away from legacy telephony toward integrated collaboration stacks. Microsoft Corporation leverages its Teams ecosystem to anchor enterprise-grade unified communications across hybrid work environments. Cisco Systems, Inc. sustains dominance in on-premises infrastructure through deep channel control and certified hardware integration. Zoom Video Communications, Inc. specializes in video-first collaboration tools that extend its footprint into contact center adjacencies.
Voice Over Internet Protocol denotes packet-switched voice transmission using session initiation protocol signaling and real-time transport protocol media delivery over IP networks, typically operating at latency thresholds below 150 milliseconds for acceptable conversational quality. The technology replaces circuit-switched public telephone networks with software-defined routing that enables multimedia session blending. Cloud-based deployment now leads segment momentum as enterprises abandon capital-intensive PBX hardware for subscription models with automatic feature updates. Softphones capture the fastest expansion trajectory by eliminating dedicated endpoint costs and enabling bring-your-own-device policies. Session border controllers concentrate margin pools through security enforcement and interconnection complexity that carriers cannot easily commoditize.
The FCC mandates E911 location accuracy and STIR/SHAKEN caller authentication frameworks that shape product certification requirements for US market access. Europe's GDPR and the EU AI Act impose data residency and automated decision-making constraints on cloud-hosted voice analytics platforms. Stakeholders must monitor how emerging quantum-resistant encryption standards and sovereignty-driven data localization mandates will reshape vendor qualification criteria and procurement specifications across jurisdictions.
Market Dynamics
Cloud-native Session Initiation Protocol architectures are compressing deployment cycles from months to days, forcing infrastructure vendors to abandon perpetual licensing for consumption-based pricing models that align with enterprise IT budget velocity.
Growth Catalysts
- STIR/SHAKEN Mandates:The FCC's caller authentication framework compels carriers to upgrade signaling infrastructure, creating mandatory refresh cycles across US voice networks.
- Telemedicine Workflows:Healthcare providers in India deploy cloud PBX systems to route patient consultations through encrypted SIP trunks compliant with clinical data standards.
- Softphone Proliferation:Bring-your-own-device policies eliminate endpoint procurement, accelerating seat activation velocity for distributed workforces.
Market Restraints
- Copper Retirement Costs:Incumbent carriers face stranded asset write-downs as PSTN decommissioning timelines compress maintenance revenue recognition.
- Latency Sensitivity:Real-time transport protocol jitter above 150 milliseconds degrades conversational quality, constraining satellite-dependent rural deployments.
- Session Border Controller Concentration:Three vendors control interconnection security enforcement, extracting premium pricing for transcoding and encryption functions.
Strategic Opportunities
- Contact Center AI Convergence:Natural language processing integration with SIP trunking creates voicebot orchestration platforms for automated customer service workflows.
- GDPR-Compliant Analytics:European enterprises demand on-premise voice data processing to satisfy automated decision-making constraints under the EU AI Act.
- Sub-Saharan Expansion:Mobile network operators in Nigeria and Kenya bypass fixed-line infrastructure through cellular VoIP overlays.
Industry Challenges
- Legacy PBX Integration:Enterprises maintaining hybrid TDM-IP environments face signaling protocol mismatches during phased migration.
- E911 Location Accuracy:Remote workers trigger dispatch errors when dynamic IP addressing obscures physical endpoint coordinates.
- Quantum-Resistant Certification:NIST post-quantum cryptography standards demand firmware rewrites for encrypted voice hardware before 2030 deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Over Internet Protocol (Voip) Market |
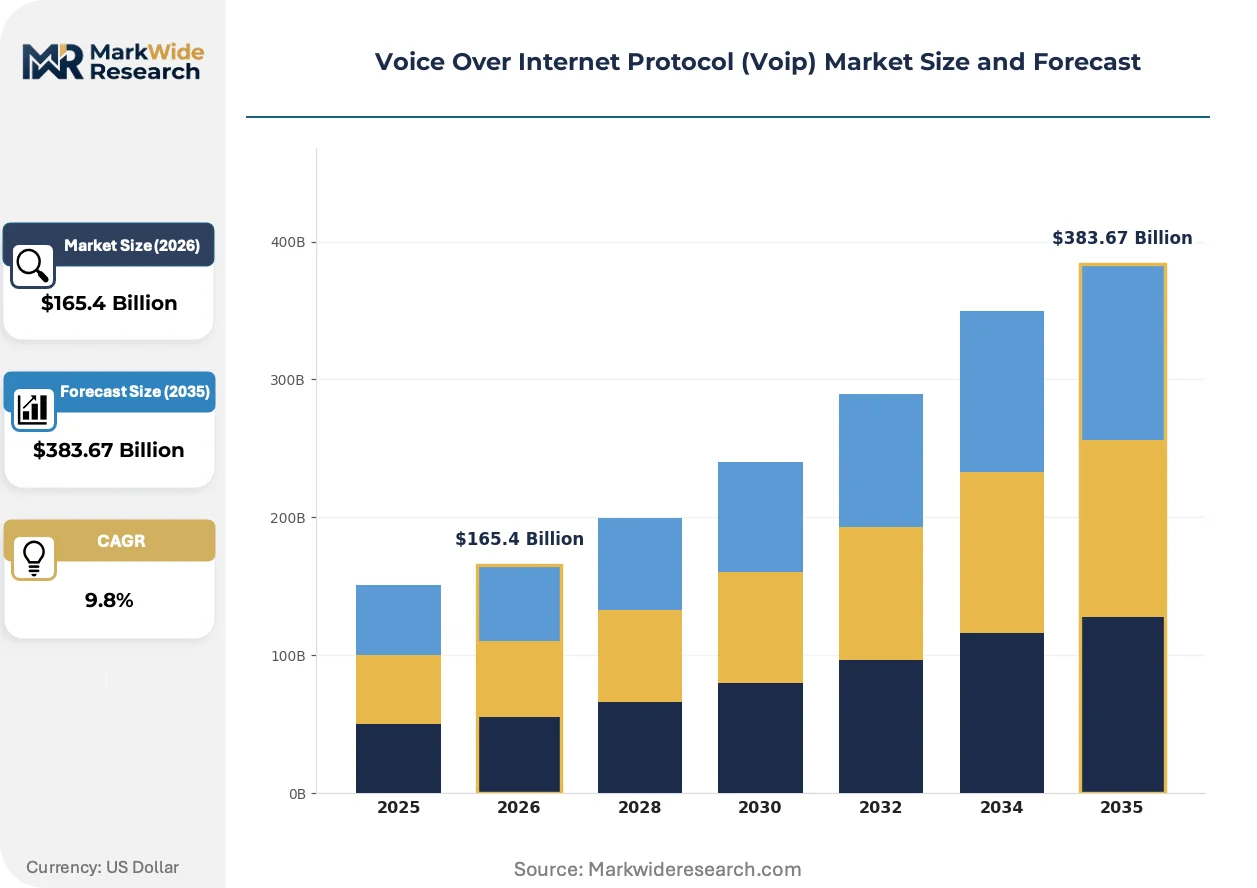
| Market Size in 2026 | $165.4 Billion |
| Market Size in 2035 | $383.67 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IP Desk Phones, Softphones, VoIP Gateways, Analog Telephone Adapters, Session Border Controllers Deployment: On-Premises, Cloud-Based, Hybrid, Hosted, Managed Application: Unified Communications, Contact Centers, Video Conferencing, Telephony, Collaboration Tools End User: Small & Medium Enterprises, Large Corporations, Call Centers, Government Agencies, Educational Institutions |
| Companies Covered | RingCentral, Inc., Microsoft Corporation, Cisco Systems, Inc., Nextiva, Vonage Holdings Corp., 8x8 Inc., Zoom Video Communications, Inc., Dialpad, Inc., Ooma, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Over Internet Protocol (Voip) Market Emerging Trajectories
Artificial intelligence is embedding into voice infrastructure at the packet layer, transforming static routing tables into self-optimizing networks that anticipate congestion before quality degradation occurs.
WebRTC is automating browser-based voice activation without plugin dependencies. Contact center operators in Germany adopt this stack to eliminate client-side software distribution. The technology is automating agent onboarding by collapsing provisioning from IT ticket queues to single-click URL distribution.
The EU AI Act imposes algorithmic transparency requirements on cloud-hosted transcription services. Vendors must document training data provenance for voice analytics sold into European healthcare and financial services. French and Dutch regulators are already rejecting certification applications lacking bias audit trails.
Consumption-based pricing is displacing per-seat licensing across mid-market enterprises. IT procurement teams in Brazil and Mexico negotiate commit-based contracts with burst elasticity rather than fixed capacity planning. This shift compresses vendor revenue recognition cycles while accelerating customer switching between competing platforms.
Voice Over Internet Protocol (Voip) Market Segmentation
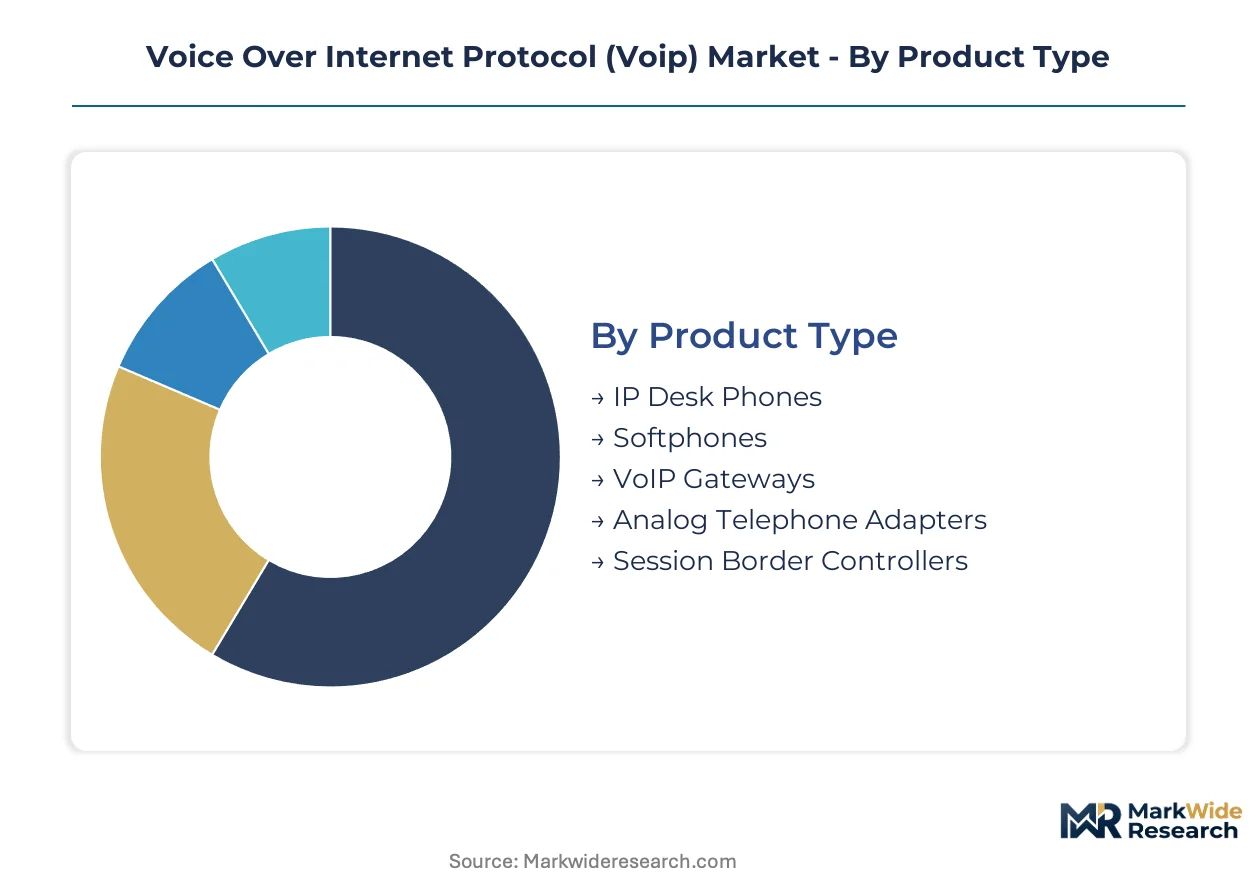
VoIP market segmentation reveals divergent growth trajectories between capital-intensive hardware endpoints and software-defined consumption models. Procurement patterns split sharply across enterprise scale, with cloud-native architectures capturing mid-market velocity while regulated verticals sustain on-premises investment.
Product Type:
Volume concentration sits with endpoint hardware, yet margin pools concentrate in interconnection security infrastructure.
- IP Desk Phones:Purpose-built SIP endpoints with Power-over-Ethernet provisioning and HD voice codecs. Manufacturing clusters in Taiwan and Shenzhen supply enterprise refresh cycles, though seat activation velocity lags softphone alternatives.
- Softphones:Software-based clients running on general-purpose computing devices, eliminating dedicated endpoint procurement entirely. Distributed workforces in India and Brazil activate these fastest, driven by bring-your-own-device policies and zero-touch provisioning.
- VoIP Gateways:Protocol translation bridges enabling TDM-to-IP migration for legacy PBX preservation.
- Analog Telephone Adapters:Cost-preservation devices extending POTS instrument lifespan during phased infrastructure transitions.
- Session Border Controllers:Security enforcement nodes managing signaling normalization and encryption policy across network boundaries.
Today's leader: Softphones. Tomorrow's challenger: Session Border Controllers.
Deployment:
Cost tier stratification separates capital-intensive ownership from operational expenditure flexibility.
- Cloud-Based:Multi-tenant subscription platforms delivering automatic feature updates without on-site maintenance. Healthcare providers in Germany and France select these to satisfy GDPR data residency through EU-zone hosting.
- On-Premises:Customer-managed infrastructure with perpetual licensing and full control over upgrade timing. Financial institutions in Switzerland and government agencies in Saudi Arabia maintain these for compliance with sovereign data requirements.
- Hybrid:Split architectures preserving legacy PBX investment while selectively routing traffic to cloud trunks.
- Hosted:Single-tenant dedicated instances managed by service providers on customer-specified infrastructure.
- Managed:Fully outsourced operational responsibility including monitoring, patching, and capacity planning.
Cloud-Based deployment captures the steepest expansion trajectory among mid-market enterprises abandoning hardware ownership.
Application:
Customer type determines feature depth requirements, with contact center operators demanding the most sophisticated orchestration capabilities.
- Contact Centers:Omnichannel routing platforms integrating voice with digital messaging and CRM data. Indian BPO operators and Philippine service providers expand these aggressively to support transnational client contracts.
- Unified Communications:Integrated messaging, voice, and video stacks replacing discrete productivity tools. Hybrid work policies in the United States and United Kingdom sustain enterprise investment here.
- Video Conferencing:Real-time multimedia sessions with screen sharing and recording functionality.
- Telephony:Basic voice replacement for PSTN migration without collaboration feature bundling.
- Collaboration Tools:Persistent workspaces combining synchronous and asynchronous communication modalities.
Contact Centers currently command premium pricing. Unified Communications is gaining share fastest as vendor consolidation accelerates.
End User:
Maturity gradients separate price-sensitive volume buyers from compliance-constrained institutional purchasers.
- Small & Medium Enterprises:Organizations with limited IT staff favoring zero-touch deployment and predictable monthly costs. India's SME sector drives concentrated demand for cloud PBX migration through TRAI-enabled competitive carrier access.
- Government Agencies:Sovereign entities with mandatory encryption and domestic data routing requirements. US federal deployments follow FedRAMP authorization pathways, while UAE and Saudi entities prioritize in-country hosting.
- Large Corporations:Complex multi-site environments with heterogeneous legacy infrastructure.
- Call Centers:High-density voice operations with workforce optimization and quality monitoring needs.
- Educational Institutions:Budget-constrained environments with seasonal usage patterns and remote learning requirements.
Small & Medium Enterprises anchor current volume. Government Agencies represent the most defensible margin segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting cloud infrastructure investment toward jurisdictions with clearer data localization frameworks and lighter compliance burdens. Carriers and platform providers now site primary hosting facilities in countries offering predictable certification pathways rather than lowest nominal operating costs.
United States
Enterprise hybrid work policies sustain demand for unified communications platforms with embedded compliance tools. The FCC enforces STIR/SHAKEN caller authentication and E911 location accuracy mandates that shape product certification requirements. Seattle and San Francisco Bay Area clusters host the dominant cloud-native platform engineering centers.
Germany
GDPR-constrained healthcare and financial services verticals favor on-premise voice analytics with documented bias audit trails. The EU AI Act imposes algorithmic transparency requirements on transcription services sold into regulated industries. Frankfurt and Munich industrial corridors concentrate contact center operator demand for sovereign-hosted collaboration stacks.
India
Small and medium enterprises accelerate cloud PBX migration through TRAI-enabled competitive carrier access and zero-touch provisioning models. The country's national telecommunications regulator mandates quality-of-service benchmarks for IP-based voice services. Bangalore and Hyderabad technology clusters drive softphone adoption among distributed software development workforces.
United Kingdom
Post-Brexit data adequacy negotiations push financial institutions toward hybrid deployment models with UK-specific hosting. The national data protection authority enforces automated decision-making constraints on voice analytics platforms. London's fintech corridor sustains premium pricing for compliance-certified unified communications.
Brazil
Mid-market enterprises negotiate commit-based contracts with burst elasticity rather than fixed capacity planning. The country's national telecommunications agency oversees interconnection frameworks for VoIP services competing with legacy PSTN operators. São Paulo's business services sector anchors Latin American demand for Portuguese-language contact center platforms.
Voice Over Internet Protocol (Voip) Market Vendor Landscape
Strategic partnership formation dominates the current landscape as infrastructure vendors align with cloud hyperscalers to compress deployment cycles. The vendor base clusters into three tiers: full-stack platform providers with embedded productivity software, specialized session border controller manufacturers extracting premium pricing for security enforcement, and regional service providers capturing mid-market share through localized support. Two competitive moves define current positioning: consumption-based pricing model adoption to align with enterprise IT budget velocity, and contact center AI convergence through natural language processing integration with SIP trunking.
Within the full-stack platform tier, Microsoft Corporation and Cisco Systems, Inc. occupy positions representing divergent deployment philosophies—cloud-native subscription versus on-premises perpetual licensing. Zoom Video Communications, Inc. exemplifies the video-first archetype extending into adjacent contact center markets. These three entities anchor the competitive structure without exhausting its complexity.
| Leading Market Players |
|---|
| RingCentral, Inc. |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Nextiva |
| Vonage Holdings Corp. |
| 8x8 Inc. |
| Zoom Video Communications, Inc. |
| Dialpad, Inc. |
| Ooma, Inc. |
| Others |
Supply Flow & Price Mechanics
Semiconductor component costs for session border controllers and VoIP gateways flow from Taiwanese foundries through Shenzhen assembly clusters into three-tier pricing structures across premium, standard, and economy levels, with subscription-based cloud platforms compressing hardware margin pools as enterprises abandon perpetual licensing.
Pricing Analysis
Distributor margins on IP desk phones compress as direct-to-enterprise SaaS pricing eliminates channel layers entirely. Cloud-based deployment models stratify across premium, standard, and economy tiers based on feature depth and SLA guarantees, while on-premises perpetual licenses sustain price premiums only in regulated verticals. Pricing pressure stems from softphone proliferation eliminating endpoint procurement entirely. Small and medium enterprises exhibit highest price sensitivity, driving consumption-based contract negotiation; government agencies show lowest sensitivity due to sovereign compliance mandates.
Supply Chain Analysis
SIP chipset supply rests on Taiwanese semiconductor foundries and South Korean memory producers, with final assembly concentrating in Shenzhen and Dongguan manufacturing corridors. Critical dependencies include Power-over-Ethernet controller silicon, HD voice codec modules, and encryption accelerator hardware. Single-source vulnerability concentrates in session border controller firmware providers. Distribution runs through certified channel partners for on-premises hardware, while cloud platforms deploy direct-to-customer provisioning portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between GDPR-constrained European deployments and TRAI-enabled competitive carrier access in India creates geographic cost differentials for cloud infrastructure siting and compliance certification.
For Market Incumbents: To counter softphone commoditization threatening endpoint revenue, anchor enterprise relationships through session border controller security enforcement and deepen backward integration into cloud-native SIP architecture development. Prioritize FedRAMP and EU AI Act compliance certification to defend government and healthcare verticals against emerging cloud-native challengers.
For New Entrants and Emerging Players: Launch via cellular VoIP overlay partnerships with mobile network operators in Nigeria and Kenya, bypassing fixed-line infrastructure investment entirely. Target sub-Saharan African markets where PSTN bypass creates white-space opportunity. Emphasize zero-touch provisioning and local language support to differentiate against global platform providers.
For Investors and Strategic Acquirers: Consolidation pressure builds where session border controller vendors face hyperscaler platform integration demands. Frame long-term viability around contact center AI convergence capabilities and sovereign data localization compliance. Watch for STIR/SHAKEN mandate acceleration as inflection signal for infrastructure refresh cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Contact Center AI Convergence | Natural language processing integration with SIP trunking creates voicebot orchestration platforms for automated customer service workflows in Indian BPO operations. |
| GDPR-Compliant Analytics Development | On-premise voice data processing satisfies EU AI Act automated decision-making constraints for French and Dutch healthcare transcription services. |
| Sub-Saharan Cellular VoIP Expansion | Mobile network operator partnerships in Nigeria and Kenya bypass fixed-line infrastructure through cellular overlays targeting unbanked populations. |
| Quantum-Resistant Certification Investment | NIST post-quantum cryptography firmware rewrites secure encrypted voice hardware against 2030 compliance deadlines for federal deployments. |
| Consumption-Based Pricing Transition | Commit-based contracts with burst elasticity align vendor revenue recognition with Brazilian and Mexican mid-market IT budget velocity. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with carrier network engineers, cloud platform product managers, enterprise IT procurement officers, and session border controller technical architects with secondary validation against FCC regulatory filings, TRAI quality-of-service benchmarks, EU AI Act implementation guidance, and hyperscaler capex disclosures. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against carrier revenue recognition patterns anchored value estimates.
Segment-weighting applied differential growth assumptions across cloud-based, on-premises, hybrid, hosted, and managed deployment architectures, further disaggregated by softphone versus hardware endpoint preferences and contact center versus unified communications application intensity. CAGRs derived from fitted adoption curves incorporating enterprise seat activation velocity, healthcare telemedicine workflow expansion, and government compliance-driven refresh cycles across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under quantum-resistant certification deadline acceleration or copper retirement timeline compression. Forecasts reflect assumptions about STIR/SHAKEN mandate enforcement consistency and EU AI Act bias audit trail standardization. A small set of named triggers—satellite latency mitigation breakthroughs, sovereign data localization mandate proliferation, and contact center AI orchestration platform consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Content Delivery Network (CDN) Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Service Provider Router Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
South Korea Data Center Networking Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Global Data Lakes Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Taiwan Data Center Networking Market