
 Enterprise WLAN Market | 2026-2036
Enterprise WLAN Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise WLAN Market Analysis
Managed service revenue is tilting from hardware resale toward lifecycle support contracts. Cisco Systems leverages its Meraki cloud stack to capture recurring subscription income. Huawei Technologies anchors its position through silicon-to-software vertical integration in access point design. Extreme Networks differentiates via cloud-native automation platforms that reduce on-site engineering hours.
Enterprise WLAN denotes a wireless local area network infrastructure deployed across corporate campuses, utilizing IEEE 802.11ax (Wi-Fi 6) protocols with orthogonal frequency-division multiple access to deliver gigabit throughput and sub-ten-millisecond latency for mission-critical applications. Access points dominate product-level revenue as density requirements rise in open-floor offices and warehouse robotics zones. Cloud-based networking within the technology dimension expands fastest as IT departments offload controller management to vendor-hosted platforms. Corporates and educational institutions represent the deepest end-user margin pools due to multi-thousand-node refresh cycles.
The FCC governs unlicensed spectrum allocation and power limits in the United States, while ETSI harmonizes channel plans across European member states; both frameworks directly shape access point radio configurations and regional SKU proliferation. The Wi-Fi Alliance certification program mandates interoperability testing that gates market entry for non-compliant hardware. Stakeholders must weigh private spectrum licensing against unlicensed WLAN expansion as factory automation demands deterministic wireless performance.
Market Dynamics
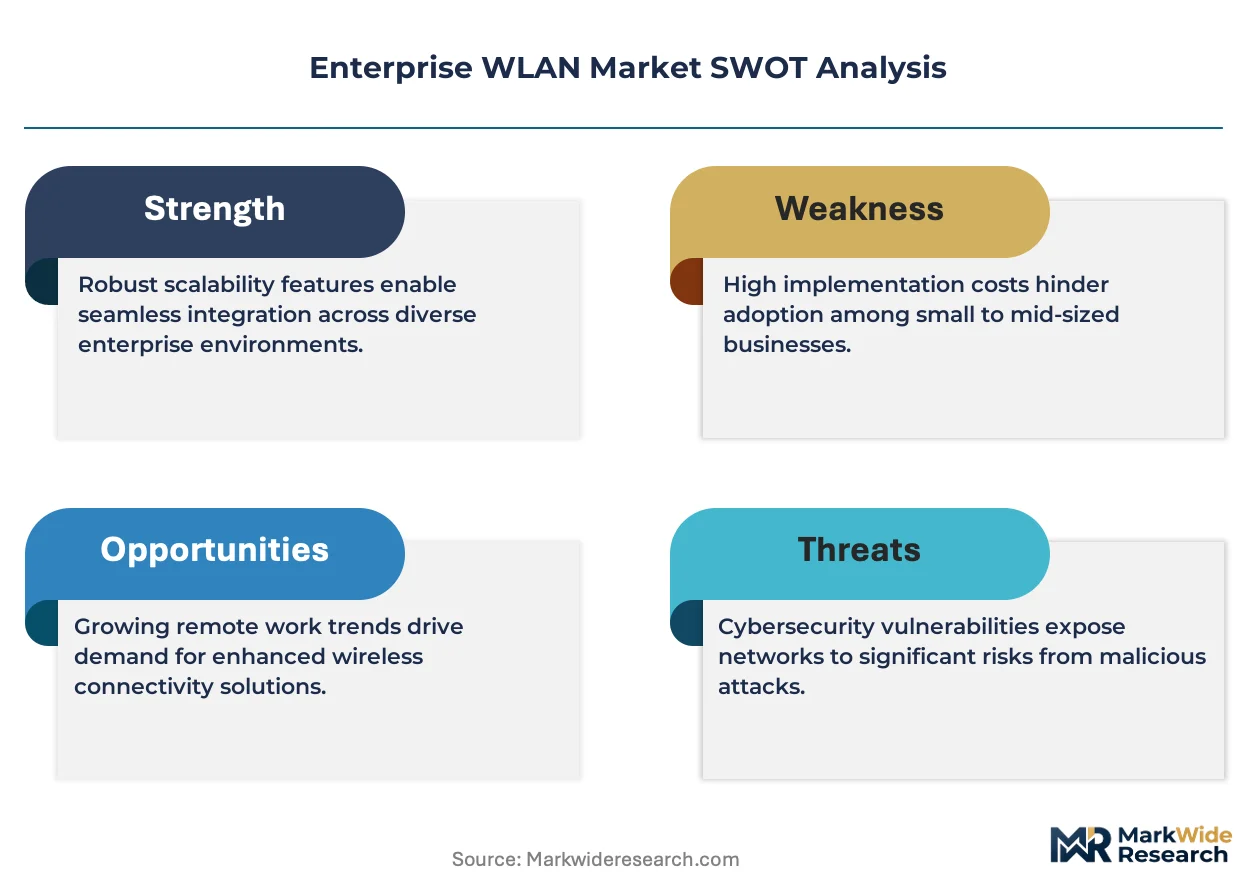
The FCC's spectrum allocation for unlicensed 6 GHz bands is compressing refresh cycles as enterprises replace aging 802.11ac infrastructure ahead of planned obsolescence. This regulatory tailwind intersects with private 5G-WLAN convergence pilots in industrial automation, creating a dual-technology procurement wave that favors vendors with unified radio platforms.
Growth Catalysts
- Healthcare infrastructure modernization:Hospital systems in the United States are retiring wired bedside telemetry in favor of wireless patient monitoring, driving dense access point deployments across clinical floors.
- ETSI harmonization:The European Telecommunications Standards Institute's unified channel plans reduce SKU complexity for multi-national campus rollouts, accelerating procurement decisions for corporates with distributed footprints.
- Wi-Fi 6E protocol expansion:Orthogonal frequency-division multiple access in the 6 GHz band delivers deterministic latency for warehouse robotics, pulling automation-grade infrastructure spend forward.
Market Restraints
- Semiconductor supply concentration:Radio frequency front-end modules depend on concentrated foundry capacity in East Asia, exposing lead times to geopolitical friction.
- Private 5G substitution threat:Factory operators in Germany are piloting licensed spectrum networks for deterministic control, splicing budget from unlicensed WLAN capex.
- Radio power limit heterogeneity:National regulators enforce divergent transmit power ceilings, fragmenting hardware designs and inflating inventory carrying costs.
Strategic Opportunities
- Private network convergence:Industrial campuses in Germany are trialing 5G-WLAN orchestration layers that unify policy management across licensed and unlicensed spectrum.
- Cloud controller offloading:IT departments are shifting controller infrastructure to vendor-hosted platforms, opening recurring revenue streams that displace one-time hardware margins.
- Educational institution refresh:Multi-thousand-node deployments across university systems present concentrated procurement windows for vendors with scalable provisioning tools.
Industry Challenges
- RF engineering talent scarcity:Dense 6 GHz deployments require specialized site-survey expertise that outstrips current certification pipeline output.
- Legacy controller integration:Hybrid cloud migrations force coexistence between on-premises and hosted management planes, complicating policy synchronization.
- Wi-Fi Alliance certification backlog:Interoperability testing queues for 6E devices extend product launch timelines, compressing vendor competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise WLAN Market |
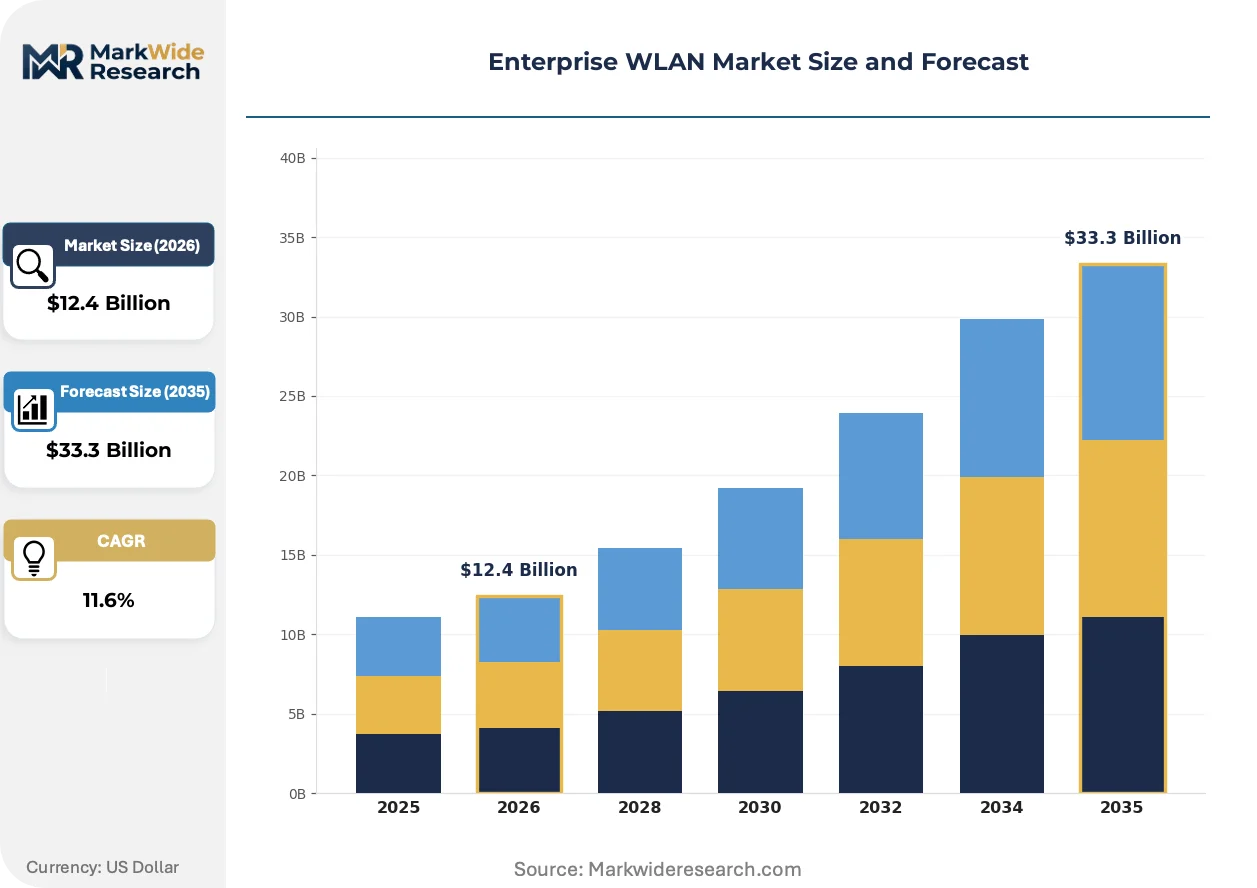
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.3 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Points, Controllers, Managed Services, Network Security Technology: Wi-Fi 6, Cloud-Based Networking, Mesh Networking, SD-WAN End User: Corporates, Educational Institutions, Healthcare Facilities, Retail Outlets Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed |
| Companies Covered | Fortinet, RUCKUS Networks, Cisco Systems, CommScope, Extreme Networks, Hewlett Packard Enterprise, Huawei Technologies, Alcatel-Lucent Enterprise, Juniper Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise WLAN Market Emerging Trajectories
Enterprise wireless infrastructure is undergoing a architectural pivot from hardware-centric deployment models to software-defined lifecycle management, with implications for vendor revenue recognition and buyer total cost of ownership calculations.
Wi-Fi 6E access point silicon is migrating from discrete radio components to system-on-chip architectures that integrate baseband processing and antenna tuning. Campus IT teams are adopting these consolidated designs to reduce on-site commissioning hours. The technology is migrating from premium-tier deployments to mid-market standard configurations, compressing hardware margin pools while expanding addressable volume.
The FCC's 6 GHz spectrum allocation order created contiguous 1,200 MHz of unlicensed bandwidth, triggering radio redesigns that exploit wider channel bonding for multi-gigabit throughput. Equipment manufacturers must now certify region-specific power profiles, fragmenting firmware development roadmaps. United States healthcare systems are responding fastest, leveraging the bandwidth infusion for uncompressed medical imaging transport.
Enterprise buyers are consolidating vendor relationships around single-stack cloud platforms that unify wired and wireless policy enforcement. Value-added resellers are losing attach-rate on professional services as automation tools reduce deployment labor. This concentration is most visible in United States education verticals, where multi-campus districts favor standardized procurement vehicles over best-of-breed component sourcing.
Enterprise WLAN Market Segmentation
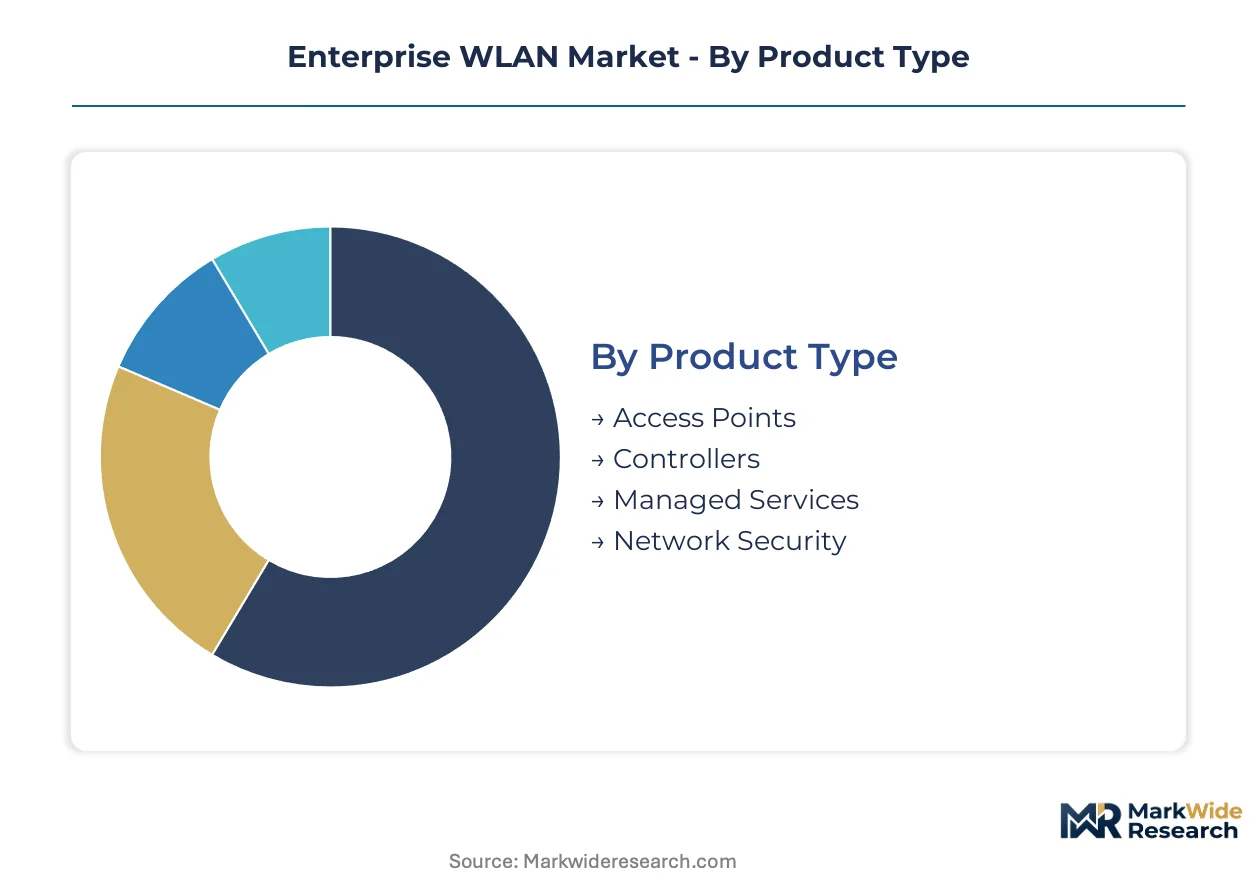
Enterprise WLAN procurement patterns diverge sharply across product architectures, technology generations, and operational models. Buyers calibrate infrastructure spend against density requirements, latency sensitivity, and IT staff capacity, creating distinct margin pools within each segment boundary.
Product Type:
Mature hardware categories coexist with emerging service wrappers as vendors pivot from transactional sales to recurring revenue architectures.
- Access Points:Radio hardware with integrated antenna arrays and baseband processing dominates capital expenditure. Hospital systems in the United States deploy dense ceiling-mounted grids to replace wired bedside telemetry, with clinical floors requiring one access point per 1,500 square feet for uninterrupted patient monitoring.
- Controllers:Centralized management appliances aggregate policy enforcement and roaming handoffs across distributed radio footprints. German industrial campuses favor controller-based architectures for deterministic latency in warehouse robotics zones, though cloud migration is compressing on-premise controller shipments.
- Managed Services:Lifecycle support contracts covering monitoring, firmware updates, and RF optimization. Enterprises with limited wireless engineering staff outsource site surveys and capacity planning.
- Network Security:Policy enforcement engines, intrusion detection, and guest access segmentation. Financial institutions mandate hardware-anchored security modules for PCI-DSS compliance.
Access Points retain volume leadership; Managed Services holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium protocol generations from legacy infrastructure and emerging architectural overlays.
- Wi-Fi 6:IEEE 802.11ax protocol with orthogonal frequency-division multiple access and target wake time for battery-constrained devices. United States healthcare systems exploit Wi-Fi 6 for uncompressed medical imaging transport, while educational institutions leverage the standard for high-density lecture hall connectivity.
- Cloud-Based Networking:Vendor-hosted controller planes with API-driven automation. Mid-market enterprises adopt these platforms to eliminate on-site controller hardware and reduce deployment engineering hours.
- Mesh Networking:Self-healing radio backhaul for rapid deployment in temporary or cable-constrained environments. Construction sites and outdoor retail extensions favor mesh for speed of activation.
- SD-WAN:Software-defined wide area networking overlays that unify wireless and wired transport policy. Distributed corporates with branch footprints deploy SD-WAN to centralize traffic steering across hybrid access circuits.
Wi-Fi 6 anchors current procurement volume; Cloud-Based Networking is gaining share fastest as IT departments offload operational burden.
End User:
Customer type determines refresh cycle length, node density tolerance, and willingness to absorb premium pricing for deterministic performance.
- Corporates:Multi-campus enterprises with standardized procurement vehicles and thousand-node refresh cycles. Financial services and technology firms drive demand for cloud-managed architectures with unified policy enforcement.
- Educational Institutions:Universities and K-12 districts with seasonal usage spikes and limited capital budgets. United States public school systems favor standardized district-wide deployments over best-of-breed component sourcing.
- Healthcare Facilities:Hospitals and outpatient clinics requiring sub-ten-millisecond latency for life-critical telemetry. The FCC's 6 GHz allocation enables these deployments by expanding unlicensed spectrum for dense radio grids.
- Retail Outlets:Brick-and-mortar chains with guest Wi-Fi mandates and point-of-sale integration requirements. Franchise operators prioritize rapid deployment tools over feature depth.
Corporates command the deepest margin pools; Healthcare Facilities exhibit the most urgent replacement timelines.
Deployment Model:
Volume concentration shifts toward operational expenditure models as buyers trade capital intensity for predictable subscription economics.
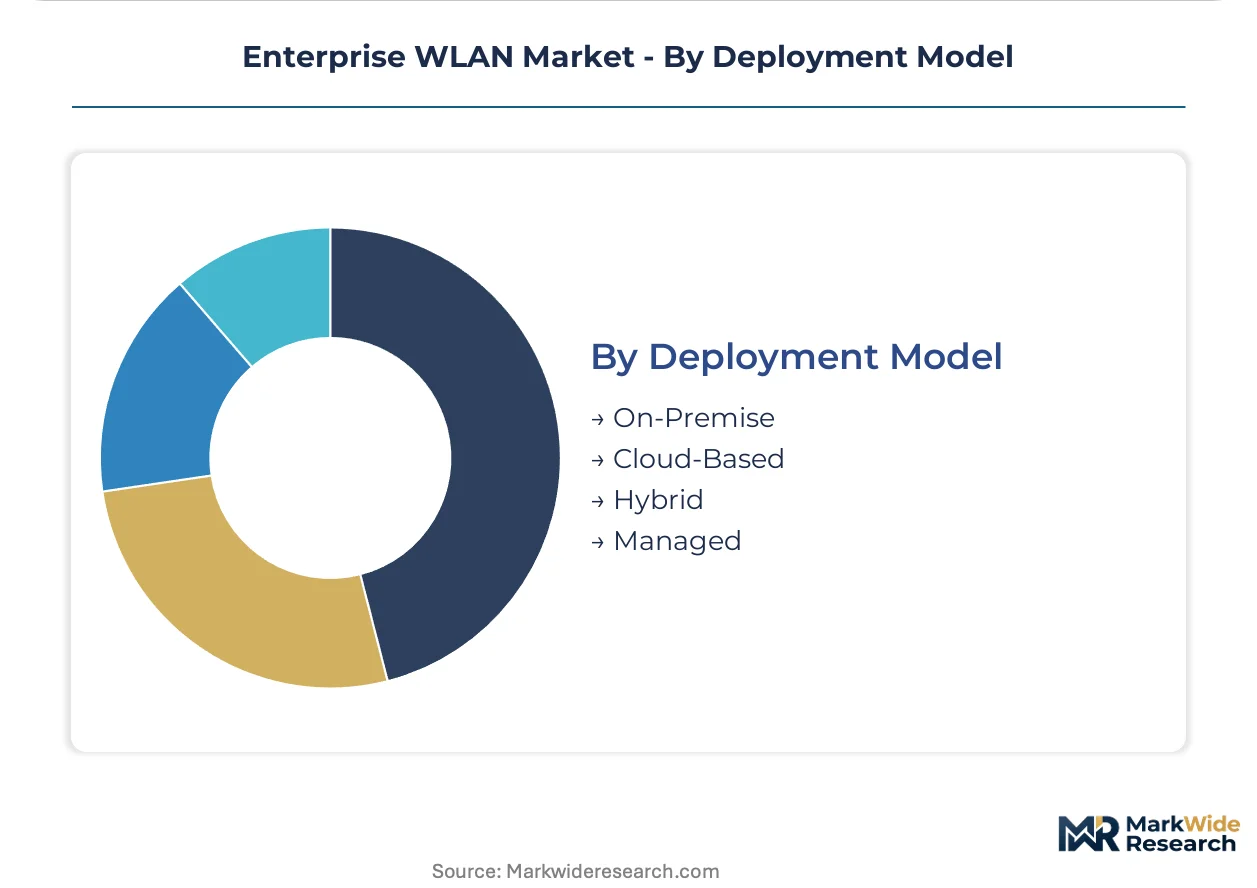
- On-Premise:Controller hardware and management software residing within customer data centers. Regulated industries with data sovereignty requirements maintain on-premise deployments despite higher staffing costs.
- Cloud-Based:Fully hosted management planes with browser-based administration. Mid-market enterprises without dedicated wireless engineering teams gravitate toward this model for reduced operational complexity.
- Hybrid:Split architectures with on-premise policy engines and cloud-hosted analytics. Large enterprises pilot hybrid models during migration windows to preserve legacy controller investments.
- Managed:Third-party operation of entire wireless infrastructure under long-term service agreements. Distributed retail and hospitality chains outsource radio management to avoid regional IT staffing.
On-Premise retains installed base dominance; Cloud-Based deployment climbs the fastest as vendor platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in the United States deploy denser access point grids than industrial campuses in Germany, where private 5G-WLAN convergence absorbs infrastructure budgets differently. Educational institutions across multiple geographies favor standardized procurement vehicles over best-of-breed sourcing.
United States
Healthcare facilities drive dense radio deployments as wired bedside telemetry retires in favor of wireless patient monitoring. The FCC's 6 GHz spectrum allocation created contiguous unlicensed bandwidth that accelerates 802.11ac infrastructure replacement. Hospital systems in Boston and the Research Triangle exploit this bandwidth infusion for uncompressed medical imaging transport.
Germany
Industrial campuses pilot private 5G-WLAN orchestration layers that unify policy management across licensed and unlicensed spectrum. ETSI harmonization of channel plans reduces SKU complexity for multi-national rollouts. Manufacturing clusters in Bavaria and North Rhine-Westphalia deploy these converged networks for deterministic warehouse robotics control.
China
Enterprise campuses adopt cloud-native controller platforms to reduce on-site engineering requirements for thousand-node deployments. MIIT spectrum policies shape regional radio configurations and firmware development roadmaps. Technology corridors in Shenzhen and Beijing host dense access point grids serving financial services and cloud computing campuses.
Japan
Educational institutions and corporate campuses refresh aging infrastructure with Wi-Fi 6E protocol equipment for high-density connectivity. METI industrial standards influence procurement specifications for automation-grade wireless performance. Osaka and Nagoya manufacturing zones deploy these systems for robotics integration and real-time production monitoring.
United Kingdom
Multi-campus enterprises consolidate vendor relationships around single-stack cloud platforms that unify wired and wireless policy enforcement. Ofcom spectrum allocations govern power limits and channel availability for enterprise deployments. London financial services clusters and Manchester technology corridors favor these standardized procurement vehicles.
Enterprise WLAN Market Vendor Landscape
Capability concentration sits with silicon-to-software integrated players; scale advantage sits with cloud-native platform vendors. The vendor base stratifies across three tiers: full-stack infrastructure providers, specialized wireless pure-plays, and IT conglomerates with networking divisions. Dominant competitive moves include portfolio diversification into adjacent security and SD-WAN domains, plus geographic expansion through channel partner ecosystems.
Within the cloud-native tier, Cisco Systems and Extreme Networks exemplify platform-centric positioning, while Huawei Technologies anchors the vertically integrated archetype with captive silicon production. These three occupy positions that reflect divergent bets on controller architecture: hosted versus on-premise versus hybrid orchestration layers.
| Leading Market Players |
|---|
| Fortinet |
| RUCKUS Networks |
| Cisco Systems |
| CommScope |
| Extreme Networks |
| Hewlett Packard Enterprise |
| Huawei Technologies |
| Alcatel-Lucent Enterprise |
| Juniper Networks |
| Others |
Supply Flow & Price Mechanics
Taipei and Hsinchu semiconductor clusters anchor radio frequency front-end module supply, with foundry capacity utilization directly translating to access point OEM pricing power during procurement cycles. Contract structures in this market favor long-term lifecycle support agreements over transactional hardware resale, compressing upfront margins while extending revenue recognition timelines.
Pricing Analysis
Long-term service contracts dominate enterprise procurement, with three-tier pricing structure across premium, standard, and economy levels differentiated by cloud management sophistication and RF optimization bundling. Certification tier—Wi-Fi Alliance 6E versus legacy 802.11ac—drives price differentiation alongside geographic delivery cost from East Asian manufacturing hubs. Pricing pressure stems from cloud-native competitors displacing hardware-centric incumbents through subscription economics. Mid-market enterprises exhibit highest price sensitivity, while healthcare systems with life-critical latency requirements absorb premium tiers without volume negotiation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for radio frequency component sourcing. Taiwan, South Korea, and mainland China concentrate foundry capacity for baseband processors and power amplifiers. Raw material dependencies center on gallium arsenide substrates, high-purity silicon wafers, and rare-earth magnetics for antenna arrays. Single-source vulnerability in 6 GHz filter modules threatens lead time stability. Distribution runs through authorized value-added resellers with certified wireless engineering capabilities, bypassing commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Enterprise WLAN market sits in cyclical recovery as FCC spectrum allocations trigger infrastructure replacement waves across healthcare and education verticals. Refresh cycle compression from regulatory tailwinds creates procurement windows favoring prepared vendors.
For Market Incumbents: Pre-empt private 5G substitution by embedding licensed spectrum orchestration into unified radio platforms before factory automation budgets fragment. Defend margin position through backward integration into captive silicon design, reducing dependency on concentrated foundry capacity. Channel control via certified wireless engineering partnerships blocks cloud-native entrants from enterprise accounts with complex RF deployment requirements. For New Entrants and Emerging Players: Southeast Asian mid-market enterprises represent underpenetrated white space where cloud-native automation platforms displace legacy controller architectures without specialized RF engineering staff. Target educational institution refresh cycles in United States public school districts favoring standardized procurement vehicles over best-of-breed sourcing. Partner with regional value-added resellers lacking wireless certification pipelines to accelerate market entry without direct sales infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because cloud controller offloading transforms capital expenditure into predictable subscription streams with negative churn characteristics. Acquisition targets should display vertical integration into radio frequency design or proprietary automation platforms reducing deployment labor. Monitor Wi-Fi Alliance certification queue lengths as early signal of vendor competitive window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Vendor-hosted controller planes reduce on-site engineering hours for mid-market enterprises. |
| Private 5G-WLAN Convergence Development | German industrial campuses pilot unified policy management across licensed and unlicensed spectrum. |
| Silicon-to-Software Vertical Integration | Captive access point chip design insulates margins from foundry concentration in East Asia. |
| Educational Institution Partnership | Multi-thousand-node university deployments concentrate procurement windows for scalable vendors. |
| Healthcare System Certification Investment | FCC 6 GHz allocation enables uncompressed medical imaging transport for hospital telemetry replacement. |
Methodological Framework
A standing panel of campus IT directors, wireless network engineers, value-added reseller principals, and healthcare technology procurement managers provided ongoing calibration against operating reality. Primary interviews combined with secondary validation from FCC spectrum allocation orders, ETSI harmonization documentation, Wi-Fi Alliance certification databases, and vendor financial disclosures. Bottom-up access point shipment modeling triangulated against top-down enterprise infrastructure spending surveys.
Scenario-bracketing framed analytical approach across the projection horizon, with segmentation modeling across deployment model, end-user vertical, protocol generation, and geographic regulatory cluster. CAGRs derived from weighted average of historical refresh cycle analysis and forward-looking spectrum policy impact assessment. Forecast inputs incorporated hospital infrastructure modernization timelines and industrial automation wireless specification evolution.
Practitioners should monitor semiconductor foundry utilization rates, private 5G pilot conversion rates, and Wi-Fi 7 standardization progress for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Multefire Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
North America in-Building Wireless Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Wigig Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
Near Field Communication Market