
 Africa Roaming Tariff Market | 2026-2036
Africa Roaming Tariff Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Roaming Tariff Market Intelligence
Project finance and spectrum leasing arrangements is tilting competitive dynamics toward asset-light network sharing models across the continent. MTN Group leverages its multi-country footprint to sustain wholesale roaming agreements that span over a dozen African markets. Orange Group anchors premium bilateral tariff negotiations through its Francophone West and Central Africa infrastructure. Airtel Africa competes on cost-optimized prepaid roaming corridors linking East African Community member states.
Africa roaming tariffs denote the wholesale and retail pricing structures applied when mobile subscribers access voice, SMS, and data services outside their home network's licensed geography, typically governed by bilateral or multilateral inter-operator agreements with per-minute, per-message, or per-megabyte rate tables. These tariffs function as the commercial backbone enabling seamless cross-border connectivity for subscribers while generating wholesale revenue for visited networks. The service type dimension shows data and bundled plans capturing margin expansion as smartphone penetration deepens, while voice and SMS segments retain volume concentration in corridors linking lower-ARPU markets. Within pricing models, prepaid and pay-as-you-go structures dominate subscriber uptake across the continent, though postpaid corporate accounts yield higher per-user roaming yields.
The African Union's digital transformation strategy, alongside national regulators such as Nigeria's NCC and South Africa's ICASA, shapes market access through wholesale rate caps and transparency mandates. The ECOWAS regional roaming framework directly compresses retail tariffs for cross-border voice and data within West African member states. Stakeholders must monitor the progression of the African Continental Free Trade Area's digital protocol negotiations, as these will determine whether pan-African roaming consolidates under harmonized regulatory umbrellas or fragments along existing regional economic community lines.
Market Dynamics
The ECOWAS regional roaming framework is compressing retail tariffs across West African corridors, forcing operators to restructure wholesale interconnection agreements and migrate toward data-centric bundled offerings.
Growth Catalysts
- Single African Air Transport Market:The African Union's aviation liberalization protocol is accelerating cross-border passenger volumes, directly stimulating roaming traffic in Nigeria, Kenya, and South Africa.
- Smartphone penetration:Deepening mobile broadband adoption across East African Community member states is shifting consumption toward data-heavy roaming bundles with higher margin profiles.
- ECOWAS roaming framework:The regional regulatory mechanism mandates wholesale rate transparency and retail price caps, eliminating arbitrage friction for voice and SMS traffic across Benin, Ghana, and Côte d'Ivoire.
Market Restraints
- Wholesale rate volatility:Bilateral inter-operator agreements lack standardized pricing floors, exposing smaller mobile virtual network operators to asymmetric negotiating power with incumbent host networks.
- Infrastructure concentration:Terrestrial fiber backhaul and submarine cable landing stations cluster in Lagos, Nairobi, and Cape Town, creating single-point-of-failure risk for cross-border traffic termination.
- Regulatory fragmentation:Divergent licensing regimes between Nigeria's NCC, South Africa's ICASA, and Kenya's CA prevent seamless pan-African spectrum harmonization for roaming service continuity.
Strategic Opportunities
- Francophone Central Africa:Cameroon and Gabon present underpenetrated corridors where Orange Group's existing infrastructure enables premium bilateral tariff positioning ahead of competitive entry.
- AfCFTA digital protocol:The African Continental Free Trade Area's pending telecommunications chapter could establish harmonized wholesale roaming rules, reducing compliance complexity for multi-country operators.
- 5G standalone roaming:Convergence of network slicing and edge computing capabilities allows operators to offer latency-guaranteed enterprise roaming services for mining and logistics verticals.
Industry Challenges
- Fraud management systems:International revenue share fraud and subscription identity module boxing require continuous capital deployment for real-time signaling analysis and artificial intelligence-driven anomaly detection.
- Legacy billing integration:Prepaid roaming corridors in East Africa depend on outdated CAMEL protocol implementations that complicate real-time charging for data session continuity across network boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Roaming Tariff Market |
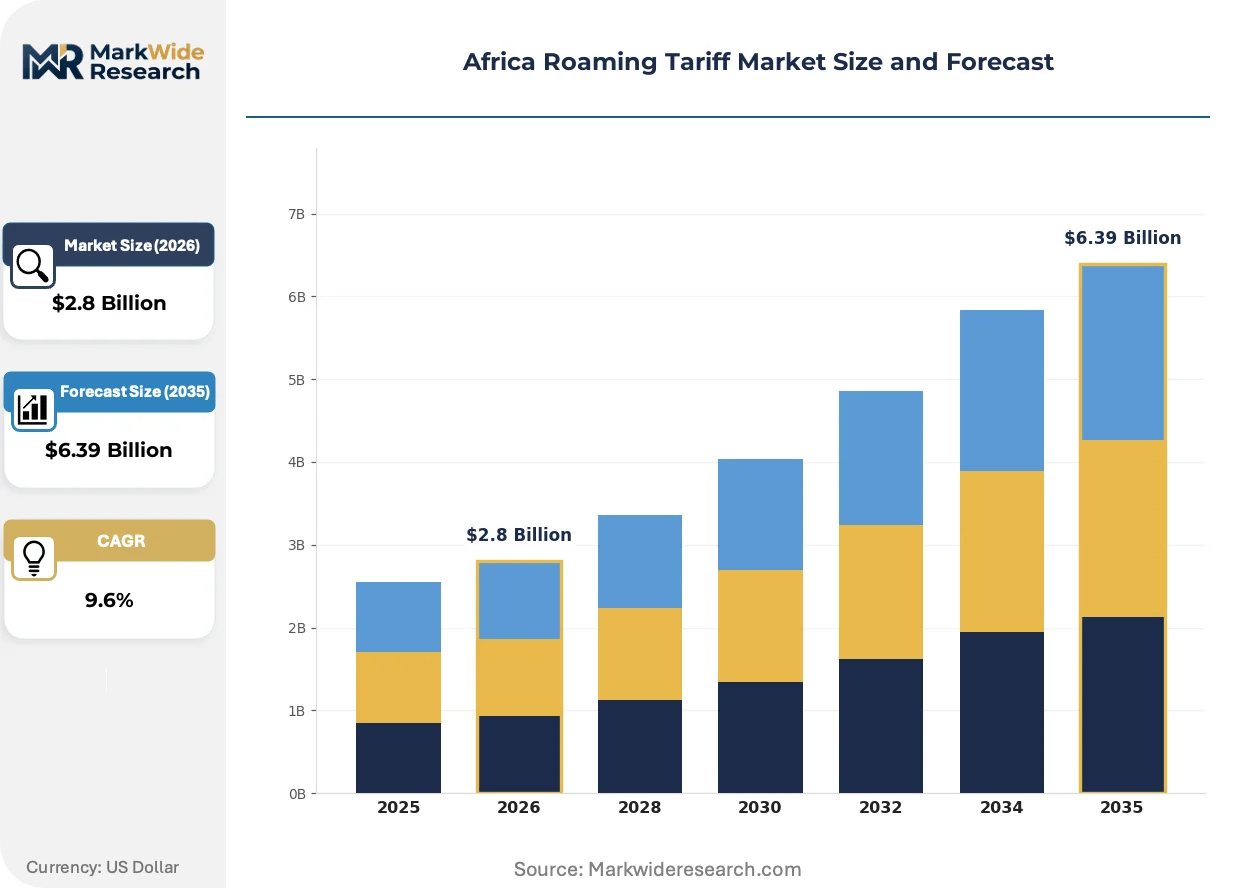
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, SMS, Data, Bundled Plans Pricing Model: Postpaid, Prepaid, Pay-As-You-Go, Flat Rate Customer Type: Business Travelers, Tourists, Expatriates, Residents Network Operator: Local Carriers, International Providers, Virtual Operators, Multinational Companies |
| Companies Covered | Orange Group, Telefonica SA, MTN Group, Digicel Group, China Mobile Ltd., Airtel Africa, Deutsche Telekom AG, Bharti Airtel Ltd, Vodafone Group plc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Roaming Tariff Market Strategic Shifts & Innovations
Artificial intelligence and machine learning are transforming how operators predict roaming demand patterns, optimize wholesale rate negotiations, and detect anomalous traffic signaling in real time.
eSIM provisioning platforms are digitizing subscriber onboarding workflows by eliminating physical distribution dependencies. Mobile network operators in Nigeria and South Africa are accelerating eSIM activation for corporate account segments. This technology is digitizing the traditional roaming enablement chain from days to minutes.
The African Union's digital transformation strategy mandates interoperable mobile money settlement for cross-border roaming charges. National regulators in Kenya and Ghana are drafting secondary legislation to operationalize instant payment clearing between home and visited networks. Francophone West African markets face the steepest compliance timelines due to overlapping regional monetary union protocols.
Enterprise procurement teams are consolidating roaming contracts under managed mobility service providers rather than negotiating directly with carriers. Mining and oil exploration companies operating across multiple African jurisdictions are driving this aggregation. South Africa's corporate sector exhibits the most advanced adoption of centralized roaming expense management platforms.
Africa Roaming Tariff Market Segmentation
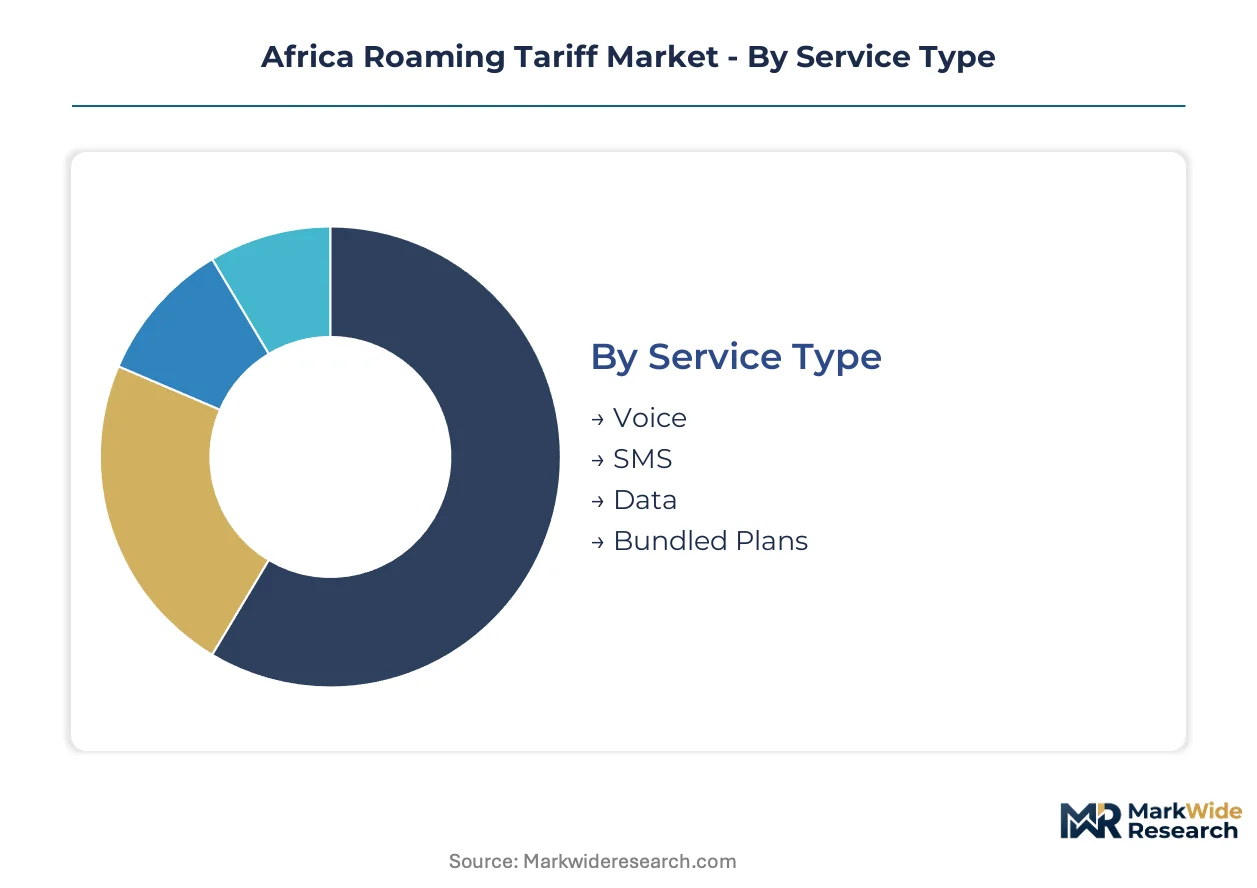
Segmentation in the Africa Roaming Tariff Market reveals divergent margin structures across service types and customer profiles. Operators calibrate wholesale negotiations and retail pricing precision based on these divides. Understanding these splits enables targeted bundle design and corridor-specific investment.
Service Type:
After-sales service intensity varies sharply across service types, with data roaming demanding continuous network optimization while voice requires minimal post-activation support.
- Data:High-bandwidth mobile internet sessions drive the steepest wholesale rate inflation due to asymmetric traffic flows between Nigerian and Kenyan corridors. Smartphone penetration in East African Community states concentrates demand here, though submarine cable concentration in Mombasa and Lagos creates termination risk.
- Bundled Plans:Integrated voice-SMS-data packages capture premium positioning through simplified rate transparency mandated by ECOWAS frameworks. Corporate procurement teams in South Africa increasingly mandate these for cross-border workforce mobility.
- Voice:Per-minute cross-border calling retains volume concentration in West African corridors linking Benin, Ghana, and Côte d'Ivoire under regional price caps.
- SMS:Text messaging traffic persists in lower-ARPU markets where feature phones dominate, particularly in Francophone Central Africa.
By volume, Voice leads. By growth pace, Data is expanding most quickly.
Pricing Model:
Cost tier stratification determines customer acquisition economics, with prepaid models dominating mass-market onboarding while postpaid anchors enterprise yield.
- Prepaid:Top-up credit systems before service use dominate subscriber uptake across Nigerian and Kenyan retail segments. Real-time charging complexity under legacy CAMEL protocols complicates data session continuity.
- Pay-As-You-Go:Per-unit consumption without subscription commitment attracts price-sensitive tourists and short-stay business visitors in South African gateway cities.
- Postpaid:Monthly billing with usage reconciliation yields highest per-user roaming yields from mining and logistics corporate accounts operating across multiple jurisdictions.
- Flat Rate:Unlimited daily or weekly allowances reduce bill shock anxiety for leisure travelers in safari tourism corridors.
Prepaid captures the widest subscriber base. Postpaid delivers the strongest margin per account.
Customer Type:
Application context shapes usage intensity, with business travelers generating predictable high-value traffic versus tourists exhibiting sporadic consumption spikes.
- Business Travelers:Intra-African commerce expansion drives consistent cross-border mobility from Nigerian corporate hubs to Kenyan and South African operational sites. Managed mobility service providers increasingly aggregate their procurement.
- Tourists:Seasonal leisure visitors concentrate demand in coastal and safari destinations, with eSIM provisioning reducing activation friction at Johannesburg and Lagos airports.
- Expatriates:Long-term foreign residents require sustained roaming for home-country banking and family communication, particularly in oil-sector employment clusters.
- Residents:Cross-border commuters in East African Community member states utilize roaming for daily work-travel patterns between Nairobi and Kampala.
Business Travelers generate the highest revenue per user. Tourists show the steepest adoption curve for eSIM-enabled services.
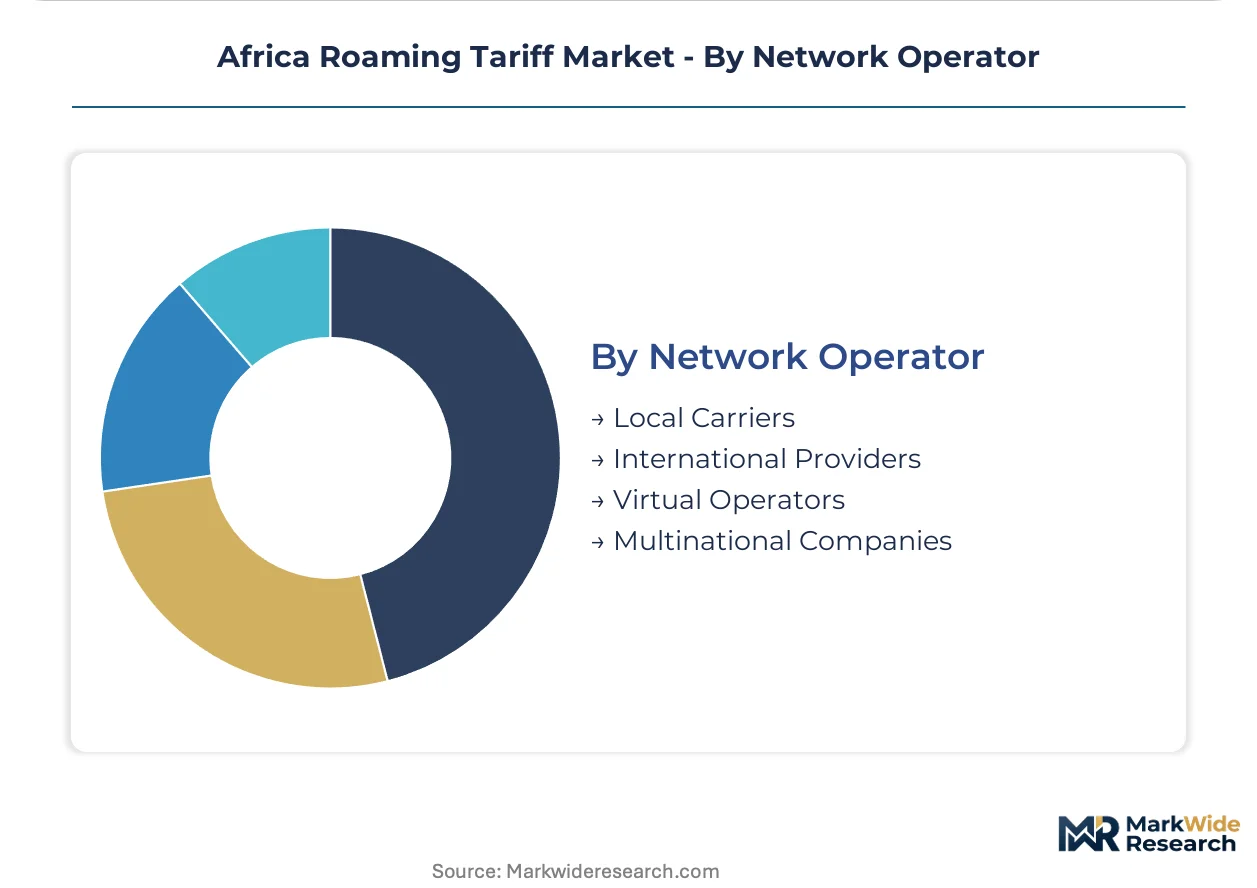
Network Operator:
Supply concentration among multinational operators versus fragmented local carriers determines wholesale negotiating leverage and retail pricing flexibility.
- Multinational Companies:MTN Group and Orange Group leverage multi-country infrastructure to sustain bilateral roaming agreements spanning over a dozen markets. Their scale enables premium tariff positioning in underpenetrated corridors.
- Local Carriers:Single-market operators in Cameroon and Gabon depend on wholesale access negotiations with dominant host networks, exposing them to asymmetric rate pressure.
- International Providers:Non-African carriers with bilateral agreements terminate traffic through Lagos and Cape Town landing stations.
- Virtual Operators:Mobile virtual network operators lack owned infrastructure and face wholesale rate volatility due to absent pricing floors in bilateral inter-operator agreements.
Multinational Companies control corridor pricing. Virtual Operators face the steepest margin compression risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pricing-power asymmetry between South African operators and their West African counterparts concentrates wholesale margin capture in Johannesburg and Cape Town corridors, while Nigerian and Kenyan networks absorb higher interconnection costs.
Nigeria
Nigeria's NCC mandates wholesale rate transparency for cross-border voice termination, compressing arbitrage margins for international carriers. Lagos anchors submarine cable landing capacity for roaming traffic termination across West African corridors. The concentration of fiber backhaul in Lagos metropolitan clusters creates single-point vulnerability for data session continuity.
South Africa
ICASA's retail tariff disclosure requirements force operators to publish standardized roaming rate cards for corporate procurement teams. Johannesburg and Cape Town host the continent's densest concentration of managed mobility service providers aggregating enterprise accounts. Mining sector procurement drives premium postpaid roaming yields across Southern African Development Community corridors.
Kenya
Kenya's CA implements East African Community harmonized roaming frameworks reducing retail voice caps between Nairobi and Kampala. Mombasa submarine cable landing stations terminate asymmetric data traffic flows from Nigerian corporate hubs. Smartphone penetration in Nairobi metropolitan clusters accelerates demand for high-bandwidth mobile internet roaming sessions.
Ghana
Ghana's NCA enforces ECOWAS regional roaming price ceilings for cross-border voice and SMS traffic with Côte d'Ivoire and Togo. Accra's emerging fintech corridor drives mobile money settlement integration for roaming charge clearing. The concentration of terrestrial fiber interconnection in Tema port clusters supports wholesale bandwidth arbitrage for visiting network operators.
Africa Roaming Tariff Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying wholesale termination capacity. The Africa roaming tariff market concentrates around pan-African multinational operators with multi-country infrastructure footprints, while single-market carriers and mobile virtual network operators occupy dependent wholesale access positions. Two strategic archetypes dominate: scale-driven bilateral negotiators leveraging cross-border infrastructure, and cost-optimized corridor specialists targeting regional economic community integration. Competitive moves center on network sharing agreements and spectrum leasing arrangements that reduce capital intensity.
Among pan-African platform operators, MTN Group and Orange Group exemplify the scale-driven bilateral negotiator archetype through their multi-country infrastructure spanning over a dozen markets. Airtel Africa occupies a position within the cost-optimized corridor specialist tier, competing on prepaid roaming bundles across East African Community member states. These three anchors represent divergent geographic coverage strategies and wholesale pricing philosophies.
| Leading Market Players |
|---|
| Orange Group |
| Telefonica SA |
| MTN Group |
| Digicel Group |
| China Mobile Ltd. |
| Airtel Africa |
| Deutsche Telekom AG |
| Bharti Airtel Ltd |
| Vodafone Group plc |
| Others |
Cost & Logistics Intelligence
Lagos-Abidjan freight corridors transmit asymmetric cost dynamics through West African roaming markets, concentrating wholesale pricing power in Nigerian hub operators while forcing Ghanaian and Ivorian networks to absorb higher interconnection charges. This logistics-cost asymmetry amplifies downstream price differentiation between prepaid mass-market tiers and premium postpaid corporate segments.
Pricing Analysis
Corporate procurement teams anchor wholesale rate negotiations through managed mobility service providers aggregating mining and logistics accounts. Pricing stratifies across premium postpaid, standard bundled, and economy prepaid tiers, with differentiation driven by data volume allowances and real-time charging capability. Cost compression in prepaid segments intensifies because legacy CAMEL protocol implementations complicate session continuity. Tourists and short-stay visitors exhibit highest price sensitivity; enterprise accounts show least elasticity due to operational necessity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from submarine cable consortiums ease capital deployment for terrestrial fiber backhaul expansion. Network infrastructure concentrates in Nigeria, South Africa, and Kenya, with equipment sourcing from Chinese and European vendors. Terrestrial backhaul draws from fiber optic cable, microwave transmission hardware, and edge computing nodes. Single-point vulnerability at Lagos and Mombasa landing stations creates termination risk for cross-border data sessions. Distribution runs through bilateral inter-operator agreements with multinational anchor tenants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated enterprise procurement through managed mobility service providers, fragmenting direct carrier relationships as mining and logistics firms centralize roaming expense management.
For Market Incumbents: Pre-empt margin erosion in West African corridors by accelerating network sharing agreements that reduce capital intensity, while investing in AI-driven fraud detection systems to counter international revenue share fraud from emerging SIM-boxing operations. Wholesale rate transparency mandates from Nigeria's NCC threaten arbitrage positions; defend through premium bilateral positioning in underpenetrated Francophone Central Africa corridors. For New Entrants and Emerging Players: Pursue white-space opportunities in Cameroon and Gabon where Orange Group's infrastructure dominance has left pricing gaps for data-centric bundled offerings. The East African Community's harmonized roaming framework creates entry vectors for cost-optimized prepaid specialists targeting Nairobi-Kampala commuter corridors. Lead with eSIM-enabled instant provisioning to bypass physical distribution dependencies that burden incumbent activation workflows. For Investors and Strategic Acquirers: Asset-light mobile virtual network operators with established wholesale access agreements represent acquisition targets with scalable corridor economics. Long-term viability hinges on AfCFTA digital protocol implementation harmonizing cross-border regulatory frameworks. Watch ECOWAS and East African Community regulatory convergence as inflection signal for pan-African consolidation viability.| Strategic Initiative | Industry Significance |
|---|---|
| Network Sharing Agreement | Reduces capital intensity for 5G standalone deployment across Nigerian and Kenyan corridors. |
| AI Fraud Detection Investment | Enables real-time signaling analysis to counter SIM-boxing and revenue share fraud. |
| eSIM Platform Launch | Compresses subscriber onboarding from days to minutes for corporate account segments. |
| Mobile Money Settlement Integration | Aligns with African Union digital transformation strategy for cross-border charge clearing. |
| Managed Mobility Service Partnership | Captures consolidated procurement from mining sector accounts across SADC corridors. |
Research Approach
A standing panel of mobile network operator wholesale directors, regulatory affairs managers at national communications authorities, and enterprise mobility procurement officers provided ongoing calibration for this analysis. Primary fieldwork combined structured interviews with bilateral roaming negotiators and real-time charging system architects, validated against secondary sources including ECOWAS regulatory filings, African Union digital strategy documents, and submarine cable consortium landing station reports. Bottom-up traffic volume modeling and top-down revenue aggregation were triangulated to establish market size estimates.
Scenario bracketing around AfCFTA digital protocol implementation timelines and regional economic community harmonization pace shaped the analytical framework. Segmentation dimensions modeled include service type, pricing model, customer category, and network operator tier across the projection horizon. CAGRs were derived from corridor-specific traffic growth assumptions and wholesale rate compression trajectories. Forecast inputs incorporated smartphone penetration curves, cross-border passenger volume projections from Single African Air Transport Market data, and mobile money adoption rates for roaming settlement.
Macroeconomic conditions sit as an overlay; deviation in currency volatility, sovereign debt stress, or fiber backhaul investment cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization progress and infrastructure deployment timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Virtual PBX Market
Telecommunications
5G Connections Market
Telecommunications
Indonesia ICT Market
Telecommunications
Europe Managed SD-WAN Services Market
Telecommunications
Germany Critical Communication Market
Telecommunications
5G Transport Networks Market
Telecommunications
Competitive Local Exchange Carriers (CLEC) Market
Telecommunications
South Africa Telecom Market
Telecommunications
Global GPON Technology Market
Telecommunications
Thailand ICT Market
Telecommunications
DWDM System Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Germany ICT Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market