
 Global Hosted PBX Market | 2026-2036
Global Hosted PBX Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hosted PBX Market Foresight
The EU Green Deal is decoupling legacy on-premises telephony from enterprise sustainability mandates across Germany, France, and the Netherlands. Microsoft Corporation leverages its Azure cloud backbone to anchor unified communications deployments in regulated European industries. Cisco Systems competes through specialized security certifications that satisfy financial services procurement requirements in London and Singapore. NEC Corporation dominates legacy migration projects across Japanese manufacturing conglomerates seeking carbon footprint reductions.
Hosted PBX denotes a cloud-delivered private branch exchange where voice switching, call routing, and voicemail reside on provider-managed infrastructure rather than customer premises equipment, typically operating over SIP trunking with 99.99% uptime SLAs and AES-256 encryption for enterprise-grade security. Cloud PBX services capture the largest revenue pool among service type segments as multi-tenant architectures reduce per-seat provisioning costs below on-premises equivalents. Small and medium businesses represent the fastest-expanding customer type category, drawn by subscription pricing that eliminates capital expenditure for PBX hardware. Unified Communications applications command premium margins by integrating voice, video, and messaging into single-platform deployments.
FCC net neutrality rulings in the United States shape bandwidth prioritization for VoIP traffic, while GDPR and the EU AI Act impose data residency and algorithmic transparency obligations on European deployments. Japan's METI promotes cloud migration through SME subsidies that explicitly cover hosted voice subscriptions. Stakeholders must weigh sovereign cloud requirements against multi-region redundancy architectures as regulatory fragmentation intensifies across jurisdictions.
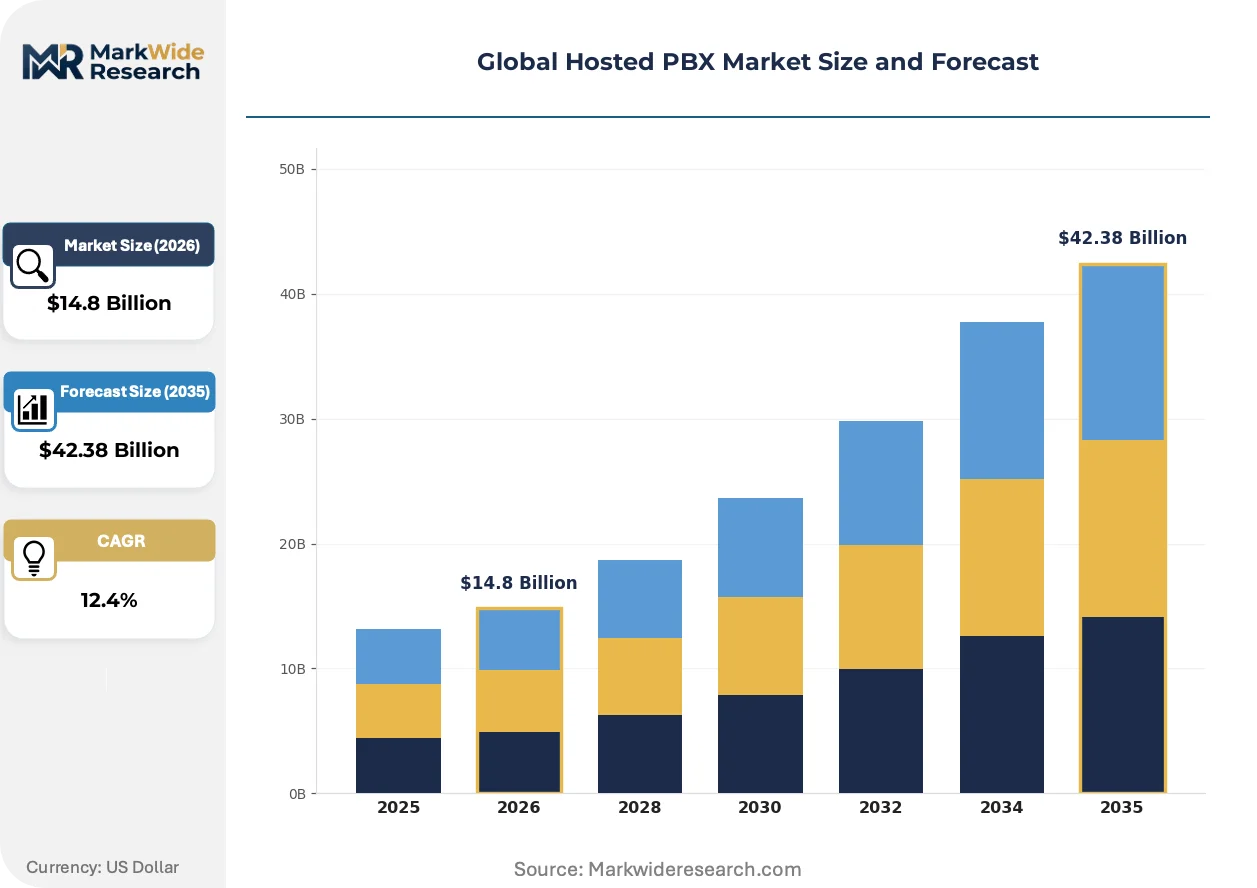
Market Dynamics
Enterprise migration from on-premises telephony to cloud-delivered voice infrastructure is compressing hardware replacement cycles and redirecting capital budgets toward subscription-based operational expenditure models.
Growth Catalysts
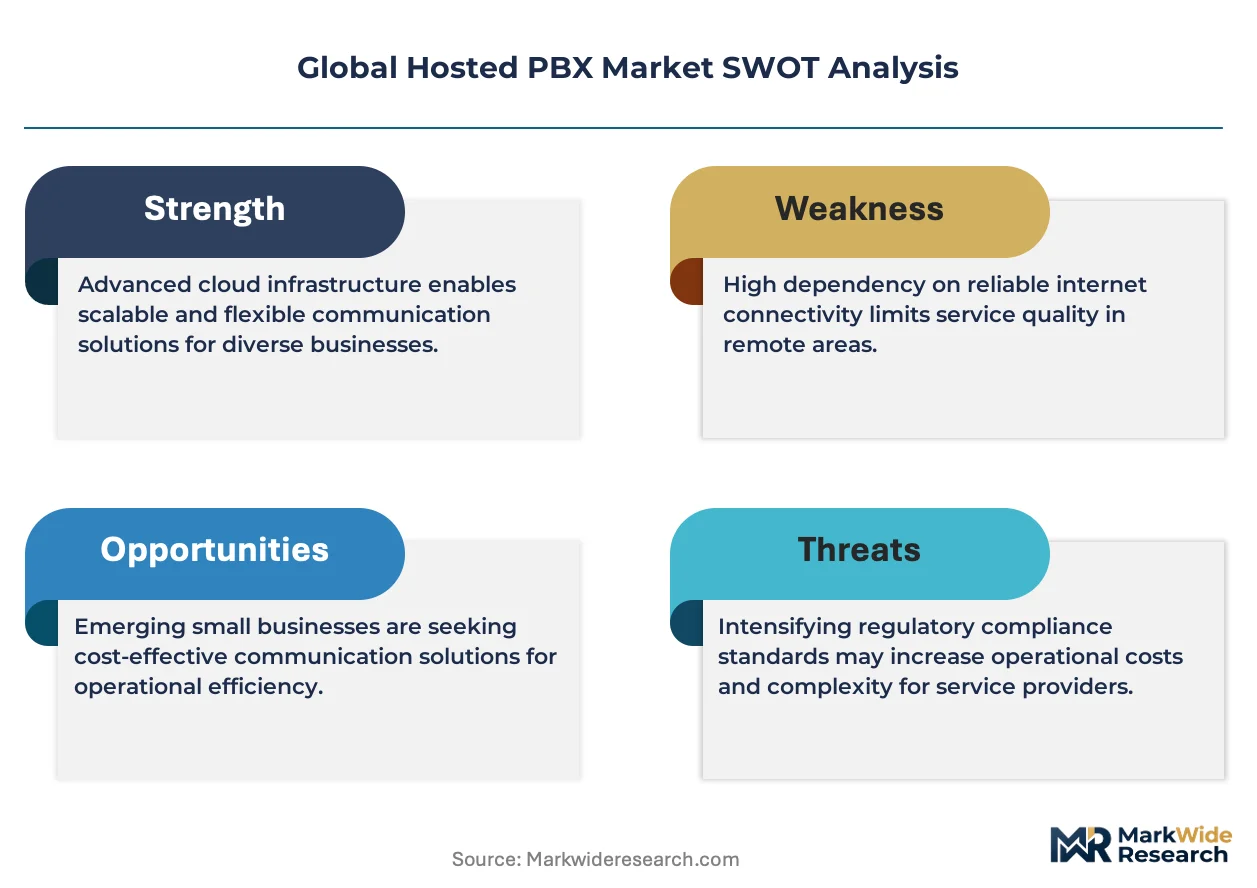
- GDPR and EU AI Act compliance mandates:European enterprises face escalating penalties for non-compliant data handling, accelerating procurement of certified cloud voice platforms with built-in encryption and residency controls.
- Healthcare cloud migration:Hospital systems and outpatient networks are replacing legacy PBX hardware with hosted solutions to unify patient communication channels and enable telehealth integration.
- SME subsidy programs:Japan's METI explicitly covers hosted voice subscriptions under cloud migration incentives, reducing adoption friction for manufacturing and service sector small businesses.
Market Restraints
- Bandwidth dependency and ISP concentration:FCC net neutrality rulings create uncertainty around VoIP traffic prioritization, while last-mile infrastructure bottlenecks in rural United States territories degrade service quality.
- Data sovereignty fragmentation:Divergent national requirements for call recording storage, lawful intercept capabilities, and encryption key management force providers to maintain jurisdiction-specific infrastructure.
- Legacy system integration costs:Custom API development for ERP and CRM connectivity often exceeds projected implementation budgets, particularly for financial services firms with decades-old mainframe dependencies.
Strategic Opportunities
- United States federal modernization:Government agencies under FITARA mandates represent an underpenetrated vertical with multi-year procurement horizons and FedRAMP authorization pathways.
- AI-powered voice analytics convergence:Integration of natural language processing with call routing systems enables real-time sentiment analysis and automated compliance monitoring for regulated industries.
- Indirect channel expansion:Managed service providers and telecommunications resellers are emerging as primary customer acquisition channels, reducing direct sales overhead while extending geographic reach.
Industry Challenges
- Certification timeline compression:FedRAMP, ISO 27001, and SOC 2 Type II audit cycles often extend 12-18 months, delaying market entry for new platform entrants and feature releases.
- Interoperability complexity:SIP trunking standardization gaps between carrier networks force engineering teams to maintain custom configurations for each geographic deployment.
- Skills scarcity in voice engineering:The shrinking pool of technicians proficient in both legacy TDM systems and cloud-native architectures constrains enterprise migration project velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hosted PBX Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $42.38 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Virtual PBX, VoIP PBX, Cloud PBX, IP PBX, SIP Trunking Application: Call Center, Unified Communications, Small Office, Contact Management, Telemarketing Customer Type: Small & Medium Businesses, Enterprises, Startups, Non-Profit Organizations, Educational Institutions Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Managed Hosting |
| Companies Covered | Microsoft Corporation, Mitel Networks, RingCentral, NEC Corporation, Avaya Holdings, 8x8, Vonage Holdings, Panasonic Corporation, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hosted PBX Market Shifts & Advancements
Artificial intelligence integration and edge computing architectures are fundamentally altering how voice infrastructure is deployed, managed, and consumed across enterprise environments.
WebRTC-based browser telephony is rewriting endpoint requirements for knowledge workers. Financial services firms in London and Singapore deploy click-to-call functionality directly within trading applications, eliminating softphone installations. This compression of client-side complexity accelerates onboarding velocity and reduces IT support ticket volumes.
The EU AI Act imposes algorithmic transparency obligations on automated call routing and voice biometric systems. European healthcare providers must now document decision logic for AI-driven patient prioritization. German hospital networks are responding by demanding vendor-provided model cards and audit trails as standard procurement requirements.
Subscription fatigue among mid-market buyers is fragmenting purchasing authority. United States manufacturing firms increasingly unbundle voice services from bundled unified communications suites, selecting best-of-breed providers for specific functions. This disintermediation of traditional telco relationships favors specialized hosted PBX vendors with transparent per-seat pricing.
Global Hosted PBX Market Segmentation
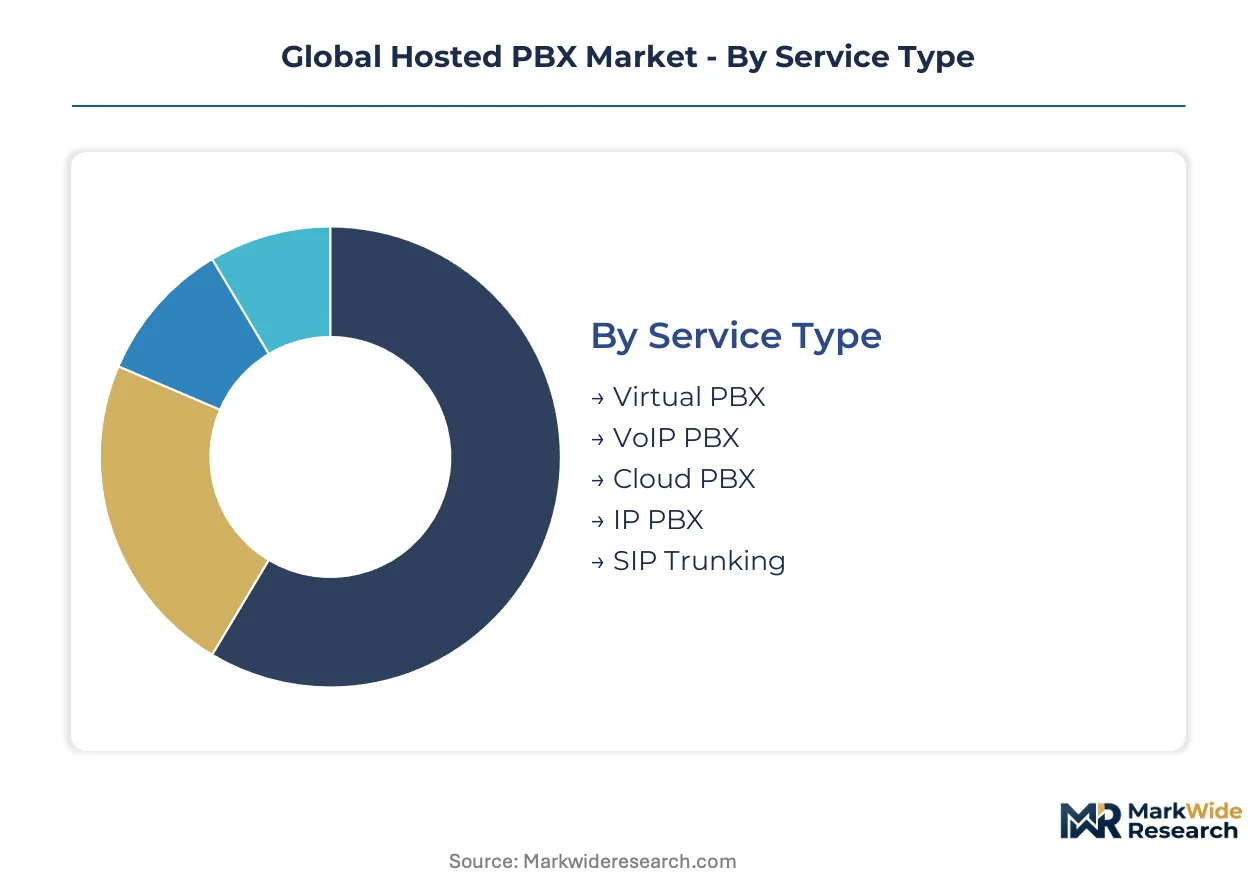
Hosted PBX architectures fragment across service delivery mechanisms, functional applications, and organizational scale. Each segmentation dimension carries distinct margin profiles, compliance obligations, and infrastructure requirements that shape vendor positioning.
Service Type:
Provider infrastructure concentration varies sharply across service architectures, with multi-tenant platforms achieving lowest per-seat economics.
- Cloud PBX:Multi-tenant architectures consolidate switching, voicemail, and auto-attendant functions on shared provider infrastructure. United States healthcare systems are migrating patient communication systems to this model under HIPAA-compliant Azure and AWS environments.
- Virtual PBX:Lightweight configurations deliver core call routing without dedicated hardware, appealing to distributed workforces. Japanese manufacturing SMEs access METI-subsidized deployments for carbon footprint reduction.
- VoIP PBX:Session initiation protocol-based voice delivery over broadband connections, requiring QoS-configured networks.
- SIP Trunking:Direct carrier connectivity replacing PRI circuits, enabling geographic number portability.
- IP PBX:Premises-based software solutions transitioning to hybrid cloud management.
Cloud PBX absorbs the bulk of installed capacity; Virtual PBX is expanding most quickly among subsidy-eligible small businesses.
Application:
Functional use cases determine integration depth, with unified platforms commanding premium pricing against single-purpose deployments.
- Unified Communications:Integrated voice, video, messaging, and presence across desktop and mobile endpoints. Financial services firms in London and Singapore deploy WebRTC-based click-to-call within trading applications, eliminating softphone overhead.
- Call Center:Omnichannel routing, IVR, and workforce management for agent pools. GDPR-compliant recording and AI-driven sentiment analysis drive European procurement specifications.
- Contact Management:CRM-embedded telephony for sales and service teams.
- Small Office:Basic auto-attendant and extension routing for under-50-employee sites.
- Telemarketing:Predictive dialer integration with do-not-call list scrubbing.
Unified Communications captures the highest revenue per seat; Call Center applications are climbing the fastest as AI-powered analytics penetrate regulated industries.
Customer Type:
Organizational scale dictates procurement authority, with enterprise buyers demanding FedRAMP certification against SME preference for month-to-month terms.
- Small & Medium Businesses:Subscription pricing eliminates capital expenditure for hardware replacement. United States manufacturing firms increasingly unbundle voice from bundled suites, selecting specialized providers with transparent per-seat pricing.
- Enterprises:Multi-site deployments requiring geographic redundancy and custom API integration for ERP connectivity.
- Startups:Rapid provisioning and pay-as-you-grow scalability without long-term contracts.
- Non-Profit Organizations:Discounted licensing and grant-funded migration from legacy systems.
- Educational Institutions:Campus-wide unified communications with emergency notification integration.
Enterprises maintain the largest aggregate spend; Small & Medium Businesses are gaining share fastest as subscription fatigue fragments purchasing authority.
Deployment Model:
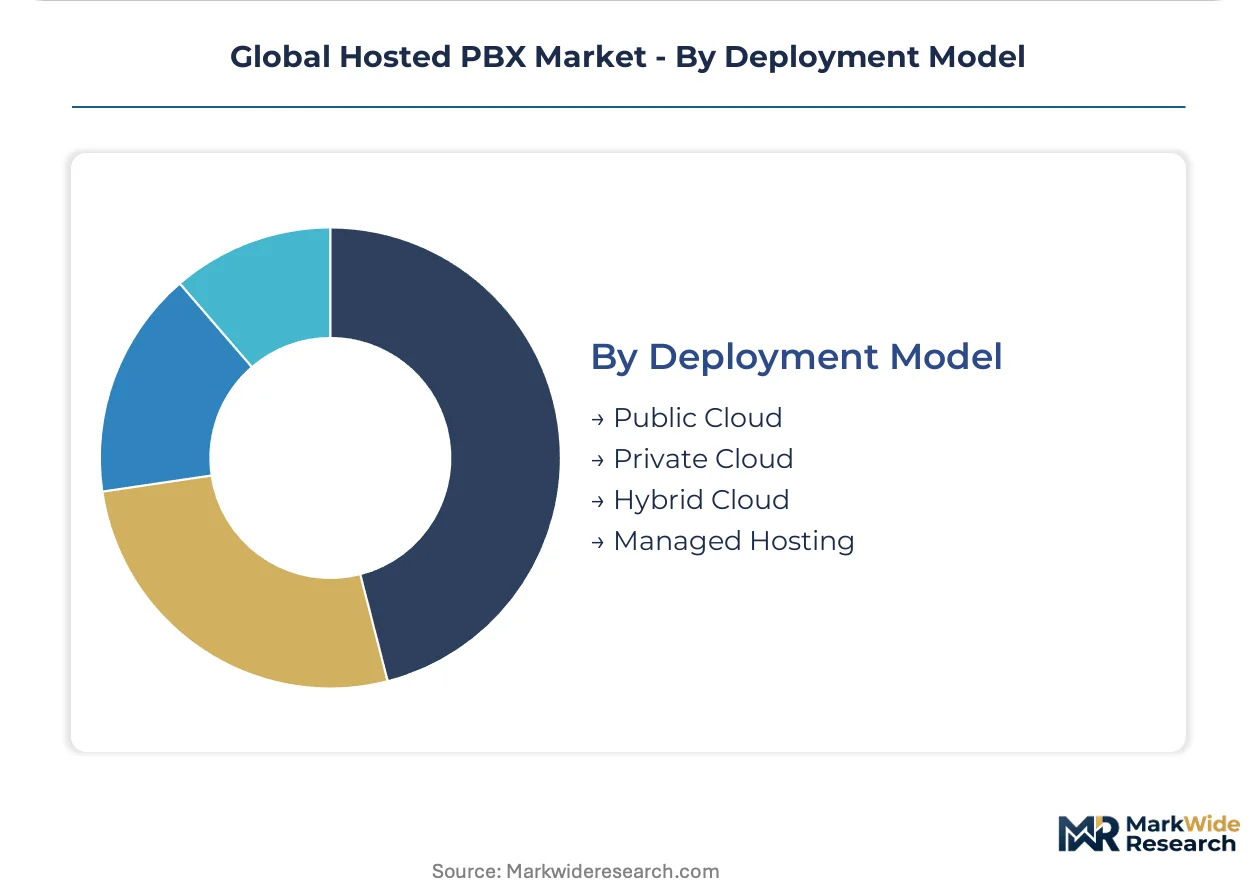
Infrastructure location determines data residency compliance, with sovereign cloud requirements forcing jurisdiction-specific platform instances.
- Public Cloud:Shared provider infrastructure with 99.99% uptime SLAs and AES-256 encryption. EU AI Act and GDPR compliance mandates accelerate European procurement of certified platforms with built-in residency controls.
- Private Cloud:Dedicated single-tenant environments for financial services and government agencies.
- Hybrid Cloud:Split architectures preserving on-premises survivability for critical sites.
- Managed Hosting:Provider-operated dedicated infrastructure with customer-defined security policies.
Public Cloud holds the dominant installed base; Private Cloud is expanding most quickly among FedRAMP-authorized federal contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors cloud voice infrastructure deployment, with enterprise adoption radiating through technology corridors in Austin, Boston, and Seattle. Regulatory fragmentation across data residency requirements shapes provider architecture decisions in every major economy.
United States
Federal agencies under FITARA mandates drive FedRAMP-authorized procurement, while healthcare systems migrate patient communications to HIPAA-compliant Azure environments. FCC net neutrality rulings create bandwidth prioritization uncertainty for VoIP traffic. Dallas-Fort Worth hosts the densest concentration of contact center deployments seeking geographic redundancy.
Germany
Industrial conglomerates in the Ruhr Valley and Bavaria decouple legacy on-premises telephony under EU Green Deal sustainability mandates. GDPR compliance requirements accelerate certified cloud voice platform procurement with built-in encryption controls. Frankfurt's financial services cluster demands vendor-provided model cards for AI-driven call routing under EU AI Act transparency obligations.
Japan
Manufacturing SMEs in the Chubu and Kansai regions access METI-subsidized hosted voice subscriptions for carbon footprint reduction. Legacy migration projects dominate procurement as conglomerates seek operational expenditure models. Tokyo's enterprise corridor concentrates multi-site deployments requiring integration with decades-old mainframe dependencies.
United Kingdom
Financial services firms in the City of London deploy WebRTC-based click-to-call within trading applications, eliminating softphone overhead. Post-Brexit data residency requirements force jurisdiction-specific infrastructure maintenance. Edinburgh and Manchester emerge as secondary hubs for regulated voice analytics procurement.
Singapore
Regional headquarters for multinational banks drive demand for security-certified unified communications satisfying financial services procurement requirements. Maritime and logistics clusters adopt cloud PBX for distributed workforce coordination across Southeast Asian operations. The Monetary Authority of Singapore's technology risk guidelines shape vendor selection criteria for trading floor deployments.
Global Hosted PBX Market Competitive Landscape
The competitive structure tilts toward cloud-native platform providers with multi-tenant architectures achieving lowest per-seat economics. Consolidation pressure intensifies as subscription fatigue fragments mid-market purchasing authority. Three archetypes dominate: hyperscale cloud infrastructure anchors, legacy equipment manufacturers pivoting to service models, and specialized security-certified specialists. Dominant competitive moves include strategic partnerships with managed service providers and geographic expansion through indirect channel networks.
Among North American platform providers, Microsoft Corporation and RingCentral occupy positions at the scale-driven end of the spectrum, while NEC Corporation represents the legacy manufacturer archetype executing carbon-focused migration projects. Cisco Systems sits within the security-specialist tier, anchoring financial services procurement in regulated European and Asian markets. Each exemplifies distinct responses to sovereign cloud requirements and certification timeline pressures.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Mitel Networks |
| RingCentral |
| NEC Corporation |
| Avaya Holdings |
| 8x8 |
| Vonage Holdings |
| Panasonic Corporation |
| Cisco Systems |
| Others |
Supply & Pricing Matrix
Enterprise procurement teams in United States federal agencies and German industrial conglomerates concentrate purchasing authority for multi-year hosted PBX deployments, locking in subscription-based pricing models that bundle compliance certification costs into per-seat rates. This buyer concentration forces providers to absorb upfront FedRAMP and GDPR audit expenses while competing on transparent operational expenditure terms.
Pricing Analysis
Uptime-guarantee pricing anchors enterprise contracts, with 99.99% SLA tiers commanding premiums over standard 99.9% offerings. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized federal deployments from HIPAA-compliant healthcare tiers and basic SME subscriptions. Cost compression in mid-market segments is intensifying because subscription fatigue drives unbundling of voice from unified communications suites. Small and medium businesses exhibit highest price sensitivity, while financial services firms in London and Singapore prioritize security certification over per-seat cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries fabricating VoIP gateway chipsets and South Korean memory suppliers providing DDR modules for data center infrastructure. Provider infrastructure draws from Chinese-manufactured networking equipment, German-engineered encryption hardware, and United States-developed SIP protocol stacks. Tariff exposure on Chinese telecommunications gear forces providers to maintain dual-sourced inventory buffers. Distribution runs through hyperscale cloud marketplaces and managed service provider channel networks rather than direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified cloud voice platform capacity remains constrained by 12-18 month FedRAMP and ISO 27001 audit timelines, propping pricing power for incumbent providers with existing authorizations. This supply bottleneck favors established players while raising barriers for new platform entrants.
For Market Incumbents: Anchor multi-tenant architecture advantages by accelerating geographic edge node deployment to satisfy EU AI Act data residency requirements. Defend against specialized security-certified specialists by deepening API integration partnerships with ERP vendors serving financial services mainframe environments. Prioritize channel control through exclusive managed service provider agreements in underpenetrated United States federal contractor verticals. For New Entrants and Emerging Players: Japanese manufacturing SMEs accessing METI subsidies represent the most penetrable buyer archetype for cloud-native platforms without legacy migration complexity. Target indirect channel expansion through telecommunications resellers in Southeast Asian maritime logistics clusters seeking distributed workforce coordination tools. Pursue WebRTC-based browser telephony as a go-to-market angle to eliminate softphone installation friction and reduce customer acquisition costs. For Investors and Strategic Acquirers: The window for entry favors security-certified specialists with existing financial services procurement relationships in London and Singapore. Long-term viability hinges on AI-powered voice analytics capabilities converging with natural language processing for real-time sentiment analysis. Watch FedRAMP authorization timeline compression as the inflection signal indicating whether regulatory bottlenecks ease or intensify competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | United States federal agencies under FITARA mandates require this certification for procurement eligibility. |
| AI-Powered Voice Analytics Integration | European healthcare providers under EU AI Act obligations demand algorithmic transparency for automated routing. |
| Indirect Channel Expansion | Managed service providers in Dallas-Fort Worth contact center clusters reduce direct sales overhead. |
| Edge Computing Architecture Deployment | German industrial conglomerates require low-latency voice processing under EU Green Deal sustainability mandates. |
| API Ecosystem Development | Financial services firms in Singapore trading floors embed click-to-call within proprietary applications. |
Research Methodology
Multi-period observation of cloud migration velocity indicators and certification timeline patterns anchored the trend analysis, supplemented by interviews with hosted PBX platform engineering directors, enterprise IT procurement officers at United States healthcare systems, telecommunications reseller channel managers, and compliance auditors specializing in FedRAMP and GDPR frameworks. Secondary validation drew from FCC net neutrality docket filings, METI subsidy program disclosures, EU AI Act implementation guidance, hyperscaler capex reports, and SEC 10-K filings from publicly traded unified communications providers. Bottom-up triangulation across service type segments converged with top-down macroeconomic scenario modeling.
Segment-weighting across the analysis window applied differential growth assumptions to cloud PBX, virtual PBX, and SIP trunking architectures while modeling organization size tiers from startups through enterprises. Deployment model distinctions between public cloud, private cloud, and hybrid configurations shaped infrastructure cost assumptions. CAGRs were derived from fitted trend extrapolation moderated by regulatory event probability assessments and technology substitution curve analysis. Voice biometric authentication adoption rates and WebRTC endpoint penetration served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC net neutrality ruling reversals, EU AI Act enforcement severity, and sovereign cloud fragmentation across data residency requirements. Forecasts reflect documented assumptions about bandwidth infrastructure investment continuity and certification body processing capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Indonesia Volte Market
Telecommunications
Cloud RAN Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Mexico Telecom Market
Telecommunications
South Africa Telecom Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Cambodia Telecom Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
Myanmar ICT Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
GPON Equipment Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
Australia Telecom Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Belgium ICT Market