
 Brazil Telecom Market | 2026-2036
Brazil Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Telecom Market Analysis
A capital-intensity divergence between national incumbents and regional challengers is redrawing the Brazil telecom landscape. Telefônica Brasil leverages its legacy infrastructure base to sustain margins in dense urban corridors. Brisanet anchors its position through aggressive fiber expansion across underserved northeastern municipalities. TIM competes on spectrum depth and 5G rollout velocity in priority metropolitan zones.
Brazil telecom encompasses voice, data, and internet service provision across fixed and mobile architectures operating on licensed radio frequencies and physical transmission media. Networks deliver connectivity through technologies spanning 4G macro cells, 5G millimeter-wave small cells, passive optical fiber nodes, and legacy copper DSL loops to residential, commercial, and institutional endpoints. Mobile services command the largest revenue pool given prepaid subscriber stickiness and smartphone penetration, while fiber optic infrastructure represents the fastest-expanding technology segment as operators replace copper plant. Enterprise plans within the subscription model dimension capture disproportionate margin contribution due to SLA-backed connectivity and managed service attachments.
ANATEL governs spectrum allocation, interconnection tariffs, and infrastructure quality standards across Brazilian telecommunications. The regulator's 5G deployment schedules and wholesale access obligations directly shape operator capex timing and rural coverage commitments. Brazil's central bank and federal revenue service coordinate digital inclusion financing mechanisms that condition market entry for regional providers. Stakeholders must track ANATEL's upcoming spectrum reframing decisions and municipal right-of-way rulings to anticipate competitive repositioning.
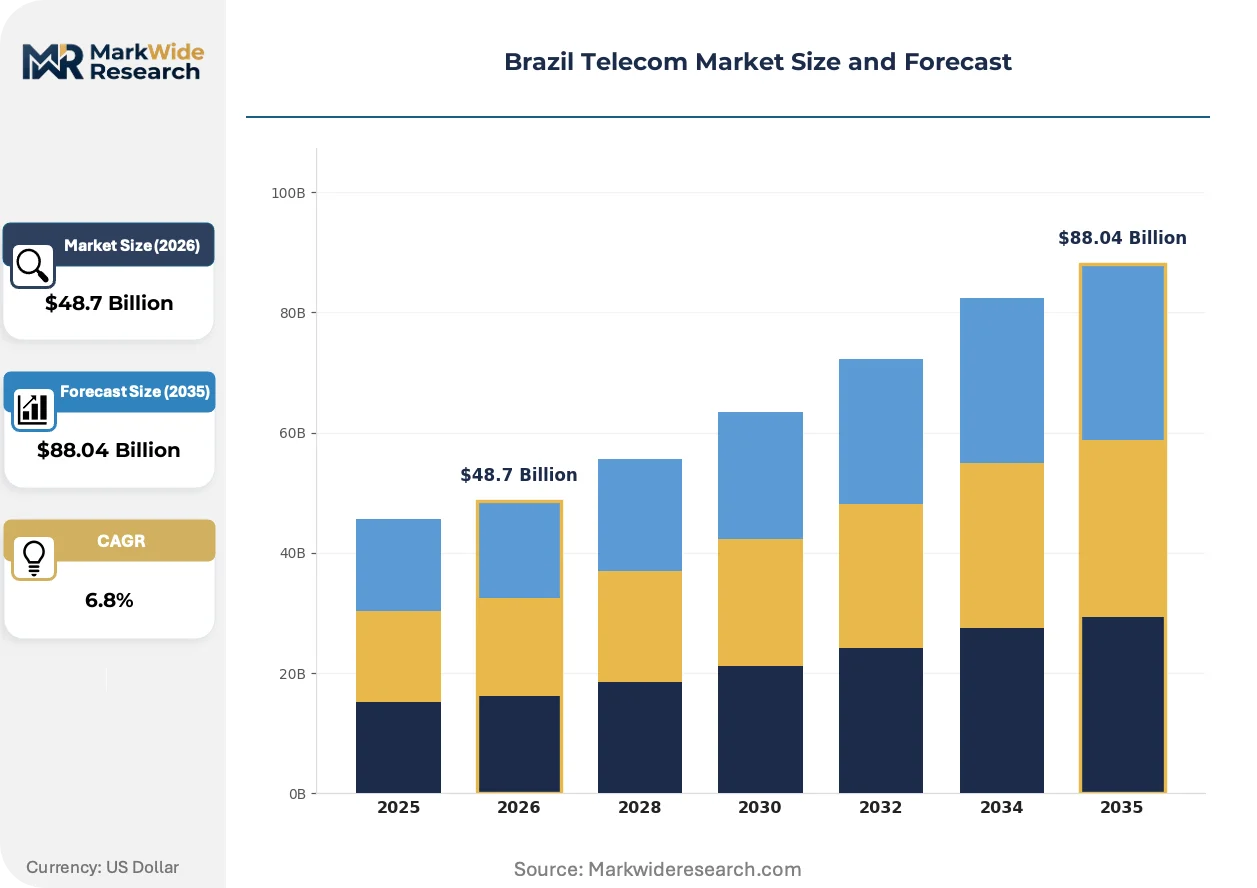
Market Dynamics
ANATEL's infrastructure sharing mandates and 5G spectrum reframing are compressing capital cycles while redistributing competitive leverage from national incumbents toward fiber-focused regional operators across Brazil's state capitals.
Growth Catalysts
- ANATEL Wholesale Access Obligations:Mandatory infrastructure sharing reduces barrier-to-entry for regional challengers entering underserved northeastern municipalities.
- Enterprise Cloud Migration:Financial services clusters in São Paulo's central business district drive SLA-backed fiber demand with managed service attachments.
- Passive Optical Network Deployment:GPON and XGS-PON technology upgrades displace legacy copper DSL loops in southeastern residential markets.
Market Restraints
- Right-of-way Municipal Friction:Disparate municipal permitting timelines delay fiber trenching in mid-sized state capitals outside priority metropolitan zones.
- Prepaid Subscriber Stickiness:Low-ARPU mobile segments resist migration to postpaid data plans, compressing revenue per user in Brazil's price-sensitive consumer base.
- Copper Plant Stranded Assets:Legacy DSL infrastructure requires ongoing maintenance expenditure while generating declining returns in fiber-competitive zones.
Strategic Opportunities
- Underserved Northeastern Expansion:Ceará, Piauí, and Maranhão state capitals present fiber greenfield opportunities with limited incumbent fiber presence.
- Smart City Infrastructure Convergence:5G small cell densification integrates with municipal IoT networks for traffic management and public safety applications.
- Digital Inclusion Financing:Federal revenue service coordinated subsidies condition market entry for regional providers serving sub-30 Mbps broadband zones.
Industry Challenges
- Optical Network Engineer Scarcity:Splicing and FTTH deployment expertise concentrates in southeastern labor markets, constraining northeastern expansion timelines.
- Multi-vendor OSS/BSS Integration:Legacy billing systems require costly middleware development to support converged fixed-mobile service bundles.
- 5G Millimeter-wave Site Acquisition:Dense urban zoning restrictions in São Paulo and Rio de Janeiro delay small cell placement in high-traffic corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Telecom Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Broadband Services, Fixed-Line Services, Data Services Technology: 4G, 5G, Fiber Optic, DSL End User: Residential, SMEs, Enterprises, Government Agencies Subscription Model: Prepaid, Postpaid, Bundled Plans, Enterprise Plans |
| Companies Covered | Algar Telecom, Brisanet, Telefônica Brasil, Desktop, Unifique Telecomunicações, TIM, Oi, Alloha, Claro Brasil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Telecom Market Emerging Trajectories
Open RAN architectures and cloud-native network functions are fragmenting vendor ecosystems while enabling disaggregated procurement models that reduce incumbent supplier lock-in across Brazilian mobile operators.
Network function virtualization is bifurcating hardware procurement from software licensing across Brazil's mobile core deployments. Tier-2 operators in Belo Horizonte and Curitiba adopt containerized packet core solutions to accelerate service velocity. This disaggregation is compressing traditional integrated vendor margins while expanding systems integrator participation in network buildouts.
ANATEL's 5G deployment schedules impose coverage milestones that synchronize capital allocation across all licensed operators. The regulator's quality-of-service benchmarking creates enforcement mechanisms for rural connectivity commitments. Priority metropolitan zones including São Paulo, Rio de Janeiro, and Brasília face accelerated small cell densification timelines under these mandates.
Enterprise procurement of connectivity services now separates network access from managed security and cloud interconnection. Large financial and industrial buyers in southeastern Brazil negotiate unbundled contracts with specialized providers rather than accepting integrated telco bundles. This unbundling is most visible in São Paulo's financial district where trading firms source ultra-low latency routes independently from commodity internet access.
Brazil Telecom Market Segmentation
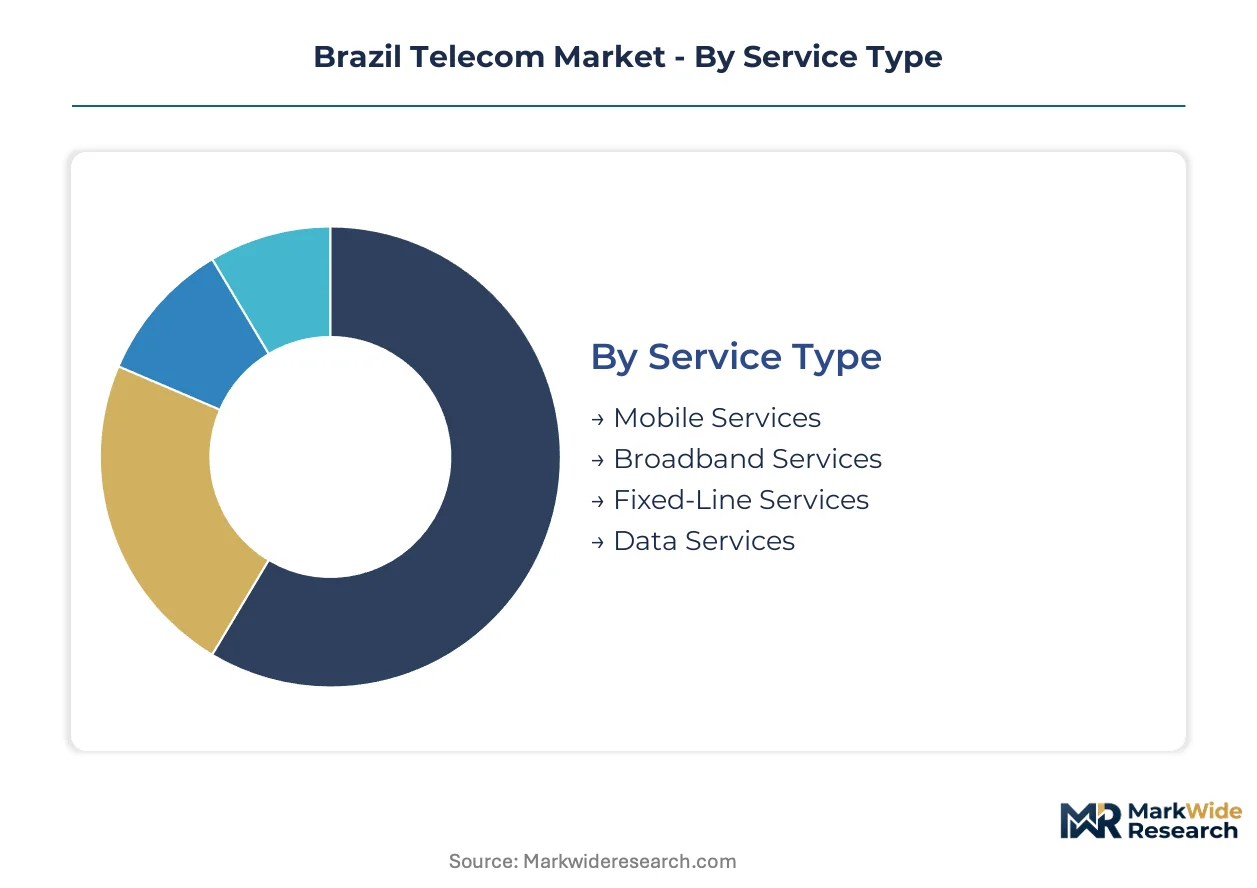
Brazil's telecom segmentation reflects ANATEL's regulatory architecture and the geographic heterogeneity of infrastructure deployment. Each dimension captures distinct competitive dynamics between national incumbents and regional challengers.
Service Type:
ANATEL's service licensing framework creates divergent margin profiles across voice, data, and internet provision. Mobile and broadband services operate under separate concession regimes with asymmetric wholesale obligations.
- Mobile Services:Prepaid subscriber bases dominate volume, with smartphone penetration driving data consumption across 4G and 5G networks. São Paulo's financial corridor concentrates enterprise mobility demand with SLA-backed connectivity requirements.
- Broadband Services:Fiber-to-the-home deployments displace legacy copper infrastructure in southeastern state capitals, with GPON and XGS-PON technology upgrades capturing residential migration. Municipal right-of-way friction constrains mid-sized city expansion timelines.
- Fixed-Line Services:Declining voice revenue pools persist in rural zones where wireless substitution lags; maintenance of stranded copper assets drains capital from fiber priorities.
- Data Services:Enterprise cloud migration accelerates consumption of dedicated connectivity and managed service attachments across Brazil's central business districts.
Mobile Services handles the majority of subscriber throughput; Broadband Services is the fastest mover on share.
Technology:
Network generation and physical media choices determine capital intensity and geographic reach. ANATEL's spectrum reframing and infrastructure sharing mandates redistribute deployment economics across technologies.
- 5G:Millimeter-wave small cell densification targets priority metropolitan zones under regulatory coverage milestones. São Paulo and Rio de Janeiro face accelerated site acquisition challenges from dense urban zoning restrictions.
- Fiber Optic:Passive optical network deployment concentrates in southeastern residential markets, with splicing expertise scarcity constraining northeastern expansion timelines. Brisanet anchors fiber expansion across Ceará and Piauí municipalities.
- 4G:Macro cell infrastructure sustains prepaid subscriber stickiness in price-sensitive consumer segments; spectrum depth determines competitive positioning in secondary cities.
- DSL:Legacy copper loops generate declining returns in fiber-competitive zones while requiring ongoing maintenance expenditure; stranded asset risk concentrates in incumbent balance sheets.
Fiber Optic absorbs the largest share of new capital deployment; 5G climbs the fastest on network investment priority.
End User:
Customer scale and procurement sophistication segment pricing power and service bundling complexity. Enterprise buyers unbundle network access from managed security and cloud interconnection.
- Enterprises:Large financial and industrial buyers negotiate unbundled contracts with specialized providers rather than accepting integrated telco bundles. Trading firms in São Paulo source ultra-low latency routes independently from commodity internet access.
- SMEs:Small and medium enterprises present fragmented demand across Brazil's state capitals; bundled fixed-mobile offerings simplify procurement for businesses with limited IT staff.
- Residential:Price sensitivity dominates subscription decisions; prepaid mobile stickiness resists migration to postpaid data plans in low-ARPU segments.
- Government Agencies:Public sector procurement operates under digital inclusion financing mechanisms coordinated by federal revenue service; coverage mandates prioritize sub-30 Mbps broadband zones.
Enterprises command the highest margin per connection; SMEs present the steepest expansion trajectory for converged service bundles.
Subscription Model:
Payment structure and contract terms segment customer lifetime value and churn risk. ANATEL's quality-of-service benchmarking creates enforcement mechanisms across all model types.
- Enterprise Plans:SLA-backed connectivity with managed service attachments captures disproportionate margin contribution. Cloud migration in São Paulo's financial district drives demand for dedicated fiber with performance guarantees.
- Prepaid:Low-ARPU mobile segments dominate subscriber counts in Brazil's price-sensitive consumer base; churn rates exceed postpaid equivalents while requiring minimal credit infrastructure.
- Postpaid:Contract terms reduce churn and enable handset financing integration; smartphone penetration drives data plan upsell opportunities in urban corridors.
- Bundled Plans:Fixed-mobile convergence simplifies billing and reduces customer acquisition costs; legacy OSS/BSS integration challenges constrain regional operator deployment.
Enterprise Plans generate the highest revenue per user; Bundled Plans gain share fastest as operators pursue convergence economics.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Brazil's sub-regions. Southeastern metropolitan buyers absorb premium fiber and 5G services with limited price sensitivity, while northeastern and northern markets remain tethered to low-ARPU prepaid mobile plans.
São Paulo
Enterprise cloud migration and high-frequency trading infrastructure dominate fiber consumption in the state's financial corridor. ANATEL's quality-of-service benchmarking enforces strict latency standards for SLA-backed connections. São Paulo city anchors Brazil's densest small cell deployment, though municipal zoning restrictions delay millimeter-wave site acquisition.
Rio de Janeiro
Tourism-dependent commercial districts and port logistics clusters drive converged fixed-mobile demand along the coastal corridor. The state's environmental licensing requirements extend fiber trenching timelines through Atlantic Forest preservation zones. Rio de Janeiro city concentrates 5G macro cell densification under federal coverage mandates.
Minas Gerais
Mining sector automation and agribusiness telemetry generate specialized connectivity requirements across the state's industrial interior. ANATEL's rural coverage obligations condition spectrum license renewals for operators serving Belo Horizonte's metropolitan periphery. The capital city anchors southeastern fiber backhaul interconnection.
Bahia
Port modernization and offshore energy logistics create enterprise connectivity demand in Salvador's industrial zone. Federal digital inclusion financing mechanisms coordinate subsidy flows for sub-30 Mbps broadband zones across the state's interior municipalities. The capital city represents the northeastern anchor point for national fiber backbone extension.
Ceará
Underserved municipal markets present greenfield fiber opportunities with limited incumbent infrastructure presence. ANATEL's infrastructure sharing mandates reduce barrier-to-entry for regional challengers entering Fortaleza's metropolitan area. The capital city anchors Brisanet's northeastern expansion cluster.
Brazil Telecom Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in Brazil's telecom structure. National incumbents leverage legacy infrastructure bases and spectrum depth to sustain margins in dense urban corridors. Regional challengers exploit infrastructure sharing obligations to penetrate underserved municipalities with fiber-first strategies. Competitive moves center on fiber trenching acceleration in priority state capitals and 5G small cell densification under regulatory coverage milestones.
Among Brazil-based operators, Telefônica Brasil, TIM, and Brisanet occupy distinct archetype positions. Telefônica Brasil exemplifies the integrated incumbent model, anchoring southeastern metropolitan markets through legacy infrastructure leverage. TIM represents spectrum-depth competition, positioning around 5G rollout velocity in priority zones. Brisanet sits within the regional challenger archetype, exploiting infrastructure sharing mandates to penetrate northeastern fiber greenfields.
| Leading Market Players |
|---|
| Algar Telecom |
| Brisanet |
| Telefônica Brasil |
| Desktop |
| Unifique Telecomunicações |
| TIM |
| Oi |
| Alloha |
| Claro Brasil |
| Others |
Supply Flow & Price Mechanics
Passive optical network equipment replacing legacy copper DSL infrastructure simultaneously shifts procurement geography toward Asian optical component manufacturers and compresses per-port pricing economics for Brazilian operators. This substitution dynamic concentrates vendor bargaining power among fiber equipment suppliers while eroding margins on stranded copper assets.
Pricing Analysis
Managed service attachments and SLA-backed enterprise support contracts drive lifetime customer value beyond commodity connectivity fees. Three-tier pricing structure across premium, standard, and economy levels segments residential, SME, and enterprise buyers, with price differentiation resting on fiber proximity and guaranteed latency performance. Cost compression in prepaid mobile tiers is intensifying because regional challengers undercut national incumbents in northeastern municipalities. Residential subscribers exhibit highest price sensitivity; financial services buyers in São Paulo's trading corridor demonstrate minimal elasticity.
Supply Chain Analysis
China, South Korea, and Japan anchor optical transceiver and GPON equipment manufacturing for Brazilian network deployments. Fiber optic cable draws from Chinese glass preform suppliers, South Korean laser diode foundries, and Japanese precision splicing equipment makers. Single-source vulnerability concentrates in millimeter-wave 5G radio units where US-China trade restrictions constrain vendor diversification. Distribution runs through systems integrators and direct OEM relationships with ANATEL-certified operators.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's telecom market functions as a service-attach opportunity where managed security, cloud interconnection, and SLA-backed support layers expand faster than underlying bandwidth commoditization. Enterprise procurement unbundling accelerates recurring revenue capture for specialized providers.
For Market Incumbents: Secure fiber backhaul dominance in southeastern state capitals through accelerated XGS-PON deployment ahead of regional challenger trenching timelines. Consolidate OSS/BSS platforms to reduce middleware costs from converged fixed-mobile bundling. TIM and Telefônica Brasil must anchor vertical integration into submarine cable landing stations to control international bandwidth costs against emerging wholesale competitors. For New Entrants and Emerging Players: Enterprise cloud interconnection gaps in Belo Horizonte and Curitiba's industrial corridors offer white-space penetration where national incumbents under-serve latency-sensitive manufacturing automation. Target Ceará and Piauí municipalities with fiber-first greenfield builds exploiting ANATEL infrastructure sharing mandates. Go-to-market leverage rests on municipal digital inclusion financing qualification and direct enterprise sales bypassing incumbent distribution. For Investors and Strategic Acquirers: Capital is best deployed toward regional fiber specialists with proven trenching velocity in ANATEL-designated underserved zones and established municipal right-of-way relationships. Long-term viability hinges on consolidation economics as infrastructure sharing mandates compress standalone operator margins. Watch ANATEL's spectrum reframing timeline as inflection signal for mobile asset valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Infrastructure Expansion | GPON and XGS-PON deployments displace copper DSL in southeastern state capitals under ANATEL quality mandates. |
| 5G Small Cell Densification | Millimeter-wave site acquisition in São Paulo and Rio de Janeiro satisfies regulatory coverage milestones. |
| Enterprise Service Unbundling | Trading firms source ultra-low latency routes independently from commodity internet access bundles. |
| Infrastructure Sharing Partnership | ANATEL wholesale access obligations reduce barrier-to-entry for regional challengers in northeastern municipalities. |
| Digital Inclusion Financing Qualification | Federal revenue service subsidies condition market entry for providers serving sub-30 Mbps broadband zones. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of ANATEL regulatory filings, operator capex disclosures, and municipal digital inclusion program documentation. Interviews with network engineering directors, enterprise procurement managers at financial services firms, and optical equipment distribution channel heads inform deployment timeline assumptions. Secondary validation draws from ANATEL spectrum auction records, federal revenue service subsidy allocation data, and infrastructure quality benchmarking reports. Bottom-up subscriber and revenue modeling triangulates against top-down market sizing from regulatory revenue aggregates.
Segmentation dimensions modeled include service type, network technology generation, end-user scale, and subscription payment structure across the analysis window. CAGRs derive from equipment deployment trajectories, subscriber migration patterns between prepaid and postpaid tiers, and enterprise service attachment rates. Forecast inputs incorporate ANATEL coverage milestone schedules, municipal right-of-way permitting velocity, and optical network engineer labor market constraints in northeastern expansion zones.
Forecasts assume regulatory continuity in ANATEL's infrastructure sharing and spectrum allocation regimes; material policy shifts would require re-modeling competitive entry economics and rural coverage commitment valuations. Specific risks include municipal permitting delays, spectrum reframing timeline acceleration, and trade restriction impacts on 5G radio equipment sourcing. Recalibration cycles align with material shifts in ANATEL regulatory mandates and federal digital inclusion financing allocation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Cellular Modem Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Egypt ICT Market
Telecommunications
Turkey Telecom Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Indonesia Telecom Market
Telecommunications
MVNO Market
Telecommunications
Europe Telecom Expense Management Market
Telecommunications
Global Esim Market
Telecommunications
5G System Integration Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Iran Telecom Market
Telecommunications
Cloud PBX Market
Telecommunications
5G RAN Market
Telecommunications
Norway Telecom Market