
 TV White Space Spectrum Market | 2026-2036
TV White Space Spectrum Market Size, Share, and Industry Trends Forecast 2026-2036
TV White Space Spectrum Market Outlook
Software-defined spectrum management is repositioning what network operators purchase in the TV White Space Spectrum Market. Microsoft Corporation leverages its Airband cloud architecture to coordinate dynamic spectrum access across multiple African deployments. Alphabet Inc. anchors its competitive stance through Taara wireless optical bridges that integrate with TVWS backhaul in India and sub-Saharan Africa. Adaptrum Inc. specializes in chip-level cognitive radio designs that sustain low-cost baseband processing for rural equipment manufacturers.
TV White Space Spectrum comprises unused VHF and UHF television broadcast frequencies, typically 54–698 MHz, that cognitive radio systems access dynamically through geolocation databases and spectrum sensing to avoid interference with licensed broadcasts. These frequencies propagate over long distances and penetrate obstacles, making them suitable for last-mile broadband in rural zones and machine-to-machine IoT networks in agricultural settings. Cognitive Radio technology leads deployment architecture due to its real-time interference mitigation capabilities, while Smart Agriculture applications represent the fastest-expanding demand segment as precision farming systems require wide-area, low-cost telemetry links. Managed Services deployments concentrate margin pools with system integrators who bundle database access, equipment provisioning, and ongoing spectrum coordination for government and educational clients.
The FCC's TV Band Device rules and the European Conference of Postal and Telecommunications Administrations' harmonized 470–694 MHz framework shape equipment certification requirements and cross-border interoperability standards. Kenya's Communications Authority and India's Wireless Planning and Coordination Wing impose additional database registration protocols that filter which vendors qualify for national rural broadband tenders. Stakeholders must monitor evolving national spectrum auctions and database governance models to anticipate where unlicensed TVWS access expands or contracts against licensed 5G mid-band allocations.
Market Dynamics
Software-defined spectrum management is compressing equipment procurement cycles as network operators shift from hardware-centric to database-coordinated deployments. Dynamic frequency allocation via cloud-based geolocation services is displacing static channel planning, forcing vendors to bundle managed spectrum coordination with physical infrastructure.
Growth Catalysts
- FCC Part 15 Rules:Unlicensed TV band device certification timelines have shortened, accelerating equipment market entry for rural broadband manufacturers targeting underserved counties.
- Smart Agriculture Telemetry:Precision farming systems in Kenya and Malawi are pulling low-cost wide-area connectivity for soil sensors and irrigation controls.
- East African Community Network Projects:Kenya's Communications Authority database registration protocols are channeling development finance into TVWS last-mile deployments.
Market Restraints
- Geolocation Database Dependency:Single-point database failures in India and sub-Saharan Africa create operational fragility for networks running dynamic spectrum access.
- Mid-Band 5G Substitution:Licensed cellular allocations in the 3.5 GHz band are capturing institutional buyers who prioritize guaranteed interference protection over unlicensed cost savings.
- Silicon Supply Concentration:Cognitive radio baseband processors depend on concentrated foundry capacity in East Asia, exposing equipment vendors to input cost volatility.
Strategic Opportunities
- IoT Convergence with LoRa:Hybrid TVWS-LoRaWAN architectures are opening meter-scale agricultural monitoring in Nigeria's cocoa belt where cellular backhaul remains uneconomical.
- Educational Institution Bundling:India's state-level digital education mandates are creating procurement channels for managed services integrators who package database access with device provisioning.
- European 470–694 MHz Harmonization:CEPT's cross-border interoperability framework is enabling equipment vendors to design single-SKU products for multi-country educational and utility networks.
Industry Challenges
- Cognitive Radio Engineering Talent Scarcity:Real-time spectrum sensing algorithm development requires specialized RF-digital hybrid expertise that concentrates in Bangalore and Shenzhen hiring pools.
- Multi-Database Certification Complexity:Vendors must validate hardware against Kenya's Communications Authority, India's WPC, and FCC protocols simultaneously, extending product launch timelines.
- Legacy Broadcast Protection Coordination:Incumbent television operators in Malawi and Nigeria demand conservative exclusion zone calculations that reduce available white space capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TV White Space Spectrum Market |
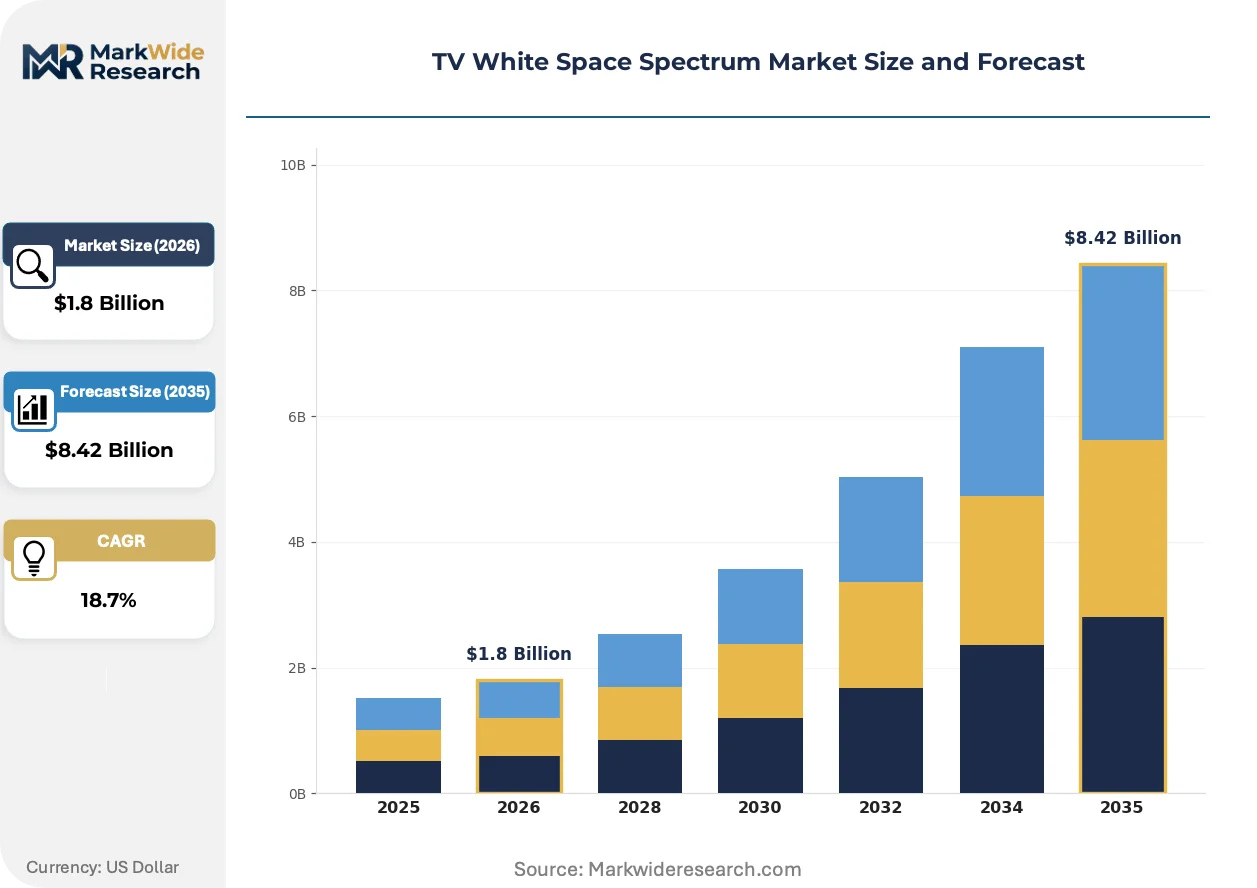
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cognitive Radio, LTE, Wi-Fi, IoT Application: Rural Connectivity, Smart Agriculture, Telemedicine, Smart Grid End User: Telecommunications Providers, Government Agencies, Educational Institutions, Enterprises Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Microsoft Corporation, Alphabet Inc., Adaptrum Inc., Carlson Wireless Technologies Inc., 6Harmonics Inc., Aviacomm Inc., Keybridge LLC, Spectrum Bridge Inc., Shared Spectrum Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TV White Space Spectrum Market Strategic Shifts
Cloud-native spectrum coordination is displacing on-premise database installations, compressing deployment timelines for rural network operators. This architectural shift is reshaping vendor business models toward recurring software revenue.
Machine-learning interference prediction is automating real-time channel selection in agricultural IoT networks. Kenyan tea cooperatives are adopting these systems for plantation-wide sensor backhaul. The technology is automating what previously required manual spectrum engineering, reducing operational headcount for community network operators.
India's Wireless Planning and Coordination Wing is tightening database governance protocols for white space device registration. Equipment vendors must now demonstrate end-to-end encryption of geolocation queries before receiving type approval. Agricultural equipment manufacturers in Maharashtra and Karnataka are responding by pre-integrating certified modem modules rather than developing proprietary radio designs.
Educational procurement authorities are consolidating rural broadband tenders into multi-year managed service contracts. State governments in Nigeria and Kenya are displacing capital-heavy equipment purchases with subscription models bundling connectivity, maintenance, and spectrum coordination. This pattern is most visible in East African school district rollouts where annual operating budgets exceed available infrastructure capital.
TV White Space Spectrum Market Segmentation
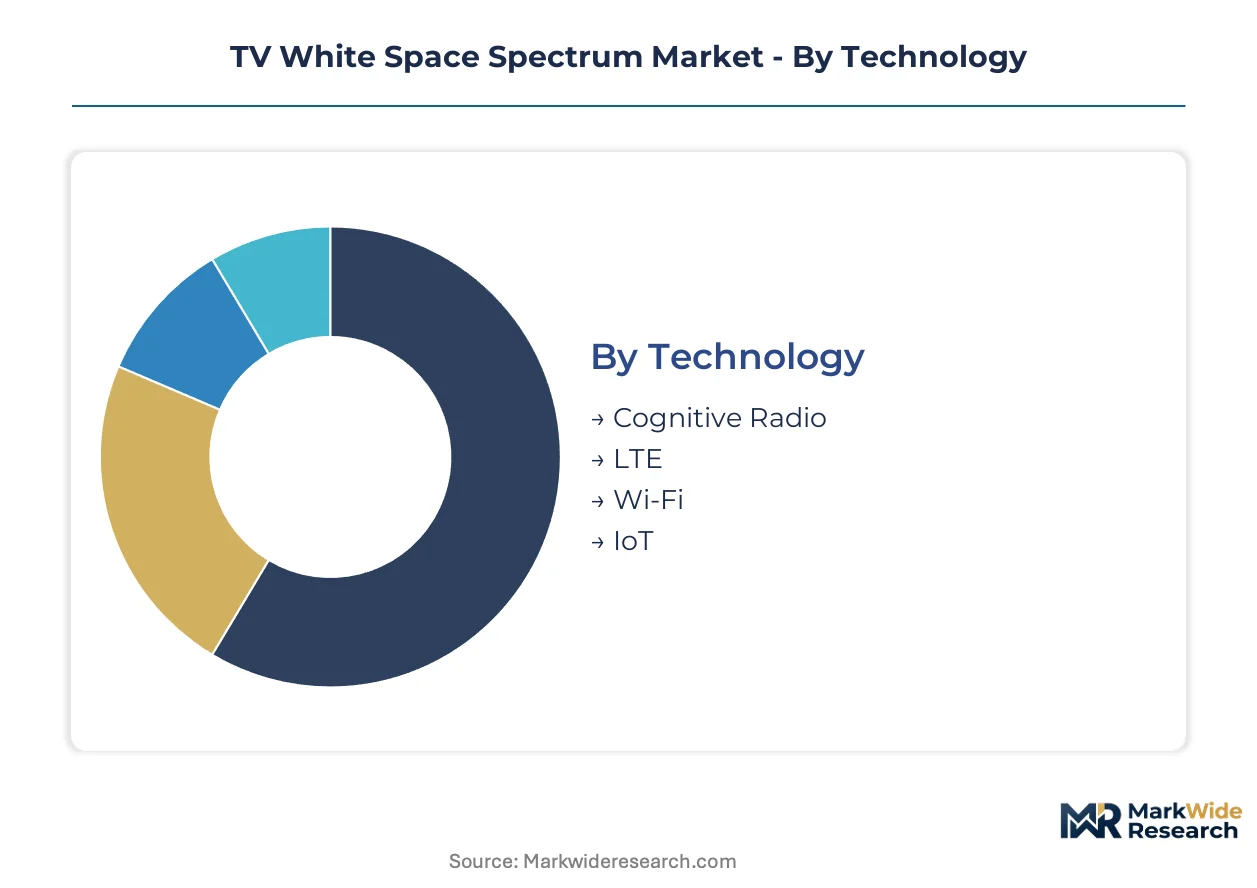
TV White Space Spectrum deployments fragment across multiple technical and commercial dimensions. Procurement patterns diverge sharply between rural connectivity mandates and precision agriculture telemetry, while deployment architecture choices determine recurring revenue potential for equipment vendors.
Technology:
Upgrade cycles in TVWS equipment are shortening as database-coordinated spectrum access displaces fixed-channel hardware. Cognitive radio platforms now refresh every 3-4 years versus 7-year replacement horizons for static radio designs.
- Cognitive Radio:Dynamic spectrum access systems integrate real-time geolocation database queries with automated interference avoidance algorithms. Kenyan tea cooperatives and Malawi community networks concentrate procurement here, driven by regulatory mandates for broadcast protection in dense VHF/UHF markets.
- LTE:Modified cellular basebands operate in TVWS bands using carrier aggregation techniques adapted from licensed spectrum. Nigerian telecommunications providers favor this architecture for subscriber density in peri-urban zones where 3.5 GHz backhaul remains uneconomical.
- Wi-Fi:Extended-range 802.11af/ah standards enable kilometer-scale coverage in sub-GHz channels. Indian state education departments deploy these for school district connectivity.
- IoT:Narrowband cognitive radio modules support low-rate telemetry for soil sensors and irrigation controllers. Maharashtra agricultural equipment manufacturers pre-integrate certified modems.
Cognitive Radio sits at the top of the volume ranking, with IoT climbing the fastest as precision farming expands sensor density.
Application:
Cost tiering separates capital-intensive rural broadband infrastructure from operational telemetry subscriptions. Smart Agriculture commands premium per-node pricing despite lower absolute contract values.
- Rural Connectivity:Last-mile broadband deployments leverage TVWS propagation advantages for obstacle penetration and long-distance links. Kenya's Communications Authority database protocols channel development finance into these projects, with community network operators prioritizing low total cost of ownership over peak throughput.
- Smart Agriculture:Precision farming systems require wide-area, low-cost telemetry for soil moisture, weather stations, and automated irrigation. Nigerian cocoa belt cooperatives and Kenyan tea plantations drive demand here, substituting TVWS for uneconomical cellular backhaul in dispersed cultivation zones.
- Telemedicine:Remote diagnostic connectivity for rural clinics demands guaranteed bandwidth for imaging transmission. Indian state health departments bundle these requirements into digital health mandates.
- Smart Grid:Utility distribution automation uses TVWS for meter reading and fault detection in areas lacking fiber infrastructure. Sub-Saharan African power authorities pilot these applications.
Rural Connectivity maintains the steepest expansion trajectory in absolute terms, though Smart Agriculture gains share fastest on a percentage basis.
End User:
Customer type determines contract structure and margin capture. Government and educational procurement consolidates into multi-year managed services, while enterprise buyers favor equipment ownership.
- Telecommunications Providers:Licensed operators deploy TVWS for rural network extension where licensed spectrum acquisition costs prove prohibitive. East African carriers concentrate investment in Kenya and Nigeria.
- Government Agencies:Universal service obligations and rural digital inclusion mandates drive procurement. India's Wireless Planning and Coordination Wing database governance shapes vendor qualification requirements.
- Educational Institutions:State-level digital education mandates in Nigeria and Kenya create subscription-based procurement channels. Operating budgets exceed available capital for infrastructure purchase.
- Enterprises:Agricultural conglomerates and mining operations deploy private TVWS networks for site-wide connectivity. Maharashtra and Karnataka manufacturing clusters show emerging interest.
Telecommunications Providers dominate current volume, with Educational Institutions expanding most quickly as subscription models displace capital expenditure.
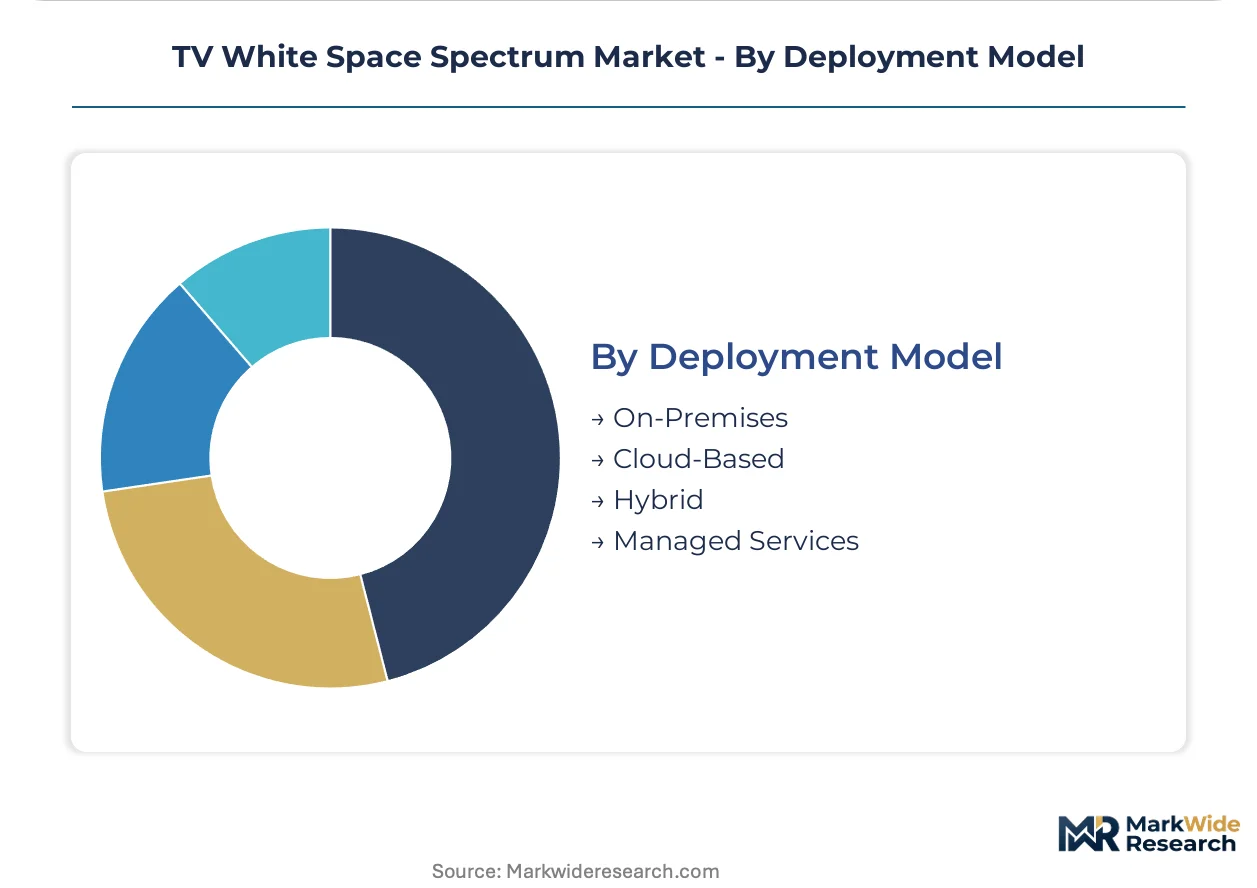
Deployment Model:
Supply concentration in cloud-native spectrum coordination is compressing on-premise database margins. Managed services bundles capture recurring revenue from operators lacking in-house RF engineering.
- On-Premises:Local database installations serve operators in jurisdictions with data sovereignty requirements or unreliable international connectivity. Limited to specialized regulatory environments.
- Cloud-Based:Geolocation-as-a-service architectures reduce deployment timelines and operational headcount. Microsoft's Airband cloud coordination exemplifies this model across African deployments.
- Hybrid:Edge caching with cloud fallback balances latency sensitivity against cost optimization. Emerging preference for mission-critical agricultural telemetry.
- Managed Services:System integrators bundle database access, equipment provisioning, and ongoing spectrum coordination. Nigerian and Kenyan educational tenders increasingly specify this structure.
Managed Services commands the highest growth rate, while Cloud-Based deployments lead in unit volume among new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya's rural connectivity mandates are accelerating faster than India's regulatory certification timelines, creating divergent procurement patterns across East African and South Asian deployment corridors.
United States
FCC Part 15 rules compress equipment certification timelines for rural broadband manufacturers. The Commission's TV Band Device framework enables unlicensed operation across 54–698 MHz with geolocation database coordination. Equipment vendors cluster in Silicon Valley and Austin metro areas where RF engineering talent concentrates for cognitive radio development.
Kenya
Community network operators in tea-growing highlands drive demand for last-mile broadband infrastructure. The Communications Authority's database registration protocols channel development finance into TVWS deployments. Nairobi-based system integrators bundle managed services for educational institutions under state digital inclusion mandates.
India
Maharashtra and Karnataka agricultural equipment manufacturers pre-integrate certified modem modules for precision farming telemetry. The Wireless Planning and Coordination Wing mandates end-to-end encryption of geolocation queries for type approval. State education departments in Tamil Nadu and Gujarat deploy extended-range Wi-Fi for school district connectivity.
Nigeria
Telecommunications providers extend rural networks into cocoa belt cooperatives where cellular backhaul remains uneconomical. National regulators impose database governance protocols that filter vendor qualification for broadband tenders. Lagos-based ISPs partner with international technology initiatives to coordinate dynamic spectrum access across peri-urban zones.
Malawi
Legacy broadcast protection demands from incumbent television operators reduce available white space capacity through conservative exclusion zone calculations. Smallholder farming cooperatives adopt low-cost sensor networks for irrigation control and soil monitoring. Blantyre community network operators prioritize total cost of ownership over peak throughput in procurement decisions.
TV White Space Spectrum Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with cloud-native coordination platforms capturing recurring revenue while hardware vendors compete on certification speed. The vendor base concentrates around three strategic archetypes: technology conglomerates with cloud infrastructure assets, specialized cognitive radio chip designers, and regional system integrators bundling managed services. Dominant competitive moves include strategic partnerships with national regulators for database governance contracts and geographic expansion through local ISP alliances in East African markets.
Within the technology conglomerate tier, Microsoft Corporation and Alphabet Inc. occupy positions defined by cloud coordination scale and optical bridge integration respectively. Adaptrum Inc. exemplifies the specialized component archetype, anchoring low-cost baseband processing capabilities for equipment manufacturers targeting price-sensitive rural deployments. These three entities collectively represent the spectrum spanning infrastructure coordination, hybrid wireless architectures, and silicon-level cognitive radio design.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Alphabet Inc. |
| Adaptrum Inc. |
| Carlson Wireless Technologies Inc. |
| 6Harmonics Inc. |
| Aviacomm Inc. |
| Keybridge LLC |
| Spectrum Bridge Inc. |
| Shared Spectrum Company |
| Others |
Value Chain & Pricing Dynamics
Educational procurement mandates in Kenya and Nigeria are compressing equipment margins as subscription-based managed services displace capital purchases, forcing manufacturers to absorb upfront costs and recover through multi-year database access fees.
Pricing Analysis
Capacity additions in Shenzhen and Bangalore are reshaping price floors for cognitive radio baseband processors. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified equipment from regional variants and unlicensed modules. Price differentiation hinges on database registration tier and after-sales spectrum coordination bundling. Cost compression in the economy tier intensifies as agricultural equipment manufacturers pre-integrate certified modems rather than develop proprietary designs. Educational institutions in East Africa exhibit highest price sensitivity due to operating budget constraints, while mining enterprises in Maharashtra show lowest sensitivity where site-wide private networks justify premium hardware.
Supply Chain Analysis
Regional distribution centers in Nairobi and Lagos coordinate hub-and-spoke patterns for East African deployments. Cognitive radio equipment draws from concentrated foundry capacity in Taiwan, South Korea, and mainland China. Raw material dependencies span silicon wafers, RF front-end components, and precision passive elements. Single-source vulnerability in baseband processor supply exposes vendors to input cost volatility. Distribution runs through certified system integrators who bundle hardware with database governance compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement committees now prioritize end-to-end encryption certification and multi-database interoperability over raw hardware specifications.
For Market Incumbents: Anchor defensive positioning through backward integration into cloud-native spectrum coordination platforms. Deepen database governance contracts with Kenya's Communications Authority and India's Wireless Planning and Coordination Wing to create switching costs. Accelerate certification investment against evolving encryption mandates before mid-band 5G substitution accelerates in institutional accounts. For New Entrants and Emerging Players: Machine-learning interference prediction algorithms offer the most penetrable wedge against established cloud coordination providers. Target Malawi's smallholder farming cooperatives where legacy broadcast protection demands have suppressed incumbent capacity deployment. Pursue go-to-market partnerships with Maharashtra agricultural equipment manufacturers seeking pre-certified modem integration. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cognitive radio chip designers possessing validated multi-database certification stacks. Long-term viability favors vendors who control both silicon-level baseband processing and recurring spectrum coordination revenue streams. Watch for inflection signals in Indian state-level digital education tender consolidation toward multi-year managed service structures.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Database Certification Investment | Accelerates market entry across Kenya, India, and Nigeria regulatory environments simultaneously. |
| Cloud-Native Spectrum Coordination Platform | Captures recurring revenue from community network operators lacking in-house RF engineering. |
| Agricultural Equipment Manufacturer Partnership | Locks in pre-certified modem volumes for Maharashtra and Karnataka precision farming deployments. |
| Educational Institution Managed Services Bundle | Aligns procurement structure with Nigerian and Kenyan state digital inclusion budget cycles. |
| Machine-Learning Interference Prediction Development | Automates channel selection for Kenyan tea cooperatives reducing operational headcount requirements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned RF engineering directors at equipment manufacturers, procurement leads at East African telecommunications providers, database governance officers at national regulators, and agricultural cooperative managers deploying sensor networks. Secondary validation drew from FCC equipment authorization databases, Kenya Communications Authority white space registrations, India's Wireless Planning and Coordination Wing type approval records, and equipment vendor SEC disclosures. Bottom-up deployment tracking across community network operators triangulated against top-down spectrum allocation forecasts.
Comparable historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions spanned technology architecture, application vertical, end-user procurement model, and deployment coordination approach. CAGRs derived from fitted growth curves adjusted for regulatory milestone timing and database governance protocol adoption rates. Forecast inputs incorporated silicon foundry capacity utilization trends and educational tender pipeline visibility.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to mid-band 5G spectrum auction results and broadcast protection rule recalibrations. Outputs reflect documented assumptions regarding database interoperability standardization and agricultural IoT sensor density trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
China ICT Market
Telecommunications
Singapore MVNO Market
Telecommunications
Myanmar Telecom Market
Telecommunications
LTE and 5G NR-Based CBRS Networks Market
Telecommunications
Turkey Telecom Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Australia Telecom Market
Telecommunications
Global Telecommunication Market
Telecommunications
Bahrain Telecom Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
LTE Base Station System Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
Iceland Telecom Market
Telecommunications
Russia Telecom Market