
 South Africa Telecom Tower Market | 2026-2036
South Africa Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Telecom Tower Market Insights
South Africa's tower build-out in the Eastern Cape and Limpopo provinces is narrowing the rural-urban connectivity divide. IHS Towers leverages its scale to dominate co-location services across these regions. Helios Towers competes through energy-efficient designs that reduce diesel dependency at off-grid sites. American Tower Corporation anchors its position with urban rooftop portfolios in Johannesburg and Cape Town.
A telecom tower is a steel or concrete structure engineered to heights between 30 and 150 meters, designed to host multiple antenna arrays, transmission equipment, and power systems for wireless communication networks. Its primary purpose is to extend radio frequency coverage across geographic terrain while enabling shared infrastructure access among competing service providers. Lattice towers occupy the largest share of installed base owing to load-bearing capacity for multi-tenant configurations, while monopole designs represent the fastest-growing category as municipalities tighten zoning restrictions on visual clutter. Greenfield deployments concentrate margin pools where first-movers secure long-term lease agreements with mobile operators rolling out 5G infrastructure.
ICASA governs spectrum allocation and tower licensing under South Africa's Electronic Communications Act, while the Department of Communications and Digital Technologies coordinates universal service obligations that mandate rural coverage targets. BIS standards govern structural integrity and wind-load specifications for steel lattice fabrication, creating compliance barriers for imported tower kits. SABS certification requirements for electrical safety and lightning protection shape procurement criteria among mobile operators. Stakeholders must weigh tower-sharing obligations against the capital intensity of independent power systems as grid reliability fluctuates across provinces.
Market Dynamics
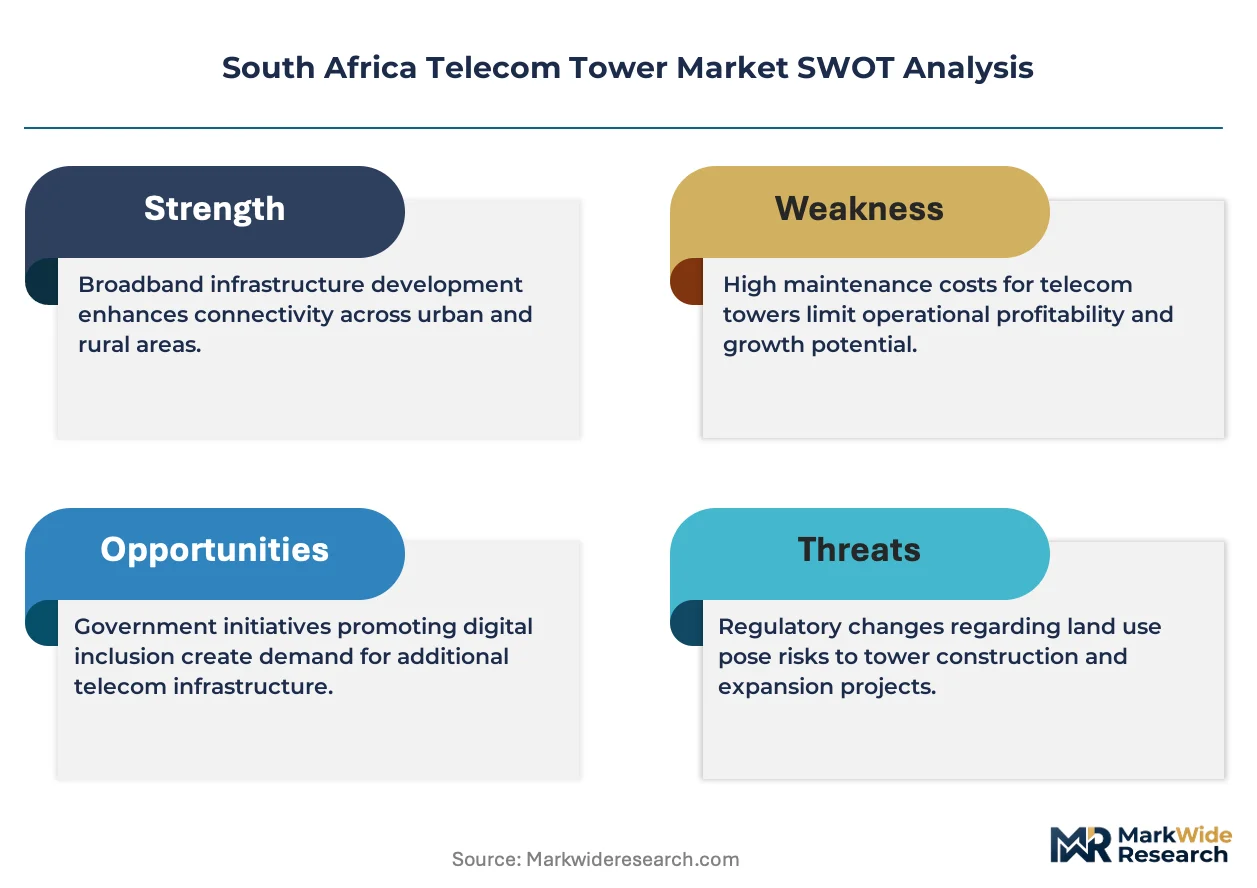
ICASA's spectrum licensing reforms are compressing deployment timelines for 5G-ready infrastructure, forcing tower operators to accelerate co-location negotiations and fiber backhaul integration ahead of auction deadlines.
Growth Catalysts
- Universal Service Obligations:The Department of Communications and Digital Technologies mandates rural coverage targets that direct capital toward Eastern Cape and Limpopo provinces. Operators must build or lease tower capacity to meet these binding commitments.
- LTE-Advanced Proliferation:Mobile network operators require densified macro sites and small cell overlays to support data traffic growth in Gauteng and Western Cape urban corridors. Tower demand tracks directly with radio access network modernization cycles.
- Fiber Backhaul Integration:Deep fiber penetration in metropolitan clusters enables higher-capacity antenna configurations. Tower sites with existing fiber connectivity command premium lease rates and faster tenant onboarding.
Market Restraints
- Steel Price Volatility:Lattice tower fabrication depends on hot-rolled steel coil imports subject to exchange rate fluctuations and global supply tightness. Input cost swings compress margin visibility on fixed-price construction contracts.
- SABS Certification Delays:Electrical safety and lightning protection approvals for imported tower kits extend procurement cycles by 8-14 weeks. Foreign manufacturers face compliance barriers that domestic fabricators exploit.
- Diesel Dependency at Off-Grid Sites:Grid reliability failures in rural provinces force tower operators to maintain dual-generator backup systems. Fuel logistics and theft elevate operating expenditure at locations outside Eskom's stable distribution network.
Strategic Opportunities
- Renewable Energy Hybridization:Solar-battery systems paired with existing diesel generators reduce fuel consumption at remote tower sites. ICASA's environmental compliance guidelines incentivize green power adoption through accelerated licensing for low-carbon infrastructure.
- Co-Location Service Expansion:Multi-tenant tower configurations generate recurring revenue streams with minimal incremental capital. First-movers in underserved municipalities secure long-term lease agreements before competitor build-outs saturate available zoning permits.
- Edge Computing Proximity:Tower real estate adjacent to fiber termination points supports distributed data center deployments. Mobile operators and cloud providers seek rack space for latency-sensitive applications in Johannesburg and Cape Town metro rings.
Industry Challenges
- Skilled Rigger Shortage:Certified tower climbing technicians and RF engineers are concentrated in Gauteng, forcing operators to relocate crews or pay premium wages for rural deployments. Training pipeline expansion lags infrastructure construction schedules.
- Legacy Equipment Interoperability:New 5G massive MIMO antenna arrays require structural reinforcement and power upgrades at existing 3G/4G sites. Retrofit complexity extends site commissioning timelines and triggers renegotiation of ground lease terms.
- Municipal Zoning Fragmentation:Visual impact assessments and height restrictions vary across metropolitan boundaries. Cape Town's stricter aesthetic guidelines favor monopole designs that carry lower load capacity than lattice alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Telecom Tower Market |
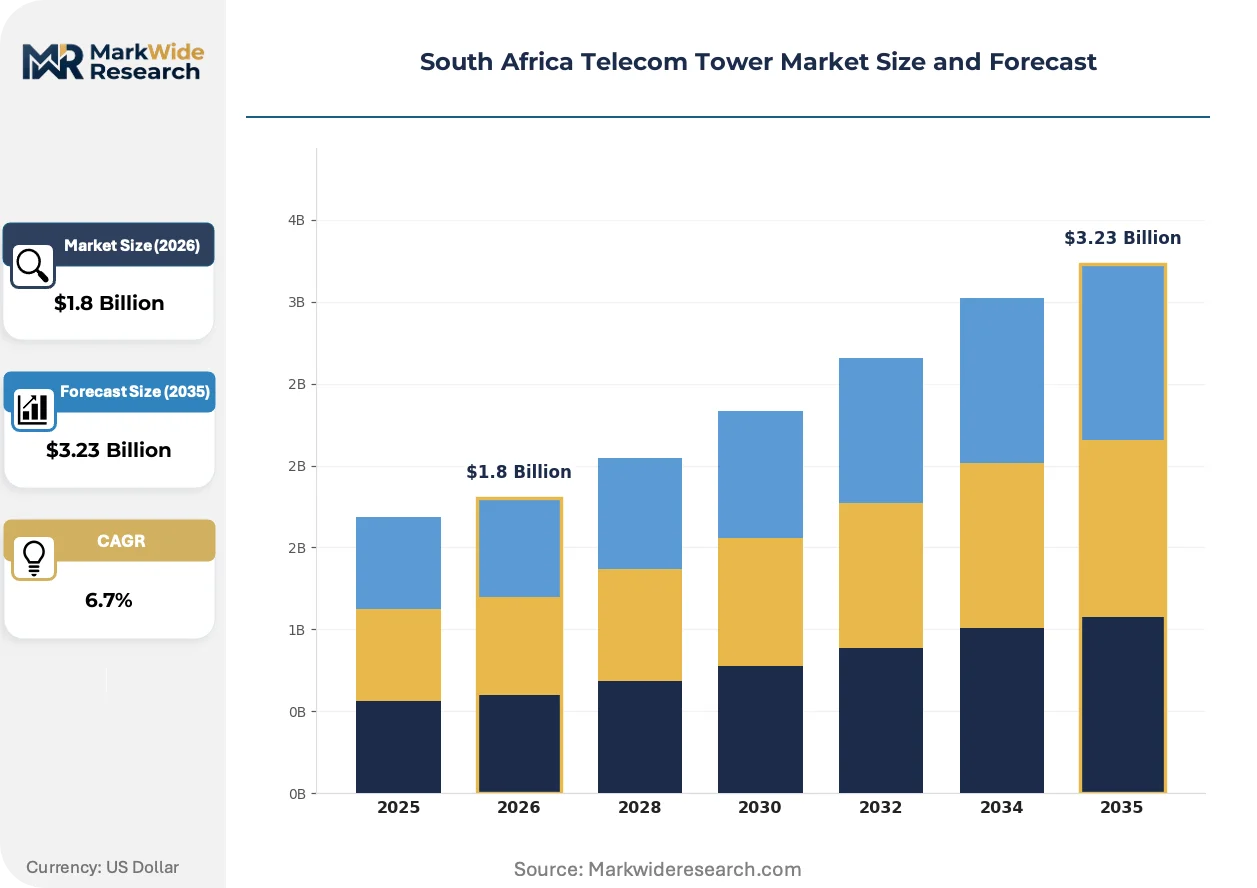
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tower Type: Monopole, Lattice, Guyed, Rooftop End User: Mobile Operators, Internet Service Providers, Broadcasting Companies, Government Agencies Deployment Type: Greenfield, Brownfield, Urban, Rural Technology: 4G LTE, 5G, WiMAX, Fiber Backhaul |
| Companies Covered | IHS Towers, Helios Towers, American Tower Corporation, Blue-Sky Towers, Eagle Towers, MTN Group, Vodacom Group, Telkom SA SOC Ltd, Eskom Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Telecom Tower Market Trends and Innovations
Active antenna systems and intelligent power management are compressing total cost of ownership for tower operators while reshaping competitive positioning around energy efficiency rather than pure site count.
Massive MIMO active antenna units consolidate multiple radio functions into integrated arrays that eliminate separate remote radio head installations. Mobile operators in Johannesburg and Pretoria are deploying these units at 60% of new macro sites. The technology is rendering obsolete traditional passive antenna configurations that required separate feeder cable runs and tower-mounted amplifiers.
ICASA's revised Electronic Communications Act implements infrastructure-sharing mandates that compel operators to disclose tower availability data. The regulation accelerates co-location negotiations and reduces redundant greenfield construction in dense urban markets. Tower companies are responding by standardizing lease templates and pre-certifying sites for multi-tenant configurations ahead of formal tenant inquiries.
Enterprise buyers now contract for managed tower services that bundle passive infrastructure with active monitoring and preventive maintenance. Mobile operators are displacing in-house site management teams with outsourced agreements that transfer operational risk. This shift is most visible in Western Cape, where Vodacom and MTN have consolidated vendor relationships to three primary tower partners.
South Africa Telecom Tower Market Segmentation
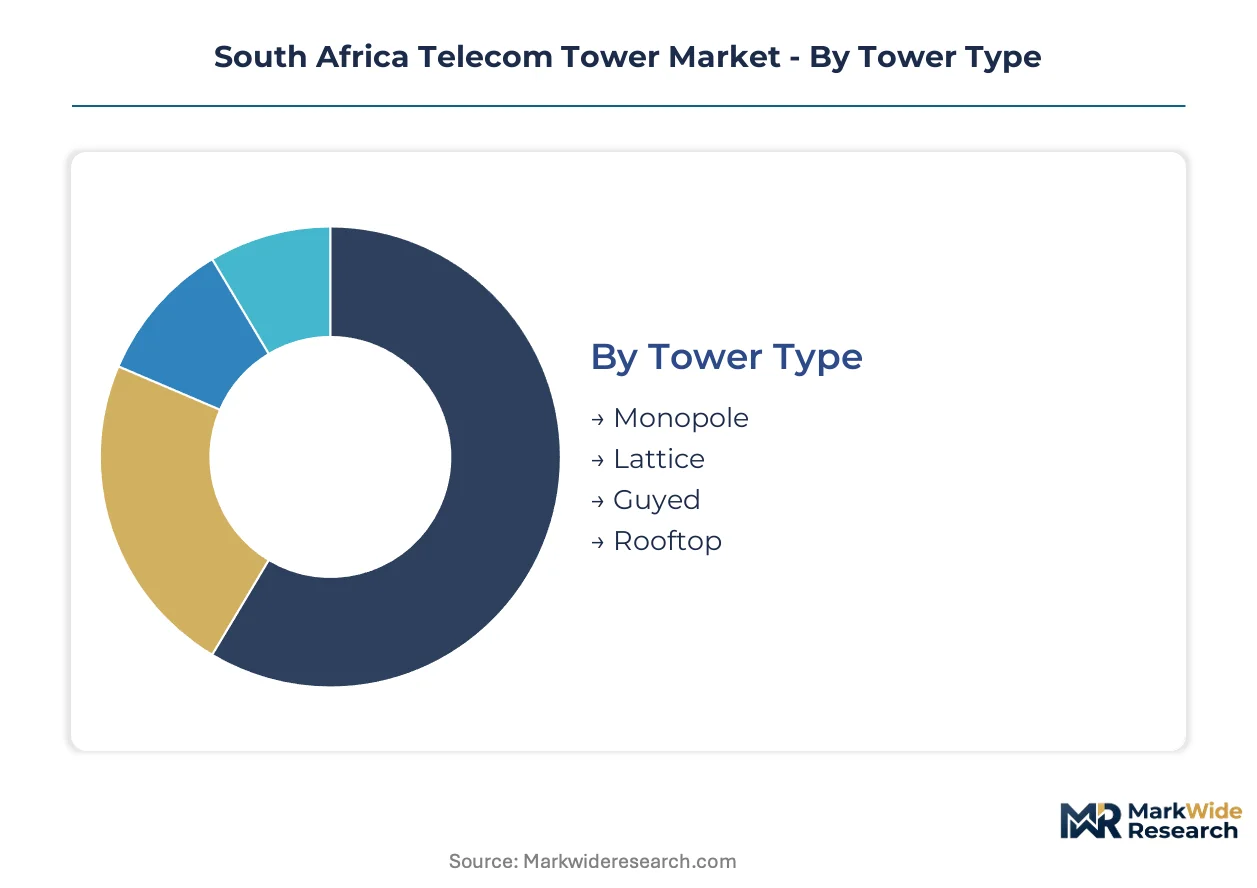
Tower configuration choices in South Africa directly determine maintenance schedules, spare parts inventory, and technician certification requirements. Each segment carries distinct after-sales service intensity profiles that shape vendor profitability and operator total cost of ownership calculations.
Tower Type:
After-sales service intensity varies sharply by structural design, with lattice towers demanding continuous weld inspection and guyed towers requiring tension monitoring protocols that monopole installations avoid entirely.
- Lattice:Triangular or square steel frameworks assembled from bolted angle sections support heavy multi-tenant antenna loads. Demand concentrates in Gauteng mining corridors and Eastern Cape logistics hubs where load-bearing capacity outweighs aesthetic concerns. Maintenance contracts emphasize structural weld inspection cycles and hot-dip galvanization touch-ups.
- Monopole:Single tubular steel shafts minimize visual footprint for municipal zoning compliance. Cape Town and Johannesburg metropolitan councils favor these designs despite lower tenant capacity. After-sales intensity focuses on foundation settlement monitoring and flange bolt torque verification.
- Guyed:Masts stabilized by tensioned cable arrays reduce steel tonnage for equivalent height. Deployment clusters in Limpopo agricultural zones where capital constraints favor material efficiency over land footprint.
- Rooftop:Building-integrated installations leverage existing structures in dense urban cores. Cape Town CBD and Sandton financial district deployments require waterproofing warranty management and landlord coordination services.
By volume, lattice towers lead. By growth pace, monopole designs are expanding most quickly.
End User:
Customer type dictates contract structure, with mobile operators demanding 99.999% uptime SLAs while government buyers prioritize local content quotas over performance guarantees.
- Mobile Operators:Vodacom, MTN, and Cell C drive bulk procurement through master lease agreements that bundle passive infrastructure with active equipment hosting. These contracts carry penalty clauses for downtime exceeding 26 minutes annually.
- Internet Service Providers:Fixed-wireless access providers deploy smaller-footprint towers for last-mile connectivity in peri-urban zones. Procurement emphasizes rapid site activation over long-term structural warranties.
- Broadcasting Companies:SABC and community radio stations require specialized transmission equipment accommodation with electromagnetic interference shielding. Tower specifications prioritize height over multi-tenant flexibility.
- Government Agencies:Provincial emergency services and defense procurement channels favor domestic fabrication certificates and BEE compliance scoring over technical performance metrics.
Mobile operators dominate installed base volume. Government agencies are gaining share fastest as universal service obligations expand.
Deployment Type:
Site development pathway determines capital recovery timelines and regulatory exposure, with greenfield builds carrying 18-24 month permitting cycles versus brownfield upgrades that leverage existing leaseholds.
- Greenfield:New tower construction on previously undeveloped land captures premium lease rates through first-mover positioning. Eastern Cape and Limpopo provinces concentrate these deployments where baseline infrastructure is sparse.
- Brownfield:Structural reinforcement and power upgrades at existing 2G/3G sites accommodate 5G massive MIMO arrays. Retrofit complexity triggers renegotiation of ground lease terms with property owners.
- Urban:Metro deployments face municipal zoning fragmentation with Cape Town enforcing stricter visual impact assessments than Johannesburg or Pretoria.
- Rural:Off-grid sites outside Eskom's stable distribution network require diesel-solar hybrid power systems with fuel logistics management contracts.
Brownfield upgrades lead by volume. Rural greenfield builds are climbing the fastest as coverage obligations tighten.
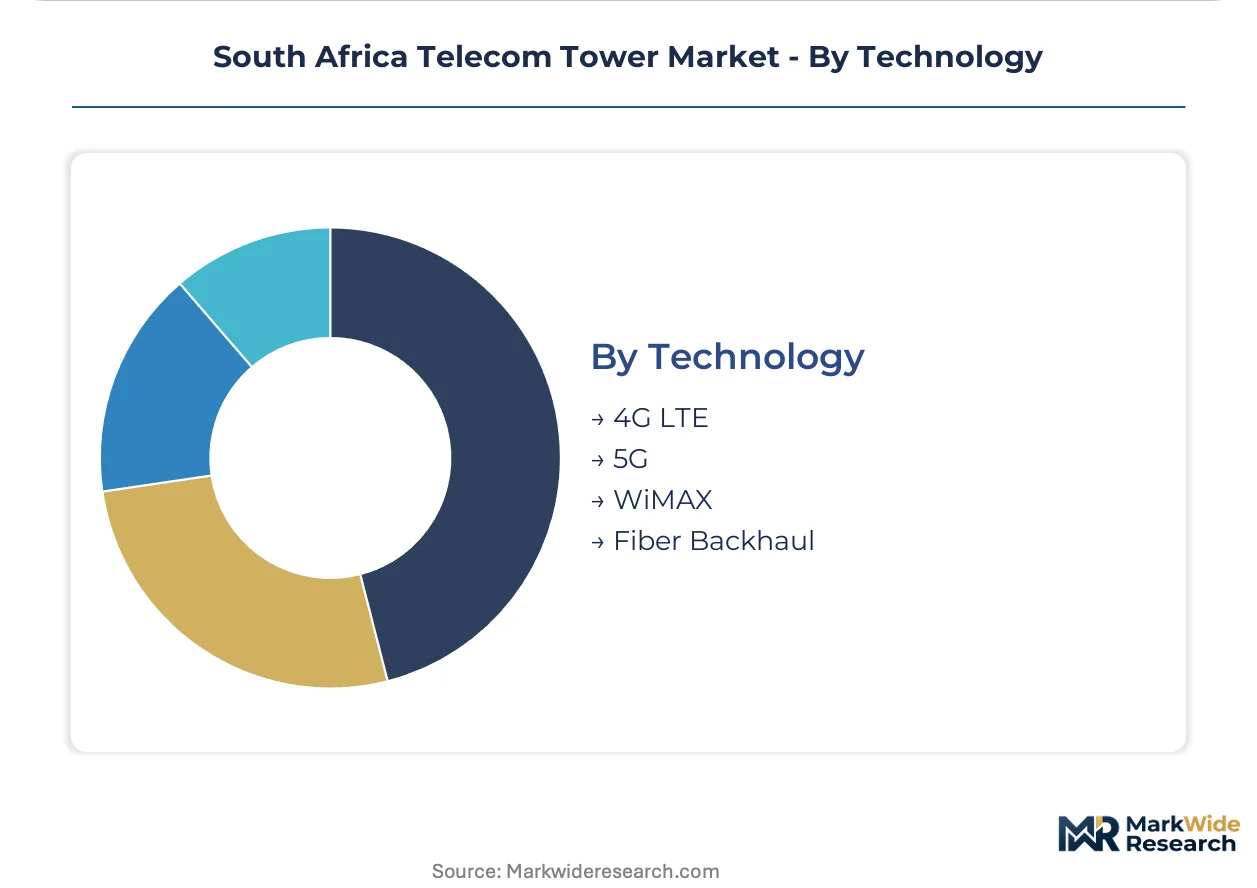
Technology:
Radio access generation and backhaul architecture determine antenna configuration density and power draw profiles that cascade into tower structural requirements.
- 5G:Massive MIMO active antenna units consolidate radio functions into integrated arrays weighing 40-60% more than legacy passive configurations. Johannesburg and Pretoria metro rings concentrate these deployments.
- 4G LTE:Densified macro sites and small cell overlays sustain data traffic growth in established coverage areas. Tower demand tracks directly with radio access network modernization cycles.
- WiMAX:Fixed broadband wireless access technology retains niche deployment in mining camp and remote industrial connectivity applications.
- Fiber Backhaul:Deep fiber penetration enables higher-capacity antenna configurations at co-located sites. Tower sites with existing fiber connectivity command premium lease rates.
4G LTE dominates current installed base. 5G infrastructure is gaining share fastest as ICASA's spectrum reforms compress deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Maputo Corridor rail-freight link and submarine cable landings at Mtunzini anchor South Africa's position as southern Africa's digital infrastructure hub.
Gauteng
Johannesburg and Pretoria concentrate 5G massive MIMO deployments driven by Vodacom and MTN network densification. ICASA's spectrum auction deadlines compress site commissioning timelines to 90 days. Sandton financial district towers now host edge computing racks for low-latency fintech applications.
Western Cape
Cape Town metropolitan zoning restrictions favor monopole designs over lattice structures for visual compliance. The city's stricter aesthetic guidelines trigger higher foundation engineering costs. Atlantic Seaboard fiber backhaul integration supports premium lease rates at Sea Point and Green Point tower clusters.
Eastern Cape
Rural coverage obligations under the Department of Communications and Digital Technologies mandate tower build-outs in Mthatha and Gqeberha corridors. IHS Towers leverages scale advantages to secure long-term co-location agreements. Grid reliability failures force diesel-solar hybrid power systems at 60% of new sites.
Limpopo
Polokwane and Tzaneen logistics hubs drive demand for heavy-load lattice towers serving mining camp connectivity. BIS structural certification requirements create procurement barriers for imported steel kits. Local fabricators exploit SABS approval delays to defend domestic market share.
KwaZulu-Natal
Durban port automation and Richards Bay industrial zones require tower-mounted private LTE networks. Eskom's unstable rural distribution network elevates operating expenditure at off-grid sites. eThekwini municipality streamlines permitting for camouflaged monopole installations in coastal tourism zones.
South Africa Telecom Tower Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying structural steel and power systems. The market consolidates around three tower operators controlling co-location infrastructure, while mobile network operators retain captive portfolios. Strategic archetypes include scale-driven independent tower companies, energy-efficient design specialists, and mobile operator captive units. Dominant competitive moves involve co-location service expansion and renewable energy hybridization at off-grid sites.
Among independent tower operators, IHS Towers and Helios Towers occupy positions as scale-driven platform integrators, while American Tower Corporation anchors the premium urban portfolio tier. These three exemplify divergent geographic strategies: IHS concentrates rural build-outs in Eastern Cape and Limpopo, Helios competes through energy-efficient tower designs reducing diesel dependency, and American Tower holds concentrated rooftop positions in Johannesburg and Cape Town metropolitan cores. Mobile operator captive units including MTN Group and Vodacom Group retain strategic control over fiber-interconnected urban sites while outsourcing rural passive infrastructure to independent partners.
| Leading Market Players |
|---|
| IHS Towers |
| Helios Towers |
| American Tower Corporation |
| Blue-Sky Towers |
| Eagle Towers |
| MTN Group |
| Vodacom Group |
| Telkom SA SOC Ltd |
| Eskom Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
Hot-rolled steel coil imports from China and India anchor tower fabrication economics, concentrating upstream margin capture with integrated mills while downstream pricing power fragments across domestic fabricators competing for SABS-certified procurement contracts.
Pricing Analysis
ICASA's infrastructure-sharing mandates under the Electronic Communications Act dictate the pricing tier structure for co-location services. Three-tier pricing structure across premium, standard, and economy levels separates fiber-interconnected urban sites with edge-computing readiness from rural off-grid locations with diesel dependency, with brownfield retrofit sites occupying the middle tier. Price differentiation hinges on BIS structural certification grade and after-sales service bundling that includes preventive maintenance and uptime guarantees. Cost compression in standard-tier rural deployments is intensifying because mobile operators consolidate vendor relationships to three primary tower partners. Government agencies exhibit highest price sensitivity due to BEE compliance scoring priorities, while mobile operators prioritize 99.999% uptime SLAs over unit cost.
Supply Chain Analysis
Domestic steel fabricators in Gauteng and KwaZulu-Natal hold contract-manufacturing capacity for lattice tower kits, while specialized monopole fabrication concentrates with Western Cape suppliers serving municipal zoning requirements. Raw material dependencies draw from Chinese hot-rolled steel coil, South African galvanized angle sections, and imported lightning protection systems. Single-source vulnerability runs through SABS certification bottlenecks that extend procurement cycles for foreign manufacturers. Distribution runs through mobile operator master lease agreements that bundle passive infrastructure with active equipment hosting, displacing spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Satellite-based direct-to-device connectivity poses a substitution threat that tower operators must navigate by hardening their fiber-interconnected site portfolios against latency-sensitive application migration.
For Market Incumbents: Pre-empt satellite displacement by securing long-term ground lease extensions at Johannesburg and Cape Town fiber termination points where edge computing proximity creates switching costs. Fortify position through backward integration into solar-battery hybrid power systems that reduce diesel dependency at Eastern Cape and Limpopo rural sites. ICASA's environmental compliance guidelines provide licensing acceleration leverage for low-carbon infrastructure investments that satellite operators cannot replicate. For New Entrants and Emerging Players: Pursue white-space opportunities in Limpopo agricultural zone guyed tower deployments where capital-constrained mining camp connectivity favors material-efficient designs over load-heavy lattice alternatives. Target eThekwini municipality camouflaged monopole installations where streamlined permitting for coastal tourism zones reduces zoning fragmentation barriers. Go-to-market angle should emphasize rapid site activation contracts that displace incumbent maintenance-heavy service models. For Investors and Strategic Acquirers: Capital is best deployed toward independent tower operators with concentrated rural greenfield exposure in Eastern Cape and Limpopo provinces where universal service obligations guarantee long-term lease visibility. Acquisition archetype favors scale-driven platform integrators with existing SABS certification pipelines and established mobile operator master lease relationships. Signal to watch is ICASA spectrum auction timing that compresses co-location negotiation windows and accelerates tenant onboarding velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Hybridization | Solar-battery systems at off-grid sites reduce diesel consumption and accelerate ICASA licensing timelines. |
| Co-Location Service Expansion | Multi-tenant configurations generate recurring revenue with minimal incremental capital in underserved municipalities. |
| Fiber Backhaul Integration | Tower sites with existing fiber connectivity command premium lease rates and faster tenant onboarding. |
| Edge Computing Proximity | Real estate adjacent to fiber termination points supports distributed data center deployments for fintech applications. |
| Certification Pipeline Investment | SABS approval capabilities create procurement barriers that domestic fabricators exploit against imported kits. |
Research Methodology
Cross-validation between tower operator procurement directors and mobile network engineering executives anchors the qualitative findings on co-location contract structures and 5G deployment timelines. Primary interviews with ICASA regulatory affairs leads, SABS certification officers, and Eskom distribution planning engineers combine with secondary validation from Electronic Communications Act amendments, BIS structural standards documentation, and mobile operator annual sustainability disclosures. Bottom-up site-level capacity modeling and top-down market sizing triangulate volume estimates across the projection horizon.
Calibration against historical tower deployment data and mobile operator capex disclosures ensures forecast robustness across the analysis window. Segmentation dimensions modeled include tower type configuration, end user contract structure, deployment pathway, and radio access generation technology. CAGRs derive from regression analysis of infrastructure investment cycles correlated with spectrum licensing timelines and universal service obligation mandates. Forecast inputs incorporate diesel price volatility assumptions and grid reliability indices by province.
Sensitivities concentrate around ICASA spectrum auction timing revisions, steel import tariff adjustments, and Eskom load-shedding intensity fluctuations that alter hybrid power system economics. Forecasts reflect documented assumptions regarding mobile operator consolidation of vendor relationships and municipal zoning enforcement consistency. Quarterly review of SABS certification queue lengths, mobile operator master lease renegotiation activity, and satellite direct-to-device service launches is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Smart SIM Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Global 5G Services Market
Telecommunications
Australia Telecom Tower Market
Telecommunications
C-RAN Market
Telecommunications
Singapore Telecom Market
Telecommunications
5G Monetization Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
Global Esim Market
Telecommunications
Transport Stream Switching Market