
 Vitamin Yeast Market | 2026-2036
Vitamin Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin Yeast Market Insights
Chinese yeast extract producers is repositioning capacity toward vitamin-fortified nutritional grades. Angel Yeast leverages state-run fermentation infrastructure to dominate domestic supply. Lesaffre Group anchors European production through French bioreactor networks. Lallemand competes in North American specialty strains with proprietary drying protocols.
Vitamin yeast comprises Saccharomyces cerevisiae and related species cultivated on molasses or grain-derived substrates, then inactivated and fortified with B-complex vitamins including B12, riboflavin, and folate for human and animal nutrition applications. Nutritional yeast leads product type demand among vegan protein seekers, while animal feed application captures the fastest volume growth as livestock producers phase out synthetic vitamin premixes under EFSA and FDA feed additive reviews. Powder form occupies the dominant share in industrial procurement, though capsules gain traction in pharmaceutical firm contracts requiring precise dosing.
FDA feed additive regulations and EFSA novel food assessments shape product approval timelines across Atlantic markets, while China's SAMR enforces GB standards on yeast-derived fortification in domestic food manufacturing. India's FSSAI recently tightened labeling requirements for B12-fortified products, redirecting importer compliance spending toward analytical certification. Stakeholders must monitor divergent regulator timelines between synthetic vitamin restrictions and yeast-natural positioning claims.
Market Dynamics
EFSA and FDA feed additive reviews are accelerating livestock producer migration from synthetic vitamin premixes to yeast-derived alternatives, compressing approval timelines and reshaping procurement specifications across Atlantic markets.
Growth Catalysts
- EFSA Fortification Guidelines:Updated European assessments for B12 and riboflavin fortification in nutritional yeast strains are expanding permissible health claims and opening new product positioning for dietary supplement manufacturers in Germany and France.
- Molasses Substrate Optimization:Advanced fermentation process controls are improving vitamin B-complex yield per batch and reducing production variability for Saccharomyces cerevisiae cultivators.
- Livestock Sector Reformulation Mandates:Poultry and swine operations across the Netherlands and Denmark are phasing out synthetic vitamin K3 and B12 premixes under animal welfare and residue monitoring protocols.
Market Restraints
- Molasses Price Volatility:Brazilian sugarcane harvest fluctuations and Indian ethanol diversion policies are creating input cost instability for yeast fermentation facilities dependent on blackstrap molasses supply.
- Bioreactor Capacity Concentration:European production gravity centers on French and German fermentation networks, creating supply vulnerability during regional energy price spikes or maintenance cycles.
- Regulatory Divergence Friction:China's SAMR GB standards for yeast-derived fortification differ materially from EFSA novel food assessment pathways, forcing dual certification investments for cross-border suppliers.
Strategic Opportunities
- India Feed Application Expansion:FSSAI's tightened B12 labeling requirements are redirecting importer compliance spending toward analytical certification partnerships, creating first-mover advantage for yeast-natural positioning.
- Capsule Pharmaceutical Channel:Precision dosing requirements from pharmaceutical firm contracts are displacing bulk powder procurement in North American and European markets.
- Dual Carbon Alignment:China's fermentation infrastructure investments under national dual carbon goals are subsidizing energy-efficient bioreactor upgrades for vitamin yeast producers.
Industry Challenges
- Analytical Certification Talent Scarcity:B12 quantification and folate verification expertise is concentrated among specialized third-party laboratories, creating bottlenecks for FSSAI and SAMR compliance documentation.
- Legacy Synthetic Premix Integration:Livestock feed mills face formulation recalibration costs and ration reformulation delays when substituting yeast-natural vitamin complexes for established synthetic premixes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin Yeast Market |
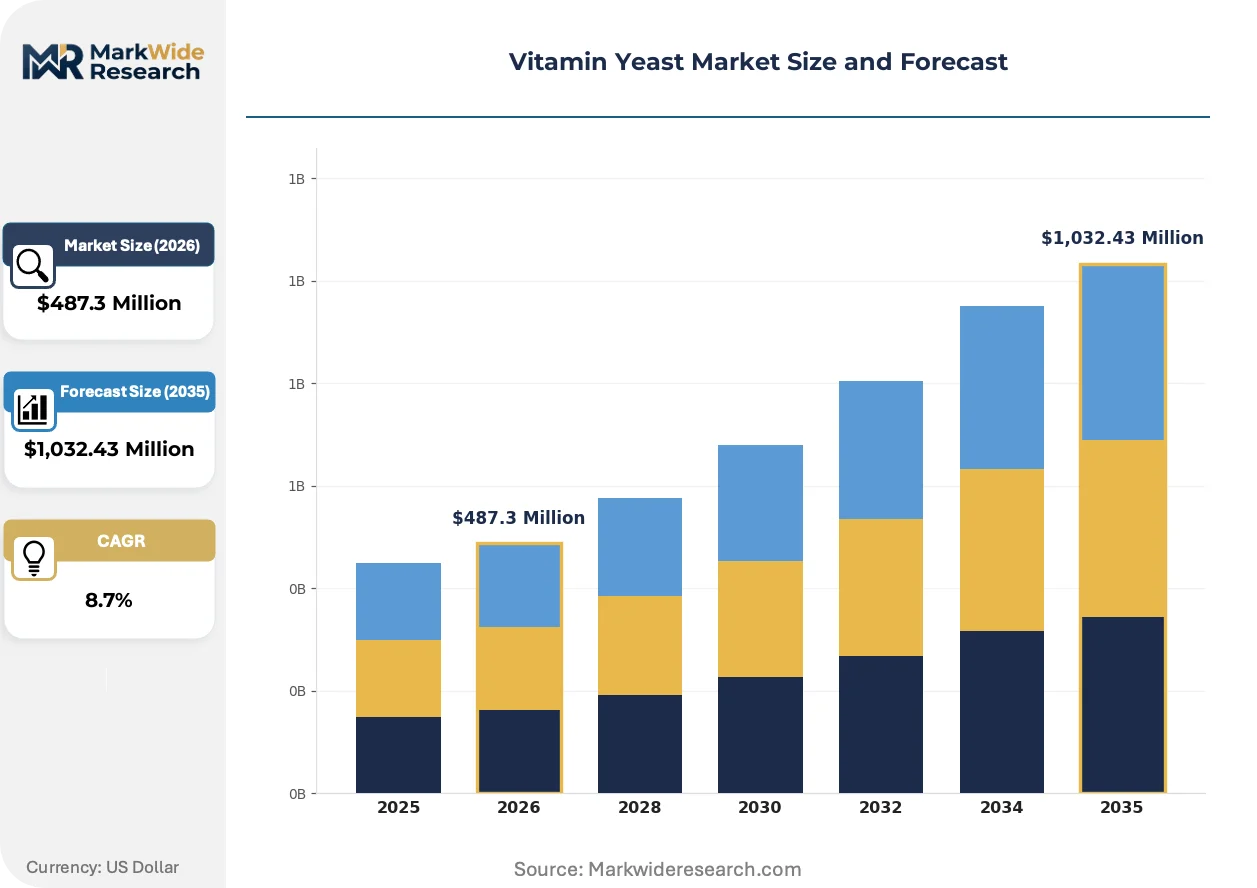
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutritional Yeast, Brewers Yeast, Baker's Yeast, Torula Yeast Application: Food Fortification, Animal Feed, Dietary Supplements, Pharmaceuticals, Cosmetics Form: Powder, Flakes, Tablets, Capsules End User: Food & Beverage Manufacturers, Animal Nutrition Companies, Pharmaceutical Firms, Personal Care Brands |
| Companies Covered | Angel Yeast, Lesaffre Group, Lallemand, ABF Ingredients, Archer Daniels Midland, Kerry Group, Alltech, Oriental Yeast, Now Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin Yeast Market Trends and Innovations
Spray-drying protocol refinements and continuous fermentation monitoring systems are compressing production variability and enabling real-time vitamin potency adjustments. These technical advances are converging with regulatory pressure on synthetic alternatives.
Continuous fermentation monitoring with dissolved oxygen and pH feedback loops is consolidating quality control into upstream process stages. Nutritional yeast manufacturers in France and Germany are adopting these systems to reduce batch rejection rates. The technology is consolidating final product testing requirements and shortening release timelines for pharmaceutical-grade contracts.
EFSA's updated novel food assessment pathways for vitamin-fortified yeast extracts are compressing approval timelines for new strain introductions. The regulatory shift is forcing competitors to front-load toxicology and bioavailability documentation. Animal feed applications in the Netherlands and Denmark are responding fastest, with several producers already submitting consolidated dossiers for B12-enhanced strains.
Direct contracting between yeast extract producers and pharmaceutical capsule manufacturers is displacing distributor-mediated bulk powder sales. German and French dietary supplement firms are negotiating multi-year supply agreements with fixed vitamin potency specifications. This channel pivot is most visible in North American markets, where precision dosing requirements are unbundling after-sales technical support from commodity procurement.
Vitamin Yeast Market Segmentation
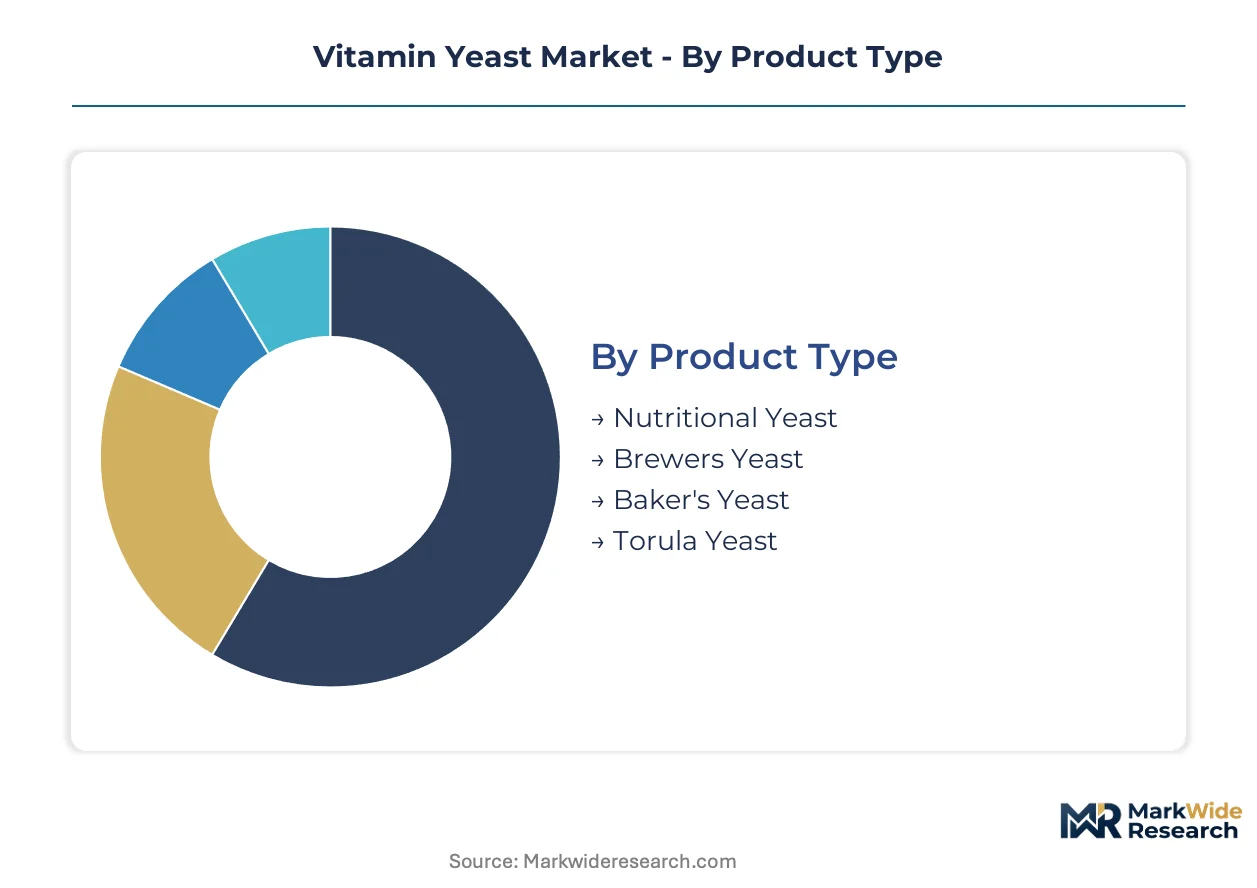
Vitamin yeast procurement specifications diverge sharply across end-use channels, with pharmaceutical and animal feed buyers imposing distinct analytical certification burdens on suppliers. Segmentation clarity enables producers to align fermentation batch sizing and fortification protocols with specific customer compliance requirements.
Product Type:
Nutritional yeast strains require EFSA novel food assessments for B12 fortification claims, while animal feed grades face separate FDA and EFSA feed additive reviews that compress strain approval timelines.
- Nutritional Yeast:Inactivated Saccharomyces cerevisiae cultivated on molasses or grain substrates, then fortified with B-complex vitamins including B12, riboflavin, and folate. Demand concentrates among German and French dietary supplement manufacturers responding to EFSA guideline updates that expand permissible health claims for vegan protein positioning.
- Brewers Yeast:Spent yeast recovered from beer fermentation, naturally rich in B-vitamins but requiring secondary fortification for standardized potency. Animal nutrition companies in the Netherlands and Denmark are phasing in brewers yeast derivatives as synthetic vitamin K3 replacements under livestock welfare protocols.
- Baker's Yeast:Active fermentation strains historically confined to leavening applications, now repurposed for vitamin extraction post-baking cycle.
- Torula Yeast:Candida utilis species cultivated on wood-derived substrates, offering distinct amino acid profiles for specialized feed formulations.
Nutritional yeast sits at the top of the volume ranking, with animal feed applications climbing the fastest as livestock producers reformulate rations.
Application:
Cost tier differentiation separates commodity bulk procurement from premium pharmaceutical contracts, with certification overhead driving margin stratification across channels.
- Animal Feed:Poultry and swine operations across Denmark, the Netherlands, and Germany are substituting yeast-natural vitamin complexes for synthetic premixes under EFSA and FDA residue monitoring protocols. Procurement specifications now mandate real-time potency verification and batch-level analytical documentation.
- Dietary Supplements:Capsule and tablet manufacturers in France and Germany negotiate multi-year supply agreements with fixed B12 and riboflavin specifications, displacing distributor-mediated bulk powder sales.
- Food Fortification:Domestic food manufacturers in China face SAMR GB standards enforcement on yeast-derived fortification levels.
- Pharmaceuticals:Precision dosing requirements from pharmaceutical firm contracts demand specialized drying protocols and enhanced stability testing.
- Cosmetics:Personal care brands incorporate yeast extracts for topical B-vitamin delivery in premium skincare positioning.
Animal feed commands the steepest expansion trajectory, with dietary supplements maintaining premium margin concentration.
Form:
Volume scale separates industrial bulk procurement from precision-dosed pharmaceutical channels, with packaging format directly determining customer type access.
- Powder:Dominant industrial procurement format for food and feed manufacturers requiring bulk blending flexibility. Chinese yeast extract producers are repositioning spray-dried powder capacity toward vitamin-fortified nutritional grades to serve domestic food fortification demand.
- Capsules:Precision dosing requirements from North American and European pharmaceutical firms are driving direct contracting with yeast extract producers, unbundling after-sales technical support from commodity procurement.
- Flakes:Specialty format for retail nutritional yeast positioning in vegan protein segments.
- Tablets:Compressed form for standardized dosing in supplement applications.
Powder retains volume leadership, with capsules gaining share fastest in pharmaceutical channel migration.
End User:
Supply concentration aligns with customer technical sophistication, with pharmaceutical and animal nutrition buyers consolidating procurement around certified fermentation networks.
- Animal Nutrition Companies:Poultry and swine operations in Denmark and the Netherlands face formulation recalibration costs when substituting yeast-natural complexes for established synthetic premixes, creating demand for supplier technical support partnerships.
- Pharmaceutical Firms:German and French dietary supplement manufacturers are front-loading toxicology and bioavailability documentation to exploit EFSA's compressed novel food assessment timelines for new strain introductions.
- Food & Beverage Manufacturers:China's SAMR GB standards enforcement redirects compliance spending toward analytical certification for domestic yeast-derived fortification.
- Personal Care Brands:Cosmetics applications remain niche, with limited regulatory harmonization across national cosmetic ingredient frameworks.
Animal nutrition companies anchor procurement volume, with pharmaceutical firms driving the fastest margin expansion through precision specification contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between EFSA's compressed novel food pathways and China's SAMR enforcement of GB standards is driving production migration toward jurisdictions with lower cost-of-compliance gaps. Yeast extract manufacturers are repositioning fermentation capacity to exploit these arbitrage opportunities.
China
Domestic food manufacturers face SAMR's tightened GB standards enforcement on yeast-derived fortification levels. State-run fermentation infrastructure subsidies under dual carbon goals are accelerating bioreactor upgrades in Hubei and Guangdong provinces. Angel Yeast leverages this public capital to dominate domestic nutritional grade supply.
Germany
Dietary supplement manufacturers in Bavaria and North Rhine-Westphalia are expanding procurement of vitamin-fortified strains following EFSA guideline updates. The country's federal food regulator enforces strict analytical certification requirements for B12-fortified products. Cologne and Hamburg harbor specialized third-party laboratories that verify folate and riboflavin potency for export documentation.
France
Lesaffre Group anchors European production through bioreactor networks concentrated in northern industrial zones. EFSA's novel food assessments for B12-enhanced strains are compressing approval timelines for new introductions. Lyon and Paris basin supplement firms negotiate multi-year supply agreements with fixed vitamin specifications.
India
FSSAI's tightened B12 labeling requirements are redirecting importer compliance spending toward analytical certification partnerships. Poultry and swine operations in Maharashtra and Gujarat face formulation recalibration costs when substituting yeast-natural complexes for synthetic premixes. Mumbai and Ahmedabad concentrate third-party laboratories with B12 quantification expertise.
United States
FDA feed additive reviews are accelerating livestock producer migration from synthetic vitamin K3 and B12 premixes. Pharmaceutical firms in New Jersey and Massachusetts demand precision-dosed capsule formats with enhanced stability testing. Chicago and Minneapolis feed mills consolidate procurement around certified fermentation networks with real-time potency verification.
Vitamin Yeast Market Competitive Landscape
Chinese producers anchor one tier through state-subsidized fermentation infrastructure; European specialists hold premium positioning through EFSA-certified novel food pathways. The vendor base stratifies across three tiers: integrated fermentation-to-extraction operators, strain-specialist licensors, and toll-manufacturing distributors. Dominant competitive moves include backward integration into molasses supply contracts and geographic expansion through dual-certification investments for SAMR and EFSA compliance.
Within the integrated fermentation tier, Angel Yeast exemplifies state-capital deployment toward nutritional grade dominance. Lesaffre Group and Lallemand occupy positions as Western archetypes of regulatory-certified production, with the former representing European bioreactor network concentration and the latter North American specialty strain positioning. These three anchors illustrate how capital structure and regulatory geography determine competitive access to pharmaceutical and animal nutrition channels.
| Leading Market Players |
|---|
| Angel Yeast |
| Lesaffre Group |
| Lallemand |
| ABF Ingredients |
| Archer Daniels Midland |
| Kerry Group |
| Alltech |
| Oriental Yeast |
| Now Foods |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical capsule manufacturers in Germany and France negotiate multi-year supply agreements with fixed vitamin potency specifications, compressing distributor margins and anchoring premium pricing tiers around EFSA-certified novel food pathways.
Pricing Analysis
Distributor margins in the bulk powder channel face compression as direct contracting between yeast extract producers and pharmaceutical firms displaces intermediary sales. Pricing stratifies across pharmaceutical-grade certification, standard food-grade fortification, and commodity animal feed tiers, with molasses input cost volatility exerting downward pressure on mid-tier offerings. Animal nutrition companies in Denmark and the Netherlands demonstrate highest price sensitivity due to ration reformulation costs, while pharmaceutical buyers absorb premium pricing for analytical documentation and batch-level verification.
Supply Chain Analysis
Molasses supply rests on Brazilian sugarcane harvest cycles and Indian ethanol diversion policies, creating input cost instability for fermentation facilities. Production gravity centers on Chinese state-subsidized bioreactor networks, French industrial zones anchored by Lesaffre Group, and North American specialty strain facilities. Single-source vulnerability concentrates in third-party B12 quantification laboratories, with distribution running through certified fermentation networks with real-time potency verification systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade certification tiers, driven by compressed EFSA novel food assessment timelines that reward front-loaded toxicology investment.
For Market Incumbents: Extend EFSA-certified strain portfolios into B12-enhanced variants before assessment pathways tighten further. Backward integration into molasses supply contracts in Brazil and India mitigates input cost volatility. Bioreactor capacity additions in Hubei province exploit China's dual carbon subsidies while defending against Angel Yeast's domestic dominance. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian animal feed applications offers white-space entry before FSSAI compliance requirements harden. Maharashtra and Gujarat poultry operations present the most penetrable demand cluster. Analytical certification partnerships with Mumbai-based laboratories provide differentiated positioning against synthetic premix incumbents. For Investors and Strategic Acquirers: Animal nutrition conglomerates are the most active acquirer in this space, consolidating fermentation-to-extraction operators with EFSA and SAMR dual certification. Long-term viability hinges on regulatory arbitrage durability between Atlantic and Chinese approval pathways. Watch for EFSA synthetic vitamin restriction announcements as inflection indicators for yeast-natural substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Submission | Compressed approval timelines reward first-movers with expanded B12 health claims in Germany and France. |
| Molasses Supply Contracting | Backward integration into Brazilian and Indian feedstock secures cost stability against ethanol diversion volatility. |
| Pharmaceutical-Grade Bioreactor Upgrade | Continuous fermentation monitoring with dissolved oxygen feedback reduces batch rejection rates for capsule contracts. |
| Analytical Certification Partnership | Third-party B12 quantification expertise in Cologne and Mumbai unlocks FSSAI and EFSA compliance documentation. |
| Dual Carbon Infrastructure Investment | China's state-run fermentation subsidies in Hubei province lower energy costs for vitamin-fortified nutritional grades. |
Research Methodology
Direct dialogue with fermentation plant managers, regulatory affairs leads at dietary supplement manufacturers, procurement officers at Dutch poultry operations, and third-party laboratory technical directors grounded qualitative findings. Secondary validation drew from EFSA novel food assessment databases, FDA feed additive filing records, SAMR GB standards enforcement notices, and customs trade data on molasses and yeast extract flows. Bottom-up strain approval timelines and top-down procurement volume estimates were triangulated against production capacity disclosures.
Output projections across the analysis window reflect modeled interactions between regulatory approval velocity, molasses price elasticity, and substitution rates from synthetic premixes. Segmentation dimensions included product type tier, application channel, pharmaceutical versus food-grade form specification, and end-user technical sophistication. CAGRs were derived from regression analysis of historical strain introduction rates correlated with EFSA and FDA review cycle compressions, with molasses futures curves and livestock feed formulation cost data as demand-side inputs.
Caveats apply where EFSA synthetic vitamin restriction timing, Brazilian sugarcane harvest disruptions, or FSSAI laboratory certification bottlenecks could materially shift the outlook. Forecasts reflect documented assumptions on regulatory pathway convergence and feedstock price mean-reversion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fat Soluble Vitamins Market
Vitamin Fortified
Global Vitamin Tonics Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Calcium-Fortified Food Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Vitamin B12 Drops Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Natural Beta Carotene Market