
 Global Yeast Market | 2026-2036
Global Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Global Yeast Market Outlook
Market Context with Strategic Players
China is tilting global yeast manufacturing capacity through aggressive fermentation infrastructure expansion and state-backed biotechnology investment. Lesaffre leverages its European heritage and deep strain libraries to dominate premium baker's yeast supply across Western markets. Angel Yeast Co. Ltd. anchors Asia-Pacific volume through massive dry yeast production complexes serving food manufacturing and bioethanol clients. Lallemand Inc. differentiates via specialized probiotic yeast strains and controlled fermentation technologies for feed additives and nutraceutical applications.
Technical Definition and Structural Segments
Yeast comprises single-celled fungi of the Saccharomyces genus, metabolizing sugars through anaerobic fermentation to produce carbon dioxide, ethanol, and biomass with protein contents reaching 40-50% in nutritional grades. Industrial yeast propagation proceeds through aerobic batch fermentation in molasses-based media, followed by centrifugal harvesting, washing, and drying to achieve shelf-stable viability counts exceeding 10 billion CFU per gram for active dry formulations. Baker's yeast and brewer's yeast command the largest revenue pools given entrenched demand from baking and beverage industries, while bioethanol yeast represents the fastest-expanding category as renewable fuel mandates intensify. Dry yeast formulations capture disproportionate margin strength due to extended ambient stability and reduced cold-chain logistics burden compared to fresh or liquid alternatives.
Regulatory Frame and Forward-Looking Close
EU Green Deal frameworks and REACH chemical safety protocols constrain feedstock sourcing and waste discharge from European yeast fermentation facilities, while China's SAMR enforces GB standards for food-grade microbial additives and bioethanol blending specifications. The FDA's GRAS designation pathway and EPA renewable fuel standards jointly shape yeast-derived product market access across United States food and energy applications. Stakeholders must monitor evolving carbon accounting rules and strain patent expirations to calibrate R&D allocation between commodity volume and specialized high-value yeast derivatives.
Market Dynamics
Fermentation capacity expansion in Asia and renewable fuel mandates across multiple continents are restructuring yeast procurement patterns and supplier investment priorities. Molasses price volatility and carbon accounting requirements now determine facility location decisions more than labor costs.
Growth Catalysts
- Bioethanol blending mandates:Brazil's ANVISA and EPA renewable fuel standards enforce escalating ethanol-gasoline ratios, forcing fuel producers to secure dedicated yeast strains optimized for high-temperature fermentation.
- Artisan bakery revival:Premium sourdough and long-fermentation bread formats in Western Europe and North America drive demand for fresh compressed yeast with specific aromatic profiles.
- Precision fermentation infrastructure:CRISPR-edited strain development and continuous bioreactor systems cut propagation cycles from days to hours, unlocking protein and nutraceutical applications.
Market Restraints
- Molasses supply concentration:Brazilian and Indian sugarcane harvests supply over 60 percent of global fermentation feedstock, exposing producers to monsoon variability and export restriction risk.
- REACH chemical safety compliance:ECHA registration requirements for novel genetically modified strains extend time-to-market by 18-24 months and inflate European R&D overhead.
- Enzyme substitution in baking:Chemical leavening agents and sourdough starter cultures displace commercial yeast in cost-sensitive industrial bakeries and home baking segments.
Strategic Opportunities
- Southeast Asia food manufacturing:Vietnam and Indonesia's expanding instant noodle and snack production sectors remain undersupplied by regional yeast capacity, creating import substitution potential.
- Carbon capture integration:Fermentation CO2 recovery systems aligned with EU Green Deal carbon border adjustments transform waste streams into revenue-generating industrial gas sales.
- Direct-to-brewery propagation:On-site yeast banking and repitching services bypass traditional distributor networks, capturing margin from craft breweries in Australia and New Zealand.
Industry Challenges
- Strain banking expertise shortage:Cryopreservation protocol development and genetic stability monitoring require specialized microbiologists that fermentation engineering programs fail to produce at sufficient scale.
- Multi-jurisdiction strain registration:Divergent GMO disclosure rules between FDA, EFSA, and China's SAMR force parallel dossier preparation for single product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Yeast Market |
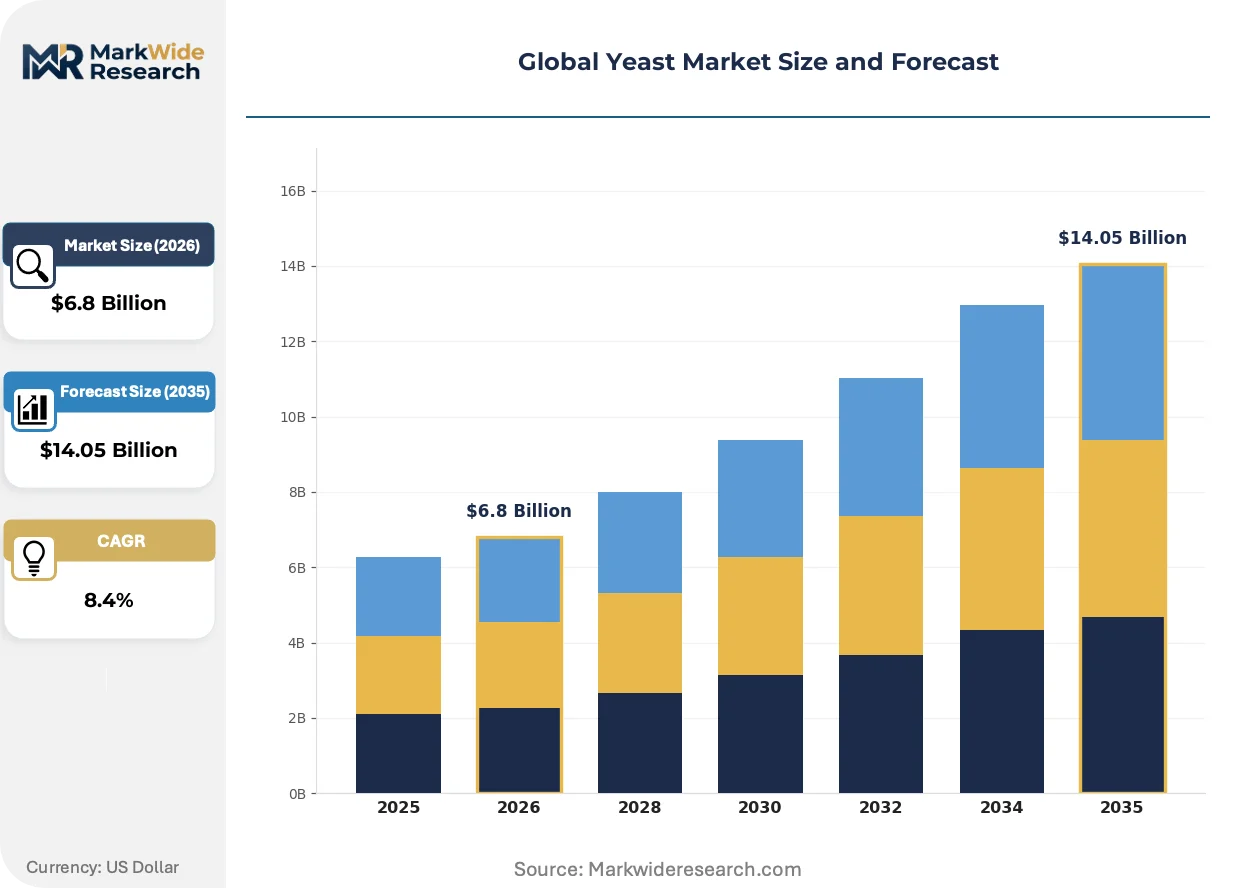
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baker's Yeast, Brewer's Yeast, Nutritional Yeast, Bioethanol Yeast Application: Baking, Brewing, Fermentation, Feed Additives Form: Dry Yeast, Liquid Yeast, Fresh Yeast, Active Dry Yeast End User: Bakeries, Food Manufacturing, Beverage Industry, Pharmaceuticals |
| Companies Covered | Associated British Foods plc, Alltech, Lesaffre, DSM-Firmenich, Chr. Hansen, Lallemand Inc., ADM, Leiber GmbH, Angel Yeast Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Yeast Market Strategic Shifts
Digital monitoring systems and synthetic biology tools are compressing strain development timelines while regulatory carbon accounting forces process redesign across fermentation facilities worldwide.
Sensor arrays and machine learning algorithms now track dissolved oxygen, pH, and biomass density in real-time during industrial propagation. Major bioethanol producers in the United States and Brazil deploy these systems to optimize feeding schedules and reduce batch failure rates. This capability is digitizing quality control functions that previously required manual sampling and laboratory analysis, enabling continuous rather than batch processing economics.
EU Green Deal carbon border adjustment mechanisms and China's dual carbon goals impose Scope 3 emission disclosure requirements on imported yeast derivatives. European facilities must document molasses sourcing emissions and biogas recovery rates to maintain market access. Bioethanol yeast categories face the steepest compliance burden, with German and French plants investing in anaerobic digesters to capture fermentation off-gases for energy recovery.
Breweries and industrial bakeries now contract directly with strain developers for proprietary cultures rather than purchasing commodity formulations through distributors. This disintermediation concentrates in North American craft brewing and European artisan baking clusters, where product differentiation justifies higher per-unit yeast costs. Technical service agreements covering viability guarantees and contamination response are displacing simple product sales in these segments.
Global Yeast Market Segmentation
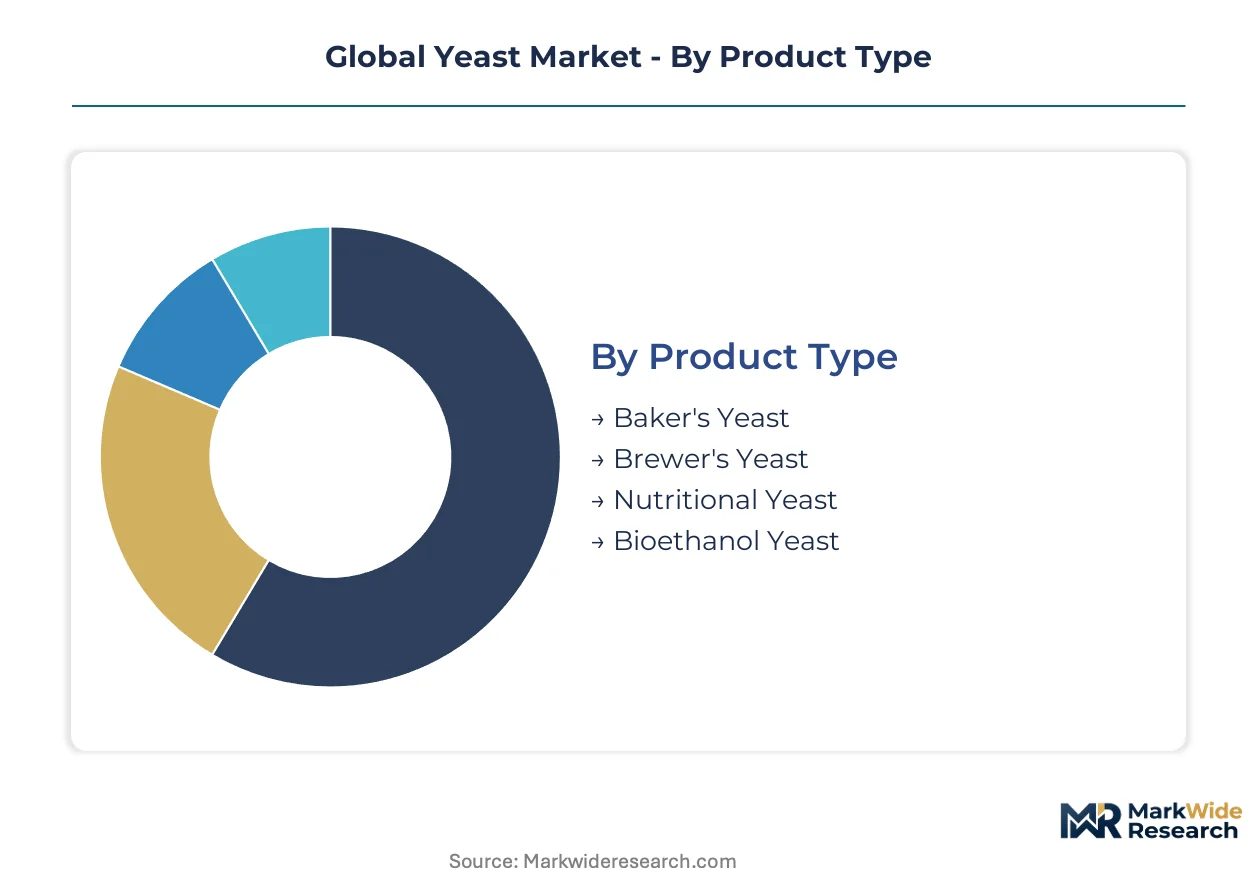
Yeast procurement patterns diverge sharply across product categories, with fermentation-derived strains serving distinct industrial workflows that demand specialized viability specifications and shelf-stability profiles. Understanding these segment boundaries clarifies why suppliers maintain parallel production lines rather than flexible multi-purpose facilities.
Product Type:
Mature commodity grades dominate volume flows while emerging specialty strains capture margin expansion through precision fermentation advances.
- Baker's Yeast:Saccharomyces cerevisiae strains selected for rapid CO2 production at 25-30°C, achieving 10 billion CFU/g viability counts after centrifugal harvesting and fluid-bed drying. Industrial bakeries across Germany and France specify fresh compressed formats for consistent proofing performance, though dry alternatives gain share in Southeast Asia's instant noodle manufacturing corridors where cold-chain infrastructure remains limited.
- Bioethanol Yeast:Thermotolerant Saccharomyces variants engineered for 38-42°C fermentation temperatures, reducing cooling costs in Brazilian and US Midwest ethanol plants. ANVISA and EPA renewable fuel standards enforce escalating blend mandates that force fuel producers to secure dedicated high-performance strains, making this category the steepest expansion trajectory among all product types.
- Brewer's Yeast:Bottom-fermenting lager strains and top-fermenting ale cultures with distinct flocculation and ester profiles. Craft breweries in Australia and New Zealand increasingly contract directly with strain developers for proprietary cultures.
- Nutritional Yeast:Inactivated whole-cell preparations with 40-50% protein content and B-vitamin fortification. Vegan food manufacturers and supplement formulators drive demand for non-GMO verified grades.
Baker's yeast handles the majority of throughput; bioethanol yeast is the fastest mover on share.
Application:
Cost tier separation distinguishes artisan-process applications from high-volume industrial fermentation where yield optimization dominates procurement criteria.
- Baking:Leavening applications span industrial pan bread production requiring 2-hour fermentation cycles through to 24-hour sourdough processes. Western European artisan bakeries specify fresh yeast with aromatic compound profiles that chemical leavening agents cannot replicate, while Asian instant noodle manufacturers prioritize cost-optimized dry formulations.
- Fermentation:Industrial ethanol and biochemical production using molasses or starch hydrolysate feedstocks. Brazilian sugarcane processors and Chinese corn refiners operate the world's largest dedicated fermentation trains.
- Brewing:Wort fermentation for alcoholic beverage production across lager, ale, and specialty beer categories. Direct-to-brewery propagation services are displacing traditional distributor networks in mature markets.
- Feed Additives:Probiotic yeast strains for ruminant and monogastric livestock nutrition, improving feed conversion ratios through gut microbiome modulation.
Baking commands the largest installed demand base; fermentation applications are expanding most quickly as renewable fuel mandates intensify.
Form:
Supply concentration in dry yeast manufacturing reflects the margin advantages of extended ambient stability and reduced logistics complexity versus perishable alternatives.
- Dry Yeast:Vacuum-packed granules with 24-month shelf life at ambient temperatures, achieving 95% viability retention. Angel Yeast's production complexes in China and Lesaffre's European facilities supply global food manufacturing clients.
- Active Dry Yeast:Intermediate moisture content requiring rehydration before use, balancing viability with storage convenience. Home baking and small commercial bakeries represent core demand.
- Fresh Yeast:Compressed blocks with 40% solids content and 2-4 week refrigerated shelf life. Western European artisan bakers specify this format for aromatic complexity.
- Liquid Yeast:Slurry formulations for direct pitching in large-scale brewing and bioethanol operations. Craft breweries value strain purity guarantees.
Dry yeast handles the majority of throughput; active dry yeast is gaining share fastest in emerging market food manufacturing.
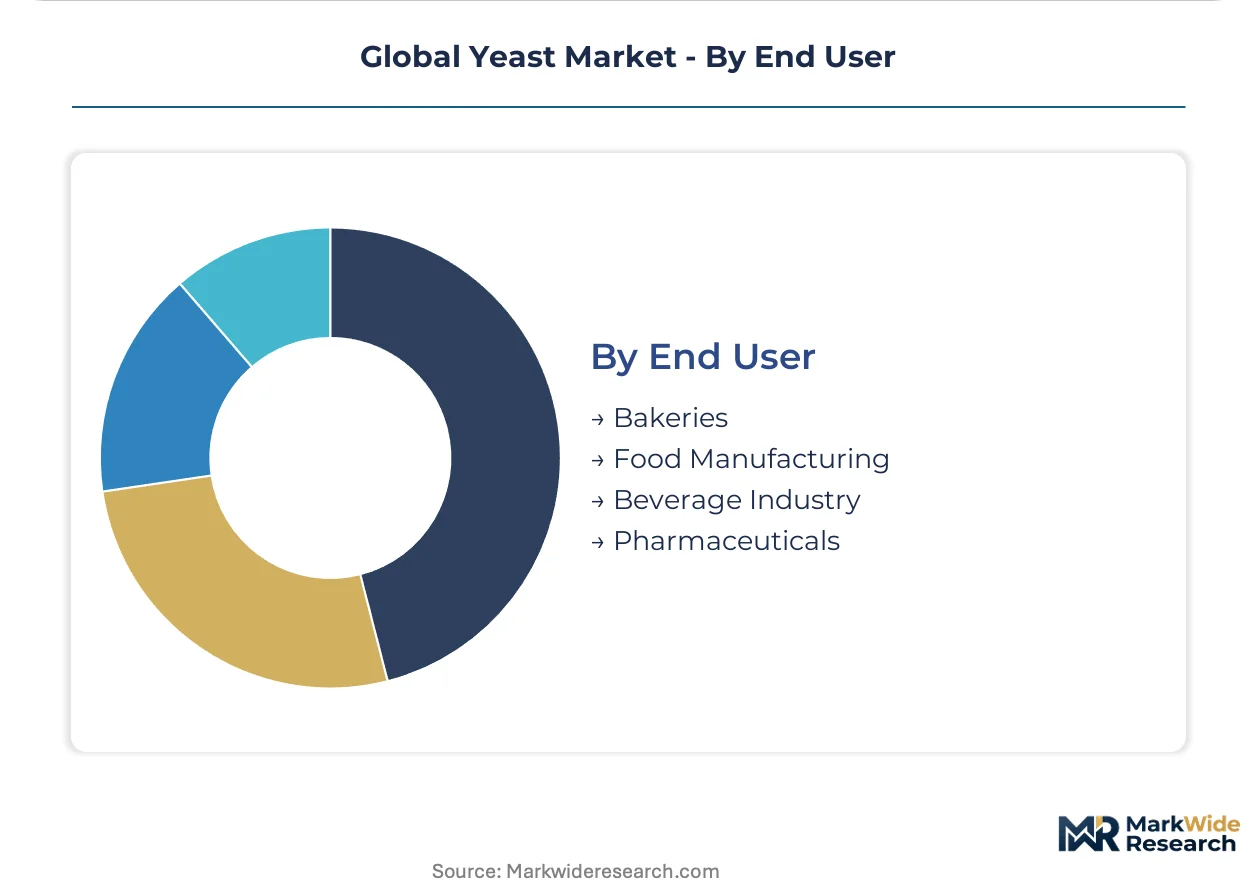
End User:
Customer type fragmentation separates commodity volume buyers from specialized purchasers requiring technical service agreements and viability guarantees.
- Food Manufacturing:Industrial-scale buyers of standardized yeast derivatives for processed food, savory snacks, and convenience meals. Vietnam and Indonesia's expanding instant noodle sectors remain undersupplied by regional capacity.
- Bakeries:Range from artisan sourdough specialists through industrial pan bread producers. Long-fermentation formats in Western Europe and North America drive demand for fresh compressed yeast with specific aromatic profiles.
- Beverage Industry:Breweries, wineries, and distilleries requiring strain-specific fermentation performance. Craft brewing clusters in Australia and New Zealand concentrate disintermediation trends.
- Pharmaceuticals:Probiotic and recombinant protein applications using controlled fermentation technologies. Regulatory compliance requirements exceed food-grade specifications.
Food manufacturing handles the majority of throughput; pharmaceuticals is climbing the fastest on value per kilogram metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforcement of GB standards for food-grade microbial additives shapes procurement requirements across Chinese yeast fermentation facilities. Regulatory carbon accounting mandates in the EU Green Deal framework and Brazil's ANVISA bioethanol blending rules are restructuring facility investment decisions across three continents.
China
Molasses-based fermentation capacity expansion in Hubei and Guangxi provinces serves domestic instant noodle manufacturers and corn-based bioethanol refiners. SAMR's GB standards enforcement for microbial food additives requires documented strain purity and viability specifications. Angel Yeast Co. Ltd. operates massive dry yeast production complexes in Yichang and Chongqing, supplying both food manufacturing and industrial ethanol clients across Asia-Pacific corridors.
Germany
Artisan bakery demand for fresh compressed yeast with specific aromatic profiles sustains premium fermentation product flows. ECHA REACH registration requirements for novel genetically modified strains extend time-to-market timelines for European R&D operations. Industrial bakeries in Bavaria and North Rhine-Westphalia specify fresh yeast formats for consistent proofing performance in long-fermentation bread production.
Brazil
Sugarcane harvests supply over sixty percent of global fermentation feedstock, concentrating bioethanol yeast demand in São Paulo and Minas Gerais processing corridors. ANVISA renewable fuel standards enforce escalating ethanol-gasoline blend ratios, forcing fuel producers to secure thermotolerant Saccharomyces variants. Fermentation facilities in the Center-South region deploy high-temperature strains to reduce cooling costs and maximize ethanol yields per ton of crushed cane.
United States
Craft brewing clusters in the Pacific Northwest and Colorado contract directly with strain developers for proprietary cultures, bypassing traditional distributor networks. EPA renewable fuel standards and FDA GRAS designation pathways jointly shape market access for yeast-derived products across food and energy applications. Midwest bioethanol plants in Iowa and Illinois operate dedicated fermentation trains using starch hydrolysate feedstocks from regional corn refiners.
Vietnam
Expanding instant noodle and savory snack production sectors remain undersupplied by regional yeast capacity, creating import substitution opportunities for dry yeast suppliers. Food manufacturing growth in Ho Chi Minh City and Binh Duong provinces outpaces domestic fermentation infrastructure development. Regional processors currently rely on Chinese and Thai imports for standardized yeast derivatives used in processed food applications.
Global Yeast Market Competitive Environment
Heritage fermentation specialists and precision biotechnology platforms split the market along commodity-specialist fault lines. Consolidation pressure concentrates among European and Asian producers with captive molasses sourcing or strain library depth. Three archetypes dominate: integrated fermentation conglomerates with backward feedstock control, precision biotechnology specialists leveraging CRISPR-edited strain development, and regional volume producers serving cost-optimized food manufacturing. Capacity expansion in Southeast Asia and carbon capture integration in European facilities represent the dominant competitive moves reshaping facility economics.
Within the heritage specialist tier, Lesaffre and Lallemand Inc. occupy positions anchored by deep strain libraries and controlled fermentation technologies. Angel Yeast Co. Ltd. exemplifies the scale-driven archetype through massive dry yeast production complexes serving food manufacturing and bioethanol clients. These three entities represent the strategic poles around which procurement patterns and technical service agreements now organize across baking, brewing, and renewable fuel applications.
| Leading Market Players |
|---|
| Associated British Foods plc |
| Alltech |
| Lesaffre |
| DSM-Firmenich |
| Chr. Hansen |
| Lallemand Inc. |
| ADM |
| Leiber GmbH |
| Angel Yeast Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Molasses price volatility driven by Brazilian and Indian monsoon variability determines both the spread between premium and economy yeast tiers and the geographic clustering of fermentation capacity. Buyers facing feedstock cost surges pivot toward long-term offtake contracts or backward-integrated suppliers, compressing margins for spot-market dependent processors.
Pricing Analysis
Chinese-manufactured dry yeast undercuts European fresh yeast by 30-40% on delivered cost, creating a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade (SAMR GB standards versus EFSA novel food approvals) and cold-chain logistics requirements. Cost compression in economy dry yeast is intensifying because Brazilian molasses export restrictions tighten feedstock availability. Industrial bakeries in Southeast Asia exhibit highest price sensitivity, while European artisan bakeries prioritize aromatic profile consistency over per-unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement between Brazilian sugarcane processors and fermentation equipment suppliers. Manufacturing concentrates in China, Brazil, and Germany, with each hub serving distinct regional demand corridors. Raw material dependencies center on sugarcane molasses, corn starch hydrolysates, and nitrogen-rich yeast extracts. Single-source vulnerability pervades the Brazilian molasses trade, where Center-South harvest fluctuations transmit directly to global fermentation input costs. Distribution runs through integrated fermentation conglomerates with captive feedstock sourcing rather than independent trading networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation infrastructure and CRISPR-edited strain development constitute a technological inflection that disrupts traditional propagation economics across baking, brewing, and bioethanol applications.
For Market Incumbents: Build strain library depth as the primary moat against precision biotechnology specialists. Secure captive molasses supply through long-term offtake agreements with Brazilian and Indian sugarcane processors to insulate against feedstock volatility. Invest in carbon capture integration at European facilities to preempt EU Green Deal carbon border adjustment penalties. For New Entrants and Emerging Players: Pursue direct-to-brewery propagation services in Australia and New Zealand, where craft brewing clusters disintermediate traditional distributor networks. Target Vietnam and Indonesia's instant noodle manufacturing corridors, which remain undersupplied by regional fermentation capacity. Lead with technical service agreements covering viability guarantees rather than commodity product sales. For Investors and Strategic Acquirers: EPA renewable fuel standard enforcement reshapes the acquisition landscape toward thermotolerant bioethanol yeast specialists. Five-to-ten year viability favors precision fermentation platforms with CRISPR-edited strain pipelines over commodity volume producers. Target acquisition archetype: mid-cap biotechnology firms with validated high-temperature Saccharomyces variants and SAMR registration dossiers in progress. Signal to monitor: ANVISA blend mandate acceleration above current ethanol-gasoline ratios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Sourcing | Captive Brazilian feedstock supply locks in cost advantage against spot-market competitors. |
| CRISPR Strain Development Program | Gene-edited thermotolerance cuts cooling costs in bioethanol fermentation trains. |
| Carbon Capture Facility Integration | Fermentation CO2 recovery aligns with EU Green Deal Scope 3 disclosure requirements. |
| Direct-to-Brewery Technical Service Launch | On-site yeast banking captures margin from disintermediating craft brewing clusters. |
| Southeast Asia Manufacturing Scale-Up | Regional capacity addition targets Vietnam and Indonesia's instant noodle production growth. |
Study Parameters
Initial hypotheses were tested against primary input from fermentation plant managers, yeast procurement leads at industrial bakeries, bioethanol process engineers, and regulatory affairs specialists at strain developers, then refined through secondary validation. Data synthesis combined customs trade records for molasses and yeast derivatives, SEC filings from publicly traded fermentation conglomerates, ECHA REACH registration databases, and ANVISA bioethanol blending compliance reports. Bottom-up facility capacity modeling and top-down demand segmentation were triangulated to constrain estimate variance.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation across product type (baker's, bioethanol, brewer's, nutritional), application (baking, fermentation, brewing, feed), form (dry, active dry, fresh, liquid), and end user (food manufacturing, bakeries, beverage, pharmaceuticals). CAGRs were derived from elasticity-adjusted consumption trajectories and capacity expansion announcements. Industry-specific inputs included molasses price forecasting curves and renewable fuel mandate enforcement schedules.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Indian monsoon precipitation indices, or EU carbon border adjustment implementation timelines would shift the trajectory. Forecasts reflect documented assumptions regarding strain registration timelines, feedstock trade policy stability, and precision fermentation technology diffusion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cocoa Bean Extract Market
Ingredients
Plant Sterols and Esters Market
Ingredients
United States Protein Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Xylooligosaccharide Market
Ingredients
Horehound Extract Market
Ingredients
Terminalia Extract Market
Ingredients
Ingredients Market
Ingredients
Sesame Seed Extract Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Alkalized Cocoa Powder Market
Ingredients
North America Corn Starch Market
Ingredients
Europe Fruit and Vegetable Ingredients Market
Ingredients
Africa Fats and Oil Market