
 Vitamins Drink Market | 2026-2036
Vitamins Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamins Drink Market Analysis
E-commerce subscriptions is tilting how vitamins drink brands reach repeat buyers. Seed Health leverages direct-to-consumer microbiome testing to personalize vitamin drink regimens. SmartyPants sustains shelf presence through gummy-to-liquid format expansion in mass retail. Thorne anchors practitioner channel loyalty by integrating vitamin drinks with diagnostic testing protocols.
Vitamins drinks are aqueous or reconstitutable formulations delivering water-soluble vitamins, minerals, and bioactive compounds at standardized concentrations, typically processed through cold-aseptic filling to preserve thermolabile nutrients like vitamin C and B-complex. Ready-to-Drink formats dominate volume but carry thinner margins due to logistics weight, while Powdered Supplements capture higher margin pools through lower shipping costs and flavor customization. Functional Beverages segment growth outpaces concentrates as consumers prioritize grab-and-convenience over preparation steps.
The FDA oversees dietary supplement labeling and Good Manufacturing Practice compliance for vitamins drinks sold in the United States, while the EFSA governs health claim substantiation across European markets, and China's SAMR enforces GB standards for imported functional beverages. Regulatory divergence in maximum vitamin fortification levels forces manufacturers to maintain multiple formulation specifications. Stakeholders must monitor evolving premarket notification pathways as classification ambiguity between foods and supplements persists in major jurisdictions.
Market Dynamics
E-commerce subscription models have reconfigured customer acquisition economics for vitamins drink manufacturers, shifting capital allocation from trade marketing to direct fulfillment infrastructure and microbiome personalization platforms.
Growth Catalysts
- EFSA health claim substantiation pathways:Clarified scientific evidence standards in Europe accelerate novel bioactive ingredient approvals, enabling faster product line extensions for brands with robust clinical dossiers.
- Millennial preventive health expenditure:This demographic segment allocates disproportionate wallet share to functional beverages over traditional supplement pills, concentrating demand in subscription and auto-replenishment channels.
- Cold-aseptic filling equipment:Advances in aseptic processing preserve thermolabile vitamins without preservatives, extending clean-label positioning to ready-to-drink formats previously limited by thermal degradation.
Market Restraints
- Vitamin C raw material volatility:Ascorbic acid supply concentrates among Chinese fermentation facilities, exposing margins to feedstock corn price swings and seasonal production constraints.
- Maximum fortification divergence:FDA, EFSA, and SAMR maintain incompatible upper limits for B-vitamin addition, forcing manufacturers to operate parallel formulation specifications and inventory pools.
- Refrigerated logistics cost:Cold-chain requirements for probiotic-enhanced vitamin drinks inflate last-mile delivery expenses versus ambient-stable pill formats, compressing unit economics in mass retail distribution.
Strategic Opportunities
- Germany's pharmacy channel:Underpenetrated vitamins drink presence in Apotheke retail creates whitespace for practitioner-endorsed formulations with reimbursement-adjacent positioning.
- Diagnostic integration:At-home micronutrient testing convergence with personalized subscription regimens enables outcome-linked pricing models and churn reduction through data-driven reorder triggers.
- Powder-to-liquid customization:Flavor sachet systems and on-demand mixing hardware address taste fatigue in repeat purchasers while reducing shipping weights versus bottled alternatives.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in aqueous vitamin stability and bioavailability enhancement concentrates among contract manufacturers, constraining in-house R&D scale-up for emerging brands.
- Dual classification ambiguity:Persistent jurisdictional uncertainty over whether vitamin drinks constitute foods or supplements delays premarket notification timelines and complicates label claim strategies across state and national boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamins Drink Market |
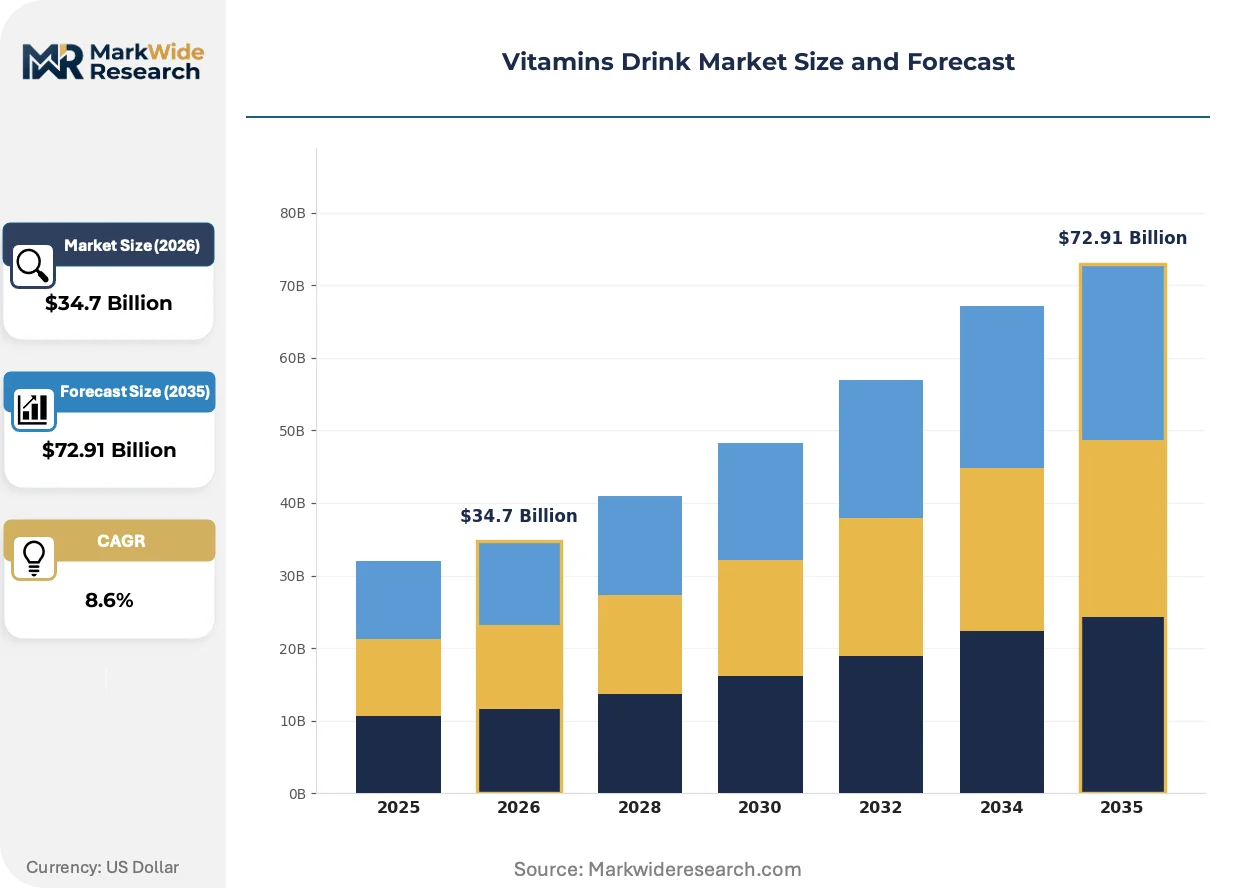
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink, Powdered Supplements, Functional Beverages, Concentrates Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores Customer Type: Health Conscious Individuals, Athletes, Working Professionals, Students Formulation: Organic, Sugar-Free, Flavored, Natural Ingredients |
| Companies Covered | Seed Health, SmartyPants, Thorne, HUM Nutrition, Ora Organics, Ritual, Garden of Life, Transparent Labs Supplements, mindbodygreen Supplements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamins Drink Market Emerging Trajectories
Personalization infrastructure and clean-label processing are compressing traditional formulation cycles while regulatory fragmentation forces adaptive manufacturing architectures.
Encapsulation technologies using liposomal and nano-emulsion delivery systems protect water-soluble vitamins from gastric degradation and improve cellular uptake efficiency. Premium-positioned brands in the United States and Germany are adopting these formats for B-complex and vitamin C fortification at accelerated pace. Conventional unencapsulated aqueous formulations are rendering obsolete in the high-absorption positioning tier.
SAMR's GB standards for imported functional beverages now mandate expanded heavy metal testing and origin documentation for bioactive ingredients entering China. This regulatory tightening elevates compliance costs for exporters while creating competitive shelter for domestic manufacturers with established testing protocols. European brands with existing EU novel food approvals face accelerated pathway friction relative to Asian entrants with prior China registration experience.
Subscription bundling with wearable biomarker data is displacing static replenishment schedules in the direct-to-consumer channel. Fitness tracker integration enables dynamic dosing recommendations tied to sleep, stress, and activity metrics, with Silicon Valley and Berlin emerging as pilot markets for this convergence. Traditional fixed-interval auto-ship models face elevated cancellation risk where personalization platforms demonstrate measurable outcome differentiation.
Vitamins Drink Market Segmentation
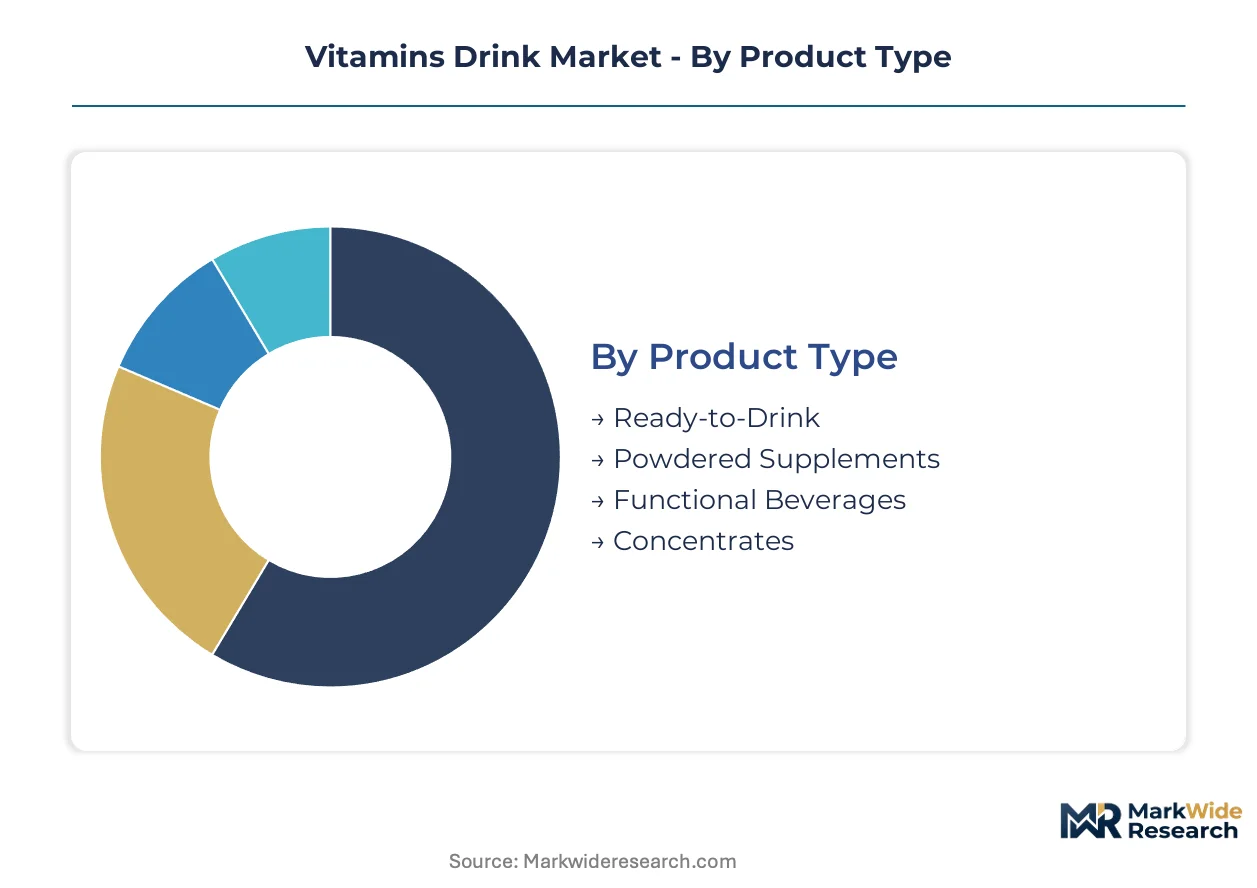
Vitamins drink manufacturers navigate divergent margin structures and channel economics across product formats. Segmentation reveals where cold-chain logistics, flavor customization, and subscription bundling concentrate investment returns.
Product Type:
Mature ready-to-drink formats coexist with emerging powder-to-liquid systems that slash shipping weights and enable on-demand personalization.
- Ready-to-Drink:Aqueous formulations packaged in bottles or cans, typically processed through cold-aseptic filling to preserve thermolabile vitamins like B-complex and vitamin C. Demand concentrates in United States convenience retail and China urban grab-and-go channels, though refrigerated logistics compress margins versus ambient-stable alternatives.
- Powdered Supplements:Reconstitutable dry blends offering flavor customization and reduced shipping costs. Adoption accelerates in German direct-to-consumer subscriptions and Silicon Valley wellness clusters where microbiome personalization platforms bundle diagnostic testing with tailored regimens.
- Functional Beverages:Positioned between supplements and conventional drinks with standardized nutrient delivery. Clean-label positioning drives shelf placement in United States mass retail and Chinese tier-one city supermarkets.
- Concentrates:High-potency liquid or gel formats requiring dilution, capturing pharmacy channel presence in Germany Apotheke retail and practitioner-endorsed positioning.
Ready-to-Drink retains volume leadership; Powdered Supplements holds the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates capital-light digital acquisition from trade marketing-heavy physical retail.
- Online Retail:Direct-to-consumer subscriptions and marketplace storefronts enabling auto-replenishment and diagnostic integration. Auto-ship models with wearable biomarker data displace static schedules in Berlin and Silicon Valley pilot markets.
- Supermarkets:Mass retail placement requiring slotting fees and promotional support, with gummy-to-liquid format expansions sustaining shelf presence.
- Health Food Stores:Curated specialty retail emphasizing clean-label and organic certification, particularly strong in German naturkost channels and United States coastal metros.
- Convenience Stores:Impulse-driven grab-and-go positioning for single-serve ready-to-drink units, concentrated in China urban convenience networks and United States petroleum retail.
Online Retail commands the highest customer lifetime value; Convenience Stores deliver the lowest acquisition cost per trial.
Customer Type:
Application focus separates preventive wellness expenditure from performance optimization and occupational stress management.
- Health Conscious Individuals:Preventive-focused consumers allocating disproportionate wallet share to functional beverages over traditional pills, concentrated in millennial demographics across United States and German urban centers.
- Athletes:Performance-oriented users seeking bioavailability-enhanced formats with electrolyte and amino acid co-fortification, driving liposomal encapsulation adoption.
- Working Professionals:Stress and fatigue management positioning with B-complex and adaptogen blends, strong in Chinese white-collar districts and United States tech corridors.
- Students:Cognitive support and convenience-driven consumption, price-sensitive segment favoring powdered formats and private label offerings.
Health Conscious Individuals anchor subscription revenue; Athletes generate the highest per-unit premium realization.
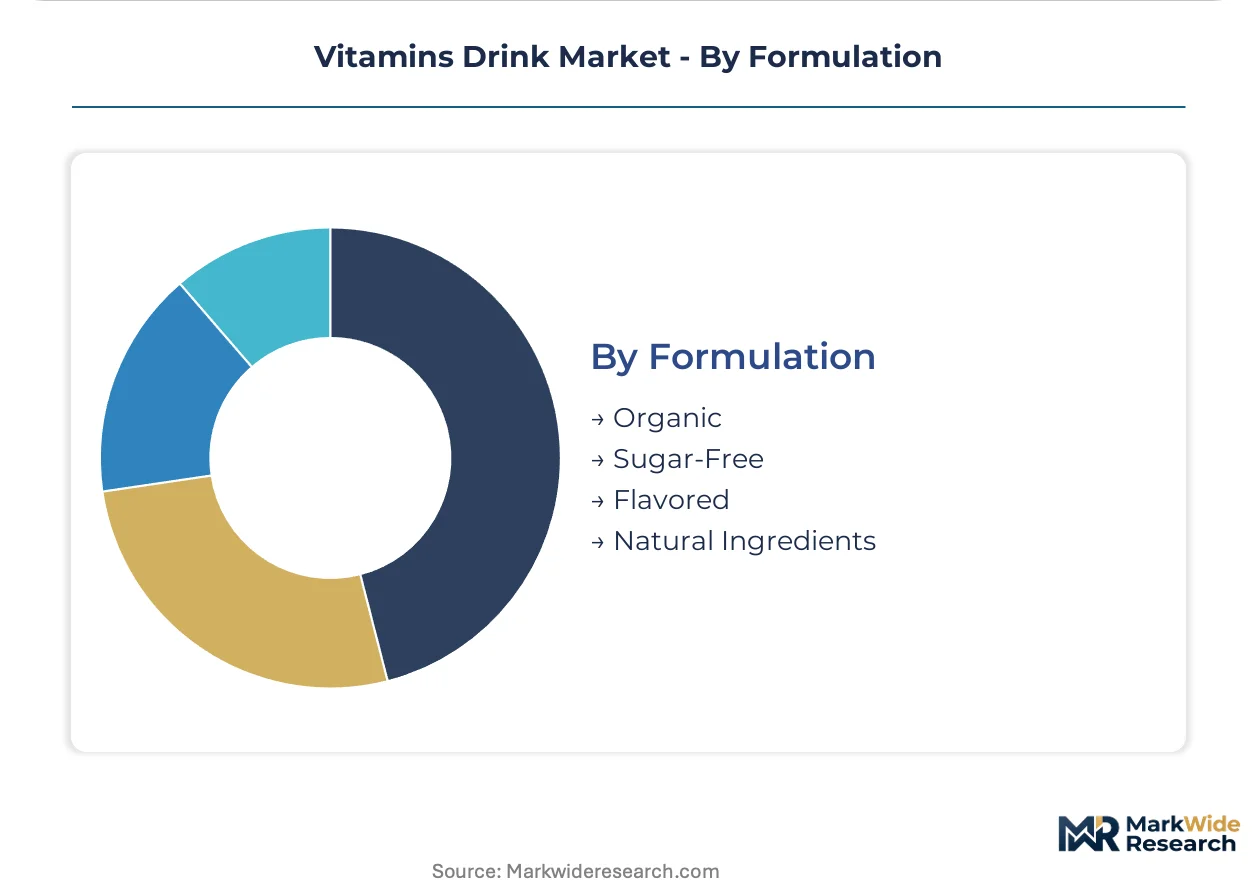
Formulation:
Ingredient sourcing tier separates certified organic supply chains from conventional commodity inputs.
- Organic:Certified ingredient sourcing with full traceability documentation, commanding shelf price premiums in German naturkost and United States Whole Foods-type retail.
- Sugar-Free:Non-nutritive sweetener or unsweetened formulations addressing metabolic health positioning, regulatory divergence on sweetener approvals complicates cross-border formulation.
- Flavored:Taste-masked systems addressing palatability barriers in vitamin-fortified applications, with rotating seasonal profiles combating repeat purchase fatigue.
- Natural Ingredients:Clean-label positioning without synthetic additives, overlapping with organic but permitting conventional agricultural inputs.
Organic captures the certification premium; Sugar-Free is climbing fastest on metabolic health positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence in maximum vitamin fortification levels is forcing manufacturers to maintain parallel formulation specifications across major markets. Demand concentrates where e-commerce subscription infrastructure and cold-aseptic processing capabilities intersect.
United States
Millennial preventive health expenditure drives disproportionate wallet share toward functional beverages over traditional supplement pills. The FDA oversees dietary supplement labeling and Good Manufacturing Practice compliance, with updated requirements reshaping formulation standards. Silicon Valley wellness clusters pilot subscription bundling with wearable biomarker data, displacing static replenishment schedules.
China
Urban grab-and-go consumption accelerates in tier-one city convenience networks and supermarket channels. SAMR enforces GB standards for imported functional beverages, mandating expanded heavy metal testing and origin documentation for bioactive ingredients. Shanghai and Beijing concentrate demand for probiotic-enhanced vitamin drinks requiring refrigerated logistics.
Germany
Apotheke retail channels create whitespace for practitioner-endorsed formulations with reimbursement-adjacent positioning. EFSA governs health claim substantiation with clarified scientific evidence standards accelerating novel bioactive ingredient approvals. Berlin emerges as a pilot market for diagnostic-integrated subscription regimens with dynamic dosing recommendations.
Japan
Health-conscious aging demographics sustain demand for bioavailability-enhanced formats with clean-label positioning. METI and PMDA regulate functional food claims with stringent safety documentation requirements. Tokyo and Osaka concentrate liposomal encapsulation adoption among premium-positioned brands seeking cellular uptake efficiency advantages.
United Kingdom
Direct-to-consumer subscriptions capture health-conscious urban professionals seeking convenience over preparation steps. The FSA and Trading Standards enforce novel food regulations with post-Brexit divergence from EU frameworks. London anchors e-commerce acquisition economics with microbiome personalization platforms bundling diagnostic testing with tailored regimens.
Vitamins Drink Market Vendor Landscape
On the supply side, the industry is fragmented across direct-to-consumer specialists, mass retail incumbents, and practitioner-channel anchors. Seed Health, SmartyPants, and Thorne exemplify three distinct strategic archetypes: microbiome personalization platforms, gummy-to-liquid format expanders, and diagnostic-integrated practitioner networks. Competitive moves concentrate on e-commerce subscription infrastructure and cold-aseptic processing capacity expansion.
Within the personalization-platform archetype, Seed Health leverages direct-to-consumer microbiome testing to anchor subscription retention. SmartyPants occupies a position in mass retail format expansion, while Thorne exemplifies practitioner-channel loyalty through diagnostic integration. HUM Nutrition and Ritual represent additional direct-to-consumer specialists, with Garden of Life and Ora Organics sitting within the clean-label organic tier. Transparent Labs Supplements and mindbodygreen Supplements occupy positions in transparency-forward and media-integrated positioning respectively.
| Leading Market Players |
|---|
| Seed Health |
| SmartyPants |
| Thorne |
| HUM Nutrition |
| Ora Organics |
| Ritual |
| Garden of Life |
| Transparent Labs Supplements |
| mindbodygreen Supplements |
| Others |
Supply Flow & Price Mechanics
Ascorbic acid fermentation capacity concentrates in Chinese industrial clusters, directly tethering margin pools to corn feedstock volatility and seasonal production constraints downstream. This upstream concentration forces brands to absorb cost swings or push price adjustments through subscription tiers, reshaping where value capture concentrates across ready-to-drink and powdered formats.
Pricing Analysis
Volume-discount tiering structures stratify across subscription auto-replenishment, practitioner-channel bundles, and mass retail single-serve. Price differentiation rests on certification grade—organic and clean-label commands shelf premiums—and geographic delivery cost differentials between cold-chain probiotic formats and ambient-stable powders. Pricing pressure stems from refrigerated logistics inflation compressing unit economics in last-mile distribution. Students and price-sensitive trial purchasers exhibit highest elasticity, while diagnostic-integrated subscribers show lowest sensitivity due to outcome-linked retention.
Supply Chain Analysis
Supplier-financing facilities and extended payment terms have become critical working capital tools for contract manufacturers navigating vitamin raw material volatility. Sourcing concentrates in China for ascorbic acid and B-complex fermentation, India for botanical extracts, and Germany for encapsulation equipment and precision dosing hardware. Corn-derived feedstock and liposomal lipid inputs anchor cost structures. Single-source vulnerability in Chinese fermentation capacity exposes margins to trade policy friction. Distribution runs through direct-to-consumer fulfillment centers, mass retail distribution networks, and pharmacy-channel wholesalers with divergent cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—specifically FDA, EFSA, and SAMR compliance dossiers—creates asymmetric barriers against unproven entrants lacking clinical substantiation infrastructure.
For Market Incumbents: Entrench practitioner-channel loyalty through deeper diagnostic integration and exclusive testing protocol partnerships that elevate switching costs. Cold-aseptic processing capacity expansion in United States and German manufacturing clusters defends against emerging brands reliant on contract manufacturing. Patent-protected encapsulation technologies and established novel food approvals in Europe and China create regulatory moats that delay fast-follower entry timelines. For New Entrants and Emerging Players: Germany's Apotheke retail channel presents whitespace for reimbursement-adjacent positioning with practitioner endorsement, as vitamins drink penetration lags traditional supplement formats. Powder-to-liquid customization systems targeting Silicon Valley and Berlin wellness clusters enable lower customer acquisition costs through microbiome personalization platforms. Go-to-market execution should anchor in diagnostic-integrated subscriptions with dynamic dosing algorithms rather than static auto-ship commodity competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer specialists possessing subscription infrastructure but lacking practitioner-channel credibility or international regulatory approvals. Long-term viability over the next decade hinges on convergence with at-home diagnostic hardware and wearable biomarker integration. The signal to watch is SAMR registration velocity for imported functional beverages, as accelerated approval timelines would indicate competitive shelter erosion for domestic Chinese manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Integration Platform | Seed Health's microbiome testing convergence enables outcome-linked pricing and churn reduction through data-driven reorder triggers. |
| Cold-Aseptic Capacity Expansion | Preservation of thermolabile vitamins without preservatives extends clean-label positioning to ready-to-drink formats previously limited by thermal degradation. |
| Pharmacy Channel Penetration | Germany's Apotheke retail creates whitespace for practitioner-endorsed formulations with reimbursement-adjacent positioning and professional credibility. |
| Powder-to-Liquid Customization | Flavor sachet systems and on-demand mixing hardware reduce shipping weights versus bottled alternatives while addressing taste fatigue in repeat purchasers. |
| Regulatory Dossier Investment | EFSA health claim substantiation and SAMR GB standard compliance create asymmetric barriers against unproven entrants lacking clinical infrastructure. |
Methodological Framework
Initial hypotheses were tested against primary input from brand managers at vitamins drink manufacturers, procurement leads at contract fermentation facilities, pharmacy channel buyers in German Apotheke networks, and diagnostic platform executives developing microbiome personalization tools. These perspectives were refined through secondary validation against FDA dietary supplement labeling guidance, EFSA health claim substantiation databases, SAMR GB standards documentation, and trade data on ascorbic acid and B-complex raw material flows. Bottom-up segment sizing and top-down market reconciliation anchored volume and value estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product format, distribution channel, customer application focus, and formulation certification tier. CAGRs were derived from growth driver elasticity analysis applied to baseline penetration rates. Industry-specific forecast inputs incorporated e-commerce subscription adoption curves, cold-aseptic processing capacity expansion timelines, and regulatory approval velocity for novel bioactive ingredients.
Practitioners should monitor SAMR registration timelines for imported functional beverages, EFSA novel food approval acceleration, and wearable biomarker integration adoption rates for early signals of competitive inflection. Forecasts reflect assumptions about sustained millennial preventive health expenditure, continued cold-chain logistics cost inflation, and stable regulatory classification frameworks. Macroeconomic contraction in discretionary wellness spending, abrupt tariff escalation on Chinese fermentation inputs, or reclassification of vitamins drinks as pharmaceuticals would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market
Vitamin Fortified
Global Vitamin Tonics Market
Vitamin Fortified
Vitamin Yeast Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Fat Soluble Vitamins Market
Vitamin Fortified
Middle East and Africa Vitamin a Market