
 Natural Beta Carotene Market | 2026-2036
Natural Beta Carotene Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Beta Carotene Market Outlook
Dietary supplement applications is broadening as the fastest-rising vertical for natural beta carotene, pulling share from traditional food coloring uses. DSM Nutritional Products leverages its fermentation-based algae platforms to secure pharmaceutical-grade supply chains. Chr. Hansen Holding A/S anchors its position through microbial strain optimization for high-purity carotenoid output. BASF SE competes across multiple grade tiers with integrated cultivation-to-extraction assets in temperate zones.
Natural beta carotene denotes a lipid-soluble carotenoid pigment extracted from plant or algal biomass, typically yielding 1-30% active compound concentration depending on source and solvent method, functioning primarily as a provitamin A precursor and natural colorant in formulated products. Powder formulations dominate volume throughput for dry-blend supplement and feed applications where handling stability and shelf-life extension matter most. Oil suspensions capture premium positioning in cosmetics and softgel encapsulation where bioavailability enhancement drives formulation value. Algae sources are gaining fastest traction as Dunaliella salina cultivation delivers contaminant-free, vegan-certified material that bypasses agricultural land constraints.
EFSA and FDA both maintain strict purity thresholds for carotenoid additives in ingestible products, while REACH governs extraction solvent residuals in European supply chains, collectively elevating compliance costs for unverified suppliers. ISO 22000 and FSSC 22000 certifications have become baseline requirements for accessing branded food manufacturer procurement lists across major import markets. Stakeholders must monitor evolving clean-label definitions and algae cultivation scale economics to secure positioning before supply bottlenecks emerge in certified natural grades.
Market Dynamics
Clean-label mandates across Europe and North America are compressing synthetic carotenoid supply chains while algae-derived extraction platforms scale to meet pharmaceutical-grade purity thresholds. This regulatory compression is redrawing competitive positioning around certified cultivation assets and solvent-free processing capabilities.
Growth Catalysts
- REACH solvent restrictions:ECHA's tightening residual limits on hexane and acetone in food-grade extracts are disqualifying conventional extraction operators, opening procurement slots for supercritical CO2 processors.
- Pharmaceutical-grade demand:Softgel manufacturers in the United States are specifying USP-grade beta carotene for prenatal vitamin lines, pulling volume from food coloring applications.
- Algae photobioreactor yields:Dunaliella salina cultivation in Israel and Australia is achieving 15% dry-weight carotenoid content, bypassing seasonal agricultural constraints that limit carrot and palm oil sources.
Market Restraints
- Capital intensity of photobioreactors:Closed-system algae cultivation requires USD 8-12 million per hectare of installed capacity, concentrating supply among asset-heavy operators.
- Input cost volatility:Magnesium and potassium nitrate fertilizers for algae growth media fluctuate with energy markets, compressing margins for non-integrated cultivators.
- Technical yield ceilings:Natural extraction methods plateau at 30% active compound concentration versus 96% synthetic equivalence, limiting high-potency pharmaceutical applications.
Strategic Opportunities
- Indian dietary supplement expansion:FSSAI's 2022 notification permitting algae-derived carotenoids in Ayurvedic formulations creates a 1.4 billion-person addressable market for certified suppliers.
- Cosmeceutical encapsulation:Liposomal delivery systems for topical antioxidant serums represent an emerging application with 40-60% formulation premiums over bulk powder.
- EU Green Deal bioeconomy incentives:Horizon Europe funding for circular algae cultivation is offsetting capex for operators co-locating with industrial CO2 emitters.
Industry Challenges
- ISO 22000 certification timelines:Branded food manufacturers now require 18-24 month supplier qualification periods, freezing out uncertified mid-tier processors.
- Phycocyanin contamination control:Cross-species algae management demands molecular diagnostic capabilities that strain quality control budgets at smaller cultivation facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Beta Carotene Market |
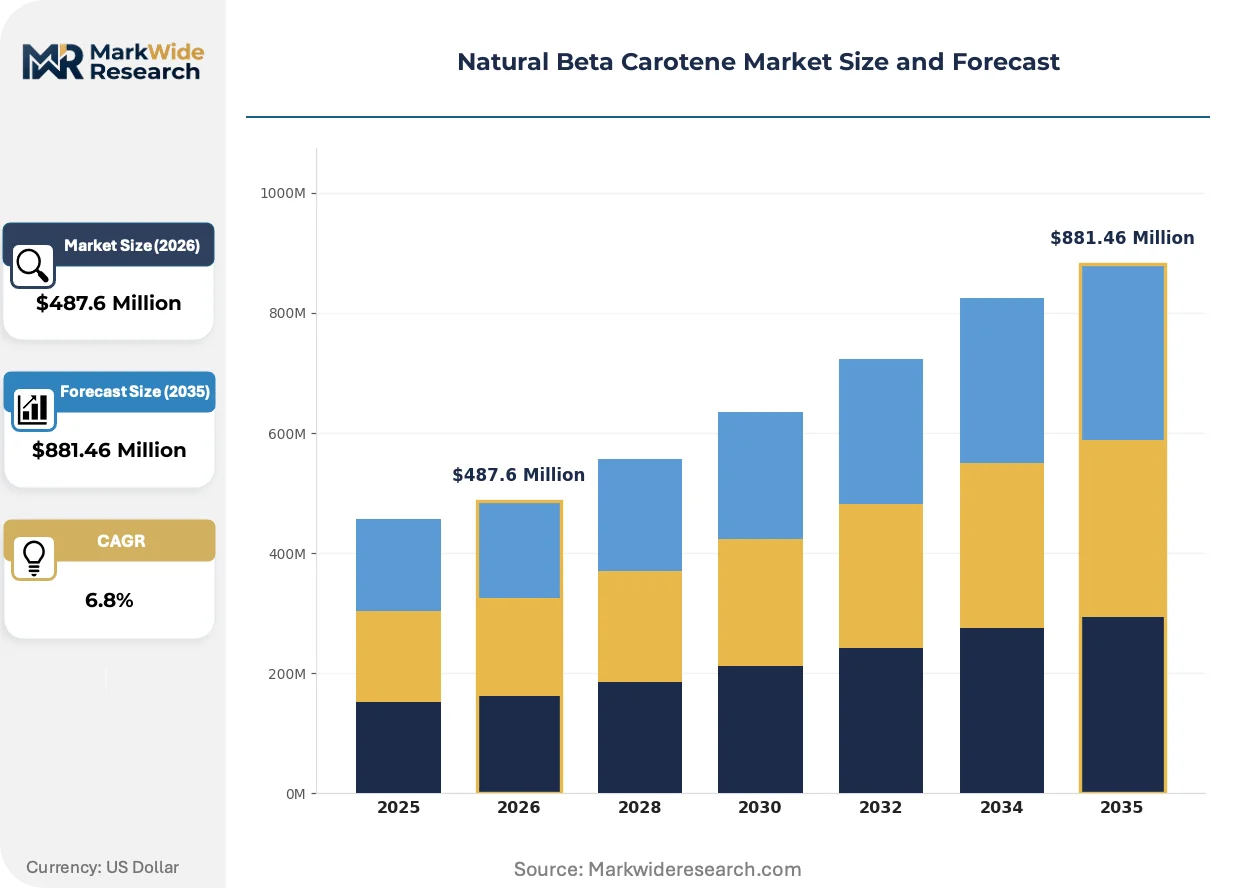
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Oil, Granules, Emulsions Application: Food & Beverage, Dietary Supplements, Cosmetics, Animal Feed Source: Algae, Carrots, Pumpkins, Spinach Grade: Food Grade, Feed Grade, Pharmaceutical Grade, Industrial Grade |
| Companies Covered | BASF SE, DSM Nutritional Products, Chr. Hansen Holding A/S, Lycored, Allied Biotech Corporation, Givaudan S.A., Divi's Laboratories Limited, Cyanotech Corporation, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Beta Carotene Market Strategic Shifts
Bioprocess engineering and regulatory chemistry are jointly transforming how natural beta carotene moves from cultivation to formulated products. These shifts favor operators with integrated strain development, extraction technology, and certification management capabilities.
Supercritical CO2 extraction is converging with in-line chromatographic purification to produce solvent-free, high-purity carotenoid crystals. Pharmaceutical softgel manufacturers in Germany and Switzerland are adopting these systems at commercial scale. This convergence is compressing the traditional multi-step refinement chain into single-pass processing, reducing batch-to-batch variability and enabling real-time release testing.
EFSA's 2023 updated guidance on novel food safety assessments for algae-derived ingredients is tightening toxicological data requirements for new cultivars. The regulation now mandates 90-day rodent studies and genotoxicity screening for any modified Dunaliella strain. European suppliers with legacy EFSA approvals for established strains are widening their competitive moat against new market entrants facing extended approval timelines.
Formulators are consolidating supplier relationships around vertically integrated algae operators who control cultivation through extraction. Dietary supplement brands in California and New York are reducing their approved vendor lists from twelve to three certified sources. This concentration is most visible in the United States, where NSF International and USP verification programs have become non-negotiable gatekeepers for retail shelf placement.
Natural Beta Carotene Market Segmentation
Natural beta carotene procurement patterns diverge sharply across formulation requirements and end-use specifications. Suppliers configure extraction and purification assets around these segment boundaries to capture margin premiums in certified-grade markets.
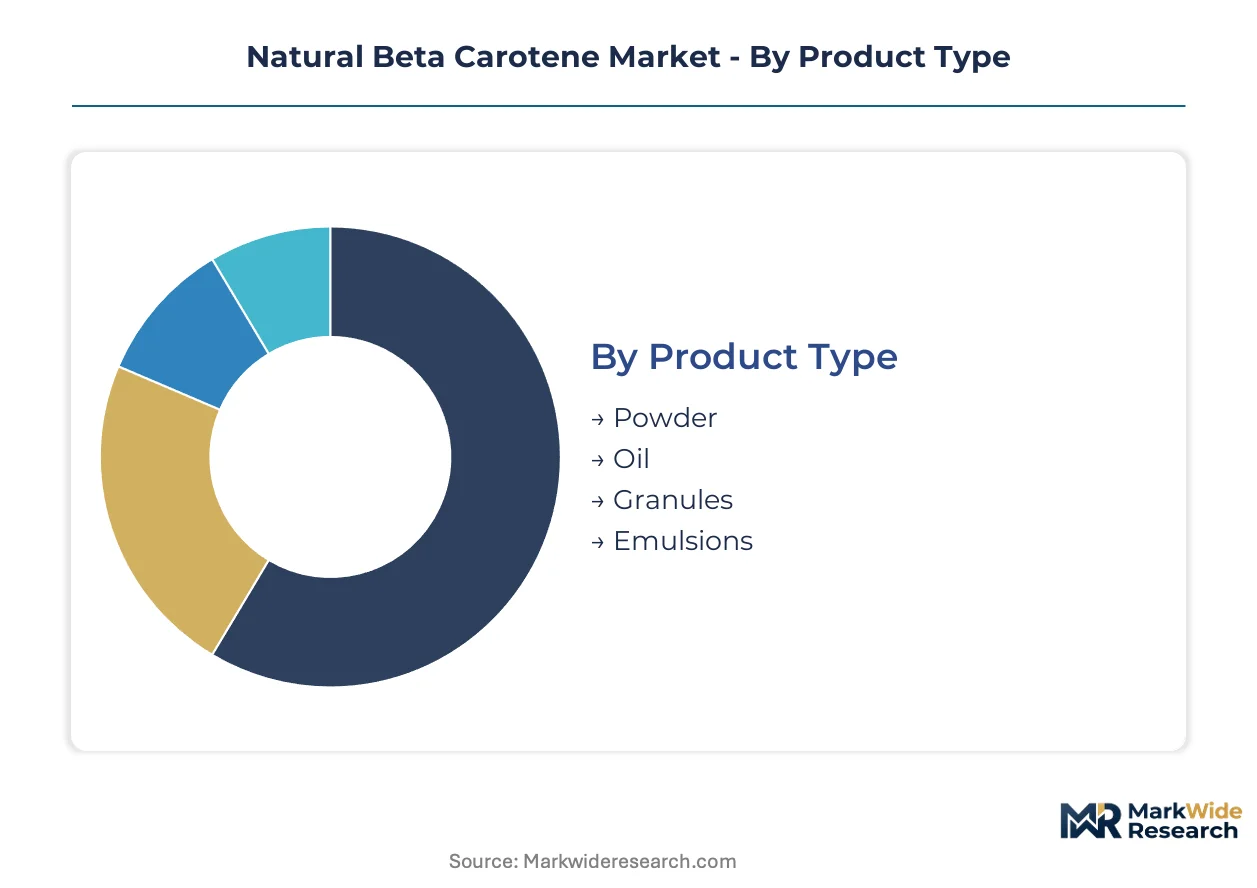
Product Type:
Powder formulations dominate volume throughput while oil suspensions command formulation premiums in specialized delivery systems.
- Powder:Dry-blend matrices with 1-10% active compound concentration serve mass-market supplement and feed applications where handling stability and extended shelf-life reduce downstream processing costs. Demand concentrates in United States contract manufacturers producing multivitamin tablets and hard-shell capsules.
- Oil:Lipid-dispersed suspensions at 20-30% concentration enable softgel encapsulation and cosmetic serum formulations where bioavailability enhancement justifies unit price premiums. German pharmaceutical softgel specialists specify oil-based inputs for prenatal vitamin lines.
- Granules:Agglomerated particles improve flowability in high-speed tableting operations for dietary supplement producers.
- Emulsions:Aqueous-dispersible systems target beverage fortification and liquid supplement applications requiring homogeneous suspension stability.
Today's leader: Powder. Tomorrow's challenger: Oil.
Application:
End-use concentration is shifting from legacy colorant markets toward health-positioned formulations with regulatory certification requirements.
- Dietary Supplements:Softgel, tablet, and gummy delivery systems for antioxidant and provitamin A positioning drive fastest volume expansion. United States brands specify USP-verified inputs for NSF International retail compliance.
- Food & Beverage:Natural colorant replacement for synthetic carotenoids in dairy, confectionery, and beverage applications faces margin compression from clean-label mandates.
- Cosmetics:Topical antioxidant serums and anti-aging formulations utilize liposomal encapsulation with 40-60% formulation premiums over bulk inputs.
- Animal Feed:Poultry and aquaculture pigment enhancement for egg yolk and flesh coloration operates on specification-grade procurement with limited premium capture.
Dietary supplements is climbing the fastest; food and beverage holds volume dominance but loses share.
Source:
Algae cultivation platforms are displacing agricultural extraction as regulatory thresholds tighten on solvent residuals and seasonal supply variability.
- Algae:Dunaliella salina photobioreactor cultivation delivers 15% dry-weight carotenoid content with vegan certification and contaminant-free profiles. Israeli and Australian operators bypass agricultural land constraints.
- Carrots:Root vegetable extraction remains cost-competitive for feed-grade applications with lower purity requirements.
- Pumpkins:Seasonal harvest cycles limit supply consistency for year-round manufacturing operations.
- Spinach:Leafy green sources carry lower carotenoid density, requiring higher biomass throughput for equivalent active compound yield.
Algae commands the premium tier; carrots anchor commodity supply.
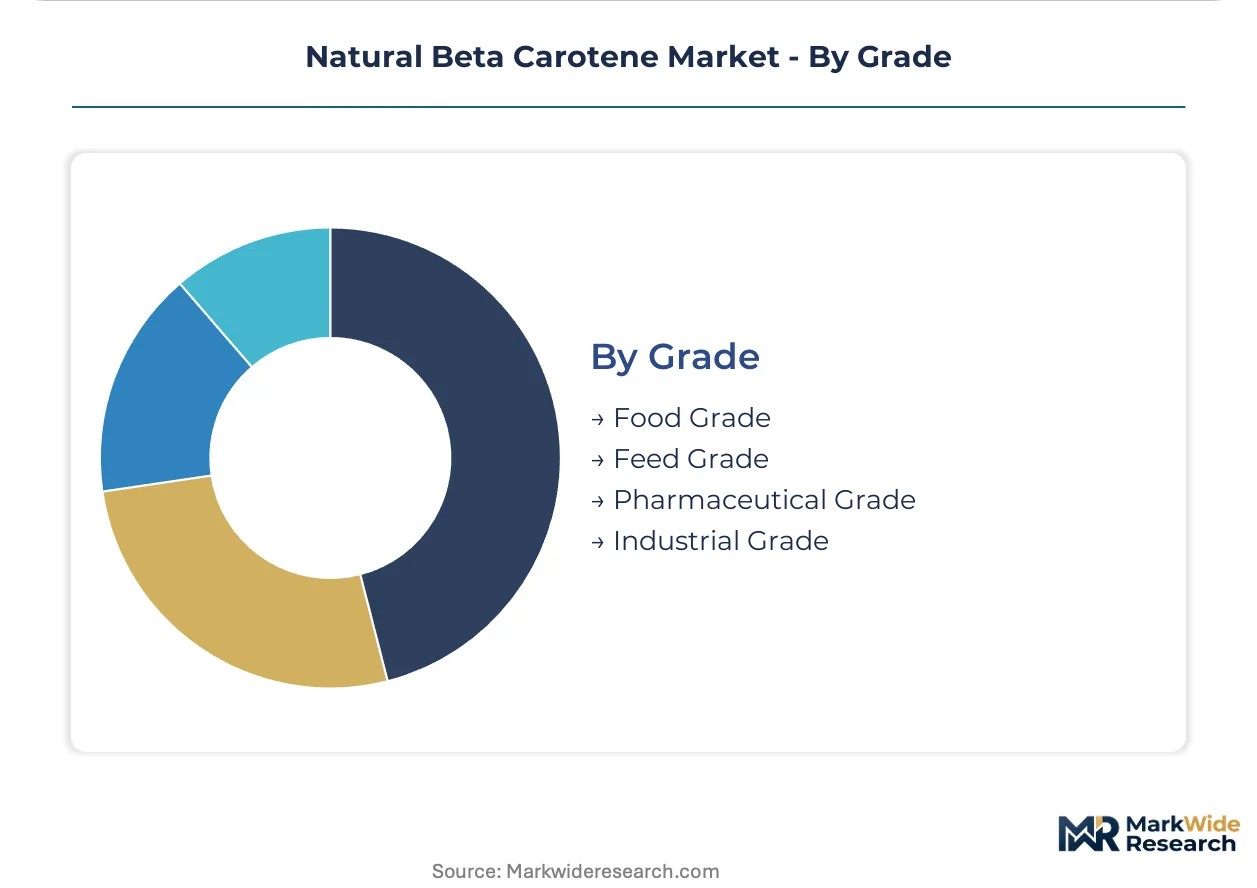
Grade:
Certification tier directly determines accessible customer segments and pricing power in regulated markets.
- Pharmaceutical Grade:USP and EP-compliant specifications with batch-level CoA documentation enable prenatal vitamin and clinical nutrition applications. FDA inspection history and DMF filings create supplier stickiness.
- Food Grade:EFSA and FDA food additive regulations govern purity thresholds for ingestible products with ISO 22000 certification as baseline entry requirement.
- Feed Grade:Lower specification tiers serve animal nutrition with reduced documentation burdens and compressed margins.
- Industrial Grade:Non-ingestible applications in textiles and printing inks operate outside pharmaceutical and food regulatory frameworks.
Pharmaceutical grade captures margin expansion; food grade defends volume position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as EFSA and FDA compliance costs widen the gap between certified and conventional extraction operations. Algae cultivation assets are migrating toward jurisdictions with favorable permitting timelines and renewable energy access.
United States
Pharmaceutical-grade softgel demand from prenatal vitamin manufacturers drives procurement of USP-verified inputs. FDA inspection history and DMF filings create supplier stickiness for domestic encapsulation specialists. California and New York dietary supplement brands are consolidating approved vendor lists around NSF International-certified sources.
Germany
EFSA's 2023 novel food guidance tightens toxicological requirements for modified Dunaliella strains, favoring legacy-approved suppliers. REACH solvent restrictions disqualify hexane-based processors, opening slots for supercritical CO2 operators. Swiss and German pharmaceutical softgel specialists specify EP-compliant inputs for clinical nutrition lines.
China
SAMR's tightening food additive purity standards are compressing unverified domestic supply chains. NMPA pharmaceutical-grade registrations enable access to clinical nutrition and prenatal vitamin exports. Yangtze River Delta fermentation facilities are scaling algae-derived platforms to meet dual carbon goals.
Israel
Dunaliella salina photobioreactor cultivation achieves 15% dry-weight carotenoid content in Negev Desert facilities. The country's national pharmaceutical regulator maintains alignment with USP and EP specifications for export-grade material. Israeli operators leverage year-round solar irradiance to bypass seasonal agricultural constraints affecting carrot and palm oil competitors.
India
FSSAI's 2022 notification permitting algae-derived carotenoids in Ayurvedic formulations opens a 1.4 billion-person addressable market. CDSCO pharmaceutical-grade registrations remain limited, concentrating premium supply among import-dependent formulators. Maharashtra and Gujarat dietary supplement contract manufacturers are qualifying ISO 22000-certified international suppliers.
Natural Beta Carotene Market Competitive Environment
Capacity expansion dominates the current landscape as operators race to secure certified cultivation assets before supply bottlenecks emerge in pharmaceutical-grade segments. The vendor base clusters around three tiers: integrated algae cultivators with photobioreactor assets, fermentation-based specialists leveraging microbial strain platforms, and agricultural extractors defending feed-grade commodity positions. Strategic archetypes include vertically integrated operators controlling cultivation-through-extraction chains, technology licensors monetizing proprietary extraction methods, and regional processors serving local dietary supplement formulators. M&A activity and geographic expansion represent the dominant competitive moves as players seek EFSA and FDA pre-approved supply chains.
Among European-integrated multinationals, BASF SE and DSM Nutritional Products exemplify the asset-heavy archetype with captive cultivation and multi-grade extraction capabilities. Chr. Hansen Holding A/S occupies a specialized position within microbial fermentation platforms for high-purity carotenoid output. These three anchors represent divergent strategic bets on algae photobioreactors versus fermentation scale economics.
| Leading Market Players |
|---|
| BASF SE |
| DSM Nutritional Products |
| Chr. Hansen Holding A/S |
| Lycored |
| Allied Biotech Corporation |
| Givaudan S.A. |
| Divi's Laboratories Limited |
| Cyanotech Corporation |
| Sensient Technologies Corporation |
| Others |
Value Chain & Pricing Dynamics
Supercritical CO2 extraction adoption is compressing production economics for pharmaceutical-grade material while simultaneously concentrating supply among asset-heavy operators who can absorb the capital burden. This technological shift creates pricing power for certified processors as REACH solvent restrictions disqualify conventional hexane-based competitors from European procurement lists.
Pricing Analysis
Distributor margins for natural beta carotene compress at the feed-grade tier while pharmaceutical-grade channels sustain wider spreads through certification premiums. Three-tier pricing structure across pharmaceutical, food, and feed grades reflects differential documentation burdens and purity thresholds. Cost compression in food-grade segments is intensifying as clean-label mandates expand qualified supplier pools. Contract manufacturers exhibit highest price sensitivity, while prenatal vitamin specialists prioritize USP verification over unit cost.
Supply Chain Analysis
Returns and reprocessing flows remain minimal given the ingestible nature of natural beta carotene, though oil suspension batches failing crystallization specifications redirect to feed-grade channels. Supply concentrates in Israel, Australia, and China, with Israeli photobioreactor operators leveraging year-round solar irradiance. Cultivation draws from magnesium nitrate and potassium phosphate feedstocks tethered to energy market volatility. Single-source vulnerability exists for pharmaceutical-grade Dunaliella strains with legacy EFSA approvals. Distribution runs through vertically integrated algae operators and specialized carotenoid distributors serving dietary supplement contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural beta carotene market has entered a late-cycle quality phase where pharmaceutical-grade certification and solvent-free processing capabilities command persistent premiums. This shift reflects prenatal vitamin manufacturers specifying USP-verified algae-derived inputs over commodity agricultural extracts.
For Market Incumbents: Deploy supercritical CO2 capacity expansion to capture procurement slots vacated by REACH-disqualified hexane processors. Secure captive cultivation assets in Israel or Australia to bypass agricultural land constraints and seasonal variability. Consolidate supplier relationships with California and New York dietary supplement brands reducing approved vendor lists from twelve to three certified sources. For New Entrants and Emerging Players: Capture the Ayurvedic formulation opportunity created by FSSAI's 2022 notification permitting algae-derived carotenoids in India's 1.4 billion-person market. Target cosmeceutical encapsulation with liposomal delivery systems commanding 40-60% formulation premiums over bulk powder. Pursue EU Green Deal bioeconomy incentives through co-location with industrial CO2 emitters to offset photobioreactor capital intensity. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier agricultural extractors defending feed-grade commodity positions against algae platform displacement. Long-term viability favors operators with integrated cultivation-through-extraction chains and legacy EFSA strain approvals. Watch for supply bottlenecks in pharmaceutical-grade segments as softgel manufacturers consolidate around three certified sources.| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Capacity Expansion | Israeli operators scale Dunaliella cultivation to 15% dry-weight carotenoid content, bypassing seasonal constraints. |
| Supercritical CO2 Processing Investment | German pharmaceutical softgel specialists adopt solvent-free extraction to meet REACH residual limits and EP compliance. |
| Backward Integration into Algae Cultivation | DSM Nutritional Products secures fermentation-based supply chains through proprietary strain platforms. |
| Pharmaceutical-Grade Certification | USP verification and DMF filings create supplier stickiness for prenatal vitamin encapsulation specialists. |
| Geographic Expansion to India | FSSAI-permitted algae-derived carotenoids in Ayurvedic formulations open access to contract manufacturers in Maharashtra and Gujarat. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews incorporated formulation scientists at dietary supplement contract manufacturers, procurement leads at pharmaceutical softgel specialists, regulatory affairs directors navigating EFSA and FDA additive frameworks, and cultivation engineers at Israeli and Australian photobioreactor facilities. Secondary sources included EFSA novel food guidance documents, FDA food additive regulations, REACH solvent restriction updates, customs trade data for carotenoid imports, and SEC filings from publicly traded ingredient suppliers. Bottom-up volume estimates triangulated against top-down market sizing.
Rate-of-change decomposition separated volume expansion from value premium capture across the projection horizon. Segmentation modeling incorporated product type, application vertical, source material, and certification grade dimensions. CAGRs derived from fitted growth curves applied to historical consumption patterns and projected regulatory adoption timelines. Forecast inputs included EFSA approval timelines for modified Dunaliella strains, FSSAI enforcement patterns for Ayurvedic formulations, and photobioreactor yield improvements from bioprocess engineering advances.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision than feed-grade commodity flows given documentation requirements. Forecasts reflect assumptions regarding regulatory enforcement consistency, algae cultivation scale economics, and clean-label definition evolution. Supply disruption from fertilizer cost volatility or extended EFSA approval timelines could materially revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Calcium-Fortified Food Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
High Calcium Fortified Food Market