
 Global Quercetin Market | 2026-2036
Global Quercetin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Quercetin Market Foresight
Plant-based extraction automation is reconfiguring how quercetin manufacturers achieve batch consistency and solvent recovery rates. Sichuan Xieli Pharmaceutical leverages vertical integration from Sophora japonica cultivation through final powder output. Merck KGaA anchors its position through pharmaceutical-grade HPLC validation protocols that exceed compendial standards. Kingherbs Limited specializes in botanical raw material sourcing across multiple flavonoid streams.
Quercetin is a flavonol glycoside with the molecular formula C15H10O7, typically extracted from onion skins, apples, or Sophora japonica flowers through ethanol or water-based solvent systems; manufacturers target minimum 95% purity for dietary supplement applications and 98% plus for pharmaceutical formulations. Powder formulations dominate current volume due to lower production complexity and broader blending compatibility across end-use matrices. Nanoemulsion technology represents the fastest-expanding processing segment as bioavailability enhancement becomes a critical purchasing criterion for sports nutrition brands. Dietary supplements command the largest application share, though pharmaceutical-grade demand is accelerating where clinicians prescribe quercetin for adjuvant anti-inflammatory protocols.
FDA dietary supplement GMPs, EFSA novel food assessments, and China's NMPA traditional medicine registration pathways collectively determine market access timelines and purity labeling requirements for cross-border quercetin commerce. REACH compliance for imported botanical extracts adds testing burden for European-bound shipments from Asian manufacturers. Stakeholders must monitor evolving pharmacopeial monograph harmonization between USP, EP, and ChP standards as divergence in heavy metal limits and residual solvent thresholds directly shapes supplier qualification costs and competitive positioning.
Market Dynamics
Pharmaceutical-grade purity mandates from EFSA and FDA are compressing supplier margins while rewarding manufacturers with validated HPLC protocols and captive Sophora japonica cultivation networks.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined safety assessments for purified quercetin extracts are accelerating dietary supplement approvals across EU member states.
- Nanoemulsion bioavailability platforms:Sports nutrition brands now specify particle-size specifications below 200 nanometers in procurement contracts.
- Cardiovascular adjuvant protocols:German naturopathic practitioners are expanding flavonoid prescriptions beyond traditional antioxidant applications.
Market Restraints
- Raw material concentration:Sophora japonica flower supply concentrates in Sichuan and Shandong provinces, creating geographic vulnerability to climate disruption.
- Residual solvent thresholds:REACH compliance for ethanol and hexane traces adds EUR 15,000-25,000 per batch testing burden for Asian exporters.
- Synthetic substitute competition:Chemically produced rutin derivatives from pharmaceutical intermediates compete on cost for non-premium applications.
Strategic Opportunities
- Indian Ayurvedic integration:FSSAI functional food regulations are opening pathways for flavonoid-fortified traditional medicine formats.
- Cosmeceutical topical delivery:Liposomal encapsulation technologies are penetrating premium skincare formulations in South Korea.
- Direct-to-practitioner channels:Specialized distributors are bypassing retail intermediaries to serve integrative medicine clinics in Australia.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent heavy metal limits between USP, EP, and ChP standards force redundant testing protocols.
- Specialized extraction workforce:Scarcity of technicians trained in supercritical CO2 and pressurized liquid extraction systems constrains capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Quercetin Market |
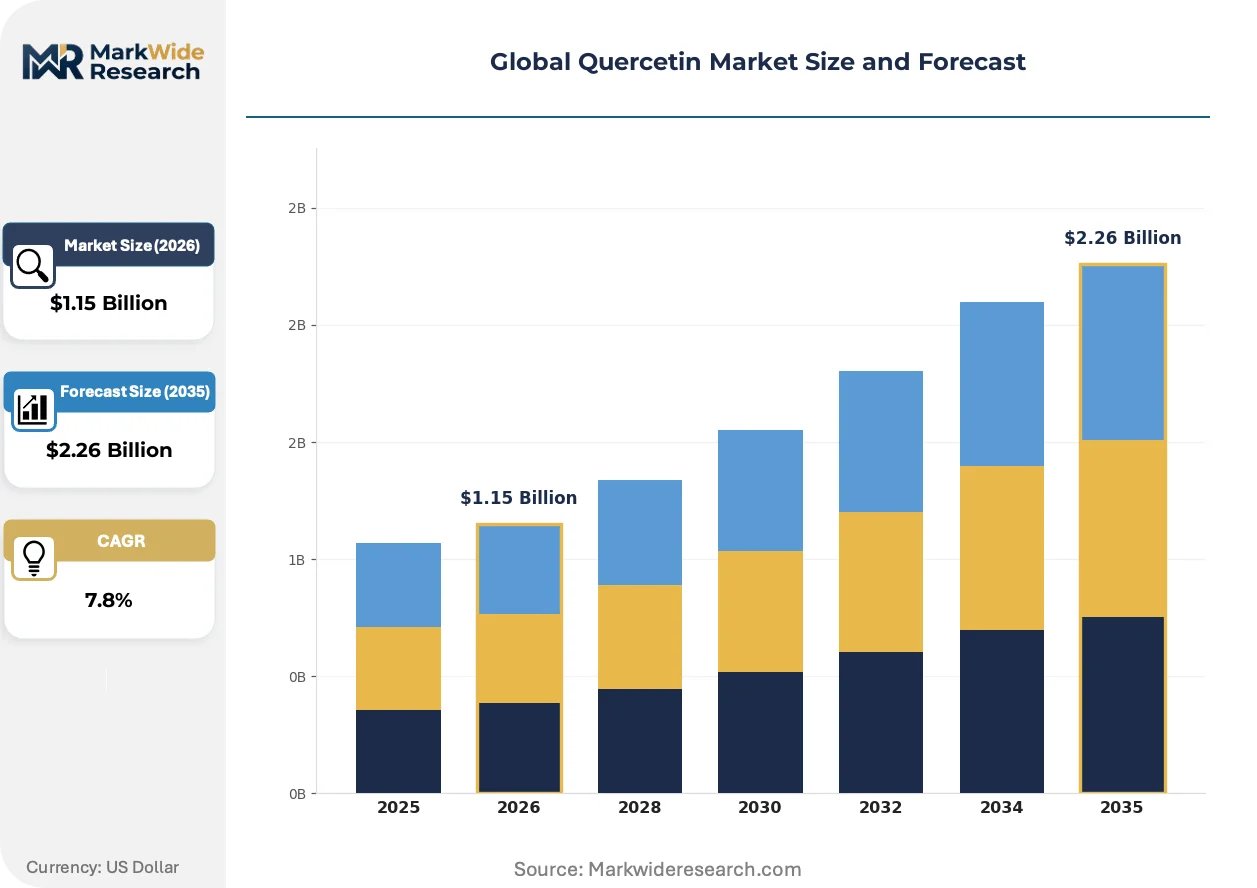
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.26 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tablets, Liquid Extracts, Functional Foods Technology: High-Performance Liquid Chromatography, Ultrasonic Extraction, Spray Drying, Nanoemulsion Application: Dietary Supplements, Cosmetics, Pharmaceuticals, Animal Nutrition, Sports Nutrition End User: Nutritionists, Dermatologists, Pharmacists, Veterinarians, Fitness Trainers |
| Companies Covered | Sichuan Xieli Pharmaceutical, Monteloeder SL, Merck KGaA, Kingherbs Limited, Innophos, Inc., Indena S.p.A., Chengdu Chenlv Biological Technology, Natrol LLC, Sichuan Benepure Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Quercetin Market Shifts & Advancements
Processing technology and regulatory science are converging to redefine competitive advantage around validated purity rather than commodity volume, with bioavailability enhancement emerging as the decisive purchasing criterion.
Continuous flow chemistry systems for flavonoid extraction are rendering obsolete batch reactor operations that dominated Sophora japonica processing for decades. Pharmaceutical contract manufacturers in Switzerland and Germany are retrofitting facilities at pace. This compression of cycle times and solvent volumes is rendering obsolete the traditional cost advantage of manual batch operations in low-labor-cost jurisdictions.
REACH Annex XVII updates for botanical extracts are tightening residual solvent and pesticide maximum residue limits for European-bound shipments. Manufacturers in China and India face expanded documentation requirements for every production lot. Dietary supplement distributors are responding by consolidating supplier relationships around REACH-registered producers with established only-representative structures.
Buyer specifications now routinely incorporate bioequivalence data rather than simple purity certificates. Sports nutrition and clinical nutrition procurement teams are disqualifying suppliers lacking pharmacokinetic studies. This credential-driven selection pattern is most pronounced in Germany and Australia, where practitioner-channel brands command price premiums for validated absorption profiles.
Global Quercetin Market Segmentation
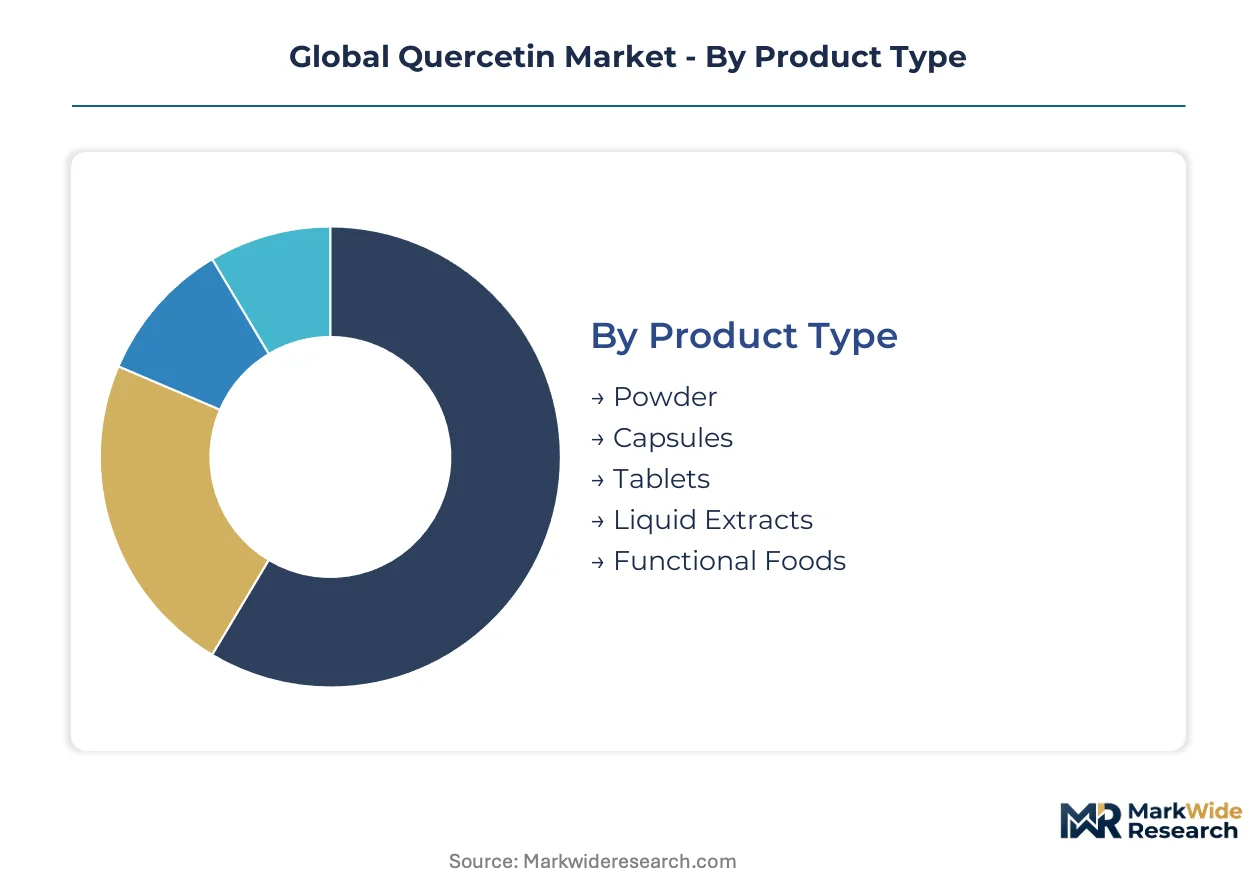
Quercetin manufacturers configure production lines around distinct specification tiers that demand varying degrees of post-sale technical support. Each segment carries unique purity thresholds, stability requirements, and regulatory documentation burdens that reshape supplier-customer relationships.
Product Type:
After-sales service intensity varies dramatically across physical formats, with liquid and functional food applications demanding formulation troubleshooting that powder suppliers rarely provide.
- Powder:Bulk crystalline or micronized quercetin with 95-98% purity specifications serves contract manufacturers and compounding pharmacies. German dietary supplement brands specify particle size distributions below 50 microns for direct compression tablet production.
- Capsules:Pre-encapsulated quercetin with excipient blends addresses bioavailability concerns through lipid-based delivery systems. Sports nutrition distributors in Australia increasingly require dissolution profile certificates with every lot.
- Tablets:Compressed formulations with binders and disintegrants target retail pharmacy channels where shelf stability exceeds 24 months. Stability testing protocols add documentation burden for exporters to REACH jurisdictions.
- Liquid Extracts:Ethanol or glycerin-based solutions with standardized flavonoid content serve functional beverage manufacturers. Preservative compatibility testing creates ongoing technical support obligations.
- Functional Foods:Microencapsulated quercetin for baked goods and dairy applications requires heat stability validation. FSSAI registration in India mandates additional safety documentation for novel food formats.
By volume, Powder leads. By growth pace, Functional Foods is ahead.
Technology:
Capital deployment and operating cost structures diverge sharply across purification and delivery platforms, with continuous processing systems commanding premium pricing.
- High-Performance Liquid Chromatography:Analytical and preparative HPLC systems deliver pharmaceutical-grade purity verification exceeding compendial standards. Swiss contract manufacturers leverage HPLC validation to access clinician-directed channels.
- Ultrasonic Extraction:Cavitation-assisted solvent systems reduce extraction times and thermal degradation of flavonoid structures. Chinese Sophora japonica processors deploy ultrasonic units to meet EFSA residual solvent limits.
- Spray Drying:Atomization and hot air dehydration convert liquid extracts into stable powders with controlled moisture content. South Korean cosmeceutical brands specify spray-dried quercetin for hygroscopic stability in topical formulations.
- Nanoemulsion:High-pressure homogenization produces sub-200 nanometer particles for enhanced bioavailability. Sports nutrition procurement teams in Germany now mandate particle size distribution certificates.
By installed base, Spray Drying leads. By investment velocity, Nanoemulsion is climbing the fastest.
Application:
Regulatory pathway complexity and end-user sophistication create distinct margin profiles across consumption contexts.
- Dietary Supplements:Capsule, tablet, and powder formats for daily antioxidant and cardiovascular support regimens. EFSA novel food approvals are streamlining access across EU member states.
- Cosmetics:Topical formulations targeting anti-inflammatory and photoprotective claims. South Korean liposomal encapsulation technologies are penetrating premium skincare lines.
- Pharmaceuticals:Adjuvant anti-inflammatory protocols prescribed by German naturopathic practitioners. NMPA traditional medicine registration in China adds documentation requirements for clinical-grade supply.
- Animal Nutrition:Feed additives for livestock antioxidant support and stress reduction. Veterinary prescription pathways vary across national regulatory frameworks.
- Sports Nutrition:Pre- and post-workout formulations emphasizing recovery and oxidative stress management. Australian integrative medicine clinics drive demand for validated absorption profiles.
By revenue concentration, Dietary Supplements leads. By prescription velocity, Pharmaceuticals is gaining share fastest.
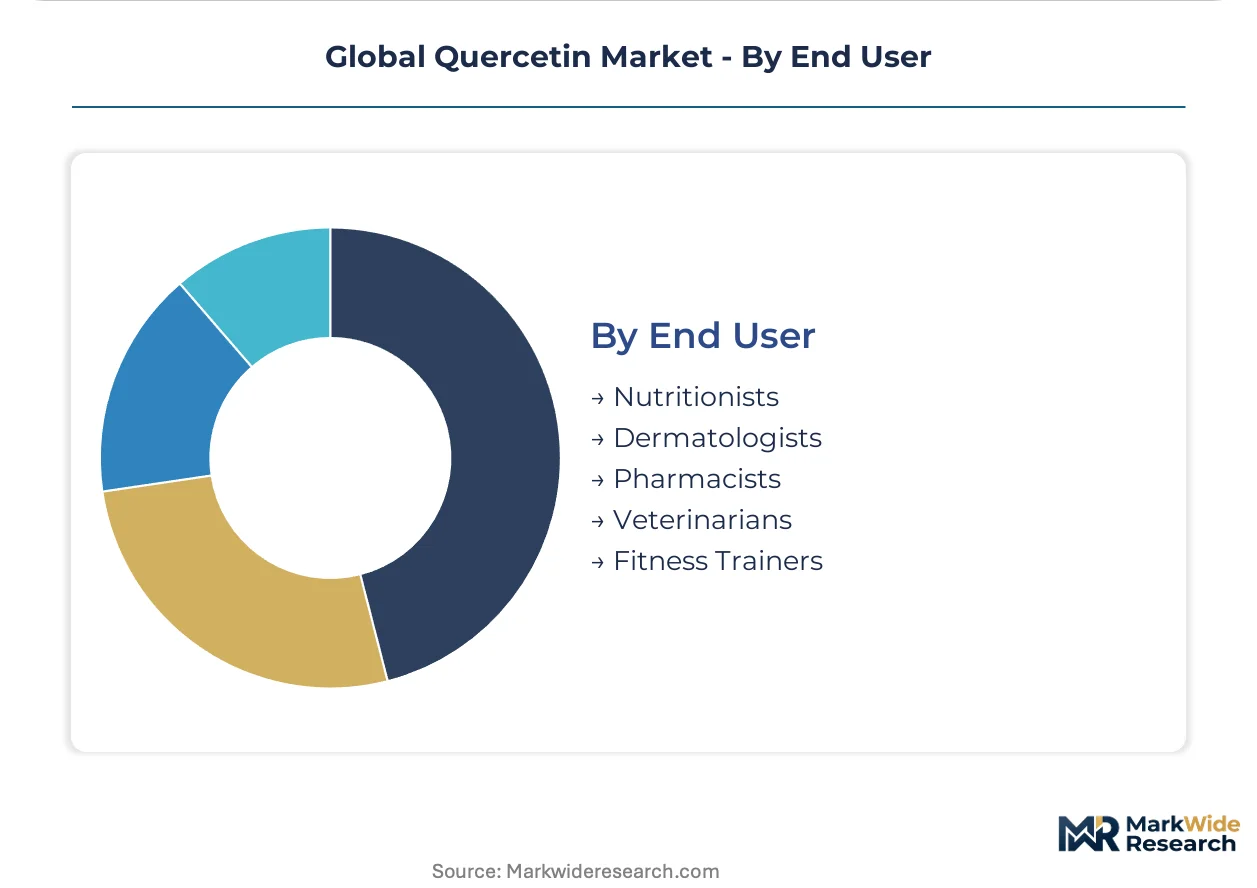
End User:
Professional channel access determines pricing power and brand loyalty intensity across practitioner categories.
- Nutritionists:Clinical and sports nutrition professionals specifying quercetin for immune and cardiovascular protocols. German practitioner-channel brands command price premiums for bioequivalence documentation.
- Dermatologists:Skin health specialists incorporating flavonoid therapies into topical and systemic regimens. South Korean cosmeceutical distribution runs through dermatology clinic networks.
- Pharmacists:Community and hospital pharmacy professionals dispensing pharmaceutical-grade formulations. Swissmedic oversight in Switzerland creates compliance barriers for non-registered suppliers.
- Veterinarians:Animal health practitioners prescribing flavonoid supplements for companion and production animals. Regulatory fragmentation across veterinary pharmaceutical frameworks complicates cross-border supply.
- Fitness Trainers:Sports performance coaches recommending recovery and antioxidant support products. Direct-to-practitioner channels in Australia bypass retail intermediaries.
By channel volume, Nutritionists lead. By prescription growth, Dermatologists is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports bulk quercetin extracts to Germany and the United States, where pharmaceutical-grade purification and finished-formulation manufacturing command premium pricing. This trade corridor concentrates raw material cultivation in Sichuan and Shandong provinces while downstream value capture accrues to REACH-registered processors and clinician-channel brands in Western Europe and North America.
Germany
German naturopathic practitioners prescribe quercetin for cardiovascular adjuvant protocols, expanding flavonoid applications beyond traditional antioxidant use. EFSA novel food assessments streamline dietary supplement approvals across EU member states. The Baden-Württemberg cluster hosts pharmaceutical contract manufacturers retrofitting facilities with continuous flow chemistry systems for flavonoid extraction.
United States
FDA dietary supplement GMPs shape procurement criteria for sports nutrition brands seeking validated bioavailability data. The agency's enforcement of 21 CFR Part 111 compels importer verification of foreign supplier compliance. Greater Boston anchors clinical nutrition research, where integrative medicine clinics demand pharmacokinetic documentation for practitioner-channel products.
China
NMPA traditional medicine registration pathways determine market access timelines for pharmaceutical-grade quercetin destined for hospital pharmacies. The Sichuan-Chongqing region concentrates Sophora japonica cultivation and extraction capacity. Chengdu-based processors deploy ultrasonic extraction units to meet EFSA residual solvent limits for European-bound shipments.
Switzerland
Swissmedic oversight creates compliance barriers for non-registered suppliers accessing clinician-directed distribution channels. The country's pharmaceutical contract manufacturers leverage HPLC validation protocols exceeding compendial standards. Basel-Zurich corridor facilities specialize in preparative chromatography for pharmaceutical-grade flavonoid purification.
Australia
TGA regulations govern complementary medicine listings for quercetin products sold through integrative medicine clinics. Direct-to-practitioner channels bypass retail intermediaries, concentrating demand in Sydney and Melbourne metropolitan areas. Sports nutrition procurement teams disqualify suppliers lacking particle-size distribution certificates below 200 nanometers.
Global Quercetin Market Competitive Landscape
On the supply side, the industry is bifurcated between bulk extractors serving commodity dietary supplement markets and integrated processors capturing pharmaceutical-grade premiums. Chinese cultivator-processors dominate upstream Sophora japonica supply, while European and North American firms control downstream formulation and distribution. Three archetypes define competitive positioning: vertically integrated botanical specialists, pharmaceutical-grade validation laboratories, and sports nutrition bioavailability innovators. Capacity expansion and REACH registration consolidation represent the dominant competitive moves as Asian exporters absorb compliance costs.
Among Chinese cultivator-processors, Sichuan Xieli Pharmaceutical and Sichuan Benepure Pharmaceutical occupy positions spanning raw material cultivation through bulk powder output. Merck KGaA represents the pharmaceutical-grade validation archetype, anchoring its market presence through analytical protocols that exceed compendial standards. Kingherbs Limited exemplifies the botanical sourcing specialist model, maintaining multi-flavonoid raw material networks across producing regions.
| Leading Market Players |
|---|
| Sichuan Xieli Pharmaceutical |
| Monteloeder SL |
| Merck KGaA |
| Kingherbs Limited |
| Innophos, Inc. |
| Indena S.p.A. |
| Chengdu Chenlv Biological Technology |
| Natrol LLC |
| Sichuan Benepure Pharmaceutical |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor absorbs volatile bunker fuel costs that cascade through Sophora japonica extract shipments, compressing margins for Chinese processors while amplifying price spreads between pharmaceutical-grade and commodity-tier quercetin in European distribution channels.
Pricing Analysis
Batch-reactor extraction technology commands economy-tier pricing, continuous flow chemistry systems anchor standard-tier positioning, and nanoemulsion bioavailability platforms capture premium-tier margins. Price differentiation hinges on HPLC validation depth and REACH registration status, with unregistered Asian exporters facing cost compression from redundant testing protocols. Margins are tightening due to EFSA residual solvent threshold enforcement. Dietary supplement contract manufacturers exhibit highest price sensitivity; clinician-channel brands in Germany demonstrate lowest sensitivity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment for quercetin shipments. Raw material cultivation concentrates in Sichuan and Shandong provinces, extraction capacity clusters in Chengdu and Chongqing, and downstream formulation rests on Swiss and German pharmaceutical contract manufacturers. Critical dependencies include Sophora japonica flower supply, ethanol solvent availability, and HPLC-grade acetonitrile for validation. Distribution runs through REACH-registered only-representative structures serving clinician-directed channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quercetin markets are recovering from regulatory compliance cost cyclicality, with EFSA novel food pathway streamlining poised to release pent-up formulation demand across EU member states.
For Market Incumbents: Entrench pharmaceutical-grade positioning through captive Sophora japonica cultivation networks and preparative HPLC capacity expansion in Basel-Zurich corridor facilities. Synthetic rutin derivative competition threatens commodity-tier margins; backward integration into ultrasonic extraction units mitigates REACH residual solvent compliance burdens. For New Entrants and Emerging Players: Indian functional food applications under FSSAI jurisdiction represent the most penetrable entry point for microencapsulated quercetin heat-stability formats. South Korean cosmeceutical liposomal encapsulation demand offers secondary white-space targeting. Direct partnerships with dermatology clinic networks bypass entrenched distributor relationships. For Investors and Strategic Acquirers: REACH Annex XVII updates reshaping the acquisition landscape favor processors with established only-representative structures and validated pharmacokinetic documentation. Five-to-ten year viability centers on bioavailability-enhanced delivery platform ownership. Target acquisition archetype: Swiss-German contract manufacturers with continuous flow chemistry retrofit completion. Signal to watch: sports nutrition procurement mandates for sub-200 nanometer particle size certificates.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Retrofit | Swiss and German contract manufacturers compress extraction cycle times and solvent volumes below batch-reactor benchmarks. |
| REACH Only-Representative Registration | Chinese and Indian exporters consolidate European market access through established regulatory representation structures. |
| Nanoemulsion Bioavailability Platform | Sports nutrition brands in Germany and Australia specify particle-size certificates below 200 nanometers in procurement contracts. |
| Captive Sophora Japonica Cultivation | Sichuan-based processors secure raw material supply against climate disruption vulnerability in concentrated growing regions. |
| Direct-to-Practitioner Channel Development | Australian integrative medicine clinics bypass retail intermediaries, concentrating demand in Sydney and Melbourne metropolitan corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with naturopathic prescribing clinicians, dietary supplement procurement managers, pharmaceutical contract manufacturing executives, and botanical extraction technical directors. Secondary validation drew from EFSA novel food assessment registers, REACH Annex XVII update notices, NMPA traditional medicine filings, and USP-EP-ChP pharmacopeial monograph harmonization working documents. Bottom-up volume modeling from cultivation acreage through extraction yield rates was triangulated against top-down expenditure tracking across end-use application segments.
Calibration against historical price realization data and installed capacity announcements across Sichuan and Shandong processing zones anchored the analytical framework. Segmentation dimensions modeled include product format tier, purification technology generation, application regulatory pathway, and end-user professional channel. CAGRs were derived from slope analysis of segment-specific demand curves adjusted for compliance cost absorption rates. Forecast inputs incorporated Sophora japonica harvest yield variability and EFSA residual solvent limit enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in maritime freight rates, ethanol commodity pricing, or euro-yuan exchange volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway streamlining timelines and pharmacopeial harmonization progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Riboflavin Market