
 Fat Soluble Vitamins Market | 2026-2036
Fat Soluble Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Soluble Vitamins Market Foresight
Pre-mixed vitamin bundles for bone and immune health is shifting how retail consumers evaluate value. DSM-Firmenich leverages its integrated premix capabilities to anchor supply relationships with major food fortification programs. BASF SE sustains technology leadership in microencapsulation processes that protect vitamin stability. Zhejiang NHU Co., Ltd. dominates bulk vitamin E production, competing on manufacturing scale rather than formulation services.
Fat soluble vitamins comprise four organic compounds—vitamin A (retinol), vitamin D (calciferol), vitamin E (tocopherols), and vitamin K (phylloquinone, menaquinones)—that require dietary lipids for intestinal absorption and hepatic storage, with primary commercial purpose spanning nutritional fortification, clinical deficiency correction, and animal feed supplementation. Vitamin D commands structural prominence due to regulatory mandates for food fortification across multiple geographies and expanding clinical applications in bone metabolism management. Powders and liquids represent the fastest-growing form categories, driven by functional beverage integration and pediatric formulation requirements where swallowing capsules presents compliance barriers.
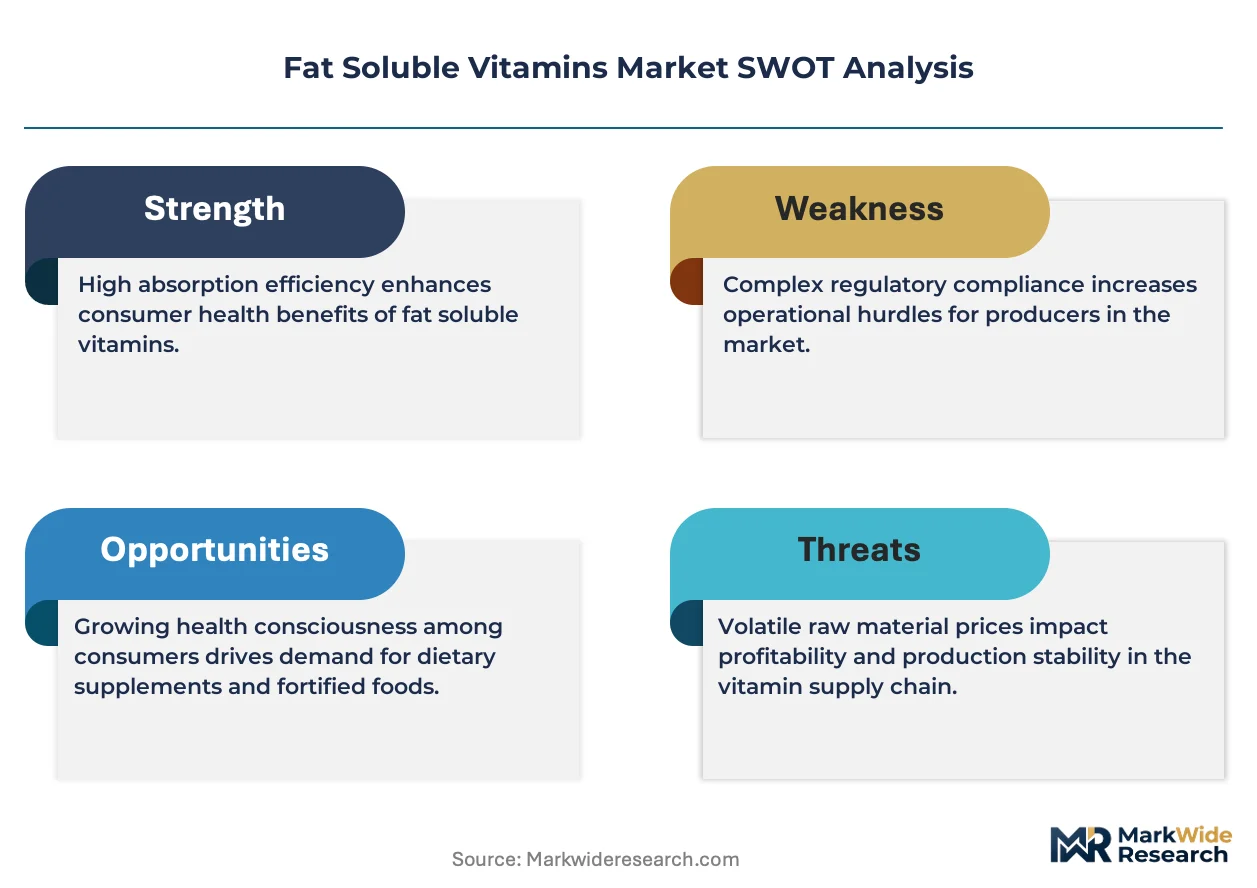
The FDA oversees dietary supplement Current Good Manufacturing Practice regulations that dictate identity, purity, and composition standards for vitamin products distributed in the United States, while the European Food Safety Authority evaluates novel food applications and health claim substantiation under EU-wide frameworks. India's FSSAI has tightened micronutrient labeling requirements for fortified staples, creating compliance thresholds for imported vitamin premixes. Stakeholders must monitor divergence between pharmacopeial standards and evolving national fortification mandates to align manufacturing investments with jurisdiction-specific enforcement trajectories.
Market Dynamics
Microencapsulation technology advances are compressing stability premiums and forcing premix suppliers to differentiate through formulation services rather than raw vitamin supply alone.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:Mandatory substantiation requirements for bone and immune health claims are driving demand for clinically validated vitamin D premixes in fortified dairy and infant nutrition.
- Pediatric formulation compliance:Liquid and powder formats are capturing share from capsules as parents and healthcare providers prioritize swallowing ease for children and elderly patients.
- Animal feed micronutrient mandates:Broiler and layer operations in Southeast Asia are accelerating vitamin E and K3 supplementation to meet export certification standards for poultry products.
Market Restraints
- Isopropanol and acetone cost volatility:Vitamin E synthesis depends on these petrochemical feedstocks, exposing margins to crude oil price swings and refinery capacity constraints.
- Zhejiang NHU bulk concentration:Over half of global vitamin E acetate capacity sits with one Chinese manufacturer, creating single-source vulnerability for Western formulators.
- Lipid malabsorption limitations:Bariatric surgery patients and cystic fibrosis sufferers require emulsified or water-dispersible forms, adding formulation complexity and cost.
Strategic Opportunities
- India FSSAI fortification expansion:Edible oil and wheat flour mandates are opening premix procurement contracts for vitamin A and D at state-level distribution scale.
- Personalized nutrition platforms:At-home micronutrient testing services are creating direct-to-consumer channels for bespoke vitamin ADEK combinations based on blood panel results.
- Microbiome-vitamin K2 convergence:Menaquinone-7 producers are targeting fermented food and synbiotic applications as gut health positioning extends beyond bone benefits.
Industry Challenges
- Analytical method standardization:USP and EP monograph divergence for vitamin D3 potency assays creates batch release delays and dual testing costs for multinational suppliers.
- Cross-functional formulation expertise:Food technologists with simultaneous competence in lipid chemistry, spray-drying, and regulatory dossier preparation command scarcity premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Soluble Vitamins Market |
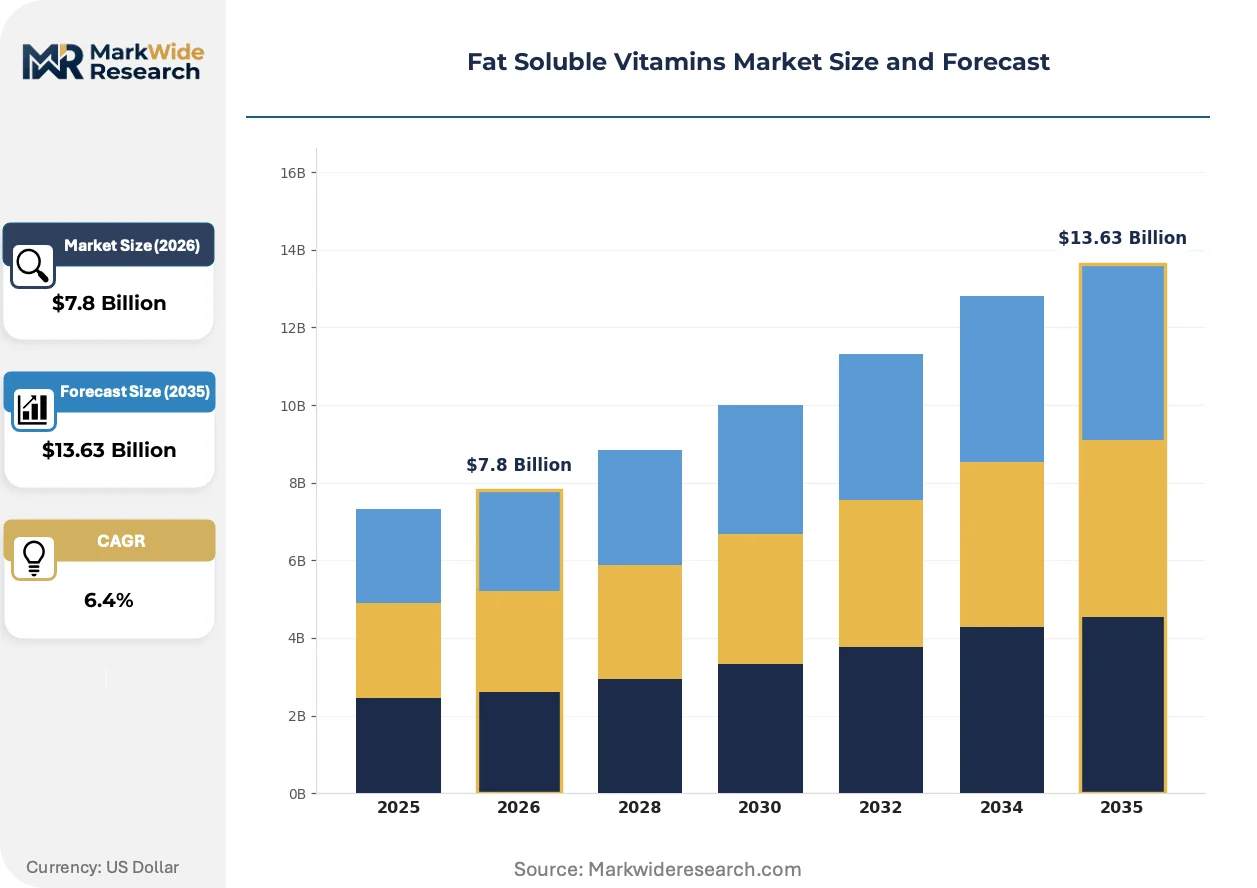
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin A, Vitamin D, Vitamin E, Vitamin K Form: Capsules, Tablets, Powders, Liquids End User: Retail Consumers, Healthcare Providers, Fitness Centers, Pharmacies Packaging Type: Bottles, Blister Packs, Bulk Containers, Sachets |
| Companies Covered | DSM-Firmenich, BASF SE, Archer Daniels Midland Company, Lonza Group AG, Pfizer Inc., Roche Vitamins, Eastman Chemical Company, Zhejiang NHU Co., Ltd., Glanbia Nutritionals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Soluble Vitamins Market Shifts & Advancements
Delivery format innovation and regulatory claim substantiation are compressing traditional premix margins while opening service-based revenue streams for integrated suppliers.
Lipid nanoparticle dispersion systems are rewriting bioavailability benchmarks for fat-soluble vitamins in functional beverages. Beverage manufacturers in Germany and California are adopting these systems at pilot scale to achieve clarity in clear-format drinks previously incompatible with oil-soluble actives. The technology is rewriting competitive positioning by collapsing the historical trade-off between stability and sensory acceptance.
EFSA's 2023 updated guidance on vitamin D upper limits is tightening maximum permitted levels in supplements across EU member states. The industrial consequence is reformulation cycles for multivitamin products previously formulated at 4000 IU per serving. Nordic markets are responding fastest, with Swedish and Finnish manufacturers already adjusting SKUs to comply with the revised tolerable upper intake level framework.
Pediatric and geriatric swallowing difficulties are accelerating liquid format preference over softgel capsules in direct-to-consumer channels. Amazon and specialty pharmacy platforms are displacing traditional retail pharmacy for these demographics, with subscription models capturing recurring purchase behavior. This shift is most visible in United States and United Kingdom markets where caregiver purchasing decisions dominate household vitamin procurement.
Fat Soluble Vitamins Market Segmentation
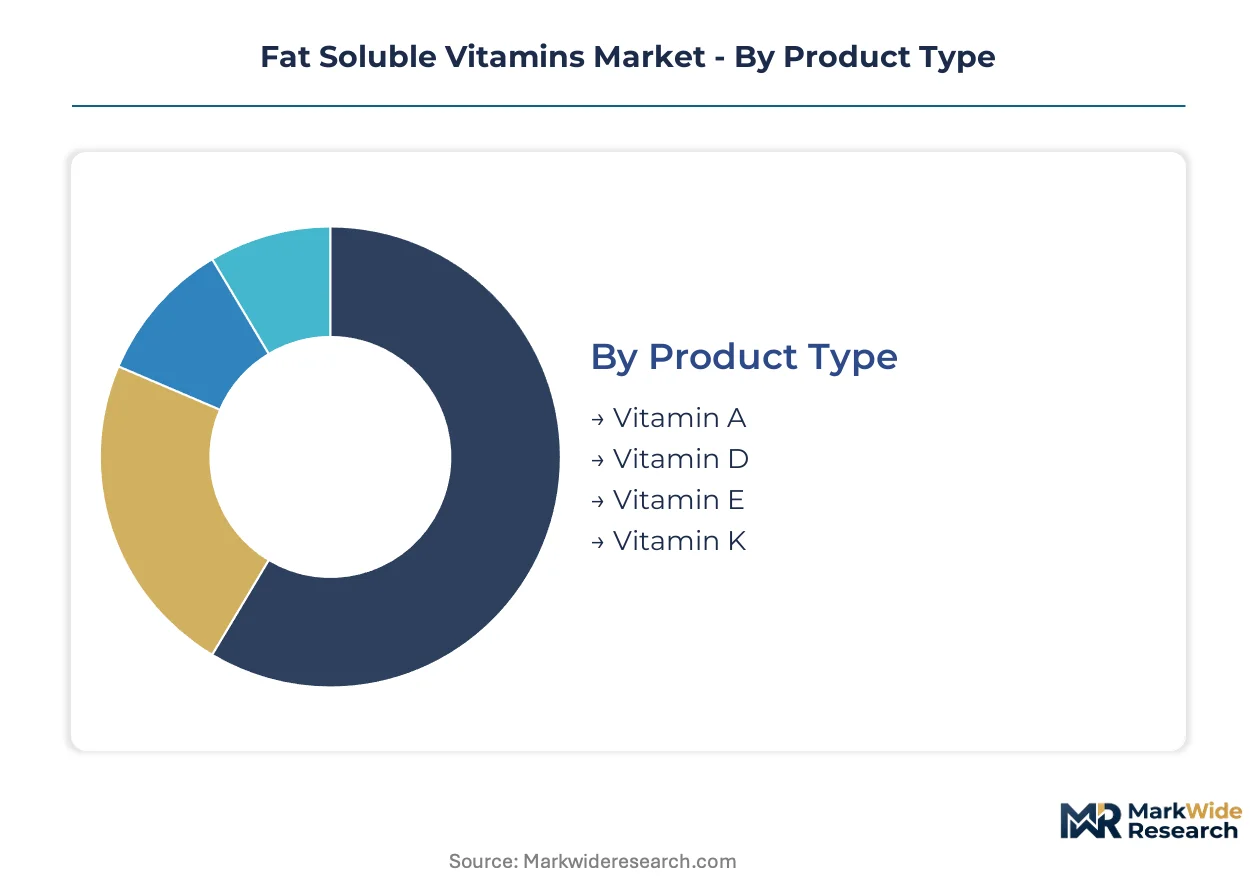
Segmentation in fat soluble vitamins reflects divergent absorption kinetics, formulation stability requirements, and channel economics. Manufacturers must align production assets with specific end-use compliance thresholds rather than treating vitamins as interchangeable commodities.
Product Type:
Biochemical structure determines solubility profiles, storage stability, and regulatory classification across jurisdictions.
- Vitamin D:Calciferol compounds dominate fortification mandates for dairy and infant nutrition. EFSA substantiation requirements for bone health claims are accelerating demand for clinically validated cholecalciferol premixes in EU member states.
- Vitamin E:Tocopherols and tocotrienols serve dual markets in human supplements and animal feed export certification. Zhejiang NHU's manufacturing concentration exposes Western formulators to single-source supply vulnerability for acetate esters.
- Vitamin A:Retinol palmitate and acetate forms anchor food fortification programs for deficiency correction in developing economies.
- Vitamin K:Phylloquinone and menaquinone variants target niche applications in coagulation management and emerging synbiotic positioning.
Mature deployment sits with Vitamin E. Newer deployment is concentrated in Vitamin K2 menaquinone-7 for microbiome-targeted applications.
Form:
Physical state dictates bioavailability engineering, shelf-life architecture, and patient compliance economics.
- Powders:Spray-dried and agglomerated formats enable functional beverage integration and pediatric formulation where swallowing barriers exist. Lipid nanoparticle dispersion systems are rewriting clarity standards for clear-format drinks in German and California pilot facilities.
- Liquids:Emulsified and micellar solutions address lipid malabsorption in bariatric and cystic fibrosis populations. Amazon and specialty pharmacy subscription models are displacing retail pharmacy for geriatric and pediatric demographics in the United States and United Kingdom.
- Capsules:Softgel and hardshell formats retain cost efficiency for adult supplement routines but face share erosion from liquid alternatives.
- Tablets:Compressed forms dominate mass-market multivitamin economics despite slower dissolution kinetics.
Volume leadership remains with tablets. Steepest expansion trajectory belongs to powders driven by beverage format innovation.
End User:
Purchasing authority and clinical oversight requirements fragment channel economics and compliance burdens.
- Retail Consumers:Direct-to-consumer purchasing through e-commerce platforms and mass retail. Subscription models capture recurring behavior for household vitamin procurement.
- Healthcare Providers:Clinical settings requiring therapeutic-grade specifications and documentation for deficiency correction protocols.
- Pharmacies:Professional counseling environments with pharmacist-mediated selection for drug-interaction screening.
- Fitness Centers:Adjacent retail positioning for performance-oriented micronutrient stacks with lower clinical oversight thresholds.
Revenue concentration sits with retail consumers. Margin expansion is concentrated in healthcare provider channels with therapeutic-grade requirements.
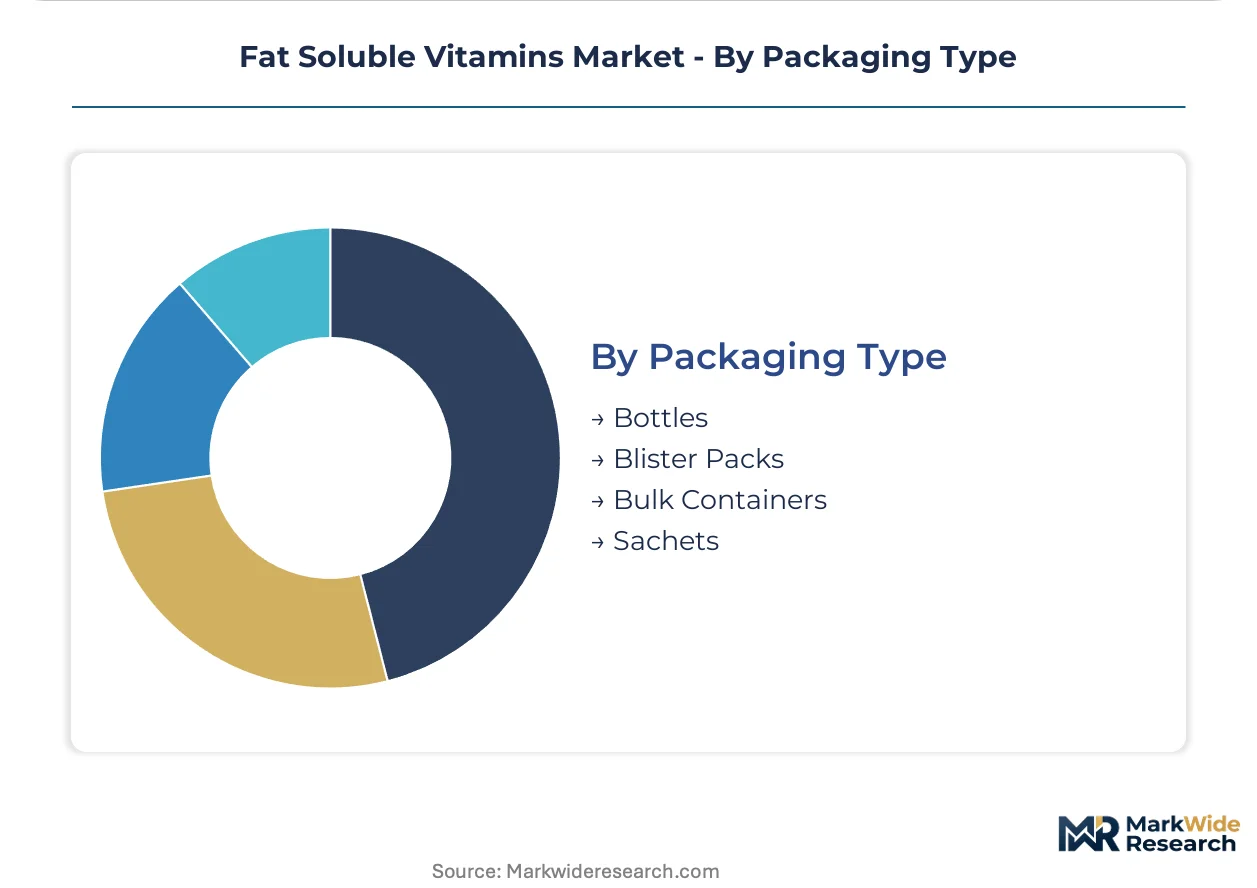
Packaging Type:
Unit economics and stability protection drive format selection across humidity-sensitive and oxidation-prone actives.
- Bottles:HDPE and glass containers with desiccant systems for high-volume SKUs in mass retail distribution.
- Blister Packs:Unit-dose aluminum-PVC laminates for oxidation protection and compliance tracking in clinical and travel segments.
- Sachets:Single-serve flexible formats for powder and liquid sampling in direct-to-consumer acquisition campaigns.
- Bulk Containers:Industrial totes and drums for premix supply to food manufacturers and animal feed compounders.
Unit-dose protection dominates blister packs. Scale efficiency is concentrated in bulk containers for B2B premix supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentration in bulk vitamin E acetate contrasts with consumption gravity in fortified food and supplement channels across North America, Europe, and Asia-Pacific. Manufacturing scale advantages in China supply Western formulators facing regulatory complexity in multiple jurisdictions. Demand fragmentation across pediatric, geriatric, and clinical segments reshapes regional procurement priorities.
United States
FDA Current Good Manufacturing Practice regulations enforce identity and purity standards for dietary supplements distributed through direct-to-consumer channels and mass retail. The agency's oversight of therapeutic-grade specifications creates compliance thresholds for deficiency correction products. DSM-Firmenich maintains integrated premix capabilities serving major food fortification programs from Midwest manufacturing positions.
Germany
EFSA's 2023 revised vitamin D upper limits are forcing reformulation cycles for multivitamin products previously formulated at higher serving levels. Lipid nanoparticle dispersion systems from Bavarian pilot facilities are achieving clarity benchmarks for functional beverages previously incompatible with oil-soluble actives. BASF SE sustains technology leadership in microencapsulation processes protecting vitamin stability across temperature variations.
China
Zhejiang NHU Co., Ltd. dominates bulk vitamin E acetate production, concentrating over half of global capacity in a single manufacturing position. The country's national pharmaceutical regulator evaluates novel food applications under frameworks converging with international standards. Yangtze River Delta chemical clusters supply petrochemical feedstocks for vitamin E synthesis, exposing margins to crude oil price volatility.
India
FSSAI fortification mandates for edible oil and wheat flour are opening state-level premix procurement contracts for vitamin A and D at distribution scale. The regulator's tightened micronutrient labeling requirements create compliance thresholds for imported vitamin premixes. Gujarat and Maharashtra industrial corridors host formulation facilities serving domestic fortified staple programs and export markets.
United Kingdom
Amazon and specialty pharmacy subscription models are displacing traditional retail pharmacy for liquid and powder formats serving pediatric and geriatric swallowing difficulties. The country's national pharmaceutical regulator maintains pharmacopeial standards diverging from USP monographs on vitamin D3 potency assays. Greater London distribution hubs coordinate pan-European supply despite post-Brexit customs complexity.
Fat Soluble Vitamins Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation services and bulk supply segments. Market structure shows tiered concentration, with integrated premix suppliers commanding premium positioning against commodity-scale manufacturers. Three archetypes dominate: technology-led encapsulation specialists, scale-driven bulk producers, and service-integrated formulation partners. Competitive moves center on backward integration into raw vitamin supply and geographic expansion into fortification-mandate jurisdictions.
Among diversified chemical conglomerates, BASF SE and DSM-Firmenich exemplify integrated positioning spanning microencapsulation technology and premix formulation services. Zhejiang NHU Co., Ltd. occupies the scale-driven archetype, competing on manufacturing volume rather than downstream formulation capabilities. These three entities represent the competitive spectrum from captive supply control to service-based differentiation in a market where stability protection and regulatory dossier preparation increasingly separate premium tiers from commodity supply.
| Leading Market Players |
|---|
| DSM-Firmenich |
| BASF SE |
| Archer Daniels Midland Company |
| Lonza Group AG |
| Pfizer Inc. |
| Roche Vitamins |
| Eastman Chemical Company |
| Zhejiang NHU Co., Ltd. |
| Glanbia Nutritionals |
| Others |
Supply & Pricing Matrix
Isopropanol and acetone feedstock costs cascade through vitamin E acetate manufacturing before stratifying into three-tier pricing structure across premium, standard, and economy levels at the formulation tier. Western premix suppliers absorb margin compression from Chinese bulk concentration while passing stability premiums to clinical-grade buyers.
Pricing Analysis
Margin tightening in standard-grade premixes reflects Zhejiang NHU's manufacturing concentration and petrochemical price volatility. Three-tier pricing structure across premium, standard, and economy levels separates microencapsulated clinical grades from commodity acetate esters. Pricing pressure intensifies in animal feed segments as Southeast Asian export certification mandates commoditize vitamin E and K3 procurement. Healthcare providers demonstrate lowest price sensitivity for therapeutic-grade specifications, while mass-market retail consumers drive cost-down negotiations.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles coordinate hub-and-spoke patterns for humidity-sensitive vitamin A and D premixes. Manufacturing gravity centers on China for bulk vitamin E acetate, India for formulation services, and Germany for microencapsulation technology. Raw material dependencies include petrochemical feedstocks for tocopherol synthesis, palm-derived carriers for emulsions, and gelatin for softgel encapsulation. Single-source vulnerability from Zhejiang NHU's capacity concentration threatens Western formulator security. Distribution runs through B2B bulk containers for food manufacturers and unit-dose blister packs for clinical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lipid nanoparticle dispersion systems are displacing legacy emulsion technologies in functional beverage applications, compressing traditional stability premiums while opening service-based revenue streams for integrated suppliers.
For Market Incumbents: Extend microencapsulation service capabilities into regulatory dossier preparation to defend against premix commoditization. BASF SE and DSM-Firmenich should deepen captive supply control over vitamin D3 cholecalciferol sources as EFSA substantiation requirements tighten. Capacity addition in India positions suppliers for FSSAI fortification mandate procurement. For New Entrants and Emerging Players: Capture white-space in personalized nutrition platforms offering bespoke vitamin ADEK combinations from at-home micronutrient testing. The United Kingdom and United States direct-to-consumer channels show lowest penetration barriers for liquid format specialists. A subscription-model go-to-market angle bypasses traditional retail pharmacy gatekeepers. For Investors and Strategic Acquirers: EFSA's 2023 vitamin D upper limit revision is the leading indicator that regulatory claim substantiation capabilities will command acquisition premiums. Long-term viability favors targets with simultaneous competence in lipid chemistry, spray-drying, and cross-jurisdictional dossier preparation. The signal to watch is divergence between USP and EP monograph standards forcing dual testing investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin D3 Sourcing | Captures margin from cholecalciferol supply as EFSA substantiation requirements tighten clinical-grade procurement. |
| Lipid Nanoparticle Dispersion Scale-Up | Enables clear-format functional beverage integration previously incompatible with oil-soluble actives in German pilot facilities. |
| India FSSAI Premix Contract Positioning | Secures state-level edible oil and wheat flour fortification procurement at distribution scale. |
| Microbiome-Vitamin K2 Convergence Development | Targets fermented food and synbiotic applications as gut health positioning extends beyond bone benefits. |
| Regulatory Dossier Service Expansion | Differentiates integrated suppliers from commodity-scale manufacturers facing margin compression. |
Research Methodology
Multi-period observation of premix pricing spreads, feedstock cost volatility, and regulatory submission volumes anchored the trend analysis, supplemented by interviews with formulation directors at dietary supplement manufacturers, procurement leads at fortified food producers, regulatory affairs specialists navigating EFSA and FDA frameworks, and distribution channel partners managing humidity-sensitive inventory. Secondary validation drew from FDA Current Good Manufacturing Practice guidance documents, EFSA novel food application registers, FSSAI fortification mandate notifications, USP and EP pharmacopeial monographs, and customs trade data on vitamin acetate ester flows. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Input-output matrices modeled vitamin demand across biochemical structure, physical form, purchasing authority, and packaging format dimensions over the projection horizon. CAGRs derived from segment-level growth rate blending weighted by revenue concentration. Industry-specific forecast inputs included petrochemical feedstock price trajectory assumptions and regulatory enforcement intensity scoring across jurisdiction clusters.
The model holds under stable regulatory enforcement timelines and intact trade flows; deviation in tariff exposure or single-source supply disruption would shift capacity investment patterns. Forecasts reflect documented assumptions on micronutrient testing adoption curves and fortification mandate expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
High Calcium Fortified Food Market