
 Global Vitamin Tonics Market | 2026-2036
Global Vitamin Tonics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vitamin Tonics Market Outlook
Aftermarket service revenue from subscription-based vitamin replenishment programs is reconfiguring profit pools away from one-time retail transactions. Abbott Laboratories leverages its pharmacy distribution network to sustain recurring prescription-adjacent tonic sales. Amway anchors its direct-selling infrastructure across Asia-Pacific markets where personal consultation drives loyalty. Vitabiotics Ltd differentiates through science-backed positioning in European retail channels.
Vitamin tonics constitute bioavailable liquid, powder, tablet, or chewable preparations delivering water-soluble and fat-soluble micronutrients in standardized doses, typically manufactured through controlled fermentation, synthetic crystallization, or botanical extraction followed by stabilization in aqueous or suspension vehicles. These formulations serve commercial purposes spanning nutritional deficiency correction, athletic performance support, and geriatric dietary supplementation. Liquid tonics capture the dominant margin pool due to faster absorption claims and premium positioning in pediatric and senior applications, while online retail distribution channels represent the fastest-expanding structural segment as direct-to-consumer brands bypass traditional pharmacy gatekeepers. Tablet formats remain mature with stable manufacturing economies but face displacement from chewable innovations targeting compliance-sensitive demographics.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements under 21 CFR Part 111, mandating identity, purity, strength, and composition verification that elevates quality assurance costs for cross-border suppliers. EFSA's health claims authorization process under Regulation (EC) No 1924/2006 restricts permissible marketing language and shapes product positioning across European markets. India's FSSAI fortification guidelines and CDSCO oversight of pharmaceutical-grade tonics create dual compliance pathways for manufacturers serving both nutraceutical and quasi-medical segments. Stakeholders must monitor evolving borderline classification disputes between food supplements and medicinal products as regulators tighten enforcement on immune and energy claims.
Market Dynamics
Subscription-based replenishment programs are restructuring profit pools away from one-time retail transactions, forcing incumbents to rebuild distribution economics around recurring revenue capture.
Growth Catalysts
- Preventive healthcare spending:Working-age adults in the United States, India, and Germany now integrate tonic consumption into routine wellness regimens, expanding pharmacy and direct-to-consumer channel volumes.
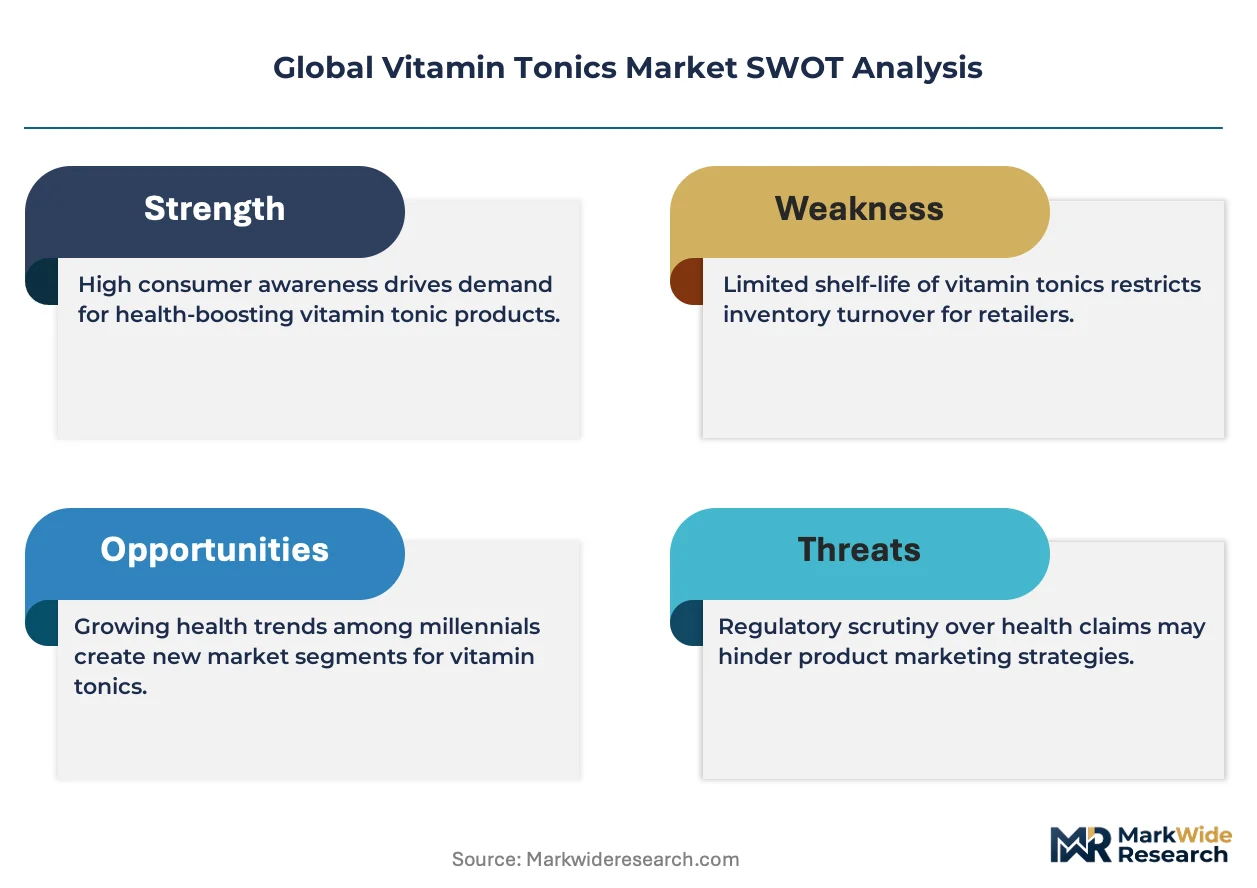
- DSHEA enforcement shifts:The FDA's updated dietary supplement labeling requirements are elevating formulation transparency obligations, filtering out substandard suppliers and concentrating demand among compliant manufacturers.
- Liquid bioavailability claims:Faster absorption positioning in pediatric and senior applications commands premium pricing, driving margin expansion in aqueous suspension vehicles.
Market Restraints
- Cross-border compliance costs:21 CFR Part 111 identity and purity verification mandates elevate quality assurance expenditures for suppliers serving US markets.
- Raw material concentration:Synthetic vitamin precursor supply chains cluster in specific manufacturing geographies, exposing formulators to input volatility and geopolitical disruption.
- Health claim restrictions:EFSA's Regulation (EC) No 1924/2006 authorization process constrains permissible marketing language, compressing differentiation space in European retail.
Strategic Opportunities
- Direct-to-consumer bypass:Online retail channels enable emerging brands to circumvent traditional pharmacy gatekeepers, capturing margin previously allocated to wholesale intermediaries.
- Chewable format innovation:Compliance-sensitive demographics—pediatric and geriatric consumers—are shifting preference away from tablets toward palatable alternatives.
- India's dual pathway:FSSAI fortification guidelines and CDSCO pharmaceutical-grade oversight create segmented positioning for manufacturers serving both nutraceutical and quasi-medical demand.
Industry Challenges
- Borderline classification disputes:Regulators in multiple jurisdictions are tightening enforcement on immune and energy claims, forcing reformulation or relabeling of existing SKUs.
- Stabilization expertise gaps:Aqueous vehicle formulation requires specialized knowledge in micronutrient degradation prevention that outstrips current technical workforce supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vitamin Tonics Market |
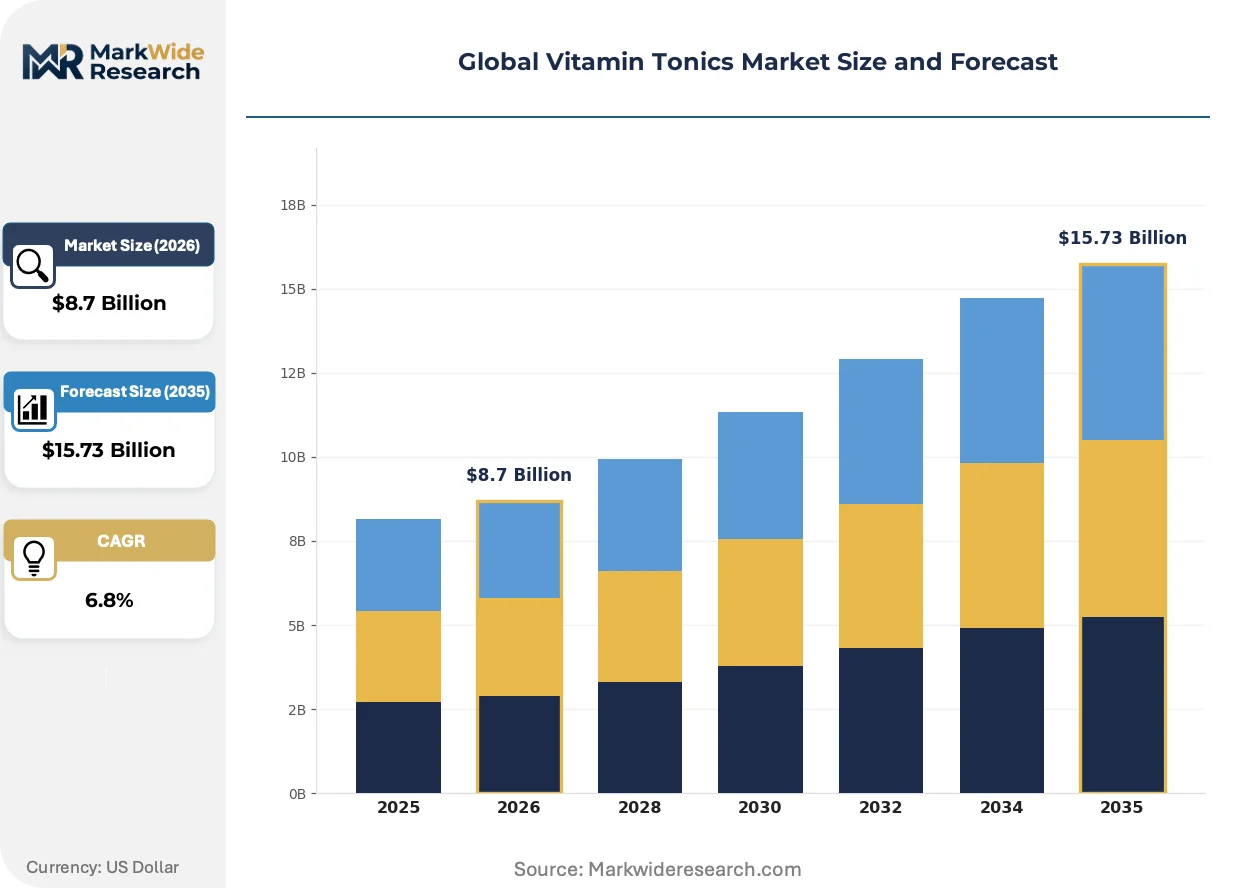
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Tablet, Chewable End User: Adults, Children, Seniors, Athletes Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores Formulation: Herbal, Synthetic, Organic, Others |
| Companies Covered | Amway, Abbott Laboratories, Seven Seas, Vitabiotics Ltd, Albert David Ltd, Sapiens Pharmaceuticals Ltd, Vitane Pharmaceuticals Inc, Fitzroy International Ltd, Raptakos Brett & Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vitamin Tonics Market Strategic Shifts
Controlled fermentation and synthetic crystallization methods are advancing precision dosing capabilities while botanical extraction techniques broaden natural-positioned product pipelines.
Liposomal encapsulation technology improves micronutrient bioavailability through phospholipid bilayer protection during digestive transit. Geriatric and athletic performance segments are adopting these formulations at accelerating rates. Conventional non-encapsulated liquid tonics are rendering obsolete in premium positioning tiers where absorption metrics drive purchase decisions.
India's FSSAI has issued updated fortification guidelines creating mandatory micronutrient thresholds for standardized tonic categories. Domestic manufacturers face reformulation deadlines to maintain market access. Quasi-medical segment suppliers are responding by seeking CDSCO pharmaceutical-grade registrations to escape food-supplement claim constraints.
Subscription auto-replenishment models now capture recurring purchase commitments previously executed through discretionary retail visits. Direct-to-consumer brands are disintermediating pharmacy chains in United States and German urban markets. This behavioral shift concentrates most visibly among working-age professionals managing preventive health regimens through mobile-enabled platforms.
Global Vitamin Tonics Market Segmentation
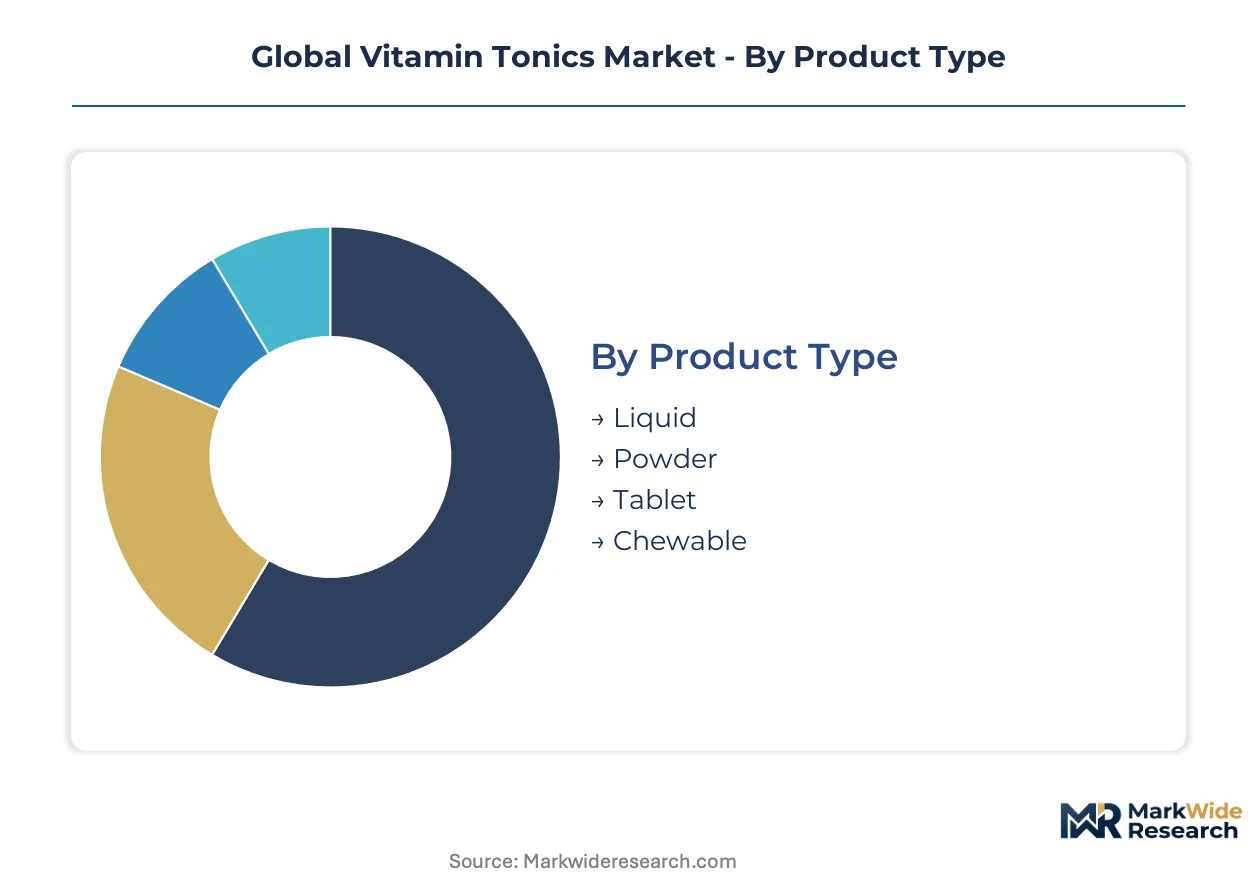
Vitamin tonic manufacturers segment demand across four intersecting dimensions that determine formulation priorities, channel economics, and regulatory pathways. Each category carries distinct margin profiles and inventory velocity characteristics that reshape competitive positioning.
Product Type:
Liquid formats turn inventory fastest through pediatric and geriatric channels, while tablets rotate slowest due to mature retail saturation and price compression.
- Liquid:Aqueous suspension vehicles deliver water-soluble and fat-soluble micronutrients with faster absorption claims. Demand concentrates in United States pharmacy channels and Indian direct-to-consumer platforms where parents and caregivers prioritize ease of administration for children and seniors.
- Tablet:Compressed solid-dose formats offer manufacturing economies and extended shelf stability. United States and German retail pharmacies anchor volume, though displacement accelerates as compliance-sensitive demographics reject swallowing difficulties.
- Powder:Dry concentrate formats enable flexible dosing and transport efficiency. Sports nutrition applications in Germany and athletic segments in India drive procurement.
- Chewable:Palatable gummy and soft-chew matrices improve adherence among pediatric and geriatric consumers. Direct-to-consumer brands in United States urban markets capture premium positioning through flavor innovation.
Tablet formats anchor the volume base while chewable alternatives gain share at the steepest rate.
End User:
Cost tier stratification separates premium-positioned athletic formulations from mass-market adult maintenance doses.
- Adults:Working-age preventive health regimens dominate procurement volume across United States, India, and Germany. Subscription auto-replenishment models capture recurring commitments from professionals managing wellness through mobile platforms.
- Seniors:Geriatric dietary supplementation demands bioavailability-optimized liposomal encapsulation. United States pharmacy networks and German retail channels concentrate demand for pharmaceutical-grade positioning.
- Children:Pediatric applications require palatable formats with precise micronutrient thresholds. India's FSSAI fortification guidelines mandate reformulation for domestic market access.
- Athletes:Performance-support formulations prioritize rapid nutrient delivery and electrolyte balance. German sports nutrition retail and United States specialty health stores drive premium pricing.
Adult segments anchor the volume base while senior applications command the steepest margin expansion.
Distribution Channel:
Volume concentration favors established pharmacy gatekeepers, though margin capture shifts toward disintermediated digital platforms.
- Online Retail:Direct-to-consumer brands bypass wholesale intermediaries, capturing margin previously allocated to pharmacy chains. United States and German urban markets concentrate mobile-enabled subscription growth.
- Pharmacies:Prescription-adjacent positioning and pharmacist consultation sustain recurring loyalty. Abbott Laboratories leverages network density in United States markets.
- Supermarkets:Mass-market accessibility drives volume for standardized tablet and powder formats. Price compression limits differentiation space.
- Health Stores:Specialty retail channels curate premium and natural-positioned assortments. European markets concentrate science-backed and organic claims.
Pharmacy channels anchor the volume base while online retail climbs the fastest.
Formulation:
Supply concentration clusters synthetic precursor manufacturing in specific geographies, while botanical extraction broadens natural-positioned pipelines.
- Synthetic:Controlled crystallization methods enable precision dosing and batch consistency. United States FDA 21 CFR Part 111 compliance elevates quality assurance costs for cross-border suppliers.
- Herbal:Botanical extraction techniques leverage traditional medicine positioning in India and Southeast Asian markets. Standardization challenges constrain scale.
- Organic:Certified cultivation and processing protocols command premium positioning in European retail. EFSA health claim restrictions compress permissible marketing language.
- Others:Fermentation-derived and hybrid formulations occupy niche positioning. Technical workforce gaps in stabilization expertise limit expansion.
Synthetic formulations anchor the volume base while organic alternatives expand most quickly in premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States and German consumers absorb premium pricing for bioavailability-optimized formulations, while Indian buyers concentrate in mass-market segments where FSSAI-mandated fortification thresholds compress margins.
United States
Preventive health regimens among working-age professionals drive subscription auto-replenishment through mobile-enabled platforms. FDA's 21 CFR Part 111 enforcement elevates quality assurance costs, filtering substandard suppliers from cross-border channels. Pharmacy networks in metropolitan clusters sustain prescription-adjacent tonic loyalty.
Germany
Sports nutrition retail channels prioritize rapid nutrient delivery formulations for athletic performance segments. EFSA's Regulation (EC) No 1924/2006 authorization process constrains permissible marketing language, compressing differentiation space. Bavaria-based manufacturing clusters specialize in pharmaceutical-grade positioning for senior applications.
India
Direct-to-consumer platforms capture working-age adults integrating tonic consumption into routine wellness regimens. FSSAI fortification guidelines mandate micronutrient thresholds with reformulation deadlines for domestic market access. Maharashtra and Gujarat house concentrated manufacturing capacity serving both nutraceutical and quasi-medical segments.
China
Pediatric and geriatric demand concentrates in urban pharmacy channels seeking palatable liquid formats. NMPA oversight of pharmaceutical-grade tonics creates dual compliance pathways alongside food-supplement classifications. Yangtze River Delta manufacturing bases supply synthetic vitamin precursors to regional formulators.
Japan
Aging demographics sustain premium demand for liposomal encapsulation technologies in geriatric dietary supplementation. METI standards for functional food claims shape permissible positioning language. Kanto region distribution networks anchor pharmacy channel volumes for bioavailability-optimized preparations.
Global Vitamin Tonics Market Competitive Environment
Capability concentration sits with formulation specialists mastering aqueous vehicle stabilization; scale advantage sits with diversified healthcare conglomerates leveraging pharmacy distribution density. The vendor base separates into three strategic archetypes: direct-selling infrastructure operators, science-backed retail positioners, and pharmaceutical-grade manufacturers. M&A activity targets subscription platform capabilities, while geographic expansion concentrates on Asia-Pacific direct-to-consumer penetration.
Within the pharmaceutical-grade tier, Abbott Laboratories exemplifies scale-driven distribution leverage through pharmacy network anchoring. Amway occupies the direct-selling infrastructure archetype across Asia-Pacific markets where personal consultation drives loyalty. Vitabiotics Ltd represents science-backed retail positioning in European channels.
| Leading Market Players |
|---|
| Amway |
| Abbott Laboratories |
| Seven Seas |
| Vitabiotics Ltd |
| Albert David Ltd |
| Sapiens Pharmaceuticals Ltd |
| Vitane Pharmaceuticals Inc |
| Fitzroy International Ltd |
| Raptakos Brett & Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Synthetic vitamin precursor manufacturing clusters in China and India anchor cost structures across formulation tiers, concentrating margin capture with aqueous vehicle specialists serving pediatric and geriatric applications. Subscription auto-replenishment programs redistribute value pools from wholesale intermediaries toward direct-to-consumer platforms.
Pricing Analysis
Aftermarket service revenue from subscription-based vitamin replenishment programs drives lifetime value capture. Three-tier pricing structure across premium liposomal encapsulation, standard liquid suspensions, and economy tablet formats separates bioavailability-optimized positioning from mass-market accessibility. Cost compression in synthetic crystallization inputs intensifies as Chinese precursor suppliers expand fermentation capacity. Pediatric and geriatric segments show least price sensitivity due to caregiver-driven purchase authority, while adult maintenance segments exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from Indian contract manufacturers to domestic botanical extract suppliers stabilize working capital for herbal-positioned product lines. Raw material dependencies center on Chinese synthetic vitamin B and C precursor production, Indian botanical extraction capacity, and German pharmaceutical-grade stabilization agents. Single-source vulnerability in liposomal phospholipid bilayer inputs exposes premium formulators to supply interruption. Distribution runs through pharmacy networks in the United States and Germany, direct-to-consumer platforms in India, and hybrid supermarket-specialty retail in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is reshaping competitive dynamics as mobile-enabled subscription infrastructure disintermediates traditional pharmacy gatekeepers. Interoperability between direct-to-consumer brands and pharmacy benefit managers represents the critical ecosystem shift.
For Market Incumbents: Build subscription platform moats through API integration with pharmacy benefit managers and employer wellness programs. Abbott Laboratories demonstrates defensive positioning via prescription-adjacent tonic anchoring in United States pharmacy networks. Incumbents must secure CDSCO pharmaceutical-grade registrations in India to escape FSSAI food-supplement claim constraints. Vertical integration into aqueous vehicle stabilization expertise addresses technical workforce scarcity. For New Entrants and Emerging Players: India's quasi-medical segment under CDSCO oversight represents the most penetrable entry point for premium positioning outside saturated United States direct-to-consumer channels. Chewable format innovation targeting compliance-sensitive pediatric demographics in German urban markets offers secondary white-space. Go-to-market execution should leverage mobile-first subscription infrastructure with pharmacist consultation partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with direct-to-consumer subscription platforms possessing established replenishment algorithms and customer lifetime value metrics. Long-term viability across the analysis window favors manufacturers with dual FSSAI-CDSCO compliance pathways in India. The signal to watch is regulatory tightening on immune and energy claims forcing relabeling expenditures.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Integration | Captures recurring revenue pools previously allocated to pharmacy wholesale intermediaries. |
| Liposomal Encapsulation Scale-Up | Addresses bioavailability-optimized demand from geriatric and athletic performance segments. |
| Dual Compliance Pathway Investment | Enables escape from FSSAI food-supplement constraints through CDSCO pharmaceutical-grade registration. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional pharmacy gatekeepers in United States and German urban markets. |
| Chewable Format Innovation | Improves adherence among compliance-sensitive pediatric and geriatric consumer demographics. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with formulation scientists, pharmacy procurement managers, direct-to-consumer brand operators, and FSSAI regulatory consultants; and secondary validation against FDA 21 CFR Part 111 enforcement records, EFSA health claim authorization databases, CDSCO pharmaceutical-grade registration filings, and Indian customs trade data. Bottom-up demand modeling triangulated against top-down market sizing from trade association disclosures.
Forecast inputs considered product type segmentation across liquid, tablet, powder, and chewable formats; end-user stratification by adults, seniors, children, and athletes; distribution channel evolution through online retail, pharmacies, supermarkets, and health stores; and formulation origin across synthetic, herbal, organic, and hybrid categories. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and channel shift elasticity. Liposomal encapsulation adoption curves and subscription penetration rates served as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary health spending, cross-border tariff regimes, or raw material input costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and channel migration patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Retinyl Linoleate Market